
 Tactical Optics Market | 2026-2036
Tactical Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Optics Market Analysis
The capital-intensity divergence between in-house sensor fabrication and outsourced assembly is rotating competitive advantage toward vertically integrated defense primes. BAE Systems leverages captive gallium arsenide foundry capacity to sustain thermal imaging supply security. Elbit Systems anchors its position through electro-optic R&D intensity across multiple military programs. Vortex Optics competes in the commercial and law enforcement tiers with specialized rifle scope manufacturing at scale.
Tactical optics comprise precision sighting and observation devices engineered to sub-arcminute angular resolution, incorporating nitrogen-purged housings, broadband anti-reflection coatings, and shock-rated reticle mechanisms for operational reliability under recoil and environmental stress. Their primary purpose is to enhance target acquisition speed, identification range, and engagement accuracy for small arms, crew-served weapons, and surveillance platforms across military and security applications. Rifle scopes and night vision systems command the dominant share of defense procurement budgets, while red dot sights represent the fastest-expanding category among law enforcement and sports shooting end users due to close-quarters combat doctrine adoption and competitive shooting discipline growth. Thermal imaging technology concentrates margin pools where export-controlled focal plane array sourcing creates supply scarcity.
The US State Department ITAR regime and the EU Green Deal F-Gas Regulation jointly constrain coolant gas availability for thermal detector dewar assemblies and restrict cross-border component transfers. The US FDA laser product performance standard and NATO STANAG 4370 environmental testing protocols further define product qualification thresholds for allied military interoperability. Stakeholders must monitor evolving multilateral export control alignment between the US, Germany, and France as dual-use classification debates reshape market access for electro-optic subsystems.
Market Dynamics
Export-controlled focal plane array sourcing is compressing thermal imaging supply availability while NATO infantry modernization programs accelerate electro-optic procurement timelines. This tension between constrained component access and rising defense demand is forcing suppliers to reconfigure qualification strategies and captive production investments.
Growth Catalysts
- ITAR-Driven Supplier Consolidation:The US State Department's export control framework is elevating qualified vendor status as a competitive moat, concentrating defense contracts among pre-cleared electro-optic specialists with established secure facility clearances.
- STANAG 4370 Environmental Testing:NATO's standardized environmental qualification protocol is harmonizing product validation requirements across allied procurement programs, reducing redundant certification costs for cross-border military sales.
- Infantry Close-Quarters Doctrine:Urban warfare training emphasis in Western militaries is accelerating red dot sight and holographic weapon sight procurement for rapid target engagement at sub-100 meter distances.
Market Restraints
- Gallium Arsenide Foundry Concentration:Captive III-V semiconductor fabrication capacity resides with a handful of vertically integrated defense primes, creating supply scarcity for independent thermal imaging module assemblers.
- F-Gas Dewar Coolant Constraints:The EU Green Deal's fluorinated gas phase-down is restricting sulfur hexafluoride and other cryogenic coolant availability for Stirling-cycle cooled thermal detector assemblies.
- Uncooled Microbolometer Substitution Ceiling:Performance limitations in uncooled thermal sensors at extended identification ranges preserve demand for export-controlled cooled focal plane arrays in precision military applications.
Strategic Opportunities
- Law Enforcement Digitization Mandates:Body-worn camera and patrol rifle optic standardization programs in US municipal police departments are opening commercial-tier volume channels for ruggedized red dot and low-power variable optics.
- Competitive Shooting Discipline Expansion:USPSA and IPSC match participation growth is driving consumer demand for rapid-acquisition optics with daylight-visible illuminated reticles and extended battery architectures.
- AI-Assisted Reticle Projection:Convergence of ballistic calculation software with heads-up display technology is enabling dynamic holdover point adjustment in next-generation rifle scopes without manual turret manipulation.
Industry Challenges
- ITAR Technical Data Handling:Controlled design documentation and manufacturing know-how transfer restrictions complicate subcontractor qualification and foreign national employee access to sensitive production lines.
- Shock-Rated Mechanism Design:Sustained recoil impulse survivability for .50 caliber and magnum rifle platforms demands specialized reticle suspension engineering that extends development cycles and qualification testing durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Optics Market |
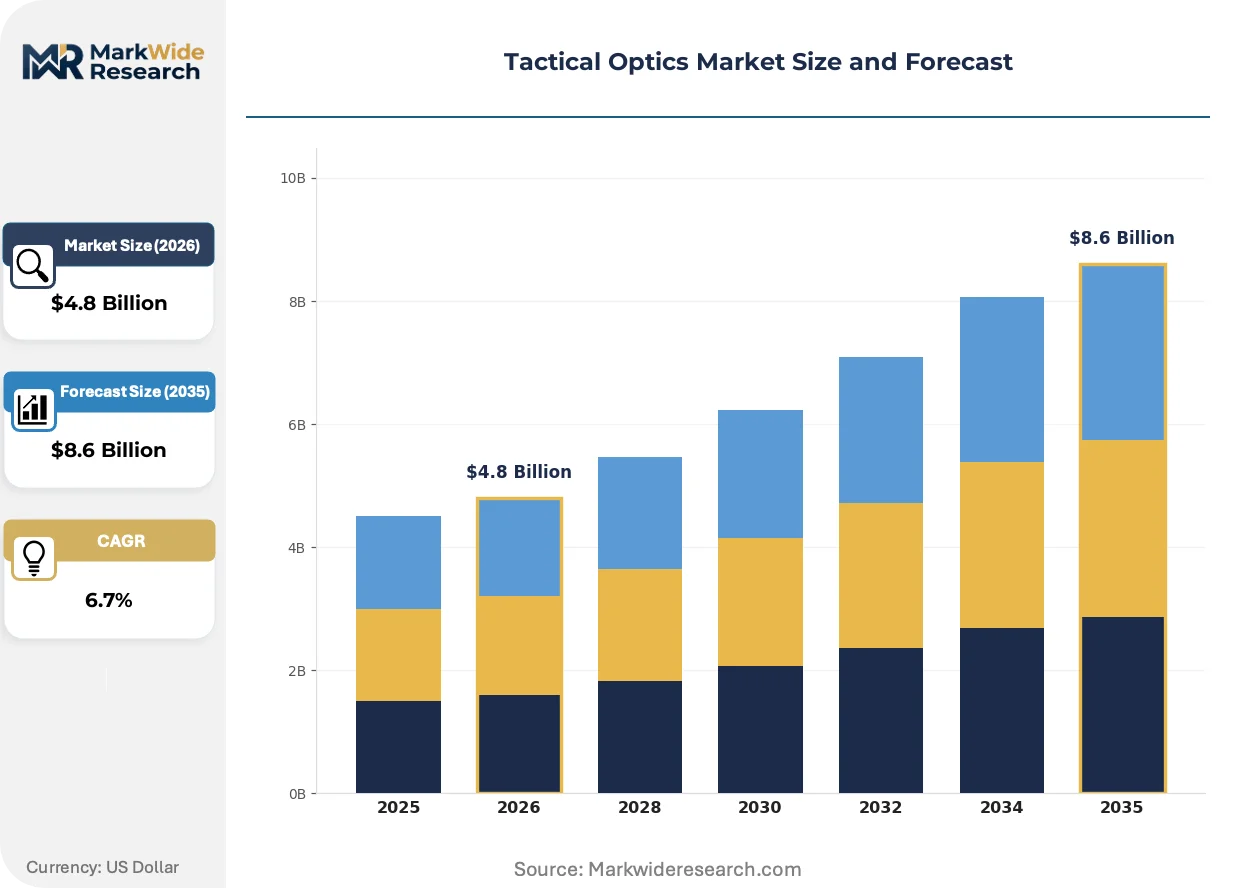
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Dot Sights, Rifle Scopes, Binoculars, Night Vision Application: Military, Law Enforcement, Hunting, Sports Shooting Technology: Electro-Optics, Thermal Imaging, Laser, Passive Optics End User: Defense Agencies, Private Security, Outdoor Enthusiasts, Military Contractors |
| Companies Covered | BAE Systems, Raytheon Technologies, Elbit Systems, Kongsberg Gruppen, Thales Group, L3Harris Technologies, Saab AB, Leonardo S.p.A., Vortex Optics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Optics Market Emerging Trajectories
Digital sensor fusion and computational imaging are displacing pure optical performance as the primary value driver in tactical sighting systems. Manufacturers are integrating ballistic solvers, atmospheric sensors, and wireless connectivity into traditional form factors.
Uncooled vanadium oxide microbolometer technology is decomposing the traditional thermal market structure by delivering adequate detection performance at fractional cost and power budgets. Law enforcement agencies and commercial security operators are adopting these sensors for perimeter surveillance and search applications previously reserved for military-grade cooled systems. The technology is decomposing margin pools at the standard-performance tier while pushing premium cooled focal plane arrays toward specialized long-range identification niches.
The EU F-Gas Regulation's phasedown schedule is forcing thermal imaging manufacturers to redesign dewar cooling architectures around alternative cryogenic fluids or solid-state thermoelectric stabilization. Industrial consequence includes accelerated R&D investment in high-operating-temperature detector materials that reduce or eliminate active cooling requirements. European thermal module assemblers are most affected, with several firms relocating final integration to non-EU jurisdictions to preserve legacy coolant access for military contract fulfillment.
Defense procurement offices are consolidating electro-optic sourcing through multi-year indefinite delivery vehicles rather than discrete program competitions. This buyer concentration is displacing opportunistic spot-market sales and forcing suppliers to absorb inventory risk and sustain engineering support across extended contract horizons. The shift is most visible in US Army and Marine Corps small arms optic programs, where single-source awards now span five to ten year performance periods with embedded technology refresh clauses.
Tactical Optics Market Segmentation
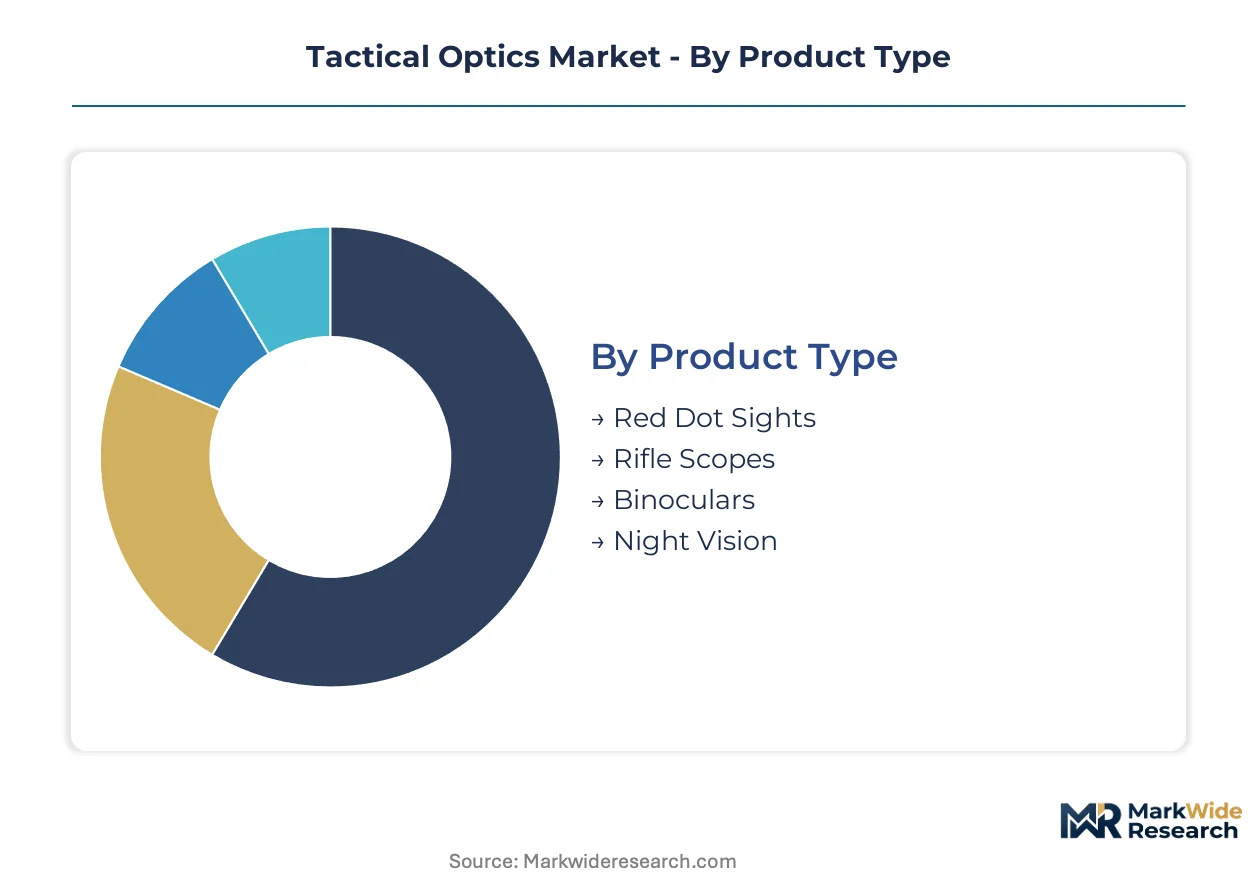
Tactical optics segmentation reveals how procurement concentration, technology export controls, and end-user mission profiles fragment demand across distinct specification tiers. Margin pools concentrate where military qualification requirements create vendor exclusivity and where thermal imaging focal plane arrays face supply scarcity.
Product Type:
Margin pools concentrate in precision sighting systems where nitrogen-purged housings and shock-rated reticle mechanisms command defense procurement premiums.
- Rifle Scopes:Variable magnification optical systems with first or second focal plane reticles, parallax adjustment, and tactical turrets for bullet drop compensation. Defense agencies in the United States drive demand through precision targeting system modernization, constrained by ITAR-qualified supplier availability.
- Night Vision:Image intensification devices utilizing photocathode tubes or digital sensor fusion for low-light target acquisition. NATO infantry modernization programs accelerate procurement despite gallium arsenide foundry concentration limiting tube production capacity.
- Red Dot Sights:Non-magnifying reflex optics with LED-illuminated reticles for rapid target engagement at close quarters.
- Binoculars:Handheld observation devices with rangefinding reticles or laser integration for surveillance and reconnaissance applications.
The dominant share belongs to Rifle Scopes, while Red Dot Sights is closing the gap fastest.
Application:
Cost tier stratification separates military-qualified systems from commercial-tier products with reduced environmental testing protocols.
- Military:Mission-critical sighting systems meeting STANAG 4370 environmental testing and ITAR technical data handling requirements. Procurement concentrates in the United States through multi-year indefinite delivery vehicles with embedded technology refresh clauses.
- Law Enforcement:Patrol rifle optics and surveillance equipment for municipal police department standardization programs. US municipal agencies drive volume demand for ruggedized red dot and low-power variable optics with body-worn camera integration.
- Sports Shooting:Competition-grade optics for USPSA and IPSC match disciplines requiring rapid acquisition and extended battery architectures.
- Hunting:Consumer-grade rifle scopes and observation optics for recreational shooting and wildlife observation.
The dominant share belongs to Military, while Law Enforcement is expanding most quickly.
Technology:
Supply concentration in export-controlled components determines competitive access and pricing power across technology tiers.
- Thermal Imaging:Focal plane array-based detection systems utilizing cooled or uncooled sensors for heat signature visualization. EU F-Gas Regulation constraints on sulfur hexafluoride dewar coolants force architecture redesigns around alternative cryogenic fluids or solid-state thermoelectric stabilization.
- Electro-Optics:Integrated sensor systems combining visible, near-infrared, and laser rangefinding capabilities. BAE Systems and Elbit Systems anchor supply security through captive gallium arsenide foundry capacity and multi-program R&D intensity.
- Laser:Designators, rangefinders, and aiming modules subject to FDA performance standards and ITAR classification protocols.
- Passive Optics:Pure optical systems without electronic augmentation, relying on glass quality and mechanical precision for performance.
The dominant share belongs to Thermal Imaging, while Electro-Optics is gaining share fastest.
End User:
Customer type determines qualification burden, contract duration, and technology refresh cadence across the demand base.
- Defense Agencies:National military procurement offices with classified requirement specifications and secure facility clearance mandates. The US Army and Marine Corps consolidate small arms optic sourcing through single-source awards spanning five to ten year performance periods.
- Military Contractors:Prime and subsystem suppliers integrating tactical optics into weapon platforms and vehicle systems. Prime contractor spending on precision targeting systems in the United States drives premium product development roadmaps.
- Private Security:Corporate and facility protection services requiring commercial-tier equipment without military qualification overhead.
- Outdoor Enthusiasts:Individual consumers purchasing through retail channels for hunting, competitive shooting, and recreational observation.
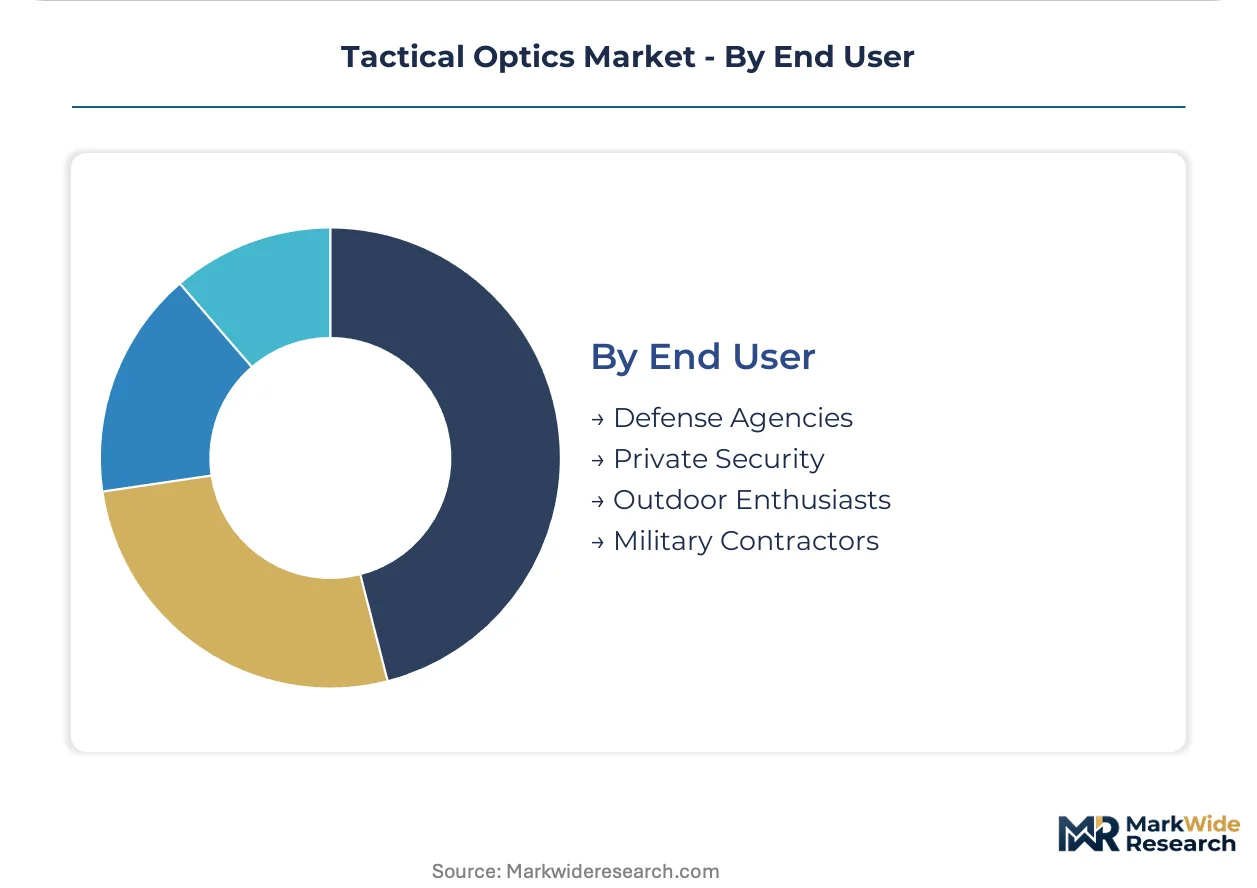
The dominant share belongs to Defense Agencies, while Military Contractors is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-controlled component flows concentrate supply security investments in defense-industrial bases with qualified foundry access, while procurement demand clusters where NATO modernization programs and law enforcement digitization mandates intersect. Import dependency for gallium arsenide substrates and thermal detector coolants shapes regional production strategies.
United States
Defense agency procurement through multi-year indefinite delivery vehicles concentrates demand for precision targeting systems and small arms optics. The US State Department ITAR framework restricts technical data transfers and elevates secure facility clearance requirements for electro-optic suppliers. Prime contractor spending in Texas and Arizona drives premium product development roadmaps for military-qualified sighting systems.
Germany
Bundeswehr infantry modernization and export-oriented defense manufacturing sustain demand for night vision and thermal imaging modules. The EU F-Gas Regulation phases down sulfur hexafluoride availability for Stirling-cycle dewar assemblies, forcing coolant architecture redesigns. Industrial clusters in Bavaria and Baden-Württemberg host thermal module assemblers relocating final integration to preserve legacy coolant access.
France
Direction Générale de l'Armement procurement prioritizes electro-optic systems for soldier modernization and vehicle platform integration. ANSM and dual-use classification debates reshape market access protocols for electro-optic subsystems with civilian applications. The Paris-Saclay defense technology cluster anchors multi-program R&D intensity across thermal and laser rangefinding domains.
Israel
Domestic defense requirements and technology export licensing sustain captive electro-optic production capacity for thermal imaging and night vision systems. The Israeli Ministry of Defense's procurement protocols emphasize multi-spectral sensor fusion for urban warfare applications. Industrial concentration in the Negev and Haifa regions supports vertically integrated foundry-to-system assembly for export-controlled focal plane arrays.
United Kingdom
British Army Soldier System and Future Soldier programs drive procurement of helmet-mounted night vision and weapon-mounted red dot sights. The UK Export Control Organisation aligns with US ITAR frameworks to harmonize qualified vendor status across allied procurement. Defense industrial activity in Scotland and the West Midlands concentrates electro-optic subsystem integration for NATO interoperability.
Tactical Optics Market Vendor Landscape
Concentration sits with vertically integrated defense primes possessing captive III-V semiconductor fabrication and secure facility clearances. The vendor base stratifies between ITAR-qualified system integrators, commercial-tier volume manufacturers, and specialized subsystem suppliers. Three archetypes dominate: defense primes with foundry ownership, commercial optics specialists with law enforcement channels, and thermal module assemblers dependent on export-controlled component sourcing. Competitive moves center on backward integration into focal plane array supply and geographic relocation to preserve coolant access.
Among defense prime archetypes, BAE Systems and Elbit Systems exemplify vertically integrated positioning through captive gallium arsenide capacity and multi-program electro-optic R&D intensity. Vortex Optics occupies a position within the commercial-tier specialist segment, competing in law enforcement and sports shooting channels with scaled rifle scope manufacturing. These three anchors illustrate how qualification requirements and supply security investments fragment competitive positioning across the demand spectrum.
| Leading Market Players |
|---|
| BAE Systems |
| Raytheon Technologies |
| Elbit Systems |
| Kongsberg Gruppen |
| Thales Group |
| L3Harris Technologies |
| Saab AB |
| Leonardo S.p.A. |
| Vortex Optics |
| Others |
Supply Flow & Price Mechanics
Twenty-four to thirty-six month qualification timelines for ITAR-cleared suppliers compress pricing power toward pre-qualified defense primes while fragmenting procurement options for second-tier assemblers. This lead-time concentration rewards vertically integrated foundry owners with premium capture on export-controlled thermal imaging modules.
Pricing Analysis
The customization-premium spread separates configured-to-order military rifle scopes from commercial off-the-shelf red dot sights by a factor of five to fifteen, with pricing stratifying across premium, standard, and economy tiers. Defense agencies absorb premium pricing for STANAG 4370-qualified systems with nitrogen-purged housings and shock-rated reticle mechanisms. Cost compression in the law enforcement tier intensifies because municipal procurement standardization drives volume aggregation. Sports shooting end users exhibit highest price sensitivity, while defense contractors demonstrate lowest sensitivity due to pass-through contract structures.
Supply Chain Analysis
Gallium arsenide foundry concentration in the United States, Israel, and the United Kingdom anchors focal plane array supply security for thermal imaging module production. The supply chain draws from germanium substrates, III-V semiconductor wafers, and sulfur hexafluoride dewar coolants. Single-source vulnerability in Stirling-cycle cooler assemblies forces European assemblers toward geographic relocation. Distribution runs through defense prime direct sales teams for military programs and specialized distributors for commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tactical optics market sits in a cyclical recovery phase as NATO infantry modernization programs restore procurement momentum following pandemic-era budget delays.
For Market Incumbents: Shield market position through captive gallium arsenide foundry investment and multi-year indefinite delivery vehicle capture. The threat of uncooled microbolometer substitution in law enforcement applications demands accelerated R&D in high-operating-temperature detector materials. Vertical integration into focal plane array supply secures margin pools where export controls create scarcity. For New Entrants and Emerging Players: Lead with AI-assisted reticle projection technology to penetrate the commercial sports shooting segment where incumbent qualification burdens are lowest. The most penetrable white space sits in USPSA and IPSC match participant equipment upgrades. A direct-to-consumer digital channel with embedded ballistic solver subscriptions offers viable go-to-market positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming electro-optic divisions lacking defense prime scale. Long-term viability over a five-to-ten year horizon favors suppliers with ITAR facility clearances and multi-program engineering support contracts. The signal to watch is EU F-Gas Regulation enforcement intensity driving coolant architecture redesign capex requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Focal Plane Arrays | Captive gallium arsenide foundry capacity insulates BAE Systems and Elbit Systems from supply scarcity. |
| Multi-Year Indefinite Delivery Vehicle Capture | US Army and Marine Corps consolidation of small arms optic sourcing displaces spot-market sales. |
| AI-Assisted Reticle Projection Development | Ballistic solver integration with heads-up display technology enables dynamic holdover without manual turret adjustment. |
| Geographic Relocation for Coolant Access | European thermal module assemblers relocate final integration to non-EU jurisdictions preserving legacy sulfur hexafluoride access. |
| Law Enforcement Channel Expansion | US municipal police department standardization programs open volume channels for ruggedized red dot and low-power variable optics. |
Methodological Framework
Desk research of defense procurement databases, ITAR regulatory filings, and EU F-Gas Regulation implementation guidance preceded structured interviews with electro-optic R&D directors, defense prime procurement executives, thermal imaging subsystem engineers, and law enforcement equipment program managers. Secondary validation drew from NATO STANAG documentation, US State Department export control advisories, SEC 10-K filings of listed defense contractors, and customs trade data for gallium arsenide substrate flows. Bottom-up unit demand modeling triangulated against top-down defense budget allocation analysis.
Variance decomposition across product type, application tier, technology platform, and end-user archetype shaped the analytical framework over the projection horizon. CAGRs derived from segment-level unit economics and pricing trajectory assumptions. Industry-specific forecast inputs included ITAR qualification pipeline durations, EU F-Gas phasedown implementation schedules, and NATO member state infantry modernization program commitments.
Forecasts assume regulatory continuity in US ITAR export control regimes and EU F-Gas Regulation enforcement; material policy shifts would require re-modeling of supplier qualification strategies and thermal imaging architecture roadmaps. Revision becomes warranted when uncooled microbolometer performance thresholds cross military identification range requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
UXO Detection Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Military Jammer Market