
 Tactical Satellite Market | 2026-2036
Tactical Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Satellite Market Insights
Multi-source satellite procurement is realigning how defense agencies contract for tactical space assets. Lockheed Martin leverages its classified manufacturing infrastructure to dominate prime contractor roles for US military payloads. Northrop Grumman sustains long-term positioning through in-house production of satellite buses and sensor integration. Boeing competes across both commercial and defense orbits, extending its heritage in geostationary platforms toward proliferated Low Earth Orbit architectures.
Tactical satellites are spacecraft designed for military operations with masses typically under 1,000 kilograms, operating in Low Earth Orbit at altitudes of 300 to 2,000 kilometers to deliver low-latency secure communications and real-time reconnaissance. These platforms employ hardened electronics, anti-jam signal processing, and encrypted cross-links to survive contested electromagnetic environments. Low Earth Orbit platforms command the largest procurement volumes as militaries prioritize resilience through constellation dispersion over single-point geostationary assets. Secure Communications applications anchor current program spending, while Electronic Warfare capabilities represent the fastest-expanding technology investment area as spectrum dominance becomes central to joint force operations. Defense Forces remain the dominant end-user segment, though Intelligence Agencies are deepening their dedicated satellite procurement as space-based signals intelligence gains operational priority.
The US Space Force enforces National Security Space Launch requirements that filter contractor eligibility through demonstrated launch reliability and domestic supply chain provenance. ESA member states coordinate through the European Defence Fund to reduce dependency on non-European satellite providers for sovereign communications. The US Department of Commerce and EU dual-use export control regimes jointly shape market access for encryption and remote sensing technologies. Stakeholders must monitor how accelerating ITAR reform discussions and emerging EU space security procurement rules will redraw competitive boundaries for non-allied suppliers.
Market Dynamics
The US Space Force's classified payload standards and ITAR export controls are tightening supplier qualification requirements, forcing defense contractors to restructure supply chains around domestic provenance and proven launch reliability.
Growth Catalysts
- Proliferated LEO Architectures:Defense forces across NATO member states are expanding procurement of Low Earth Orbit constellations for battlefield surveillance and resilient communications.
- Electronic Warfare Prioritization:Spectrum dominance requirements are accelerating investment in satellite-based jamming and signals intelligence capabilities for joint force operations.
- European Defence Fund Coordination:ESA member states are pooling resources to reduce sovereign dependency on non-European satellite providers for secure military communications.
Market Restraints
- ITAR Compliance Burden:US export control regimes create structural friction for non-domestic suppliers seeking access to classified payload contracts.
- Launch Capacity Concentration:National Security Space Launch requirements filter contractor eligibility through a narrow base of demonstrated domestic launch providers.
- Hardened Electronics Cost:Radiation-hardened components and anti-jam signal processing impose significant cost premiums versus commercial satellite equivalents.
Strategic Opportunities
- Intelligence Agency Procurement:Dedicated satellite acquisition by signals intelligence services represents an underpenetrated buyer segment beyond traditional defense forces.
- Dual-Use Technology Convergence:Commercial remote sensing platforms and military-grade encryption standards are converging to create hybrid procurement channels.
- EU Space Security Procurement Rules:Emerging European regulations will create preferential access for allied suppliers in continental defense satellite markets.
Industry Challenges
- Cleared Workforce Scarcity:Security clearance requirements for personnel restrict talent pools available for classified satellite manufacturing programs.
- Legacy System Integration:New proliferated constellations must interoperate with existing geostationary command infrastructure, complicating architecture transitions.
- Cross-Domain Certification Timelines:Dual-use export control approvals from both US Department of Commerce and EU regimes delay encryption technology deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Satellite Market |
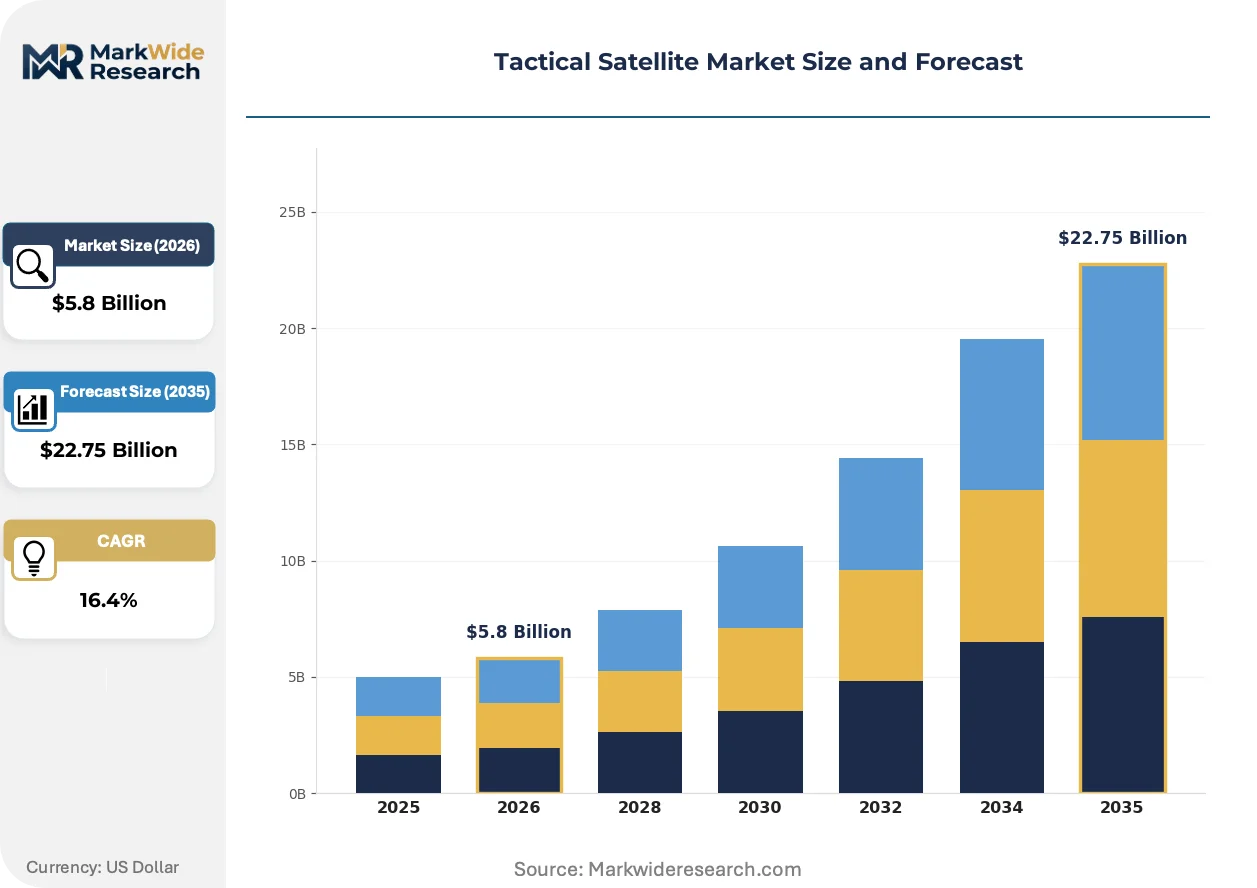
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $22.75 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Highly Elliptical Orbit Application: Secure Communications, Battlefield Surveillance, Reconnaissance, Positioning & Navigation, Electronic Warfare End User: Defense Forces, Intelligence Agencies, Homeland Security, Space Operations Commands Technology: Radio Frequency, Laser Communications, Signal Processing, Encryption, Data Relay |
| Companies Covered | Lockheed Martin, Northrop Grumman, Boeing, Raytheon Technologies, Airbus Defence and Space, Thales Alenia Space, L3Harris Technologies, Israel Aerospace Industries, OHB SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Satellite Market Trends and Innovations
Battlefield requirements for low-latency, resilient communications are reshaping satellite architecture priorities across allied defense procurement agencies.
Software-defined radio payloads are electrifying how tactical satellites manage spectrum allocation and signal processing. Defense forces in the United States and United Kingdom are mandating programmable RF systems for future constellation tranches. This flexibility is compressing hardware refresh cycles while enabling rapid reprogramming for emerging electronic warfare threats.
REACH and RoHS compliance requirements in the European Union are restricting hazardous materials in satellite electronics manufacturing. Suppliers serving ESA member states must reformulate solder alloys and substrate materials to maintain market access. German and French prime contractors are accelerating qualification of lead-free assembly processes for defense-grade components.
Allied militaries are consolidating satellite procurement under multi-orbit service contracts rather than discrete platform acquisitions. The United Kingdom's Skynet program and US Space Force leasing arrangements are displacing traditional capital expenditure models. This shift concentrates vendor selection authority with defense ministry central procurement offices in Washington and London.
Tactical Satellite Market Segmentation
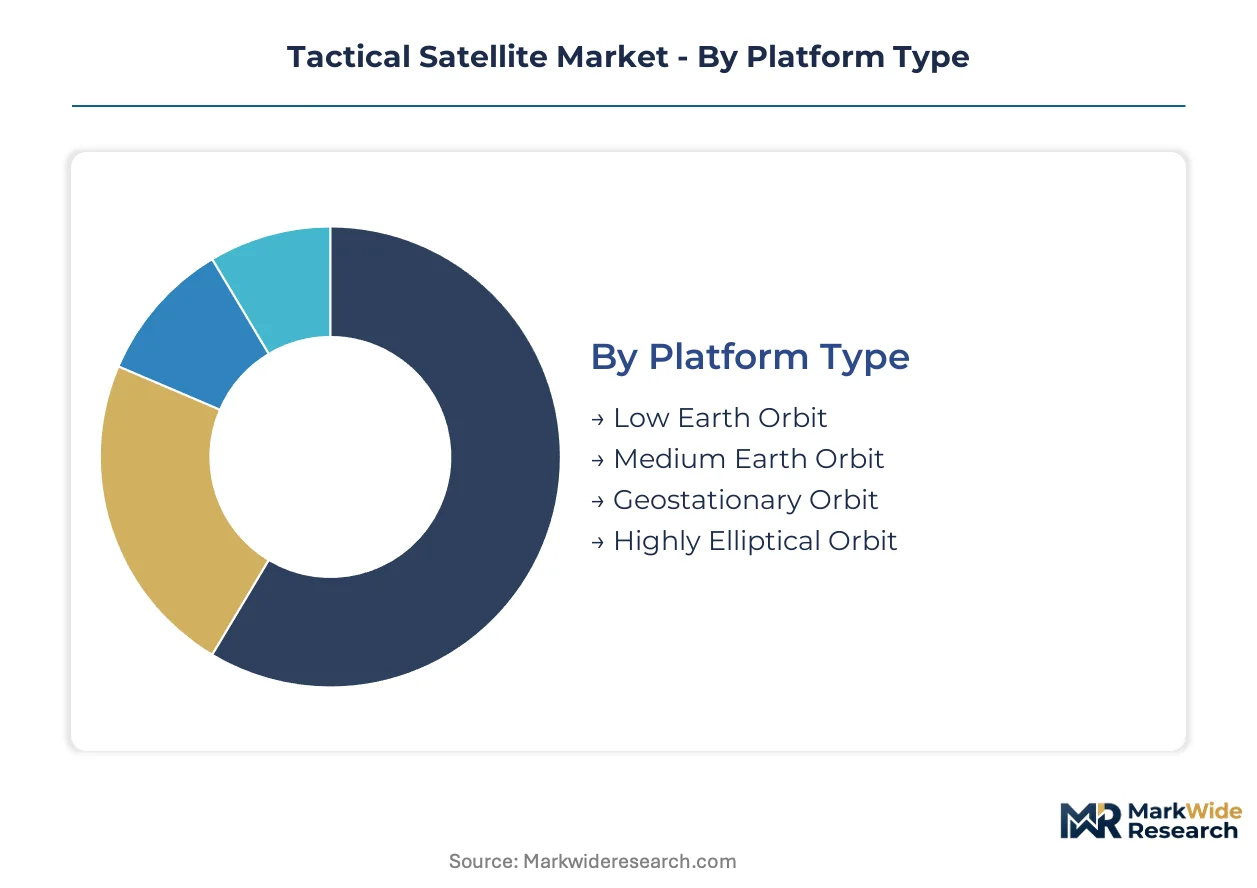
Tactical satellite procurement diverges sharply across orbital regimes, mission applications, and user hierarchies. Defense agencies structure acquisition around threat environment, latency requirements, and electromagnetic survivability rather than commercial cost optimization.
Platform Type:
Upgrade cycles for orbital infrastructure accelerate as legacy geostationary assets face obsolescence against proliferated LEO alternatives. Constellation refresh timelines now compress from fifteen-year replacement windows toward seven-year technology insertion schedules.
- Low Earth Orbit:These platforms operate at 300 to 2,000 kilometer altitudes with sub-50 millisecond latency for real-time battlefield communications. Procurement concentrates in the United States and United Kingdom as NATO forces prioritize resilience through dispersed architectures over single-point vulnerability.
- Geostationary Orbit:Fixed-position satellites at 35,786 kilometers deliver persistent coverage for strategic command links and missile warning. Demand persists in Germany and France for sovereign high-bandwidth trunk communications despite higher susceptibility to kinetic and electronic attack.
- Medium Earth Orbit:Intermediate-altitude platforms balance coverage footprint with latency performance for regional navigation augmentation and tactical data relay.
- Highly Elliptical Orbit:Elliptical trajectories enable extended dwell over high-latitude regions where geostationary visibility degrades; Arctic-focused militaries deploy these for polar communications continuity.
Volume placements concentrate in Low Earth Orbit; the faster expansion belongs to Highly Elliptical Orbit as polar access gains operational priority.
Application:
Mission-specific procurement reflects shifting joint force doctrine toward spectrum dominance and contested logistics. Budget authority migrates from platform ownership toward service-level outcomes across multi-orbit architectures.
- Secure Communications:Encrypted tactical links for maneuver forces employ anti-jam waveforms and frequency-hopping protocols. Current program spending anchors here in the United States as Space Force leasing arrangements displace traditional capital expenditure models.
- Electronic Warfare:Satellite-based jamming, signals intelligence collection, and RF sensing for spectrum dominance represent the steepest investment trajectory. United Kingdom defense planners accelerate procurement for joint electromagnetic spectrum operations.
- Battlefield Surveillance:Synthetic aperture radar and electro-optical payloads deliver persistent area monitoring for targeting and damage assessment.
- Reconnaissance:High-resolution imaging for strategic intelligence collection serves national-level consumers with specialized security clearance requirements.
- Positioning & Navigation:GPS augmentation and alternative PNT signals harden against denial in contested environments.
Secure Communications captures current budget share; Electronic Warfare climbs fastest as spectrum control becomes central to joint operations.
End User:
Customer-type segmentation reveals procurement authority fragmentation across defense and intelligence hierarchies. Contracting vehicles diverge between operational commands and civilian agency acquisition offices.
- Defense Forces:Military service branches dominate platform acquisition for tactical communications and surveillance. Budget authority concentrates with United States Space Force and United Kingdom Strategic Command for constellation deployment.
- Intelligence Agencies:Signals intelligence services deepen dedicated satellite procurement as space-based collection gains operational priority; this segment remains underpenetrated relative to traditional defense demand.
- Homeland Security:Border surveillance and disaster response applications drive specialized procurement for domestic situational awareness.
- Space Operations Commands:Unified combatant commands coordinate cross-service satellite utilization and prioritize interoperability standards.
Defense Forces anchor procurement volume; Intelligence Agencies expand most quickly as dedicated space-based SIGINT gains priority.
Technology:
Technology segmentation tracks hardware-software convergence in payload design. Programmable systems displace fixed-function hardware across frequency bands and mission profiles.
- Radio Frequency:Software-defined radio payloads enable programmable spectrum allocation and rapid reprogramming for emerging electronic warfare threats. United States and United Kingdom forces mandate RF flexibility for future constellation tranches.
- Signal Processing:Onboard digital beamforming and interference cancellation compress hardware refresh cycles while enabling dynamic resource allocation.
- Laser Communications:Free-space optical links offer high-bandwidth, low-probability-of-intercept transmission for cross-satellite and space-to-ground connectivity.
- Encryption:Quantum-resistant algorithms and hardware security modules protect against computational cryptanalysis advances.
- Data Relay:Store-and-forward or bent-pipe architectures bridge disconnected tactical users with strategic command nodes.
Radio Frequency deployments dominate current procurement; Laser Communications gains share fastest as anti-jam requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth element processing in Mountain Pass, California anchors North American satellite magnet supply chains. German precision manufacturing clusters in Bavaria produce radiation-hardened electronic substrates. Israeli aerospace engineering corridors around Haifa specialize in miniaturized sensor integration for tactical platforms.
United States
Space Force procurement concentrates in El Segundo and Colorado Springs for Low Earth Orbit constellation deployment. ITAR export controls administered by the US Department of State restrict foreign supplier access to classified payload contracts. Lockheed Martin's classified manufacturing infrastructure in Sunnyvale dominates prime contractor positioning for military satellite buses.
United Kingdom
Strategic Command accelerates Skynet program leasing arrangements for resilient battlefield communications. Ministry of Defence procurement rules mandate domestic supply chain provenance for sovereign satellite capabilities. Airbus Defence and Space facilities in Stevenage anchor European payload integration for NATO-aligned architectures.
Germany
Bundeswehr demand for geostationary trunk communications persists despite LEO proliferation trends. ESA coordination through the European Defence Fund pools member state resources for sovereign space assets. OHB SE operations in Bremen and Munich concentrate satellite bus manufacturing for continental defense markets.
France
Direction Générale de l'Armement prioritizes electronic warfare payloads for spectrum dominance operations. CNES and Thales Alenia Space partnerships in Cannes and Toulouse drive signals intelligence satellite development. REACH and RoHS compliance requirements restrict hazardous materials in defense electronics assembly processes.
Israel
Israel Defense Forces demand compact tactical satellites for regional surveillance and secure communications. Ministry of Defense procurement channels favor domestic suppliers for classified reconnaissance platforms. Israel Aerospace Industries facilities near Tel Aviv specialize in electro-optical payload miniaturization for export markets.
Tactical Satellite Market Competitive Landscape
Global majors compete with regional champions across classified payload integration and sovereign satellite manufacturing. The vendor base stratifies between US primes with security-cleared infrastructure and European consortia leveraging ESA funding mechanisms. Two archetypes dominate: vertically integrated defense conglomerates controlling satellite bus and payload production, and specialist subsystem suppliers focused on hardened electronics and sensor modules. Competitive moves center on supply chain restructuring for ITAR compliance and multi-orbit service contract consolidation.
Within the US prime contractor tier, Lockheed Martin and Northrop Grumman exemplify vertically integrated positioning through captive satellite bus manufacturing and classified payload integration. Boeing occupies a hybrid archetype spanning commercial and defense orbital regimes. Among European players, Airbus Defence and Space and Thales Alenia Space represent consortium-based models leveraging ESA member state coordination for sovereign capability development.
| Leading Market Players |
|---|
| Lockheed Martin |
| Northrop Grumman |
| Boeing |
| Raytheon Technologies |
| Airbus Defence and Space |
| Thales Alenia Space |
| L3Harris Technologies |
| Israel Aerospace Industries |
| OHB SE |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of radiation-hardened electronics and classified satellite buses anchors supply positions for US primes while concentrating pricing power with security-cleared manufacturers. This integration pattern forces non-domestic suppliers to absorb ITAR compliance premiums or exit classified payload markets entirely.
Pricing Analysis
Service bundling separates platform acquisition from launch assurance and orbital operations support. Three-tier pricing structure across premium, standard, and economy levels tracks ITAR certification depth and domestic supply chain provenance. Price differentiation hinges on security clearance infrastructure and anti-jam signal processing capability. Cost compression in standard-tier commercial-derived platforms is intensifying because ESA member states are pooling procurement leverage through the European Defence Fund. Intelligence agencies exhibit lowest price sensitivity due to mission-critical requirements and classified program budgets.
Supply Chain Analysis
Domestic-content mandates from the US Space Force and UK Ministry of Defence are reshaping sourcing toward Colorado Springs, El Segundo, and Stevenage facilities. Geographic supply concentration draws from the United States, Germany, and Israel for satellite bus manufacturing, payload integration, and miniaturized sensor production respectively. Raw material dependencies rest on rare earth element processing in California, radiation-hardened substrates from Bavarian precision clusters, and specialized solder alloys reformulated for REACH and RoHS compliance. Single-source vulnerability concentrates in qualified launch providers meeting National Security Space Launch requirements. Distribution runs through defense ministry central procurement offices rather than commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration races are accelerating as primes pursue captive control over radiation-hardened component supply to defend margins against ITAR compliance cost inflation.
For Market Incumbents: Acquire cleared workforce pipelines and classified manufacturing infrastructure to defend prime contractor positioning against emerging specialist subsystem suppliers. Consolidate multi-orbit service contract authority with defense ministry procurement offices in Washington and London. Reinforce backward integration into radiation-hardened electronics to offset cost premiums from domestic supply chain mandates. For New Entrants and Emerging Players: Enter via dual-use technology convergence channels bridging commercial remote sensing platforms with military-grade encryption standards. Target intelligence agency procurement as the most penetrable buyer segment beyond traditional defense forces. Pursue ESA funding mechanisms for sovereign capability development as the primary go-to-market pathway in continental European markets. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated defense conglomerates seeking satellite bus and payload production capabilities. Long-term viability favors suppliers with demonstrated launch reliability and security-cleared infrastructure. Watch ITAR reform discussions and emerging EU space security procurement rules as the critical inflection signal for competitive boundary redraw.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Radiation-Hardened Electronics Production | Lockheed Martin's Sunnyvale infrastructure demonstrates how in-house component supply secures prime contractor positioning against ITAR cost pressure. |
| Multi-Orbit Service Contract Consolidation | UK Skynet leasing arrangements displace capital expenditure models and concentrate vendor selection authority with Strategic Command procurement. |
| ESA Member State Coordination | European Defence Fund pooling reduces sovereign dependency on non-European providers and creates preferential access for allied suppliers. |
| Software-Defined Radio Payload Mandates | US Space Force and UK forces require programmable RF systems that compress hardware refresh cycles and enable rapid electronic warfare reprogramming. |
| REACH and RoHS Compliance Qualification | German and French primes accelerate lead-free assembly processes to maintain market access across ESA member state procurement channels. |
Research Methodology
Independent corroboration across defense procurement officers, satellite program executives, and classified payload engineers underwrites the qualitative findings in this study. Primary interviews with Space Force acquisition leads, ESA coordination officials, and prime contractor supply chain directors combined with secondary validation from National Security Space Launch filings, European Defence Fund disbursement records, and ITAR compliance disclosure databases. Bottom-up constellation deployment tracking and top-down defense budget appropriation analysis provided triangulation across market sizing dimensions.
Comparable-period anchoring to historical procurement cycles from geostationary platform acquisitions through proliferated LEO constellation rollouts structured the forecast framework. Segmentation modeling spanned orbital regime, mission application, end-user hierarchy, and technology payload type throughout the projection horizon. CAGRs derived from deployment timeline compression, refresh cycle acceleration, and electronic warfare investment trajectory curves. Forecast inputs incorporated ITAR reform probability weighting and EU space security procurement rule implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ITAR liberalization or delayed European sovereign capability consolidation. Analytical boundaries exclude commercial broadband constellation overlap and purely scientific space agency missions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Satellite Transponder Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Satellite Signal Meter Market
Satellite
Remote Sensing Satellite Market
Satellite
South Korea Satellite Communication Market
Satellite
US Satellite Connectivity Market
Satellite
Satellite Communication Subsystem Market
Satellite
Satellite Internet Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Satellite Antenna Market