
 Tactical Footwear Market | 2026-2036
Tactical Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Footwear Market Intelligence
The push for sustainable materials, including recycled polyester and bio-based leather alternatives, is repositioning product development priorities for tactical gear manufacturers. Nike leverages its massive R&D budget to innovate with lightweight, durable synthetics for its tactical lines. Danner sustains its market position through a focus on premium, handcrafted leather boots for professional users. Meanwhile, 5.11 Tactical specializes in purpose-built gear for law enforcement and first responders, controlling a key distribution channel.
Tactical footwear comprises boots and shoes engineered for high-performance use in demanding conditions. Key features include reinforced ankle support, slip-resistant outsoles meeting ASTM F2913 standards, and lightweight construction using materials like Cordura nylon. The military application segment remains the largest by volume, driven by government contracts and established replacement cycles. Leather continues to dominate the premium boot category, while nylon and polyester blends represent the fastest-growing material segment due to their weight and breathability advantages.
Product quality and safety are governed by standards like ISO 9001 for manufacturing and specific performance criteria set by military procurement bodies. The US Berry Amendment mandates domestic sourcing for Department of Defense contracts, while the EU's REACH regulation restricts certain chemicals in footwear materials. Manufacturers must navigate the trade-off between traditional durability associated with heavy materials and the operational demand for lighter, more athletic footwear.
Market Dynamics
The central dynamic in the tactical footwear market is the structural tension between legacy durability requirements and the modern operational demand for athletic performance. This conflict forces a continuous trade-off between the protection offered by heavy, traditional materials like leather and the agility provided by lightweight synthetics.
Growth Catalysts
- Modernization Programs:Government-funded initiatives to upgrade law enforcement and military personnel equipment, particularly in North America and Europe, create consistent, large-volume demand cycles for footwear meeting new performance specifications.
- Crossover Recreation:The adoption of tactical-style boots by consumers for demanding outdoor activities like hiking, hunting, and airsoft expands the total addressable market beyond professional end-users and diversifies revenue streams.
- Material Innovation:The integration of advanced materials like Cordura nylon and proprietary waterproof-breathable membranes allows for the creation of lighter, more comfortable boots without completely sacrificing durability, appealing to users focused on mobility.
Market Restraints
- Material Cost Volatility:The price of high-quality, full-grain leather and specialized synthetic textiles is subject to fluctuations in global commodity markets, creating margin pressure for manufacturers of premium, handcrafted boots.
- Regulatory Compliance Burden:Adherence to chemical restrictions under the EU's REACH framework for leather and rubber components adds significant testing, documentation, and supply chain validation costs for brands operating in Europe.
- Sourcing Restrictions:Procurement mandates like the US Berry Amendment, which require domestic sourcing for Department of Defense contracts, limit the supplier base and can increase production costs compared to using global supply chains.
Strategic Opportunities
- Sustainable Product Lines:Developing footwear using recycled polyesters, bio-based leather alternatives, and environmentally certified materials provides a path to capture demand from government agencies and consumers with sustainability mandates.
- Emerging Geographies:Military and police modernization programs in Eastern European and Southeast Asian nations represent significant white-space opportunities for manufacturers able to meet local tender requirements and performance criteria.
- Smart Footwear Integration:The incorporation of embedded sensors for biometric monitoring, location tracking, and fatigue analysis offers a new frontier for product differentiation, targeting special operations and advanced first responder units.
Industry Challenges
- Supply Chain Complexity:Manufacturers face the operational challenge of managing intricate global supply chains for components while simultaneously ensuring compliance with domestic sourcing regulations in key government contracts.
- Counterfeit Products:The proliferation of low-cost, non-compliant counterfeit boots, particularly through online marketplaces, erodes brand value and poses significant safety risks to users who unknowingly purchase substandard gear.
- Multi-Standard Certification:Products must often be certified against a complex matrix of standards, including ISO 9001 for quality, ASTM for slip resistance, and specific, bespoke requirements from individual military procurement bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Footwear Market |
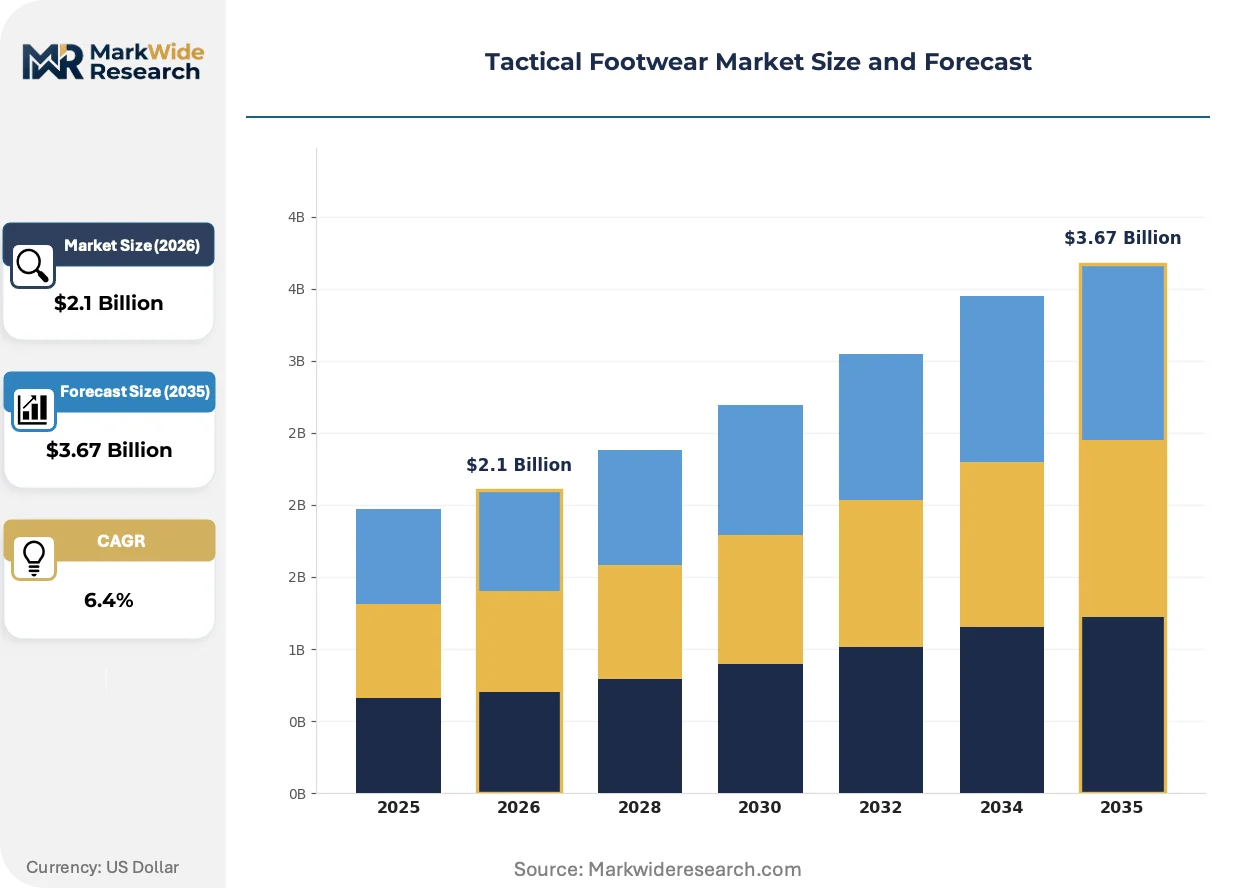
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Boots, Shoes, Sandals, Sneakers Material: Leather, Nylon, Polyester, Rubber Application: Military, Law Enforcement, Outdoor, Security End User: Professional, Recreational, Industrial, Civilian |
| Companies Covered | Belleville Boot Company, ASICS Corporation, Nike, Danner, Garmont International, Adidas AG, Salomon, 5.11 Tactical, Under Armour, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Footwear Market Strategic Shifts & Innovations
Product evolution is defined by the hybridization of athletic shoe technology with the ruggedness of traditional combat boots. This convergence creates footwear that balances protection and mobility, driven by the operational needs of users who perform diverse tasks in a single duty cycle.
Advanced polymer composites and additive manufacturing techniques like 3D printing are enabling highly customized footwear components. Special operations forces and elite law enforcement SWAT teams are the primary early adopters, valuing the ability to tailor outsole tread and midsole cushioning to specific mission profiles. This on-demand production capability is decentralizing performance, allowing for mission-specific footwear to be created outside of traditional mass-manufacturing constraints.
The European Union's REACH regulation imposes stringent controls on substances used in manufacturing, directly impacting footwear components. This forces a re-evaluation of leather tanning processes to avoid restricted chemicals like chromium VI and the sourcing of polymers free from certain phthalates. The premium leather boot category is most affected, accelerating R&D into compliant alternative tanning agents and bio-based synthetics to ensure continued market access.
A significant behavioral change is the rise of individual-led purchasing, where soldiers and police officers select their own footwear rather than using standard-issue items. This consumer-driven trend disintermediates large institutional procurement cycles and favors brands with strong direct-to-professional marketing. The pattern is most visible in the United States law enforcement market and among specialized military commands within NATO countries.
Tactical Footwear Market Segmentation
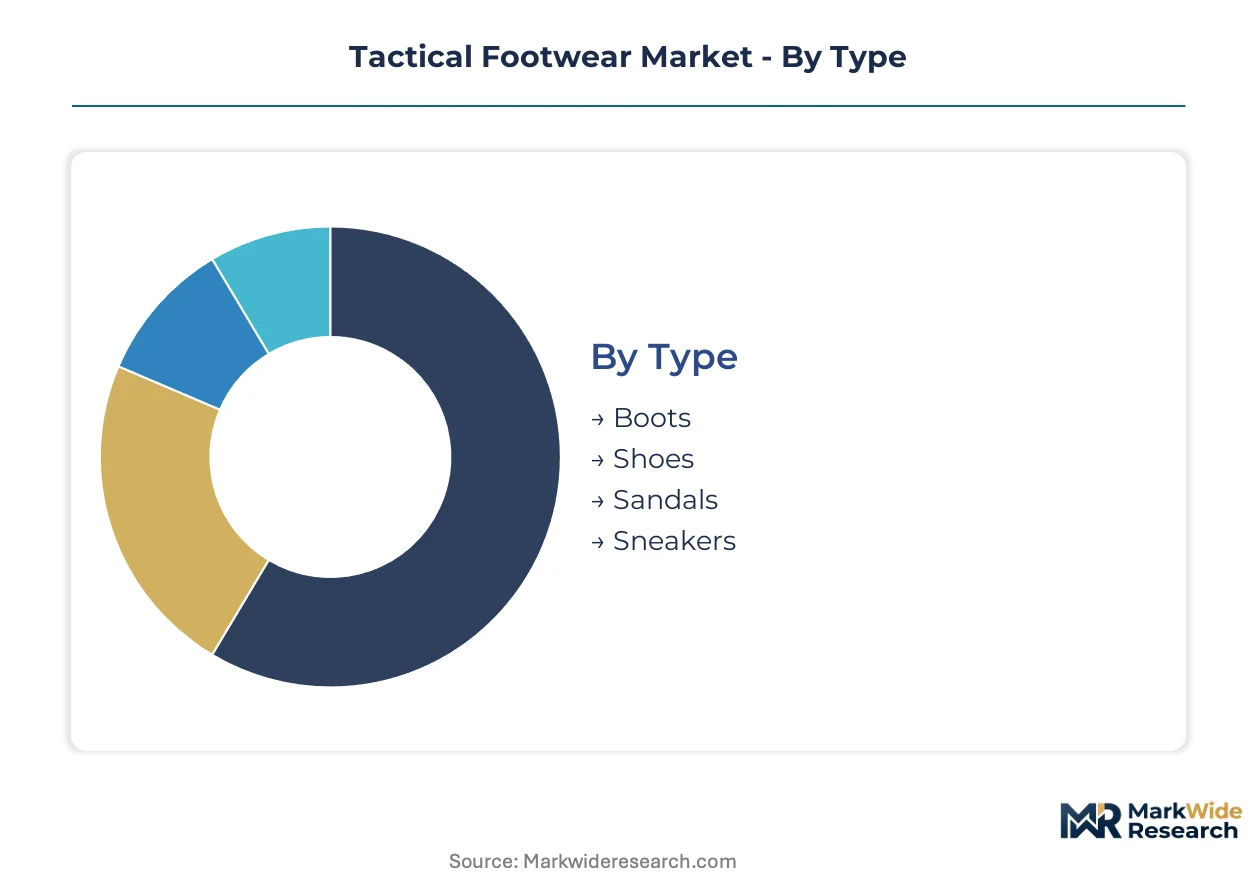
The tactical footwear market's segmentation reflects the diverse operational needs and material preferences of its end-users. Understanding these distinct categories allows manufacturers to tailor product development and distribution strategies effectively. Each segment presents unique performance requirements and purchasing drivers for specialized gear.
Type:
Buyers often select footwear type based on the balance required between ankle support, agility, and protection for specific mission profiles.
- Boots:These high-cut footwear items provide extensive ankle support and protection, often featuring reinforced toes and waterproof membranes. Demand concentrates in military and law enforcement sectors for their ruggedness in diverse operational environments.
- Shoes:Lower-cut than boots, tactical shoes prioritize agility and lighter weight, frequently incorporating athletic shoe technology for enhanced mobility. Law enforcement and first responders increasingly seek these for urban operations where speed is critical.
- Sandals:Specialized tactical sandals offer breathability and quick-drying properties for warm weather or aquatic operations, often with robust outsoles for traction. They serve niche applications within military and outdoor recreational contexts.
- Sneakers:Tactical sneakers combine athletic shoe comfort with enhanced durability and grip, appealing to users requiring discreet yet capable footwear. This type gains traction among plainclothes officers and for training scenarios.
Volume sits with Boots; growth tilts toward Shoes.
Material:
Material choices are primarily driven by the required balance of durability, weight, and breathability for the intended application.
- Leather:This natural material provides superior durability, abrasion resistance, and a classic aesthetic, particularly in premium tactical boots. Demand for full-grain leather is influenced by traditional preferences for robustness and the need for chemical compliance under regulations like EU REACH.
- Nylon:A synthetic polymer, nylon offers an excellent strength-to-weight ratio and breathability, often used in Cordura weaves for lightweight tactical footwear. Its adoption is accelerating in military and law enforcement applications seeking reduced load and enhanced comfort.
- Polyester:Similar to nylon, polyester blends provide lightweight and quick-drying characteristics, frequently used in upper constructions and linings for tactical shoes. This material is gaining share fastest due to its versatility and cost-effectiveness.
- Rubber:Primarily used for outsoles, rubber provides essential slip resistance and traction, meeting standards such as ASTM F2913. Specialized rubber compounds are critical for performance in varied terrains and weather conditions.
Demand is driven by Leather, with Nylon showing strong expansion.
Application:
Customer type significantly influences the specific performance features and regulatory compliance required for tactical footwear.
- Military:This segment encompasses footwear designed for combat, training, and field operations, prioritizing durability, traction, and protection in extreme conditions. Procurement cycles in the United States, driven by the Berry Amendment, ensure domestic sourcing for Department of Defense contracts.
- Law Enforcement:Footwear in this segment supports police, SWAT, and tactical units with features like slip-resistant outsoles and reinforced construction for urban and patrol duties. Modernization programs in North America and Europe consistently drive demand for advanced performance gear.
- Outdoor:This application includes hiking, hunting, and other demanding recreational activities where users seek rugged, protective, and comfortable footwear. The crossover appeal of tactical styles expands this market segment.
- Security:Personnel in private security, corrections, and emergency services require durable and comfortable footwear for long shifts and various operational environments. Emphasis is placed on comfort, slip resistance, and professional appearance.
Military accounts for the majority of sales, while Law Enforcement is gaining traction.
End User:
Performance requirements dictate the design and material selection for tactical footwear, ensuring suitability for specific user groups.
- Professional:This category includes military personnel, police officers, and first responders who require specialized footwear for their duty-specific requirements. Procurement decisions are influenced by stringent performance standards and institutional budgets.
- Recreational:Consumers engaging in activities like hiking, hunting, and airsoft seek tactical-style footwear for its perceived durability and rugged aesthetic. This segment benefits from crossover appeal and individual-led purchasing trends.
- Industrial:Workers in physically demanding industrial environments such as construction or manufacturing use tactical-grade footwear for enhanced safety and durability. These products often meet specific safety certifications.
- Civilian:General consumers who appreciate the ruggedness, comfort, and style of tactical footwear for everyday wear or light outdoor activities constitute this segment. Brand reputation and aesthetic appeal are significant purchase factors.
Professional represents the established base, and Recreational is expanding its share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C. area remains a focal point for tactical footwear procurement, influencing global demand patterns. Government contracts for military and law enforcement personnel consistently drive innovation and volume. Manufacturers align product development with evolving operational requirements, ensuring compliance with stringent performance standards.
United States
Military and police modernization programs, alongside individual-led purchasing by service members, significantly drive demand for high-performance tactical footwear. The US Berry Amendment mandates domestic sourcing for Department of Defense contracts, influencing manufacturing locations and supply chains. Fort Bragg, North Carolina, serves as a key military base, driving demand for specialized combat boots and related gear.
Germany
European law enforcement upgrades and a robust outdoor recreation market generate consistent demand for advanced tactical footwear. The EU's REACH framework heavily influences material selection for leather and rubber components, forcing manufacturers to adopt compliant alternatives. Pirmasens, a traditional footwear manufacturing hub, adapts its expertise to produce technical tactical gear for both professional and civilian users.
Japan
Equipment upgrades for the Japan Self-Defense Forces and a growing civilian outdoor segment fuel demand for durable and lightweight tactical footwear. METI provides guidance on industrial standards for performance and safety in specialized apparel and protective gear. Tokyo's urban centers see high demand for discreet tactical sneakers among security personnel and for everyday wear.
India
Police force modernization initiatives and increasing paramilitary equipment needs represent significant demand drivers for tactical footwear across India. BIS standards for protective footwear are increasingly adopted for domestic procurement, ensuring quality and safety. Kanpur, a traditional leather industry center, is strategically repositioning its manufacturing capabilities for technical boot production to meet new requirements.
Australia
Defense force equipment replacement cycles and a robust outdoor and emergency services sector contribute to steady demand for tactical footwear. TGA regulations on material safety impact specialized footwear components, particularly those used in protective applications. Melbourne's design and innovation firms collaborate on advanced tactical footwear concepts, focusing on local operational conditions.
Tactical Footwear Market Key Industry Players
The competitive structure tilts toward specialized manufacturers with deep expertise in performance gear. The tactical footwear market exhibits a tiered structure, with established brands focusing on premium segments and smaller players innovating in niche areas. Consolidation occurs in segments requiring extensive R&D and compliance with military specifications. Strategic archetypes include heritage brands emphasizing traditional durability, athletic wear giants leveraging advanced material science, and purpose-built tactical specialists. Companies pursue portfolio diversification and geographic expansion to capture new demand across professional and recreational user bases.
Within the athletic performance segment, Nike leverages its substantial research and development capabilities to integrate lightweight, durable synthetics into its tactical lines. Danner, a heritage brand, occupies a premium position through its focus on handcrafted leather boots, appealing to professional users seeking traditional robustness and craftsmanship. Meanwhile, 5.11 Tactical exemplifies the purpose-built specialist archetype, providing gear specifically engineered for law enforcement and first responders with a strong distribution channel. These three companies represent distinct strategies, from broad athletic innovation to niche traditional quality and specialized utility, shaping the competitive dynamics of the market.
| Leading Market Players |
|---|
| Belleville Boot Company |
| ASICS Corporation |
| Nike |
| Danner |
| Garmont International |
| Adidas AG |
| Salomon |
| 5.11 Tactical |
| Under Armour |
Cost & Logistics Intelligence
Advanced polymer composites and additive manufacturing techniques reshape cost economics for specialized tactical footwear while concentrating supply in advanced manufacturing hubs. This shift introduces both efficiency gains and new dependencies within the production ecosystem.
Pricing Analysis
Outcome-based pricing anchors tactical footwear sales for professional users, where performance directly impacts operational success. Price differentiation stems from certification levels, such as ASTM F2913 for slip resistance, and established brand premium for durability. Pricing softness reflects material cost volatility and increasing regulatory compliance burdens, particularly for premium leather components. Professional users exhibit the least price sensitivity, prioritizing performance, while the recreational segment is more price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers for advanced waterproof-breathable membranes and high-performance rubber outsoles. Geographic supply concentration includes East Asia for synthetic textiles and Europe for premium leather. Key raw material dependencies involve full-grain leather, Cordura nylon, and specialized rubber compounds. Regulatory restrictions, such as the US Berry Amendment and EU REACH framework, present a structural risk by limiting the supplier base. Distribution runs through specialized retail channels and direct government procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tactical footwear market is experiencing a technology-transition phase, with athletic shoe technology increasingly displacing traditional heavy boot construction.
For Market Incumbents: Acquire advanced material science capabilities to counter the threat of new lightweight synthetics from athletic wear giants. Invest in domestic manufacturing capacity to meet US Berry Amendment sourcing requirements for government contracts. Consolidate smaller specialized brands to expand product portfolios and distribution networks. Adapt existing production lines to incorporate sustainable materials, addressing evolving procurement mandates.
For New Entrants and Emerging Players: Begin with underserved niche segments, like specialized units requiring custom 3D-printed outsole geometries for specific mission profiles. Target emerging geographies in Southeast Asia with police force modernization programs, leveraging agile product development. Focus on direct-to-professional marketing strategies to capture individual-led purchasing trends. Develop bio-based leather alternatives to differentiate products in a sustainability-conscious market.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated specialists possessing strong brand equity and direct government contract access. Long-term viability depends on adapting to individual-led purchasing trends and sustainable material demands. Monitor shifts in military procurement away from standard issue gear as an inflection indicator. Evaluate companies with strong R&D in lightweight, durable synthetics and advanced manufacturing techniques.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced material R&D | Manufacturers gain competitive advantage through lighter, more durable footwear for professional users. |
| Expand direct-to-professional sales channels | Brands capture individual-led purchasing trends among military and law enforcement personnel. |
| Acquire specialized component manufacturers | Companies secure critical supply chains for waterproof membranes and high-performance outsoles. |
| Develop sustainable product lines | Brands meet government agency and consumer demand for environmentally certified tactical gear. |
| Target emerging markets in Eastern Europe | Manufacturers access new demand from police and military modernization programs in growing regions. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for the tactical footwear market analysis. Primary research involved interviews with military procurement officers, law enforcement equipment managers, material scientists, and specialized retail buyers. This approach ensured robust bottom-up and top-down triangulation of market figures. Secondary sources included government procurement databases, ASTM standards, and EU REACH documentation.
Market granularity was modeled across Type, Material, Application, End User, and performance tier dimensions. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates of new technologies. Key forecast inputs included government spending on defense and law enforcement modernization programs, alongside material innovation cycles across the analysis window.
Underlying measurement precision varies by segment; professional and military applications carry tighter precision than recreational and civilian segments. Forecasts reflect assumptions regarding geopolitical stability and raw material price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Wedge Boots Market
Footwear
Duck Boots Market
Footwear
Asia Pacific Footwear Market
Footwear
Europe Athletic Footwear Market
Footwear
UGG Boots Market
Footwear
Global Espadrille Flats Market
Footwear
Indian Footwear Market
Footwear
Cowboy Boots Market
Footwear
Running Shoes Market
Footwear
Shoe Insoles Market
Footwear
Driving Footwear Market
Footwear
Loafers Market
Footwear
Global Recovery Footwear Market
Footwear
E-Commerce Footwear Market
Footwear
Sandals Market
Footwear
Shoe Rental Service Market