
 Global Recovery Footwear Market | 2026-2036
Global Recovery Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recovery Footwear Market Outlook
Premium cushioning specifications are reorganizing competitive dynamics in recovery footwear. OOFOS leverages proprietary foam compounds to dominate the post-activity comfort niche. Adidas AG sustains R&D intensity across biomechanically tuned midsole platforms. HOKA ONE ONE anchors its position through maximalist cushioning architectures that extend from performance running into recovery applications.
Recovery footwear encompasses post-exertion and therapeutic shoes engineered with energy-return foams, rocker-bottom geometries, and arch-support structures to reduce plantar pressure and accelerate muscular recovery. Manufacturing emphasizes compression-molded EVA and injection-blown rubber compounds calibrated for durometer ratings between 30-50 Shore C. The material dimension reveals EVA formulations commanding the largest volume share due to cost-efficiency, while textile uppers represent the fastest-growing category as breathability and sustainability claims reshape consumer preference. End-user segmentation shows athletes generating the highest per-unit margins, though casual users contribute the broadest volume base as wellness positioning expands addressable demand beyond sports medicine.
Regulatory oversight spans the US FDA for therapeutic claims on medical-grade recovery products, the EU REACH framework restricting chemical inputs in foam production, and California's Proposition 65 labeling requirements affecting rubber component transparency. These standards elevate compliance costs for new entrants while rewarding incumbent investments in certified supply chains. Stakeholders must monitor evolving material restrictions and therapeutic classification thresholds as jurisdictions tighten boundaries between wellness marketing and regulated medical device claims.
Market Dynamics
The EU Green Deal's material sustainability mandates are forcing footwear manufacturers to reconstitute supply chains around bio-based foams and recycled textile inputs, creating a compliance-driven technology race that favors incumbents with certified sourcing infrastructure.
Growth Catalysts
- Professional athlete recovery protocols:Post-workout recovery prioritization among elite sports programs is institutionalizing recovery footwear as standard equipment rather than discretionary purchase.
- REACH chemical restrictions:The EU framework's tightening limits on hazardous foam additives are accelerating investment in non-toxic formulation R&D across European manufacturing bases.
- Wellness culture penetration:Running participation rates in the United States are sustaining premium category development through consumer education on biomechanical recovery benefits.
Market Restraints
- Petrochemical input volatility:EVA and synthetic rubber pricing fluctuates with crude oil markets, compressing margin predictability for foam-dependent manufacturers.
- East Asian foam concentration:Compression-molded EVA production clusters in China and Taiwan create geographic supply vulnerability for brands without multi-source strategies.
- Medical device classification friction:FDA therapeutic claim thresholds impose lengthy 510(k) pathways for products positioned between wellness and clinical recovery.
Strategic Opportunities
- India urban wellness expansion:Metro fitness culture in Mumbai and Bangalore offers first-mover positioning for recovery footwear before market saturation.
- Direct-to-consumer biometric fitting:Smartphone-based foot-scanning apps are collapsing traditional retail dependency for sizing accuracy.
- EU circular economy mandates:Extended producer responsibility frameworks incentivize take-back programs and closed-loop material recovery systems.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized footwear designers with podiatric and materials science cross-training command premium compensation and limited availability.
- Multi-jurisdiction label compliance:California Proposition 65, EU REACH, and emerging state-level chemical disclosure laws require parallel certification tracks that extend launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recovery Footwear Market |
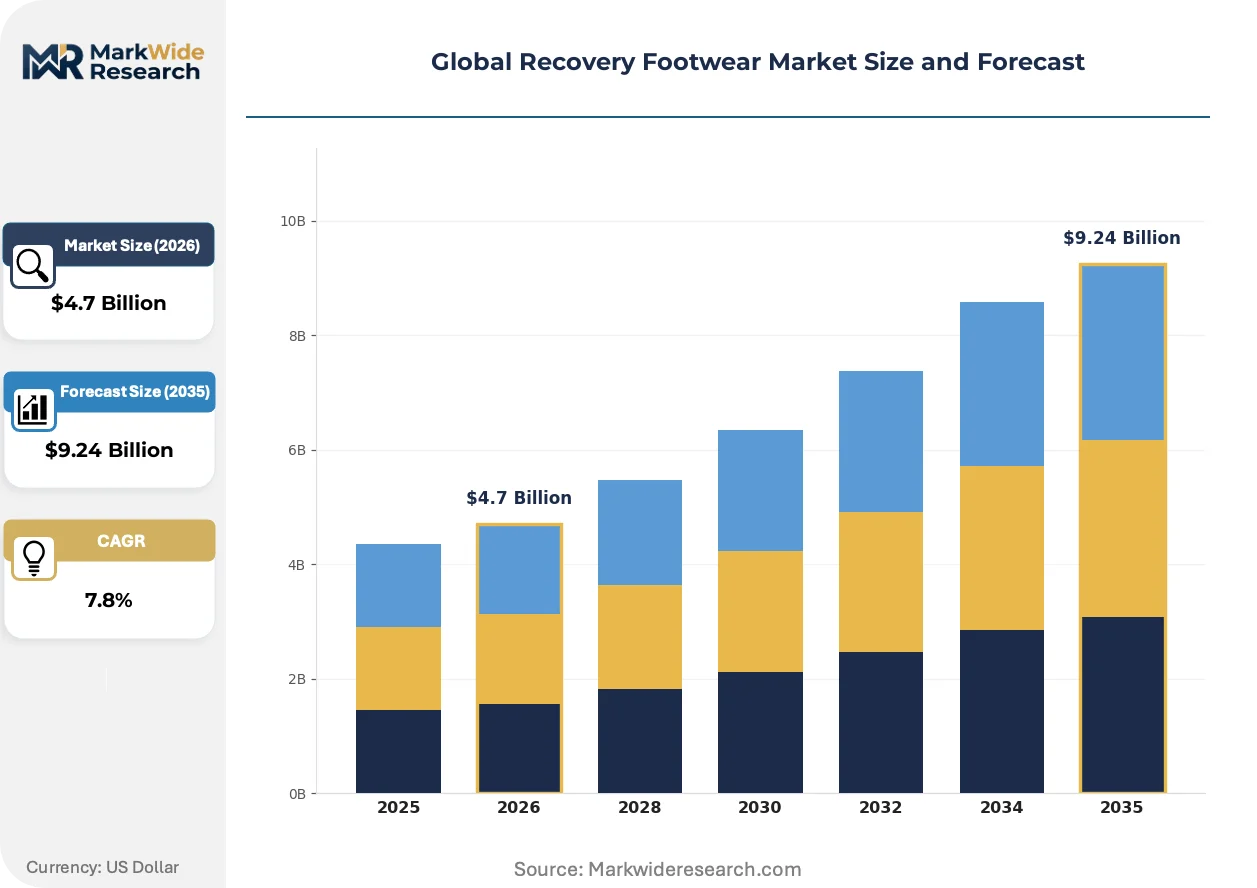
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.24 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Flops, Sandals, Sneakers, Clogs Material: EVA, Rubber, Textile, Foam End User: Athletes, Casual Users, Seniors, Rehabilitation Patients Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | OOFOS, NIKE, Inc., Adidas AG, HOKA ONE ONE, Kane Footwear, Under Armour, Okabashi, SKECHERS USA, Inc., ASICS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recovery Footwear Market Strategic Shifts
Material science breakthroughs and regulatory pressure on petrochemical inputs are actively restructuring how recovery footwear is engineered, tested, and brought to market across premium and mass tiers.
Bio-based foam chemistry is bifurcating the midsole materials landscape. Algae-derived and sugarcane-based EVA alternatives now deliver durometer ratings matching petroleum formulations. Adidas and smaller specialists are scaling these inputs for performance-tier lines, while cost-sensitive manufacturers retain conventional foams. This material divergence is compressing price-competitive positioning for brands without sustainable supply chain credentials.
REACH Annex XVII restrictions on isocyanates and plasticizers are compelling reformulation of polyurethane foam production across European contract manufacturers. The industrial consequence is accelerated migration toward water-based adhesive systems and thermal bonding processes. Medical-grade recovery products face the steepest compliance burdens, with German and French producers investing most heavily in alternative chemistry pilot lines.
Subscription-based replacement cycles are displacing transactional retail for committed runners. Brands now offer annual membership models delivering fresh recovery footwear at biomechanically recommended intervals. This channel innovation concentrates most visibly in the United States, where Strava-integrated purchasing and automated wear-tracking apps are collapsing traditional repurchase decision friction.
Global Recovery Footwear Market Segmentation
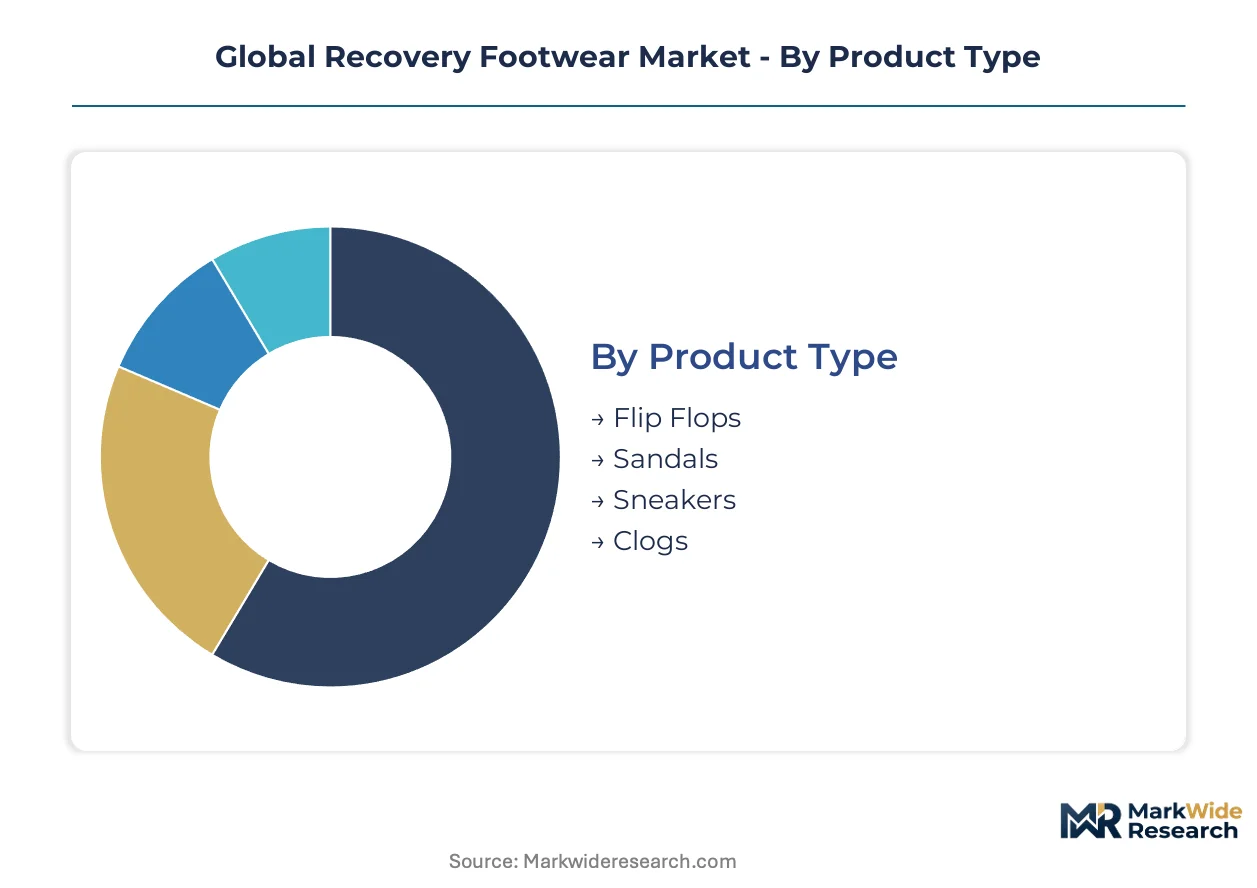
Recovery footwear segmentation reveals divergent margin profiles across product architectures and user contexts. Material chemistry and distribution channel choices determine which manufacturers capture value from professional athletes versus casual wellness consumers.
Product Type:
Flip flops face the most acute substitution threat from conventional casual footwear, forcing recovery-positioned variants to differentiate through patented foam geometries and biomechanical certifications.
- Sneakers:Full-coverage uppers with compression-molded midsoles and rocker-bottom geometries dominate professional athlete adoption. Demand concentrates in the United States where marathon training programs institutionalize post-run recovery protocols.
- Sandals:Open-strap architectures with arch-support footbeds bridge athletic and casual use cases. German and French consumers drive premium positioning through podiatric reimbursement pathways.
- Flip Flops:Minimalist Y-strap designs with energy-return foam bases compete on portability and price accessibility.
- Clogs:Enclosed heel cups with slip-resistant outsoles serve rehabilitation and clinical settings requiring hygiene compliance.
Sneakers anchor the volume base while sandals gain share at the steepest rate.
Material:
Cost tier stratification separates premium bio-based formulations from commodity petrochemical inputs, with mid-market brands caught between sustainability credentials and margin pressure.
- EVA:Compression-molded ethylene-vinyl acetate delivers calibrated durometer ratings between 30-50 Shore C for controlled energy return. Chinese and Taiwanese manufacturing clusters supply cost-sensitive global brands.
- Foam:Injection-blown polyurethane and proprietary closed-cell compounds enable medical-grade pressure redistribution. REACH Annex XVII compliance costs favor incumbent European producers with reformulated water-based chemistry lines.
- Rubber:Natural and synthetic outsole compounds provide abrasion resistance and ground contact stability.
- Textile:Knitted and woven uppers from recycled polyester and bio-based yarns address EU Green Deal circularity mandates.
EVA formulations dominate production volume while textile uppers expand most quickly on sustainability-driven consumer preference.
End User:
Application context determines pricing power, with clinical and athletic segments commanding specification premiums that casual wellness markets cannot support.
- Athletes:Elite sports programs and amateur endurance competitors generate the highest per-unit margins through performance-verified product claims. United States running participation rates sustain premium category development.
- Rehabilitation Patients:Post-surgical and chronic condition users require FDA-classified therapeutic features with pressure-mapping validation. German statutory health insurance reimbursement codes accelerate adoption.
- Casual Users:Wellness-culture consumers seeking post-workout comfort represent the broadest volume base.
- Seniors:Fall-prevention and arthritis management applications drive stability-focused design requirements.
Casual users provide the widest volume foundation while rehabilitation patients deliver the steepest margin expansion trajectory.
Distribution Channel:
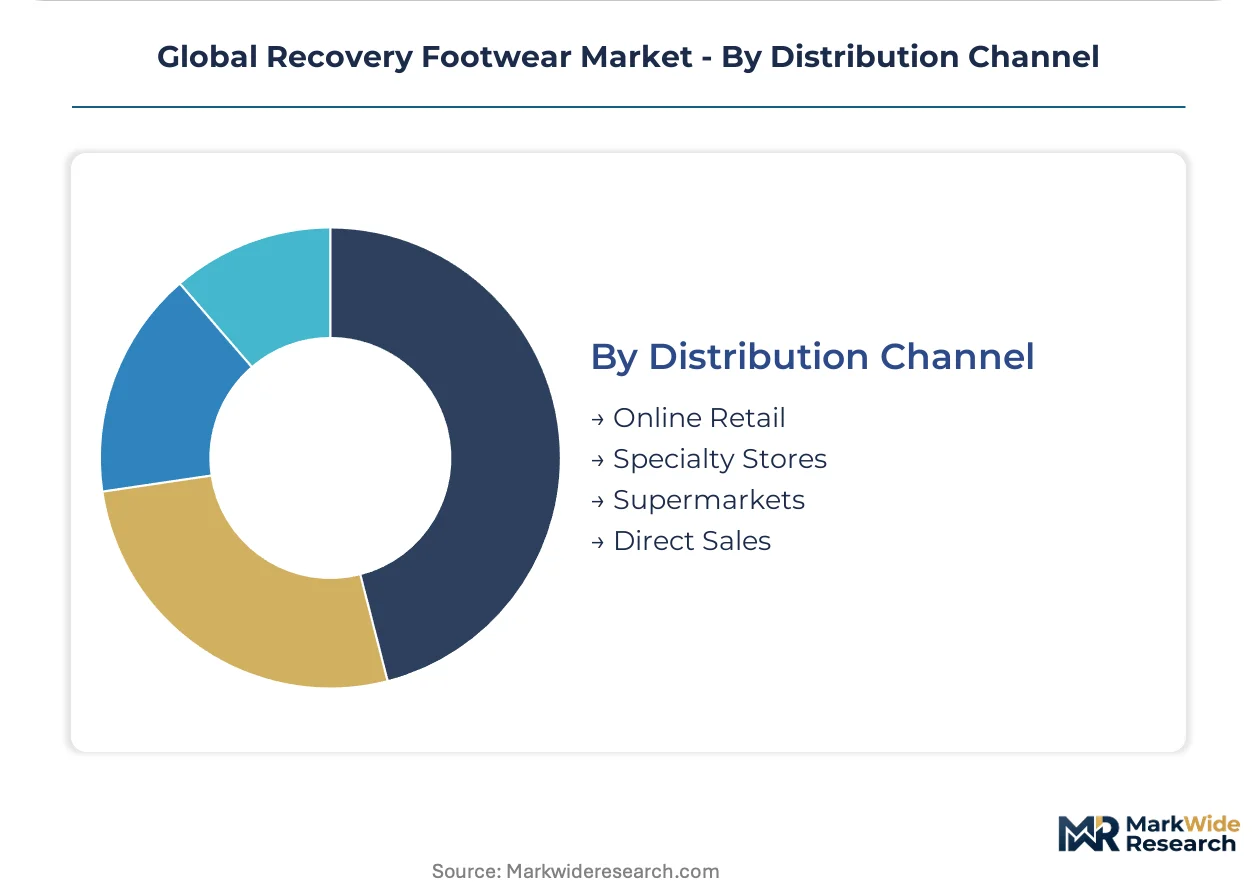
Customer type fragmentation across digital-native and experience-dependent segments rewards hybrid channel architectures over pure-play strategies.
- Online Retail:Direct-to-consumer platforms with smartphone foot-scanning integration collapse sizing friction and enable subscription replacement models. United States Strava-integrated purchasing concentrates technology investment.
- Specialty Stores:Running and outdoor retailers with gait-analysis services command loyalty from serious athletes seeking expert fitting.
- Direct Sales:Brand-owned flagship and pop-up experiences control narrative and margin capture.
- Supermarkets:Mass-market shelf placement reaches price-sensitive casual users with limited specification requirements.
Specialty stores anchor athletic segment volume while online retail climbs the fastest on digital fitting technology deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compression-molded EVA production clusters in China and Taiwan supply cost-sensitive global brands, while European manufacturers lead REACH-compliant foam reformulation. Demand fragmentation across athletic rehabilitation, casual wellness, and clinical applications creates divergent growth profiles by geography.
United States
Marathon training programs and Strava-integrated purchasing institutionalize recovery footwear as standard post-run equipment. FDA therapeutic claim thresholds impose 510(k) pathways for medical-grade products, elevating compliance costs for clinical-positioned entrants. The Pacific Northwest and Colorado Front Range anchor specialty retail density with gait-analysis service integration.
Germany
Statutory health insurance reimbursement codes accelerate podiatric recovery footwear adoption among rehabilitation patients. ECHA REACH Annex XVII restrictions on isocyanates compel polyurethane foam reformulation across Bavarian and North Rhine-Westphalian manufacturing bases. The Stuttgart industrial corridor hosts pilot lines for water-based adhesive systems and thermal bonding alternatives.
China
Domestic running participation growth and urban fitness culture expansion drive mid-market volume demand. MIIT industrial standards for footwear materials intersect with provincial environmental compliance mandates in Guangdong and Zhejiang production zones. The Dongguan manufacturing cluster dominates compression-molded EVA supply for export-oriented brands.
Japan
Aging demographics and fall-prevention priorities sustain stability-focused design requirements for senior-oriented recovery products. METI circular economy guidelines incentivize closed-loop material recovery systems among domestic manufacturers. The Kansai region around Osaka maintains specialized biomechanical engineering talent pools for podiatric footwear development.
India
Metro fitness culture in Mumbai and Bangalore creates first-mover positioning opportunities before market saturation. BIS footwear quality standards and DGFT import regulations shape competitive entry pathways for international brands. The Tamil Nadu leather and footwear manufacturing belt is diversifying into technical foam midsole production for athletic applications.
Global Recovery Footwear Market Competitive Environment
Concentration sits with diversified sportswear conglomerates and specialized recovery footwear pure-plays competing across distinct price-performance tiers. The vendor base spans multinational athletic brands with biomechanical R&D infrastructure, regional foam specialists with manufacturing scale advantages, and direct-to-consumer challengers with subscription-based replacement models. Two dominant competitive moves define current positioning: portfolio diversification into adjacent wellness categories and backward integration into proprietary foam compound development.
Within the specialized recovery footwear tier, OOFOS and Kane Footwear exemplify brand architectures built entirely around post-activity comfort positioning rather than performance-to-recovery extension strategies. Among diversified athletic conglomerates, Adidas AG and HOKA ONE ONE occupy positions where maximalist cushioning R&D from performance running migrates into dedicated recovery product lines. ASICS and SKECHERS USA, Inc. sit within the scale-driven mid-market segment, leveraging existing distribution infrastructure and price-accessible manufacturing to capture casual wellness demand expansion.
| Leading Market Players |
|---|
| OOFOS |
| NIKE, Inc. |
| Adidas AG |
| HOKA ONE ONE |
| Kane Footwear |
| Under Armour |
| Okabashi |
| SKECHERS USA, Inc. |
| ASICS |
| Others |
Value Chain & Pricing Dynamics
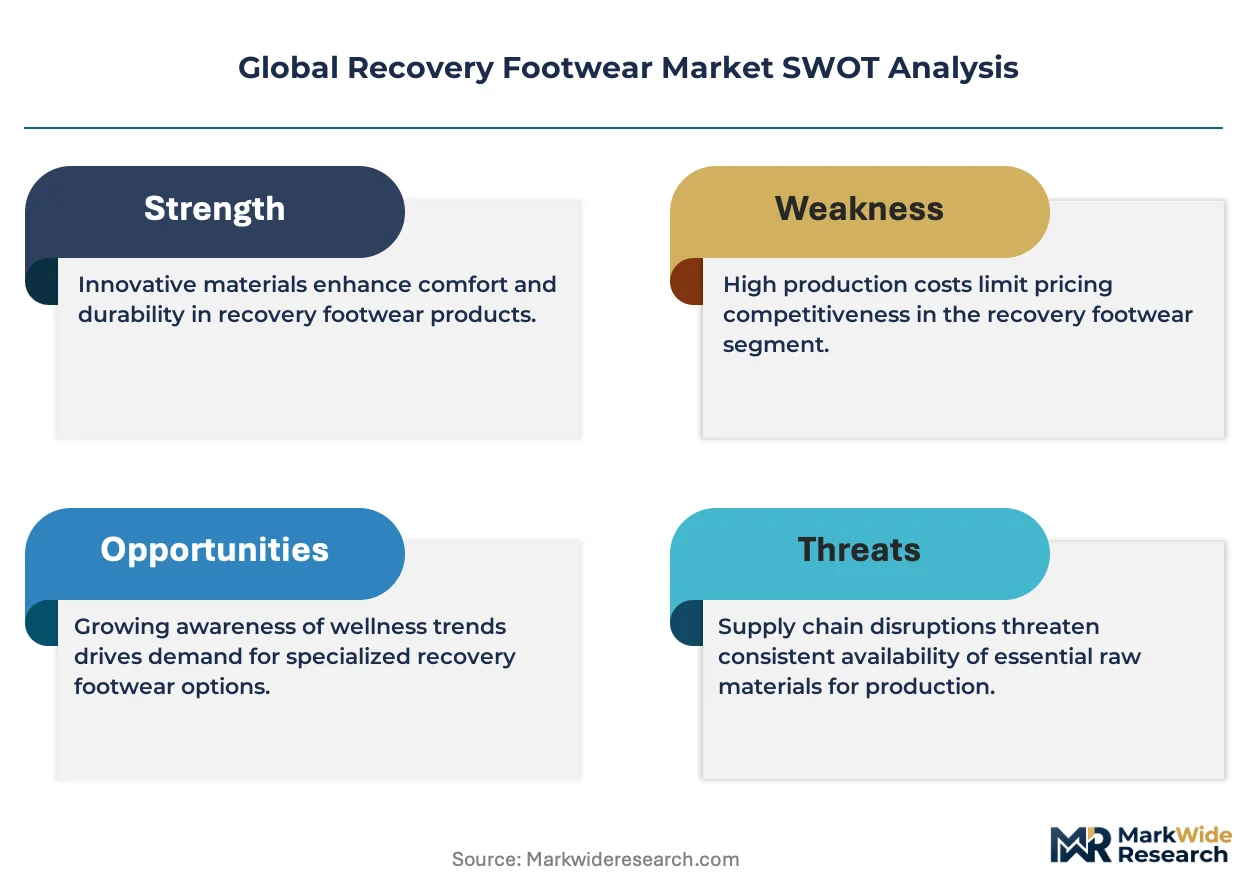
Bio-based foam chemistry replacing petroleum-derived EVA is redrawing manufacturing geography toward European REACH-compliant facilities while compressing margins for brands without certified sustainable supply chains. This substitution dynamic simultaneously elevates compliance costs and fragments pricing power across premium and mass-market tiers.
Pricing Analysis
EU REACH Annex XVII dictates the pricing tier structure through differentiated compliance burdens on foam chemistry. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade certified products from wellness-positioned footwear and mass-market casual variants. Price differentiation stems from certification grade and vertical integration depth. Cost compression in the economy tier is intensifying because Chinese EVA supply faces REACH-equivalent scrutiny on export batches. Casual wellness consumers exhibit highest price sensitivity while rehabilitation patients and elite athletes accept specification premiums.
Supply Chain Analysis
China and Taiwan anchor compression-molded EVA production for cost-sensitive global brands while Germany and France pilot REACH-compliant water-based chemistry lines. Raw material flows draw from petrochemical feedstocks, algae-derived foam precursors, and recycled textile inputs. Single-source vulnerability concentrates in Dongguan-area EVA molding clusters serving export-oriented footwear brands. Distribution runs through direct-to-consumer platforms with biometric fitting, specialty running retailers with gait analysis, and mass-market supermarkets for price-accessible segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment—REACH compliance infrastructure and FDA 510(k) pathways create switching costs that lock in institutional buyers and deter unqualified challengers.
For Market Incumbents: Fortify proprietary foam compound development through backward integration into bio-based chemistry R&D, securing supply chain control over algae-derived and sugarcane-based EVA alternatives. Expand certified manufacturing capacity in Germany and France to capture REACH-driven substitution demand while defending against Asian cost competitors. Prioritize FDA therapeutic classification for medical-grade lines to elevate reimbursement access barriers.
For New Entrants and Emerging Players: Differentiate on direct-to-consumer biometric fitting technology, collapsing traditional retail dependency with smartphone foot-scanning apps and subscription replacement models. Target India's metro fitness markets in Mumbai and Bangalore before incumbent saturation. Pursue white-space positioning in senior fall-prevention segments where stability-focused design requirements remain underdeveloped.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive bio-based foam supply and multi-jurisdiction certification infrastructure. Long-term viability across the projection horizon hinges on regulatory compliance depth rather than manufacturing scale alone. Monitor EU circular economy mandate implementation timelines as inflection indicators for material recovery system valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Foam Chemistry | Captive supply of algae-derived EVA insulates margins from REACH reformulation costs. |
| Direct-to-Consumer Biometric Fitting Platform | Strava-integrated foot-scanning apps collapse sizing friction and enable subscription models. |
| FDA 510(k) Therapeutic Classification Pathway | Medical device status unlocks rehabilitation patient reimbursement and institutional procurement. |
| EU Circular Economy Take-Back Program | Extended producer responsibility compliance secures brand positioning in sustainability-driven markets. |
| India Metro Market Flagship Expansion | First-mover positioning in Mumbai and Bangalore captures urban fitness culture before saturation. |
Study Parameters
Operator-level perspectives from footwear R&D directors, podiatric biomechanists, specialty retail buyers, and EU regulatory compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from ECHA REACH substance databases, FDA 510(k) clearance records, MIIT industrial standards filings, and customs trade flow data. Bottom-up segment sizing and top-down macro constraint checks triangulated volume and value estimates.
Sensitivity analysis across petrochemical price volatility scenarios, REACH enforcement intensity variations, and runner participation rate trajectories stress-tested projection robustness. Segmentation dimensions modeled include product architecture, material chemistry tier, end-user application context, and distribution channel type. CAGRs were derived from fitted growth curves against historical adoption patterns and regulatory mandate implementation schedules. Industry-specific forecast inputs encompassed marathon participation indices and statutory health insurance reimbursement code expansions.
Material uncertainties—foam chemistry substitution breakthroughs, EU circular economy mandate acceleration, FDA therapeutic claim reclassification—sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory stability and consumer education penetration rates. Recalibration cycles align with material shifts in REACH Annex XVII amendments and major market reimbursement policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
United States Footwear Market
Footwear
Flip Flops Market
Footwear
UGG Boots Market
Footwear
US Slip Resistant Shoes Market
Footwear
Refurbished Running Shoes Market
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Ankle Boots Market
Footwear
Tennis Shoes Market
Footwear
Tactical Footwear Market
Footwear
Lace Up Boots Market
Footwear
Europe Barefoot Shoes Market
Footwear
Premium Shoes Market
Footwear
Loafers Market
Footwear
Shoe Rental Service Market
Footwear
Slip Resistant Shoes Market
Footwear
Western Boots Market