
 Global Espadrille Flats Market | 2026-2036
Global Espadrille Flats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Espadrille Flats Market Analysis
The EU Green Deal's sustainable textile strategy is decoupling espadrille demand from fast-fashion supply chains. TOMS Shoes, LLC leverages its one-for-one giving model to sustain consumer loyalty in ethical footwear segments. Chanel S.A. anchors ultra-premium positioning through controlled jute sourcing and limited artisan workshops in Spain. Kering Group competes across multiple luxury houses with integrated Mediterranean manufacturing.
Espadrille flats are flat-soled casual footwear constructed with woven jute rope soles, canvas or cotton uppers, and traditionally hand-stitched construction using natural fiber thread. The jute midsole provides breathable, lightweight structure suited to warm-climate casual and resort wear. Classic product types occupy the volume core, while wedge variants command higher margin pools in premium channels. Cotton material grades dominate unit economics, though linen compositions differentiate artisan-positioned brands. Women end users represent the established demand base, with unisex sizing emerging as a growth contour in direct-to-online distribution.
REACH chemical restrictions govern EU-market dye and adhesive formulations, while California's Proposition 65 extends comparable substance disclosure requirements for US-bound shipments. BIS textile labeling standards in India and GB standards in China add compliance layers for jute and natural rubber components. Stakeholders must monitor how diverging national sustainability certifications reshape raw material qualification costs and factory audit protocols.
Market Dynamics
EU Green Deal textile sustainability requirements are forcing espadrille supply chains to decouple from conventional jute and rubber sourcing, redirecting procurement toward certified organic fiber networks and traceable artisan workshops.
Growth Catalysts
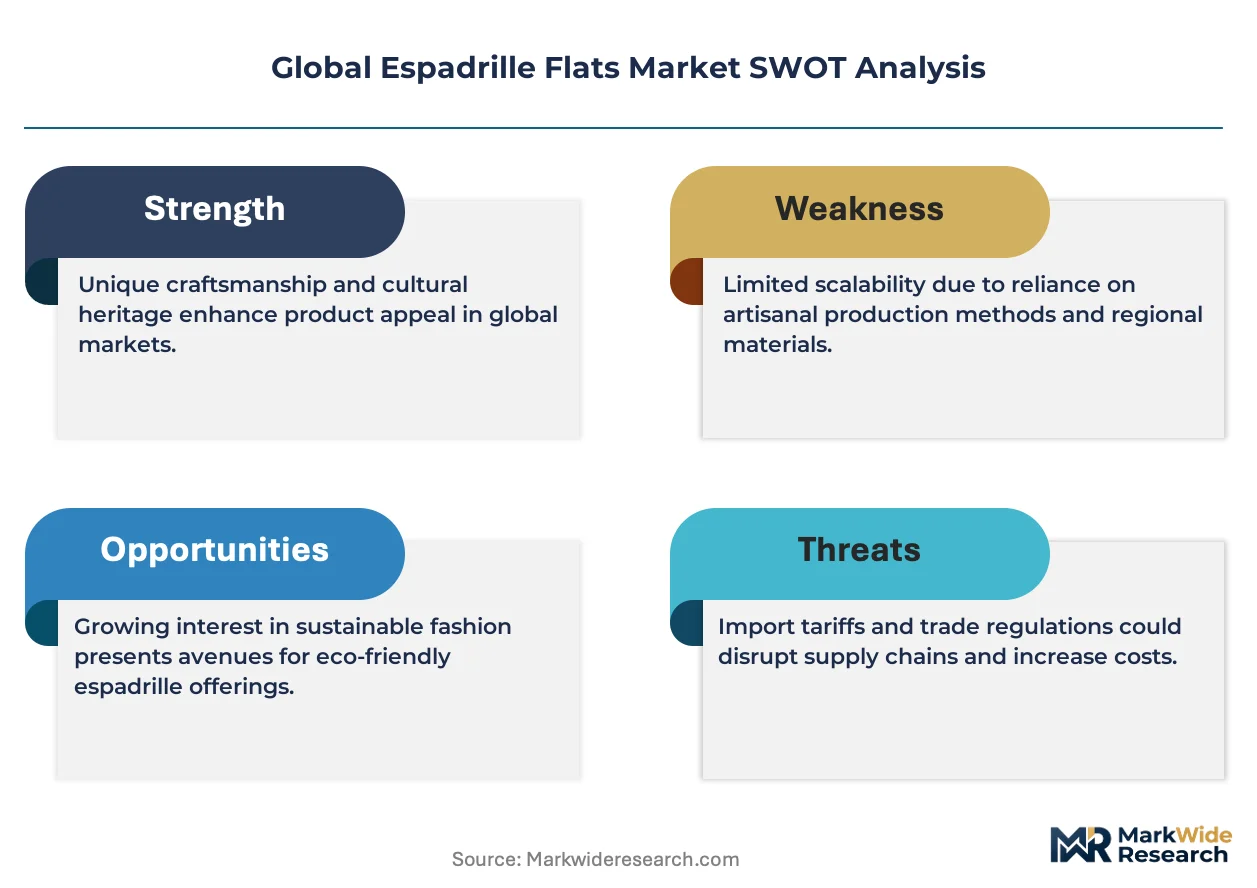
- REACH chemical restrictions:EU-market dye and adhesive compliance mandates are filtering out non-certified suppliers, concentrating volume with pre-qualified Spanish and French manufacturers.
- Resort wear expansion:Women's casual footwear collections are absorbing espadrilles as core warm-climate staples, extending seasonal purchase windows beyond traditional summer peaks.
- Alicante craft clusters:Concentrated artisan knowledge in Spain's Valencia region preserves hand-stitching techniques that command premium positioning in direct-to-online channels.
Market Restraints
- Jute price volatility:Weather-dependent harvests in Bangladesh and India create raw material cost swings that compress margin predictability for mid-tier brands.
- Artisan labor scarcity:Aging craftsperson populations in France's Pays Basque region constrain production scaling for hand-finished premium lines.
- Synthetic sole substitution:Molded polyurethane alternatives from Asian manufacturing hubs undercut natural rubber outsoles on unit cost in mass-market segments.
Strategic Opportunities
- Unisex sizing expansion:Direct-to-online distribution platforms are capturing male and non-binary demand segments previously excluded from women's-focused sizing architectures.
- CSRD disclosure mandates:EU corporate sustainability reporting requirements create procurement preference for espadrille suppliers with pre-audited organic fiber documentation.
- Linen-cotton blends:Hybrid natural fiber uppers are differentiating artisan-positioned brands from commodity cotton competitors in premium resort channels.
Industry Challenges
- Multi-jurisdiction labeling compliance:Simultaneous adherence to BIS textile standards, California Proposition 65, and EU Green Deal traceability requirements strains quality assurance teams.
- Legacy dyehouse retooling:Water-based adhesive and natural pigment transitions require capital investment that smaller Alicante workshops cannot self-finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Espadrille Flats Market |
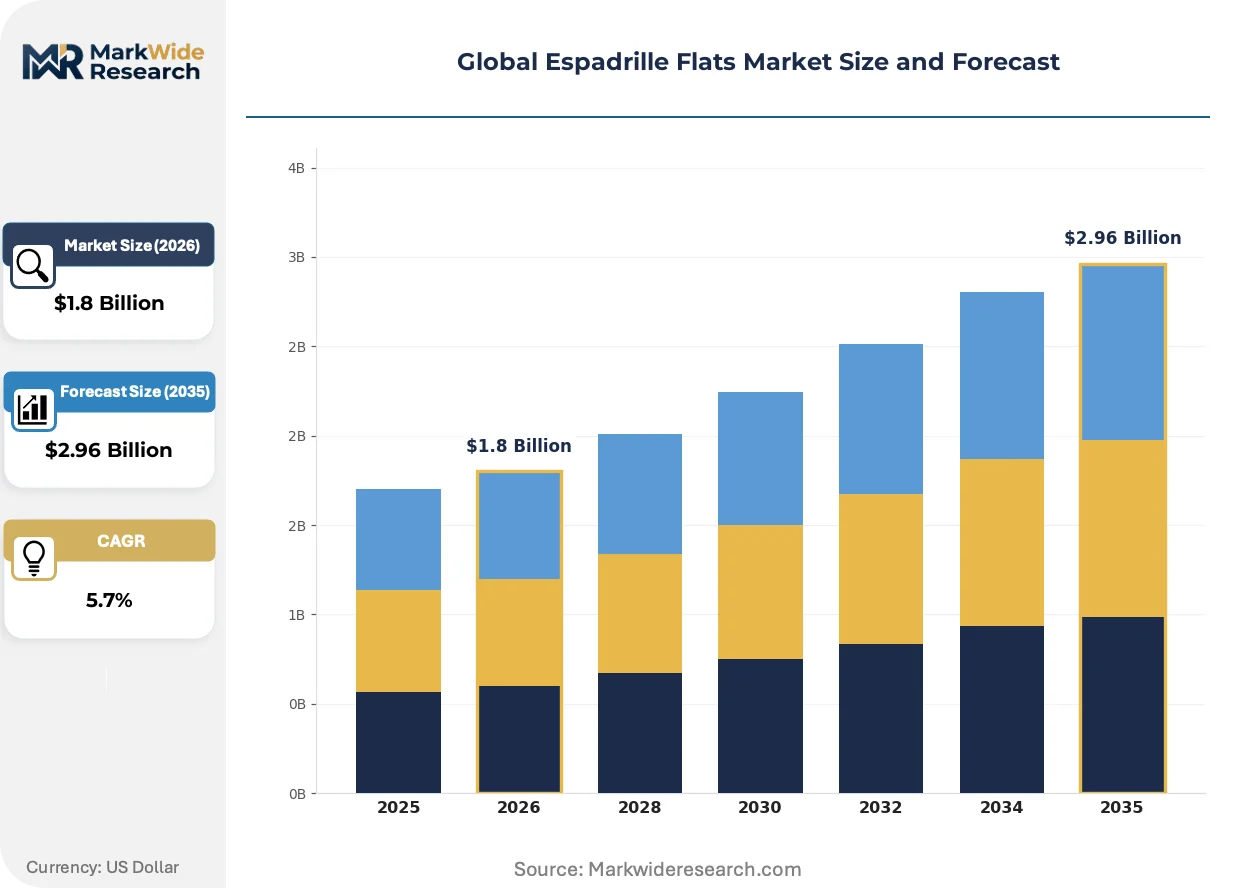
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Wedge, Casual, Sports Material: Cotton, Linen, Jute, Synthetic End User: Women, Men, Children, Unisex Distribution Channel: Online, Retail Stores, Boutique, Department Stores |
| Companies Covered | ECCO, Steve Madden, TOMS Shoes, LLC, Manolo Blahnik, Clarks, Chanel S.A., Kering Group, Nine West, Valentino, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Espadrille Flats Market Emerging Trajectories
Material science advances and regulatory disclosure mandates are converging to reshape how espadrille manufacturers source, certify, and distribute natural fiber footwear across Mediterranean production clusters and digital retail channels.
Recycled ocean plastic uppers are expanding into traditional canvas espadrille construction, displacing virgin cotton in mid-market resort collections. Sustainable footwear brands are adopting these hybrid materials at accelerating pace to satisfy EU Green Deal circularity benchmarks. The technology is expanding into price tiers previously reserved for conventional natural fiber construction.
California's Proposition 65 enforcement is extending substance disclosure requirements to natural rubber outsoles and jute midsoles in US-bound shipments. Manufacturers must now document heavy metal content in soil-retained fiber batches, adding testing overhead to export workflows. Premium Spanish exporters are responding by segregating California-certified production lines from EU-general inventory.
Direct-to-consumer platforms are compressing traditional wholesale cycles for artisan-positioned espadrille brands. Resort wear buyers are bypassing multi-brand retailers to commission limited runs from named Alicante workshops, collapsing margin layers but demanding shorter lead times. This channel rotation is most visible in North American and Australian markets where geographic distance from European production clusters previously favored importer-distributor intermediaries.
Global Espadrille Flats Market Segmentation
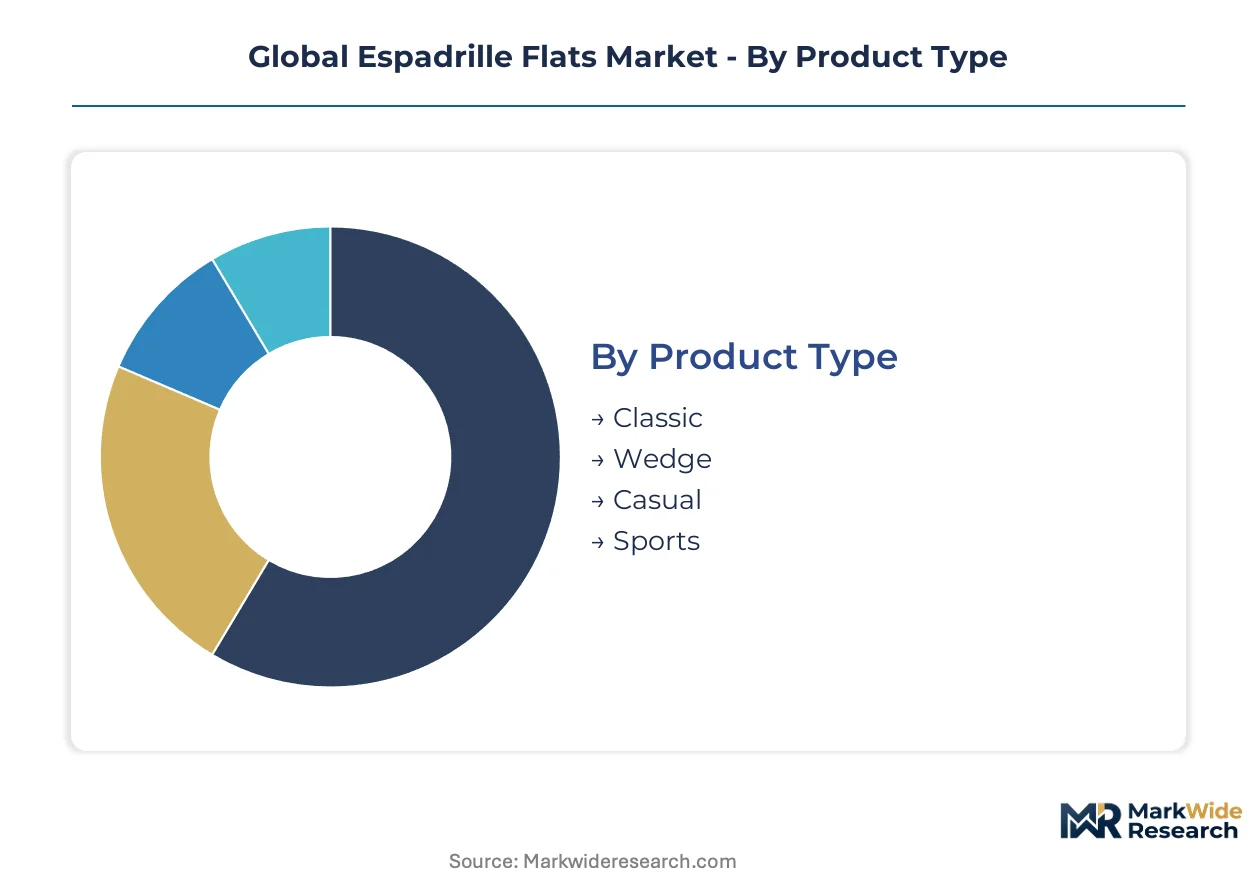
Espadrille supply chains fragment across four critical dimensions that shape procurement priorities. Product architecture determines margin pools, material grades govern sustainability compliance, end-user targeting dictates channel selection, and distribution format controls working capital intensity.
Product Type:
Consumer choice hinges on occasion-formality alignment and heel elevation preference.
- Classic:Flat-soled construction with woven jute midsoles and canvas uppers defines the category's heritage identity. Spanish artisan workshops in Alicante province concentrate volume for resort wear buyers seeking authentic Mediterranean provenance, though hand-stitching labor scarcity constrains scaling.
- Wedge:Elevated jute-wrapped heels command premium positioning in department store and boutique channels. French Pays Basque manufacturers anchor supply for this segment, where elevated construction complexity justifies price multiples over flat variants.
- Casual:Simplified uppers and machine-stitched soles target volume distribution through mass-market retail. Bangladesh and Indian assembly lines compete aggressively on unit cost for this specification tier.
- Sports:Reinforced outsoles and moisture-wicking linings adapt espadrille aesthetics to active-lifestyle positioning. Athletic footwear specialists in Portugal and Vietnam are expanding capacity for this hybrid category.
Classic leads on scale; Sports leads on momentum.
Material:
Raw material selection determines regulatory compliance pathways and carbon footprint disclosure obligations.
- Cotton:Conventional and organic grades dominate unit economics across all price tiers. Indian Punjab and Gujarat growing regions supply the majority of fiber for EU-bound production, with BIS textile labeling standards governing traceability documentation.
- Linen:Belgian and French flax cultivation yields premium fiber grades for artisan-positioned brands. Linen-cotton blends are gaining share fastest in direct-to-consumer channels targeting sustainability-conscious resort wear buyers.
- Jute:Bangladesh and West Bengal harvests provide the traditional braided midsole material. Weather-dependent crop yields create procurement volatility that compresses margin predictability for mid-tier manufacturers.
- Synthetic:Recycled ocean plastic and rPET uppers are displacing virgin cotton in mid-market collections. EU Green Deal circularity benchmarks are accelerating adoption of these certified alternatives.
Cotton leads on scale; Linen leads on momentum.
End User:
Size architecture and styling codes segment demand across demographic boundaries.
- Women:Established demand base with sizing granularity from EU 35-42 and US 5-11. Resort and urban casual wardrobes absorb the majority of production volume across all material grades.
- Men:Broader width specifications and subdued color palettes distinguish this segment. Direct-to-online platforms are capturing male demand previously excluded from women's-focused sizing architectures.
- Children:Scaled-down proportions with reinforced toe caps address durability requirements. EU REACH chemical restrictions on dyes and adhesives impose stricter compliance burdens for this sensitive-use category.
- Unisex:Extended size runs and neutral styling accommodate non-binary positioning. Digital-native brands are expanding fastest in this contour by collapsing traditional gendered merchandising.
Women leads on scale; Unisex leads on momentum.
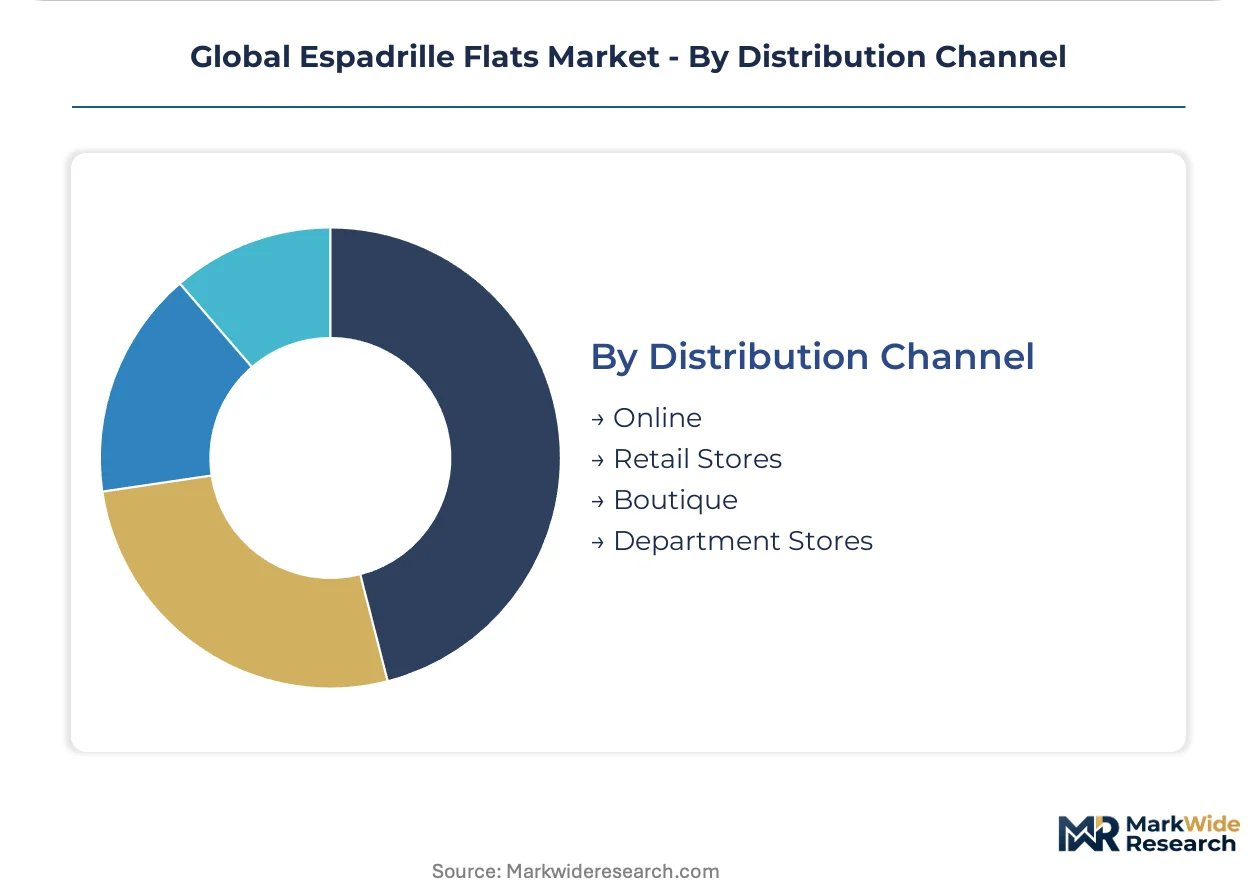
Distribution Channel:
Channel selection determines margin retention, inventory risk allocation, and consumer data access.
- Online:Direct-to-consumer platforms compress wholesale margin layers and enable made-to-order production from named Alicante workshops. California Proposition 65 disclosure requirements add compliance overhead for US-bound shipments.
- Retail Stores:Multi-brand footwear chains provide volume visibility but demand promotional support and seasonal buyback terms. Spanish and French manufacturers prioritize this channel for classic and wedge variants.
- Boutique:Curated independent retailers anchor artisan brand positioning through limited distribution. Hand-finished production from Pays Basque workshops concentrates in this channel.
- Department Stores:Legacy volume buyers with centralized purchasing and private label development programs. Markdown risk and extended payment terms strain working capital for smaller suppliers.
Retail Stores leads on scale; Online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Alicante province birthed mechanized espadrille production during the nineteenth century, establishing craft techniques that now face artisan labor scarcity. France's Pays Basque region refined wedge construction methods that persist in premium channels. Contemporary demand disperses across Mediterranean manufacturing clusters and Asian assembly hubs serving mass-market tiers.
Spain
Resort wear buyers commission limited runs from named Alicante workshops, bypassing traditional wholesale intermediaries. REACH chemical restrictions on dyes and adhesives filter out non-certified suppliers, concentrating volume with pre-qualified Valencia-region manufacturers. Hand-stitching knowledge concentrates in Elche and Elda, though aging craftsperson populations constrain scaling for premium lines.
France
Department store buyers anchor wedge variant procurement through Pays Basque production networks. EU Green Deal textile sustainability requirements redirect jute sourcing toward certified organic fiber networks with traceable documentation. Saint-Jean-de-Luz and Hasparren workshops preserve elevated construction complexity that justifies price multiples over flat-soled alternatives.
United States
California's Proposition 65 enforcement extends substance disclosure requirements to natural rubber outsoles and jute midsoles in import shipments. Direct-to-consumer platforms compress traditional wholesale cycles, with North American buyers commissioning shorter lead times from Mediterranean workshops. Segregated California-certified production lines add testing overhead to Spanish export workflows.
Italy
Luxury footwear houses integrate Mediterranean manufacturing through controlled sourcing of linen-cotton blend uppers. CSRD disclosure mandates create procurement preference for suppliers with pre-audited organic fiber documentation. Tuscany-based finishers specialize in hybrid natural fiber treatments that differentiate artisan-positioned brands from commodity competitors.
India
Bangladesh and West Bengal harvests supply jute midsole material to EU-bound production, with weather-dependent crop yields creating procurement volatility. BIS textile labeling standards govern traceability documentation for cotton grades from Punjab and Gujarat growing regions. Mumbai and Delhi-based trading houses coordinate raw material qualification for export manufacturers.
Global Espadrille Flats Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and craft provenance dimensions. The vendor base stratifies into heritage artisans with controlled workshop access, vertically integrated luxury groups with captive Mediterranean supply, and scale-driven distributors sourcing from Asian assembly networks. Three archetypes dominate: atelier-positioned brands commanding authentic provenance premiums; diversified footwear conglomerates leveraging cross-category sourcing scale; and purpose-driven labels converting ethical positioning into direct-to-consumer loyalty. Competitive moves concentrate on artisan workshop exclusivity arrangements and CSRD-compliant supply chain documentation.
Within the heritage artisan tier, Chanel S.A. and Kering Group occupy positions anchored by controlled jute sourcing and limited Spanish workshop access. TOMS Shoes, LLC exemplifies the purpose-driven archetype through its one-for-one giving model. These three entities represent distinct competitive vectors: ultra-premium positioning through scarcity, integrated luxury manufacturing across multiple houses, and ethical footwear segment loyalty conversion.
| Leading Market Players |
|---|
| ECCO |
| Steve Madden |
| TOMS Shoes, LLC |
| Manolo Blahnik |
| Clarks |
| Chanel S.A. |
| Kering Group |
| Nine West |
| Valentino |
| Others |
Supply Flow & Price Mechanics
Hand-stitching labor costs in Spain's Alicante province cascade through three distinct pricing tiers, with artisan wage premiums separating heritage-positioned workshop output from machine-stitched alternatives sourced from Bangladeshi assembly lines. Jute fiber volatility from Bangladesh and Indian harvests compresses margin predictability for mid-tier brands, forcing procurement shifts toward certified organic fiber networks that command price premiums in EU-compliant channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the espadrille market, with certification grade under EU Green Deal requirements and artisan provenance from named Spanish workshops serving as the primary differentiation drivers. Cost compression in the standard tier is intensifying because synthetic sole substitution from Asian manufacturing hubs undercuts natural rubber alternatives on unit economics. Resort wear buyers demonstrate the least price sensitivity, while mass-market retail channels exhibit acute responsiveness to jute price swings.
Supply Chain Analysis
Direct-to-consumer platforms handle boutique buyer demand through named Alicante workshop commissions, while traditional wholesale channels manage department store volume. Spain, France, and Bangladesh anchor geographic supply concentration, with raw material dependencies centering on Indian cotton, Belgian linen, and Bangladeshi jute. Single-source vulnerability in hand-stitching craft knowledge from aging Pays Basque artisans constrains premium scaling. Distribution runs through direct-to-online channels, multi-brand retail chains, and curated boutique networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the espadrille market rests on CSRD-compliant supply chain documentation that unlocks premium pricing from EU corporate buyers, alongside unisex sizing architecture that captures previously excluded demand segments without incremental material cost.
For Market Incumbents: Anticipate synthetic sole substitution pressure from Asian manufacturing hubs by securing exclusive artisan workshop arrangements in Alicante and Pays Basque clusters. Prioritize backward integration into certified organic jute sourcing networks to defend margin position against commodity fiber price volatility. Channel control through direct-to-consumer platform investment reduces wholesale margin erosion from department store consolidation.
For New Entrants and Emerging Players: CSRD disclosure mandates in Europe open a window for digital-native brands with pre-audited organic fiber documentation to capture procurement preference from sustainability-conscious corporate buyers. The unisex sizing segment represents the most penetrable white space, with male and non-binary demand previously excluded from women's-focused sizing architectures. A made-to-order go-to-market angle from named Alicante workshops collapses inventory risk while commanding artisan provenance premiums.
For Investors and Strategic Acquirers: Roll-up economics work for atelier-positioned brands with controlled workshop access because artisan labor scarcity in France's Pays Basque region creates captive supply advantages that compound with scale. Long-term viability over a five-to-ten year window favors targets with CSRD-compliant documentation infrastructure already in place. Watch for inflection in EU Green Deal enforcement intensity as the signal that organic fiber certification premiums are hardening into structural margin pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Artisan Workshop Exclusivity Arrangement | Controlled access to Alicante hand-stitching knowledge secures premium positioning in direct-to-online channels. |
| Certified Organic Fiber Sourcing Transition | EU Green Deal compliance unlocks procurement preference from CSRD-mandated corporate buyers. |
| Unisex Sizing Architecture Launch | Extended size runs capture male and non-binary demand segments without incremental material cost. |
| Direct-to-Consumer Platform Investment | Wholesale margin compression from department store consolidation makes channel control critical. |
| California-Certified Production Line Segregation | Proposition 65 compliance enables US market access without testing overhead on EU-general inventory. |
Methodological Framework
Direct dialogue with brand managers at heritage espadrille houses, category buyers at multi-brand footwear retailers, supply planners at Mediterranean manufacturing clusters, and channel sales heads at direct-to-consumer platforms grounded qualitative insights. Secondary validation drew from EU Green Deal regulatory filings, REACH chemical restriction documentation, Spanish customs export records, and BIS textile labeling standards. Bottom-up volume modeling from individual workshop capacity and top-down demand triangulation from resort wear buyer surveys converged on segment-level estimates.
Output projections across the analysis window reflect a demand-side model segmented by product architecture, material grade, end-user demographic, and distribution format. CAGRs were derived from elasticity-adjusted price trajectories and volume penetration curves calibrated to artisan labor constraints and synthetic substitution elasticities. Jute harvest volatility coefficients and CSRD adoption timelines served as industry-specific forecast inputs.
Revisions become necessary when EU Green Deal enforcement intensity shifts, artisan labor scarcity accelerates beyond modeled retirement curves, or synthetic sole technology achieves cost parity with natural rubber in premium tiers. Forecasts reflect documented assumptions on certification adoption rates and channel migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
US Slip Resistant Shoes Market
Footwear
Hiking Footwear Market
Footwear
Sneaker Boots Market
Footwear
Footwear Testing Services Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Shoe Insoles Market
Footwear
Desert Boots Market
Footwear
North America Athletic Footwear Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Europe Barefoot Shoes Market
Footwear
Sandals Market
Footwear
Tennis Shoes Market
Footwear
Winter Footwear Market
Footwear
Kids Barefoot Shoes Market
Footwear
Refurbished Sneaker Market
Footwear
Protective Footwear Market