
 Outdoor Hot Tub Market | 2026-2036
Outdoor Hot Tub Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Hot Tub Market Analytics
The outdoor hot tub industry is pivoting around a widening gap between premium acrylic systems with integrated smart controls and commodity inflatable units sold through mass retail channels. Jacuzzi leverages its heritage brand equity and dealer network density to sustain pricing power in the installed segment. Master Spas competes through vertical control over shell manufacturing and proprietary jet systems. Wellis anchors its position across European markets with energy-certified product lines.
An outdoor hot tub constitutes a thermostatically controlled vessel designed for hydrotherapy and recreational immersion, typically constructed from acrylic, fiberglass, or rotomolded polyethylene with integrated heating, filtration, and jet massage systems operating between 100–104°F. Acrylic hot tubs command the dominant share of value pools due to superior durability and customization options, while inflatable variants represent the fastest-expanding volume tier through direct-to-consumer channels. Above-ground installation dominates residential applications for cost and permitting simplicity, though in-ground configurations capture disproportionate margin in luxury new-build projects.
EPA energy-efficiency guidelines and UL electrical safety standards shape product development timelines and certification costs for manufacturers serving North American markets. ISO water-quality management protocols influence filtration system design for export-oriented producers. Stakeholders must monitor evolving building code harmonization across municipalities and the pace of smart-home integration standards to anticipate which product architectures will secure shelf space and specification preference.
Market Dynamics
EPA energy-efficiency standards and evolving insulation technologies are compressing product development cycles while forcing manufacturers to redesign thermal management systems across their entire portfolios.
Growth Catalysts
- Luxury Hospitality Expansion:Resort and wellness property developers across the United States Sun Belt are specifying integrated spa amenities as competitive differentiators in second-home markets.
- Smart-Home Integration:WiFi-enabled controls and voice-activated temperature management are pulling replacement demand from connected-home adopters in suburban residential segments.
- REACH Compliance Advantage:European energy-certified product lines are capturing specification preference among sustainability-focused commercial installers in Germany and France.
Market Restraints
- Acrylic Resin Volatility:Petrochemical feedstock fluctuations compress margin predictability for shell manufacturers dependent on virgin polymer supply.
- Dealer Network Concentration:North American distribution relies on fragmented independent retailers with limited geographic coverage, constraining brand reach into secondary markets.
- Electrical Infrastructure Gaps:Rural property electrification limitations in mountainous regions block installed-base expansion for hardwired 240V systems.
Strategic Opportunities
- Direct-to-Consumer Channels:Inflatable unit manufacturers are bypassing traditional retail through Amazon and dedicated e-commerce platforms, capturing price-sensitive first-time buyers.
- IRA Energy Credits:U.S. residential efficiency incentives are subsidizing heat-pump-equipped models, accelerating replacement cycles in existing installed base.
- Medical Wellness Positioning:Hydrotherapy certification partnerships with physical therapy clinics are opening institutional specification channels previously closed to recreational positioning.
Industry Challenges
- Certification Timeline Compression:UL electrical safety recertification for redesigned heating elements is extending product launch windows by four to six months.
- Installation Labor Scarcity:Licensed electrician and plumbing contractor availability constraints in high-growth counties are creating order fulfillment backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Hot Tub Market |
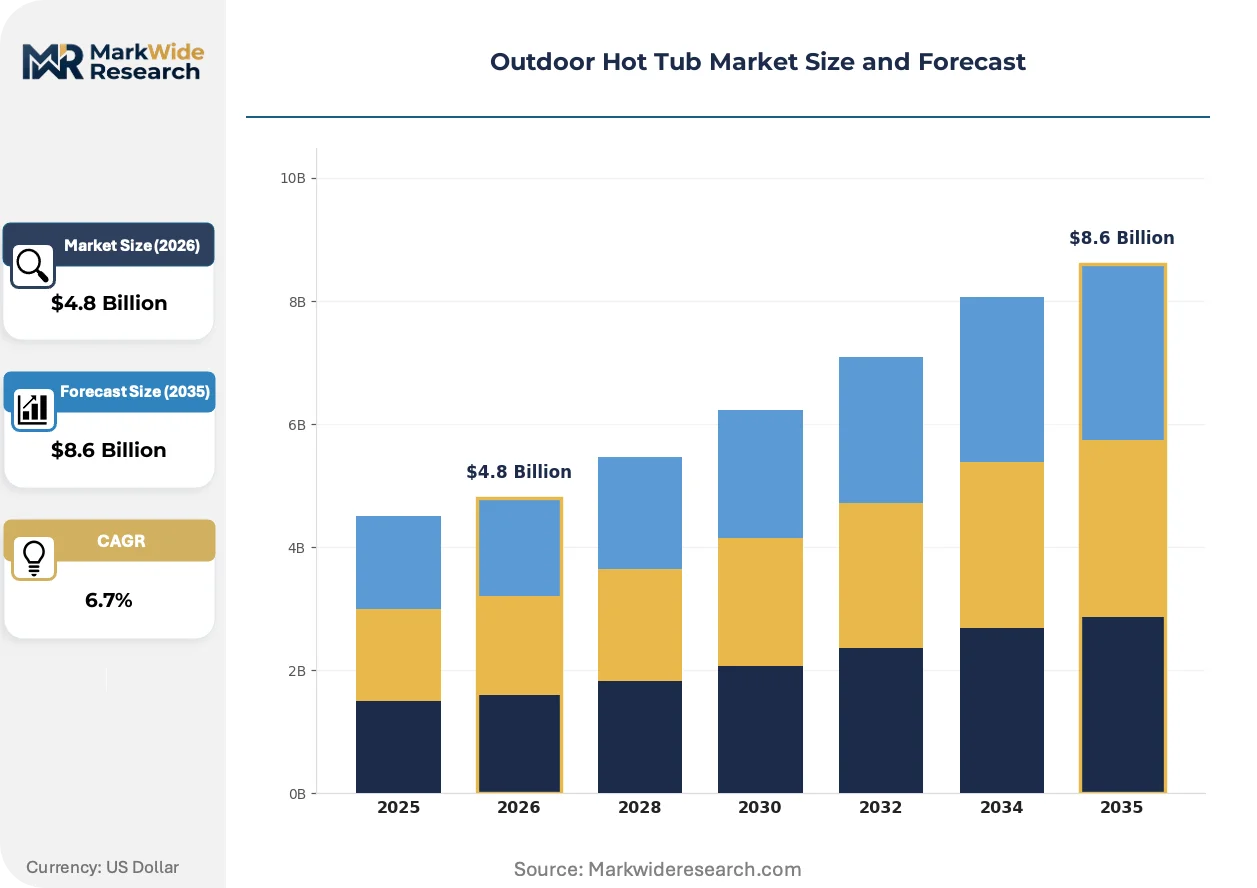
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Hot Tubs, Wooden Hot Tubs, Acrylic Hot Tubs, Portable Hot Tubs Size: 2-Person, 4-Person, 6-Person, 8-Person Material: Fiberglass, Wood, Acrylic, Vinyl Installation Type: Above Ground, In-Ground, Semi-Inground, Portable |
| Companies Covered | Jacuzzi, Sundance Spas, HotSpring, Master Spas, Dimension One Spas, Wellis, Hydropool Hot Tubs, Strong Spas, Aquavia Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Hot Tub Market Evolving Landscape
Product architecture is fragmenting between integrated premium systems and modular component platforms, while regulatory pressure on energy consumption reshapes thermal engineering priorities.
Plug-and-play jet pack systems are modularizing service and upgrade pathways for acrylic shell platforms. Mid-market buyers in Texas and Florida are adopting swappable massage configurations at twice the rate of fixed-jet alternatives. Component standardization is modularizing aftermarket revenue streams while compressing complete-system replacement cycles.
EPA ENERGY STAR certification requirements for portable spas are mandating standby power consumption below 5 watts, forcing redesign of circulation pump and control board architectures. Manufacturers serving California and New York markets are prioritizing variable-speed pump integration to meet tiered efficiency thresholds. Compliance cost concentration is favoring vertically integrated producers with captive electronics assembly.
Subscription-based water chemistry management is displacing traditional chemical retail for connected hot tub owners. Professional service firms in Arizona and Nevada are bundling remote monitoring with quarterly maintenance visits, unbundling the chemical supply relationship from equipment purchase. Channel margin reallocation is pressuring traditional pool-supply distributors to develop proprietary digital platforms.
Outdoor Hot Tub Market Segmentation
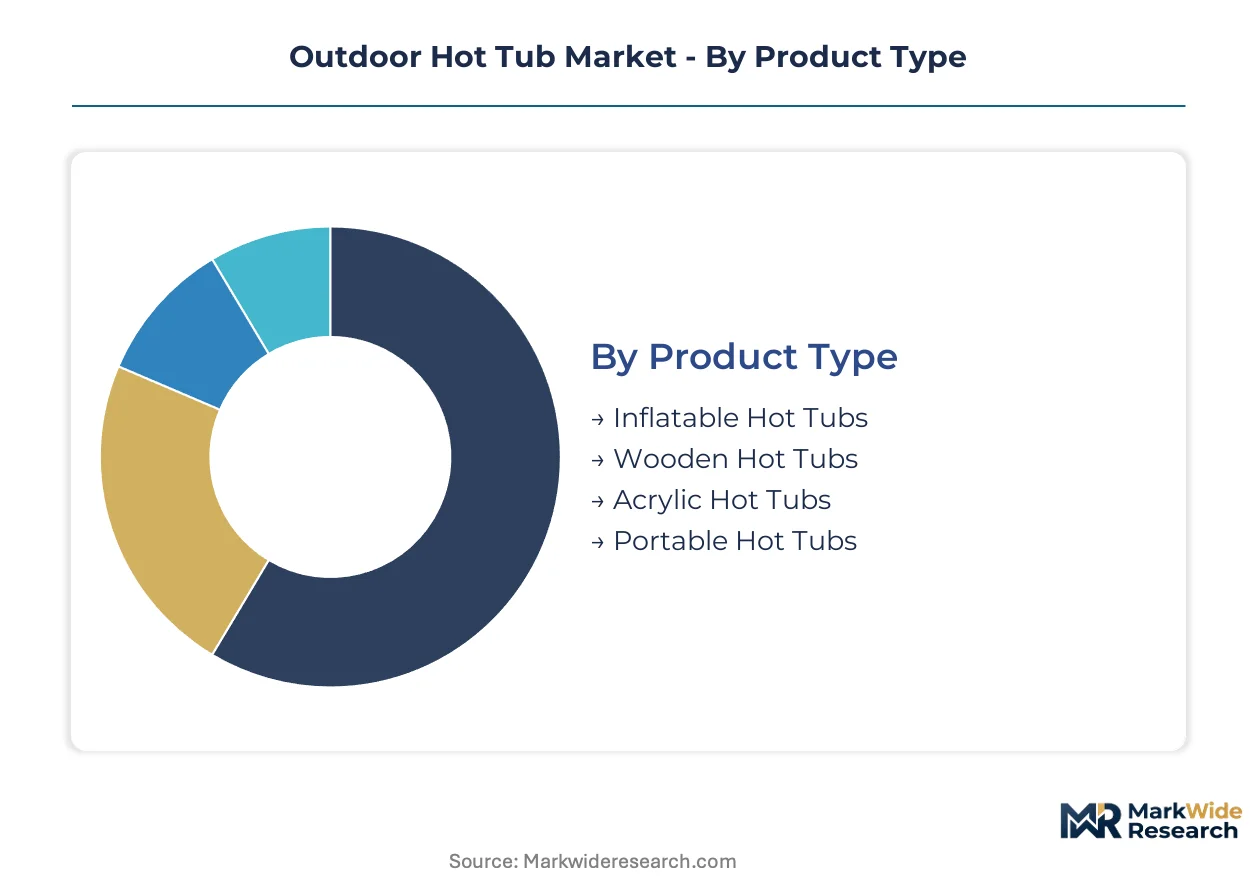
Product architecture in the outdoor hot tub industry fragments across construction method, capacity tier, shell material, and permanence of installation. Each dimension shapes procurement patterns, margin structures, and channel access for manufacturers competing across residential and commercial end-uses.
Product Type:
Buyer differentiation centers on durability expectations versus portability requirements and total cost of ownership.
- Inflatable Hot Tubs:Constructed from reinforced PVC with integrated air chambers and drop-stitch technology for structural rigidity when pressurized. Demand concentrates among first-time buyers in Texas and Florida seeking seasonal use without permanent electrical commitment, though puncture vulnerability and shorter service life constrain replacement-cycle predictability.
- Acrylic Hot Tubs:Vacuum-formed thermoplastic shells bonded to fiberglass backing, supporting integrated jet systems and ergonomic seating contours. Sun Belt resort developers specify these for amenity differentiation in second-home communities, where customization options and ten-year service life justify premium positioning.
- Wooden Hot Tubs:Cedar or redwood stave construction with stainless steel banding and wood-fired or electric heating options. Wellness retreat operators in Colorado and Vermont favor these for rustic aesthetic alignment.
- Portable Hot Tubs:Rotomolded polyethylene shells with plug-and-play electrical requirements. Rental property managers in Arizona and Nevada adopt these for tenant turnover flexibility.
Volume sits with acrylic systems; growth tilts toward inflatable units.
Size:
Capacity selection tracks household composition and entertainment use frequency rather than pure square footage economics.
- 4-Person:The standard residential footprint balancing jet count, water volume, and heating efficiency. Suburban buyers in California and New York prioritize this tier for family use without excessive electrical load.
- 6-Person:Expanded seating with dedicated lounger configurations and increased pump capacity. Hospitality developers in Florida specify these for villa amenities where guest occupancy varies.
- 2-Person:Compact footprint for balcony and small patio installation. Urban condo owners in Seattle and Boston drive specification.
- 8-Person:Maximum capacity with dual pump systems and extended filtration cycles. Commercial wellness centers in Texas select these for group hydrotherapy sessions.
4-Person units dominate transaction volume; 6-Person configurations climb the fastest in hospitality specification.
Material:
Shell composition determines thermal retention, surface longevity, and repair pathway economics across climate zones.
- Acrylic:Non-porous surface with UV-stable color-through construction enabling scratch repair and color consistency. Manufacturers serving EPA ENERGY STAR compliance prioritize this substrate for insulation integration.
- Fiberglass:Gelcoat surface with chopped-strand reinforcement offering lower unit cost and faster production cycles. Budget-conscious buyers in the Midwest accept shorter colorfast warranties.
- Wood:Natural antimicrobial properties and thermal mass buffering, requiring regular sealing maintenance. Eco-tourism operators in the Pacific Northwest specify cedar construction.
- Vinyl:Flexible membrane construction for inflatable and soft-sided portable units. Mass retail channels in the United States move the highest unit volumes through this material tier.
Acrylic commands the value pool; vinyl expands most quickly in direct-to-consumer channels.
Installation Type:
Permanence of placement shapes permitting burden, electrical infrastructure requirements, and property value implications.
- Above Ground:Self-supporting structures with integrated cabinetry and simplified foundation requirements. Residential buyers across Sun Belt states favor this tier for cost containment and relocation flexibility.
- In-Ground:Excavated installation with hardscape integration and custom surround construction. Luxury new-build developers in California and Florida specify these for seamless landscape architecture.
- Semi-Inground:Partial excavation with retained wall construction bridging above-ground accessibility and in-ground aesthetics. Sloped terrain properties in Colorado and Tennessee adopt this compromise.
- Portable:No fixed electrical or plumbing connection, enabling seasonal deployment and storage. RV park operators and vacation rental managers in Arizona rotate these through peak demand periods.
Above-ground installation captures volume concentration; in-ground configurations gain share fastest in luxury residential construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American hot tub distribution with three major dealer distribution centers serving Sun Belt second-home markets.
United States
Texas and Florida drive residential demand through vacation rental property expansion and suburban pool-adjacent installation. EPA ENERGY STAR certification requirements for portable spas mandate standby power below 5 watts, reshaping control board architectures for California and New York compliance. The Phoenix-Mesa corridor concentrates dealer network density for snowbird seasonal migration patterns.
Canada
Alberta and British Columbia sustain demand through cold-climate wellness positioning and mountain resort amenity specification. Health Canada electrical safety standards align with UL certification, streamlining cross-border product launches for manufacturers serving both markets. The Calgary-Edmonton corridor anchors Western Canadian distribution with direct rail links to Vancouver port facilities.
Germany
Baden-Württemberg and Bavaria commercial wellness centers specify energy-certified systems under REACH compliance frameworks. ECHA chemical safety protocols influence water treatment system design for export-oriented producers. The Stuttgart industrial zone concentrates shell manufacturing with captive acrylic forming operations.
United Kingdom
Southeast England and the Cotswolds drive premium residential specification through garden room integration trends. CE marking requirements and post-Brexit UKCA transition timelines compress product registration windows for EU-manufactured units. The Thames Valley corridor hosts hospitality developer procurement offices specifying spa amenities for boutique hotel portfolios.
Australia
New South Wales and Queensland coastal markets sustain demand through outdoor living culture and holiday rental investment. The country's national electrical safety regulator mandates AS/NZS 60335 compliance for immersion heater systems, extending certification timelines for imported equipment. The Gold Coast-Tweed Heads region concentrates tourism property development with integrated spa amenity packages.
Outdoor Hot Tub Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing footprints. Acrylic shell fabricators with captive polymer forming operations hold cost advantages against contract-manufactured alternatives. The market structures around heritage brand equity holders, vertically integrated mid-market specialists, and direct-to-consumer inflatable disruptors. Dominant competitive moves include backward integration into pump and control electronics assembly, plus exclusive dealer territory expansion in underserviced counties.
Within the heritage brand tier, Jacuzzi and Sundance Spas exemplify installed-base loyalty strategies through authorized service network density. Master Spas occupies a position among vertically integrated fabricators with proprietary jet system development. Wellis anchors European market presence through energy-certified product line specialization. These three represent distinct competitive archetypes: brand-equity defensibility, manufacturing control, and regulatory compliance positioning.
| Leading Market Players |
|---|
| Jacuzzi |
| Sundance Spas |
| HotSpring |
| Master Spas |
| Dimension One Spas |
| Wellis |
| Hydropool Hot Tubs |
| Strong Spas |
| Aquavia Spa |
| Others |
Value Network & Pricing Analysis
Sun Belt resort developers and luxury hospitality procurement offices concentrate demand for premium acrylic systems, anchoring value-based pricing around ten-year service life guarantees and energy certification tiers rather than commoditized unit economics.
Pricing Analysis
Value-based pricing anchors on hydrotherapy outcomes and total cost of ownership across climate zones. Three-tier pricing structure across premium, standard, and economy levels separates EPA ENERGY STAR-certified systems with variable-speed pumps from fixed-speed alternatives and entry-level inflatable units. Cost compression in the acrylic shell tier is intensifying because petrochemical feedstock volatility squeezes virgin polymer-dependent manufacturers. Price sensitivity concentrates among first-time buyers in Texas and Florida seeking seasonal inflatable deployment, while hospitality developers in California and Florida exhibit minimal elasticity for certified systems.
Supply Chain Analysis
Domestic-content mandates under the Inflation Reduction Act are reshaping sourcing for heat-pump-equipped models serving U.S. residential replacement cycles. Acrylic shell fabrication concentrates in the United States, Germany, and China, with vacuum-forming operations drawing from petrochemical complexes in the Gulf Coast and Stuttgart industrial zones. Critical inputs span virgin acrylic resin, fiberglass chopped-strand mat, and variable-speed circulation pumps. Single-source vulnerability sits with Asian-sourced control board assemblies. Distribution runs through fragmented independent dealer networks in North America and direct-to-consumer platforms for inflatable tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed electrician and plumbing contractor scarcity in high-growth Sun Belt counties constrains order fulfillment velocity, propping pricing power for vertically integrated installers with captive service capacity.
For Market Incumbents: Extend authorized service network density into underserviced secondary markets before emerging direct-to-consumer inflatable brands capture first-time buyer relationships. Deepen backward integration into pump and control electronics assembly to compress UL recertification timelines for redesigned heating elements. Prioritize heat-pump product line expansion to capture IRA residential efficiency credit eligibility. For New Entrants and Emerging Players: Rural property owners in mountainous regions with 240V infrastructure gaps represent an underserved buyer archetype for plug-and-play portable systems with reduced electrical commitment. Medical wellness positioning through hydrotherapy certification partnerships with physical therapy clinics opens institutional specification channels. E-commerce-first go-to-market angles bypass dealer network concentration barriers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated fabricators with captive acrylic forming operations and proprietary jet system development. Long-term viability hinges on regulatory compliance positioning across EPA ENERGY STAR and REACH frameworks. Watch for heat-pump adoption inflection signals in existing installed base replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Expansion | Captures specification preference in underserviced Sun Belt counties before competitors establish territory. |
| Heat-Pump Product Line Investment | Qualifies systems for IRA residential efficiency credits accelerating replacement demand. |
| Direct-to-Consumer Channel Development | Bypasses fragmented independent retailer constraints for price-sensitive first-time buyers. |
| Medical Wellness Certification Partnership | Opens institutional specification channels with physical therapy clinics previously closed to recreational positioning. |
| Backward Integration into Electronics Assembly | Compresses UL recertification timelines for redesigned heating elements and control architectures. |
Research Methodology
Document review covered regulatory filings with EPA and UL, trade association technical standards, and hospitality development procurement databases, complemented by interviews with hot tub manufacturing executives, independent dealer network operators, resort property developers, and licensed installation contractors. Secondary validation drew from customs records, energy certification registries, and building permit databases. Bottom-up shipment data triangulated against top-down hospitality construction spending.
Cross-referencing historical acrylic resin price volatility against panel input on replacement cycle timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include shell material tier, installation permanence, capacity configuration, and climate-zone energy efficiency requirements. CAGRs derived from installed base growth rates and replacement velocity assumptions. Forecast inputs incorporated EPA ENERGY STAR compliance timelines and REACH chemical safety protocol evolution.
Revisions become necessary when petrochemical feedstock disruptions extend beyond normal volatility bands or when municipal electrical code harmonization accelerates beyond baseline assumptions. Forecasts reflect documented assumptions on contractor labor availability and hospitality construction pipelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Camping Equipment Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Diving Regulator Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Europe Camping Equipment Market