
 Hunting Boots Market | 2026-2036
Hunting Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Hunting Boots Market Foresight
Subscription-based boot care and replacement programs is rebalancing how manufacturers monetize customer relationships beyond the initial purchase. Danner leverages its domestic manufacturing heritage to command premium positioning in specialty retail channels. Wolverine World Wide, Inc. sustains broad distribution scale across mass-market and outdoor specialty tiers. Rocky Brands, Inc. anchors its competitive stance through contracted supply relationships with military and institutional buyers adjacent to the hunting segment.
Hunting boots are purpose-built footwear engineered with waterproof membranes, insulation ratings measured in grams, and outsole compounds optimized for mud, ice, and uneven terrain, serving hunters and outdoor enthusiasts who require thermal protection and traction in variable backcountry conditions. Insulated and waterproof product types capture the dominant share of cold-climate demand where functional performance outweighs style considerations. Gore-Tex and neoprene material segments attract technical buyers seeking vapor permeability combined with chemical resistance, while leather retains loyalty among traditionalists prioritizing durability and repairability over weight savings.
The US Consumer Product Safety Commission and ASTM International set baseline safety and labeling requirements for protective footwear sold in the American market, while REACH compliance governs chemical substance restrictions for boots imported into European Union member states. The EU F-Gas Regulation indirectly shapes insulation supply chains by phasing down hydrofluorocarbon-based blowing agents used in some synthetic thermal materials. Stakeholders must monitor evolving chemical disclosure mandates and thermal performance certification standards as procurement criteria across public lands agencies and guided outfitter operations tighten.
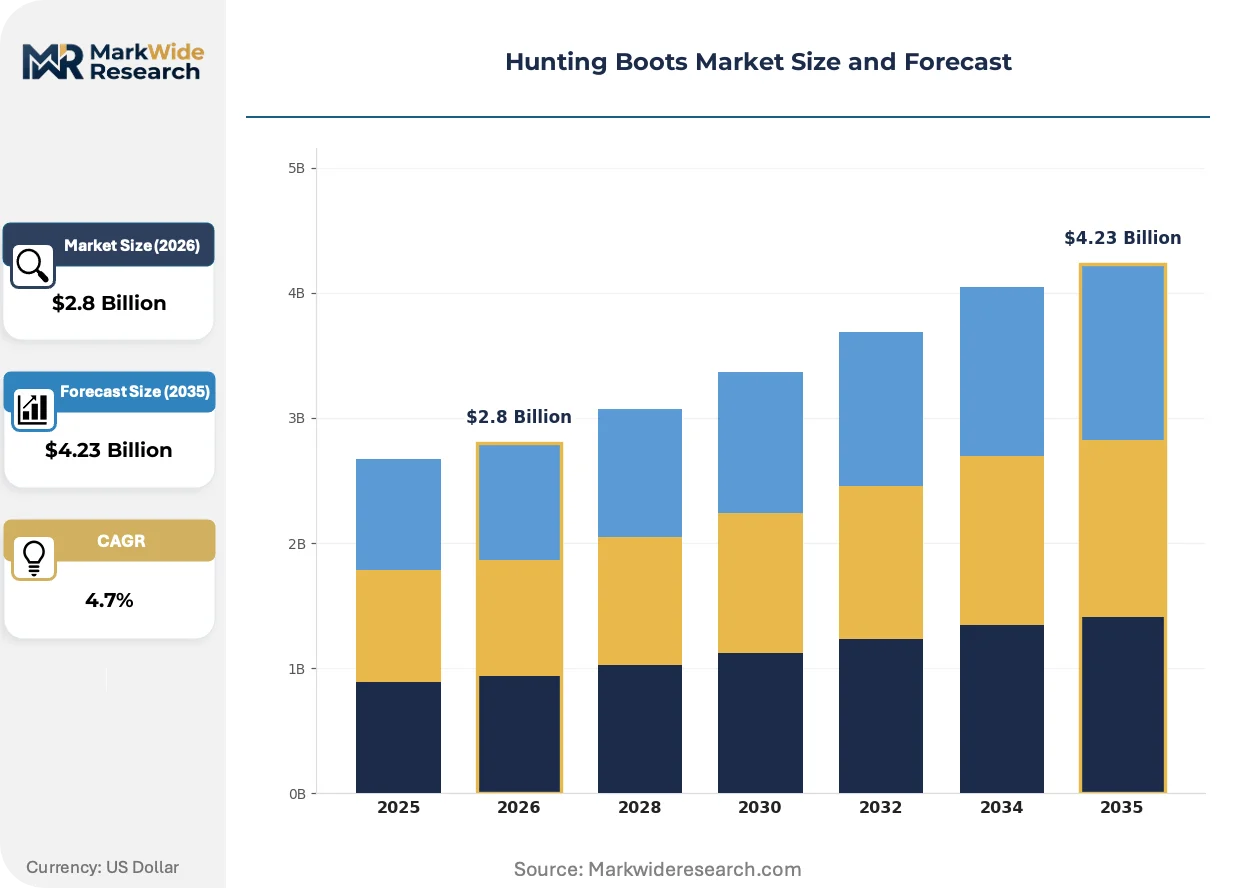
Market Dynamics
Waterproof-breathable membrane technologies are compressing replacement cycles and elevating material specifications across the hunting boots supply chain, forcing manufacturers to reconfigure thermal bonding processes and insulation sourcing strategies.
Growth Catalysts
- Cold-Climate Hunting Traditions:Sustained participation in backcountry hunting across the United States, Canada, and Scandinavia generates predictable premium boot replacement demand tied to seasonal wear patterns.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon-based blowing agents is accelerating adoption of bio-based and recycled synthetic thermal materials in European-sourced insulation layers.
- Neoprene Material Performance:Chemical resistance combined with vapor permeability attracts technical buyers in wetland and marsh hunting applications where submersion tolerance outweighs weight considerations.
Market Restraints
- Petrochemical Input Volatility:Synthetic rubber outsole compounds and petroleum-derived waterproof membranes face cost instability tied to crude oil price fluctuations and refinery capacity constraints.
- Concentrated Membrane Supply:ePTFE and polyurethane laminate production concentrates among specialized chemical processors in Germany and Japan, creating single-source vulnerability for mid-tier manufacturers.
- REACH Compliance Burden:Chemical substance disclosure requirements for boots imported into European Union member states impose testing costs and formulation reformulation timelines that disadvantage smaller suppliers.
Strategic Opportunities
- Subscription-Based Care Programs:Boot replacement and maintenance subscriptions create recurring revenue streams beyond initial purchase, with early adoption concentrated among specialty retailers in the United States.
- ASTM International Certification:Thermal performance standardization for protective footwear opens procurement channels with federal land management agencies and guided outfitter operations requiring documented insulation ratings.
- Digital Fit Customization:3D foot scanning and made-to-measure manufacturing convergence reduces return rates and captures premium price points among backcountry enthusiasts with non-standard sizing needs.
Industry Challenges
- Skilled Pattern-Making Shortage:Domestic boot last design and upper pattern engineering expertise concentrates among aging workforces in traditional manufacturing regions, constraining new product development velocity.
- Multi-Certification Timelines:Simultaneous pursuit of US Consumer Product Safety Commission labeling, ASTM International safety testing, and REACH chemical compliance extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hunting Boots Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated, Waterproof, Lightweight, Rubber End User: Hunters, Outdoor Enthusiasts, Wildlife Photographers, Hikers Material: Nylon, Leather, Neoprene, Gore-Tex Footwear Height: Mid-Cut, High-Cut, Knee-High, Ankle |
| Companies Covered | LaCrosse Footwear, Inc., Irish Setter Boots, Danner, Rocky Brands, Inc., Under Armour, Inc., Wolverine World Wide, Inc., Muck Boot Company, L.L.Bean Inc., Crispi Sport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hunting Boots Market Shifts & Advancements
Automation in bonding and membrane lamination processes is compressing production timelines while elevating consistency benchmarks, reshaping how manufacturers balance domestic assembly against offshore component sourcing.
Automated ultrasonic welding equipment is automating seam sealing in waterproof boot construction, eliminating manual cementing stages. Mid-tier manufacturers in the United States and Portugal are adopting these systems to reduce skilled labor dependency. This technology is automating throughput gains of 40-60% in upper assembly while reducing membrane delamination warranty claims.
The EU F-Gas Regulation phase-down of hydrofluorocarbon blowing agents is forcing insulation suppliers to reformulate thermal layers using CO2-based or water-blown alternatives. Boot manufacturers sourcing from European chemical processors face reformulation validation timelines of 18-24 months. Cold-climate product lines destined for Scandinavian markets are experiencing the most acute supply chain reconfiguration pressure.
Direct-to-consumer resale platforms and peer-to-peer gear exchanges are shortening effective product lifecycles by accelerating secondary market velocity. Specialty hunting retailers in the United States are responding with trade-in programs and certified pre-owned authentication services. This channel displacement is most visible among premium leather boot segments where repairability extends usable life beyond original ownership.
Hunting Boots Market Segmentation
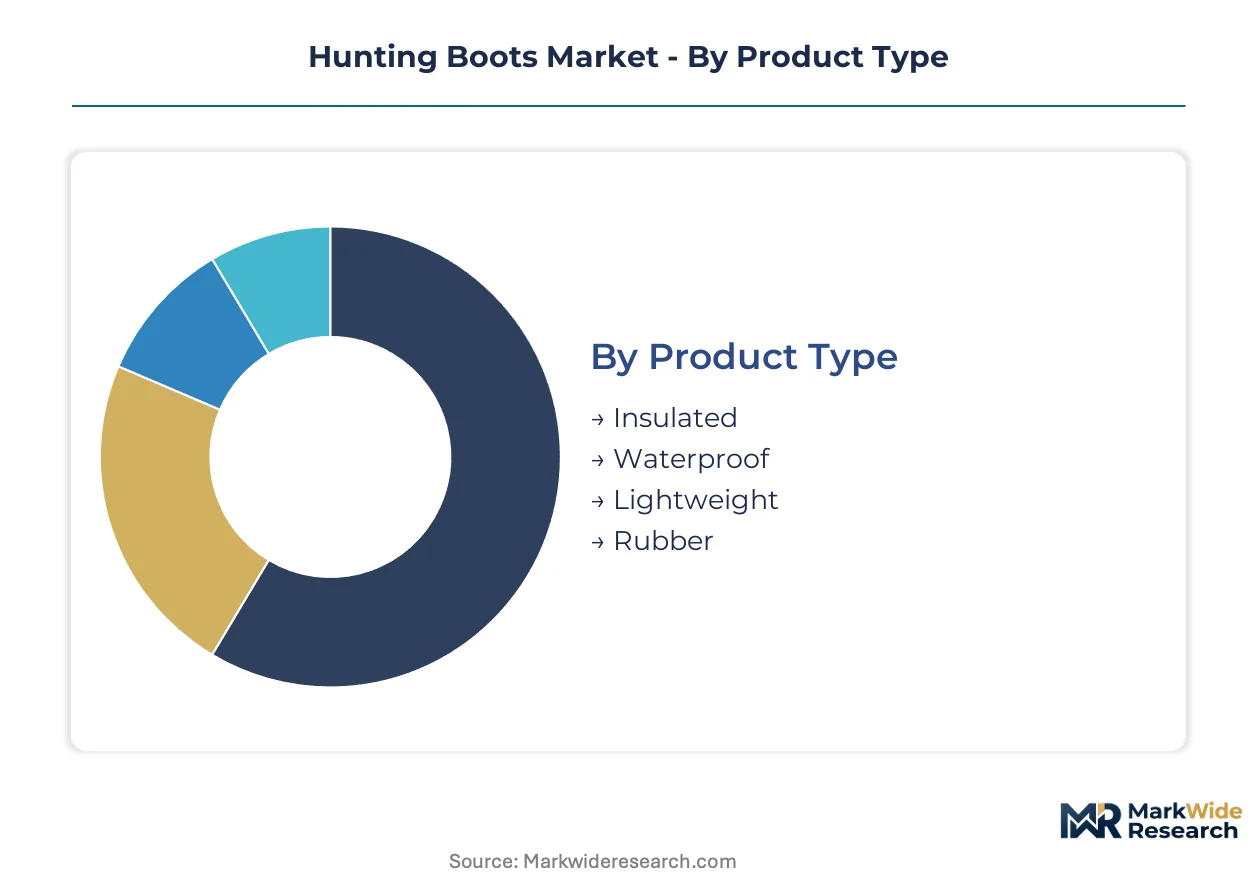
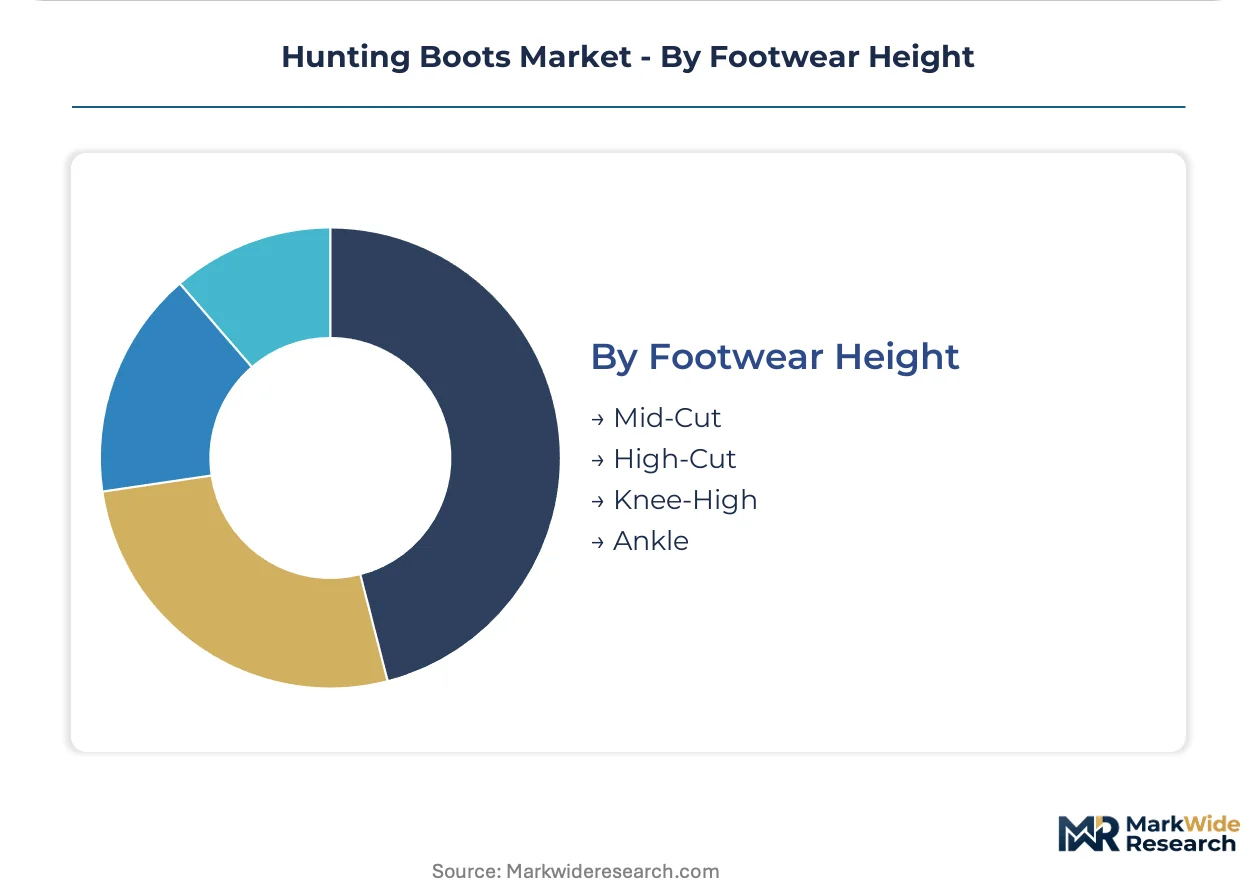
Segmentation in hunting boots reflects divergent performance priorities across climate zones, terrain types, and activity intensity levels. Buyers trade thermal protection against weight, durability against packability, and waterproofing against breathability based on specific backcountry use cases.
Product Type:
Buyers prioritize functional specifications over aesthetics, with thermal ratings and membrane performance driving purchase decisions in cold-climate markets.
- Insulated:Synthetic or down-filled thermal layers rated by gram weight (200g-2000g) trap body heat in sub-zero conditions. Demand concentrates in Minnesota, Wisconsin, and Scandinavian backcountry markets where stationary hunting demands static warmth retention.
- Waterproof:Laminated membrane construction blocks liquid water entry while permitting vapor escape. Wetland hunters in Louisiana bayous and Pacific Northwest rainforest zones drive replacement cycles tied to membrane degradation rather than upper wear.
- Lightweight:Synthetic uppers and EVA midsoles reduce pack weight for mobile hunters covering 10+ miles daily. Trail hunters in mountainous terrain favor these for cardiovascular efficiency over multi-day pack trips.
- Rubber:Molded PVC or neoprene construction delivers complete submersion tolerance for marsh and swamp applications. Mississippi Delta duck hunters and coastal waterfowl guides specify these for waist-deep wading conditions.
Insulated and Waterproof variants dominate unit volume across North American cold-climate regions; Lightweight designs gain share fastest among backcountry fitness-oriented demographics.
End User:
Activity intensity and environmental exposure duration shape boot specification requirements across user categories.
- Hunters:Big-game stalkers, upland bird hunters, and waterfowlers require species-specific traction patterns and scent-control treatments. Whitetail hunters in the Great Lakes states generate predictable seasonal demand spikes tied to firearm and archery season openings.
- Outdoor Enthusiasts:Multi-sport users demand crossover performance for hunting, hiking, and camping applications. This segment tolerates performance compromises in exchange for versatility across activity types.
- Wildlife Photographers:Extended stationary positioning in blinds and hides prioritizes comfort over mobility. Thermal retention and noise-dampening outsoles matter more than aggressive tread geometry.
- Hikers:Recreational trail users entering hunting-adjacent footwear categories seek lighter alternatives to traditional mountaineering boots. Appalachian Trail thru-hikers and regional park systems generate volume in transitional seasons.
Hunters anchor revenue concentration through premium replacement cycles; Outdoor Enthusiasts expand most quickly as category boundaries blur between hunting and general outdoor recreation.
Material:
Supply chain sourcing and repairability expectations divide buyer preferences between traditional and technical material platforms.
- Nylon:Woven synthetic uppers reduce unit weight and manufacturing cost while accepting waterproof coatings. Mass-market retailers favor these for entry-price positioning in seasonal promotional calendars.
- Leather:Full-grain and nubuck constructions offer resoling potential and abrasion resistance measured in decades. Traditionalists in Rocky Mountain elk hunting communities prioritize repairability over initial weight penalties.
- Neoprene:Closed-cell synthetic rubber delivers chemical resistance and thermal insulation in saturated conditions. Waterfowl guides in coastal Texas and Chesapeake Bay specify these for daily submersion tolerance.
- Gore-Tex:ePTFE membrane lamination provides benchmark vapor permeability with guaranteed waterproofing. Technical buyers in backcountry sheep hunting and alpine applications accept price premiums for documented breathability performance.
Leather retains loyalty among durability-focused traditionalists; Gore-Tex commands the steepest expansion trajectory as membrane technology diffuses into mid-tier price points.
Footwear Height:
Ankle support requirements and debris intrusion tolerance determine height selection against terrain roughness.
- Mid-Cut:Shaft heights between 6-8 inches balance ankle stability with calf muscle flexibility. Eastern hardwood hunters traversing rolling terrain favor these for all-day mobility without excessive restriction.
- High-Cut:9-11 inch shafts extend protection through snow, brush, and rocky scree fields. Western big-game hunters in Idaho and Montana specify these for horse-pack compatibility and stream crossing protection.
- Knee-High:Extended shafts seal against deep snow and snake habitat in specific regional applications. Prairie grouse hunters in North Dakota and rattlesnake-country varmint hunters drive niche demand.
- Ankle:Low-profile designs prioritize ground feel and packability for early-season upland bird hunting. Texas quail hunters and driven bird shooting participants in imported European traditions accept minimal protection for mobility gains.
High-Cut dominates cold-climate and mountainous applications by revenue; Mid-Cut expands most quickly as lightweight construction techniques improve support-to-weight ratios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's cold-climate hunting traditions generate steeper per-capita boot replacement rates than the United States, where volume concentration masks lower frequency purchase patterns.
United States
Whitetail hunters across the Great Lakes states drive seasonal demand spikes tied to firearm and archery season openings. OSHA workplace safety standards influence protective footwear labeling for hunting boots sold through agricultural supply channels. Rocky Brands, Inc. anchors manufacturing presence in Nelsonville, Ohio, leveraging proximity to Appalachian hunting corridors.
Canada
Sub-zero backcountry conditions in Manitoba and Saskatchewan sustain premium insulated boot demand through extended winter hunting seasons. Health Canada regulates chemical substance disclosure under the Canada Consumer Product Safety Act for imported footwear. Winnipeg serves as a distribution hub for cold-climate gear serving prairie provinces and northern territories.
Germany
REACH compliance mandates reshape formulation strategies for European-sourced waterproof membranes and synthetic thermal materials. The EU F-Gas Regulation accelerates insulation supplier transitions away from hydrofluorocarbon-based blowing agents. Bavarian chemical processors concentrate ePTFE and polyurethane laminate production for mid-tier boot manufacturers.
Sweden
Scandinavian hunting traditions sustain replacement cycles for knee-high rubber and neoprene constructions in saturated wetland conditions. ECHA chemical substance restrictions govern neoprene and synthetic rubber compounds used in submersion-tolerant footwear. Stockholm-based specialty retailers pioneer subscription-based boot care programs for backcountry enthusiasts.
Japan
Technical buyers in alpine hunting applications prioritize vapor permeability specifications documented under JIS standards for protective footwear. METI industrial policy supports domestic membrane lamination equipment manufacturing to reduce import dependency. Nagoya-area fabricators supply automated ultrasonic welding systems to North American mid-tier boot producers.
Hunting Boots Market Competitive Landscape
Top-tier vendors anchor premium positioning through domestic manufacturing heritage and specialty retail channel control, while mid-tier competitors compete on mass-market distribution scale and contracted institutional supply relationships. The vendor base stratifies across three archetypes: heritage manufacturers with repairable leather constructions, technical specialists leveraging membrane licensing agreements, and diversified footwear conglomerates spanning outdoor and work categories. M&A activity concentrates on membrane technology acquisitions and regional specialty brand consolidation. Geographic expansion into Scandinavian and Japanese markets represents the dominant competitive move alongside portfolio diversification into adjacent outdoor recreation categories.
Within the heritage manufacturer tier, Danner and L.L.Bean Inc. exemplify domestic production positioning that commands price premiums through resoling services and lifetime warranty programs. Wolverine World Wide, Inc. occupies a scale-driven position across mass-market and outdoor specialty tiers, while Rocky Brands, Inc. anchors institutional supply relationships adjacent to core hunting demand. These three represent divergent strategic archetypes: repairability-focused craftsmanship, diversified portfolio breadth, and contracted channel concentration respectively.
| Leading Market Players |
|---|
| LaCrosse Footwear, Inc. |
| Irish Setter Boots |
| Danner |
| Rocky Brands, Inc. |
| Under Armour, Inc. |
| Wolverine World Wide, Inc. |
| Muck Boot Company |
| L.L.Bean Inc. |
| Crispi Sport |
| Others |
Supply & Pricing Matrix
Captive membrane production in Germany and Japan anchors pricing power for tier-one manufacturers while forcing mid-tier competitors into costly licensing arrangements that compress margins. This integration choice separates premium-positioned heritage brands from mass-market players dependent on outsourced ePTFE supply.
Pricing Analysis
Capacity additions in Portugal and the United States are reshaping price floors for mid-tier waterproof boots as automated ultrasonic welding reduces labor-dependent cost structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by membrane certification grade and domestic assembly origin. Cost compression in the standard tier is intensifying because synthetic rubber outsole compounds face petrochemical input volatility. Price-sensitive mass-market buyers at big-box retailers drive volume, while backcountry enthusiasts in Minnesota and Alberta show minimal sensitivity to premium positioning.
Supply Chain Analysis
ePTFE membrane supply rests on German and Japanese specialty chemical producers, with polyurethane laminate production similarly concentrated in Bavarian industrial clusters. Raw material dependencies span synthetic rubber compounds, hydrofluorocarbon-blown thermal insulation, and full-grain leather tanned in domestic facilities. Single-source vulnerability in membrane lamination equipment creates chokepoint exposure for mid-tier manufacturers retooling production lines. Distribution runs through specialty outdoor retailers, agricultural supply cooperatives, and direct-to-consumer platforms serving remote hunting communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hunting boots market functions as a stable compounder where cold-climate hunting traditions in North America and Scandinavia generate predictable replacement cycles resistant to discretionary spending volatility.
For Market Incumbents: Hedge against membrane supply concentration by securing multi-year lamination equipment contracts with Nagoya-area fabricators before order backlogs extend delivery timelines. Diversify insulation sourcing away from hydrofluorocarbon-dependent European suppliers to CO2-blown alternatives validated under ASTM thermal performance standards. Channel control through specialty retail partnerships protects margin position against direct-to-consumer platform displacement. For New Entrants and Emerging Players: Launch via subscription-based boot care programs targeting backcountry enthusiasts in Manitoba and Saskatchewan where seasonal replacement cycles concentrate demand. White-space exists in digital fit customization for non-standard sizing needs among female hunters and younger demographics entering the category. Certified pre-owned authentication services represent the most penetrable go-to-market angle as peer-to-peer gear exchanges accelerate secondary market velocity. For Investors and Strategic Acquirers: Roll-up economics work for regional heritage brands with repairable leather constructions because aging skilled pattern-making workforces in Appalachian manufacturing regions constrain new product development velocity for independent operators. Long-term viability hinges on membrane technology licensing portfolios and domestic assembly positioning that commands specialty retail shelf space. Watch automated bonding equipment adoption rates as the inflection indicator separating scalable mid-tier manufacturers from labor-constrained competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Secures ePTFE supply agreements with German chemical processors for thermal performance documentation. |
| Domestic Manufacturing Footprint | Positions heritage brands for OSHA-influenced procurement channels in agricultural supply cooperatives. |
| Subscription Care Program Launch | Captures recurring revenue from backcountry enthusiasts in Minnesota and Wisconsin replacement cycles. |
| Automated Ultrasonic Welding Adoption | Reduces skilled labor dependency while compressing membrane delamination warranty claims by 40-60%. |
| Certified Pre-Owned Authentication | Defends specialty retailer positioning against direct-to-consumer resale platform channel displacement. |
Research Methodology
Bottom-up hunter segmentation modeling reconciled against top-down membrane supply tracking forms the analytical core of this study. Primary interviews with product development directors at heritage manufacturers, procurement leads at specialty outdoor retailers, and maintenance supervisors at guided outfitter operations combined with secondary validation from customs records, SEC footwear segment filings, and ASTM certification registries. Trade data from U.S. Customs and Border Protection, outdoor industry association shipment reports, and REACH chemical disclosure filings triangulate supply-side concentration metrics.
Historical trendline analysis across replacement cycle frequencies, seasonal demand spikes tied to state-level hunting season openings, and membrane technology diffusion patterns informed projection frameworks. Segmentation dimensions modeled include product type insulation ratings, end-use activity intensity, material repairability expectations, and footwear height specifications against terrain roughness. CAGRs derived from regression analysis of premium versus mass-market price tier trajectories, with inputs from EU F-Gas Regulation compliance timelines and skilled workforce demographic data.
Several conditions sit outside the modeled scope, including abrupt petrochemical price shocks, trade policy shifts affecting membrane equipment imports, and pandemic-era disruptions to seasonal hunting participation patterns. Forecasts reflect stated assumptions about steady cold-climate tradition continuity and membrane technology licensing fee structures. A small set of named triggers warrants ongoing watch: REACH chemical disclosure expansion, hydrofluorocarbon phase-down acceleration, and domestic pattern-making workforce retirement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Global Automatic Mower Market