
 Wedge Boots Market | 2026-2036
Wedge Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Wedge Boots Market Analytics
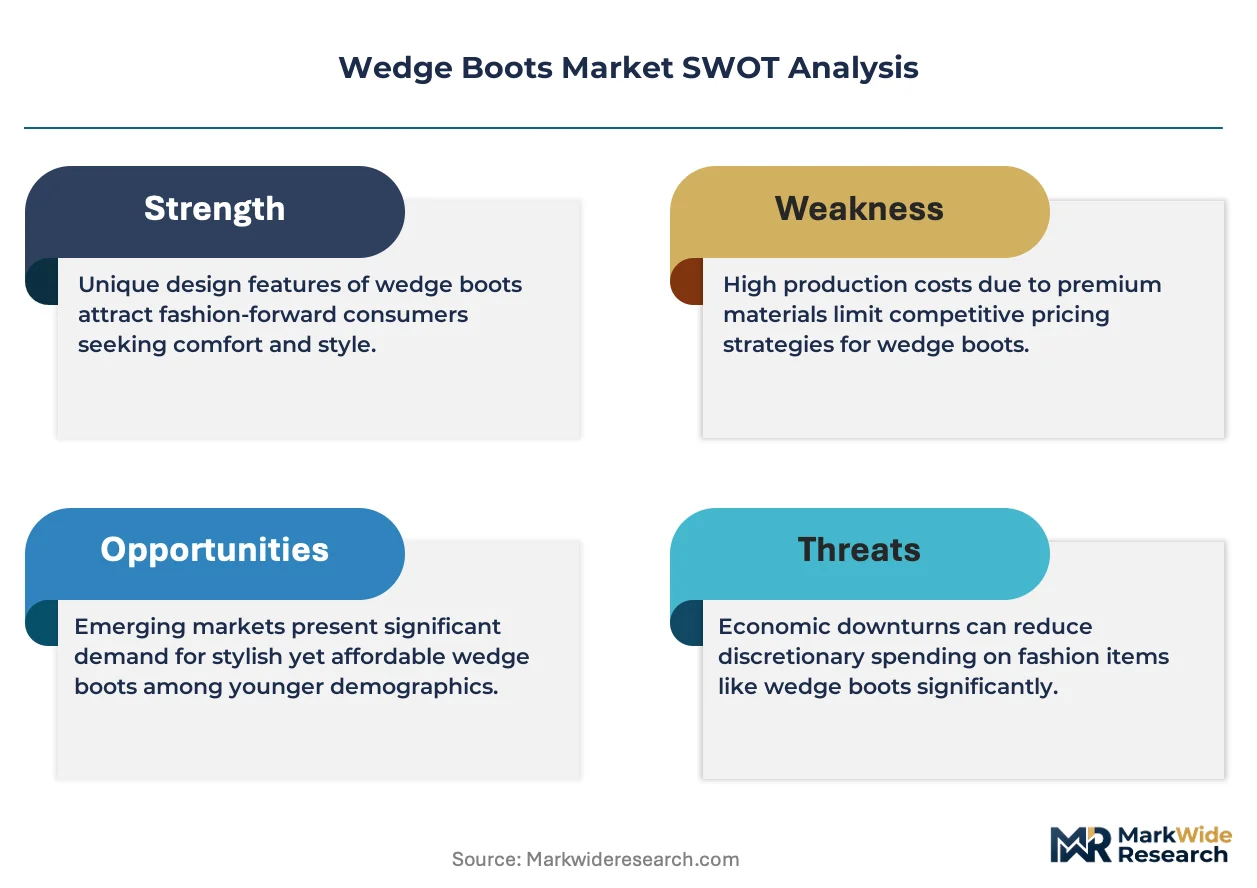
Aftermarket service revenue is fragmenting across repair, resoling, and customization channels as consumers extend product lifecycles. VF Corporation leverages its multi-brand architecture to control shelf space across premium and mid-tier retail formats. Wolverine World Wide, Inc. anchors its position through captive leather tanning operations and work-boot manufacturing expertise that transfers into wedge construction. COFRA S.r.l. specializes in safety-rated wedge soles that meet European occupational standards, differentiating it from fashion-only competitors.
Wedge boots are footwear constructed with a solid sole unit where the heel and forefoot form one continuous piece, typically elevating the wearer by 3 to 8 centimeters while distributing weight more evenly than stiletto alternatives. Manufacturers bond the wedge to the upper using cemented construction or injection molding, with TPU and EVA compounds providing flex resistance and shock absorption for extended wear. The women's segment leads absolute volume, though unisex styling is gaining shelf space as gender-fluid fashion lines expand distribution. Leather and suede materials command margin premiums in the premium price tier, while synthetic alternatives dominate budget and discount channels where unit economics favor polyurethane and microfiber compositions.
REACH restricts phthalates and heavy metals in European-sourced synthetics, compelling suppliers to reformulate compounds or source from certified tanneries. The US Consumer Product Safety Commission monitors lead content in children's wedge boots, creating compliance thresholds that exclude low-cost uncertified imports. ASTM International standards for slip resistance influence procurement specifications among industrial and healthcare buyers. Stakeholders must monitor material certification costs and regional enforcement intensity when allocating production capacity across supply nodes.
Market Dynamics
REACH compliance across the European Union is forcing reformulation of synthetic uppers and rubber outsoles, compelling manufacturers to requalify supply chains while premium leather alternatives capture displaced volume.
Growth Catalysts
- REACH chemical restrictions:Phased constraints on phthalates and heavy metals in European-sourced synthetics are accelerating certified tannery partnerships and margin capture by leather suppliers.
- Urban professional wardrobes:United States office-to-street styling norms sustain replacement cycles for heeled alternatives that distribute weight across continuous sole construction.
- TPU-EVA compounding advances:Injection molding improvements in flex resistance and shock absorption are extending wear-time ratings and justifying price premiums in mid-tier retail formats.
Market Restraints
- Petrochemical input volatility:Polyurethane and microfiber feedstock costs fluctuate with crude derivatives, compressing unit economics in budget channels where synthetic dominance is locked.
- Certified tannery concentration:REACH-compliant leather sourcing clusters in Northern Italy and select German facilities, creating single-point vulnerability for European production nodes.
- Stiletto substitution persistence:Formal occasion footwear retains preference in high-elevation segments where wedge silhouettes read as casual, limiting addressable occasion expansion.
Strategic Opportunities
- Gender-fluid fashion lines:Unisex styling expansion creates shelf space in previously segmented retail formats, capturing cross-demographic trial among younger consumer cohorts.
- Aftermarket service unbundling:Repair, resoling, and customization channels fragment as consumers extend product lifecycles, opening recurring revenue streams beyond initial purchase.
- ASTM slip-resistance procurement:Industrial and healthcare buyer specifications for safety-rated wedge soles create certified product tiers that command specification-driven premiums.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous REACH, US Consumer Product Safety Commission lead-content, and ASTM compliance requirements delay new product introductions by 8-14 months.
- Legacy cemented construction retooling:Shift toward injection molding demands capital redeployment in mold fabrication and technician retraining, straining mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wedge Boots Market |
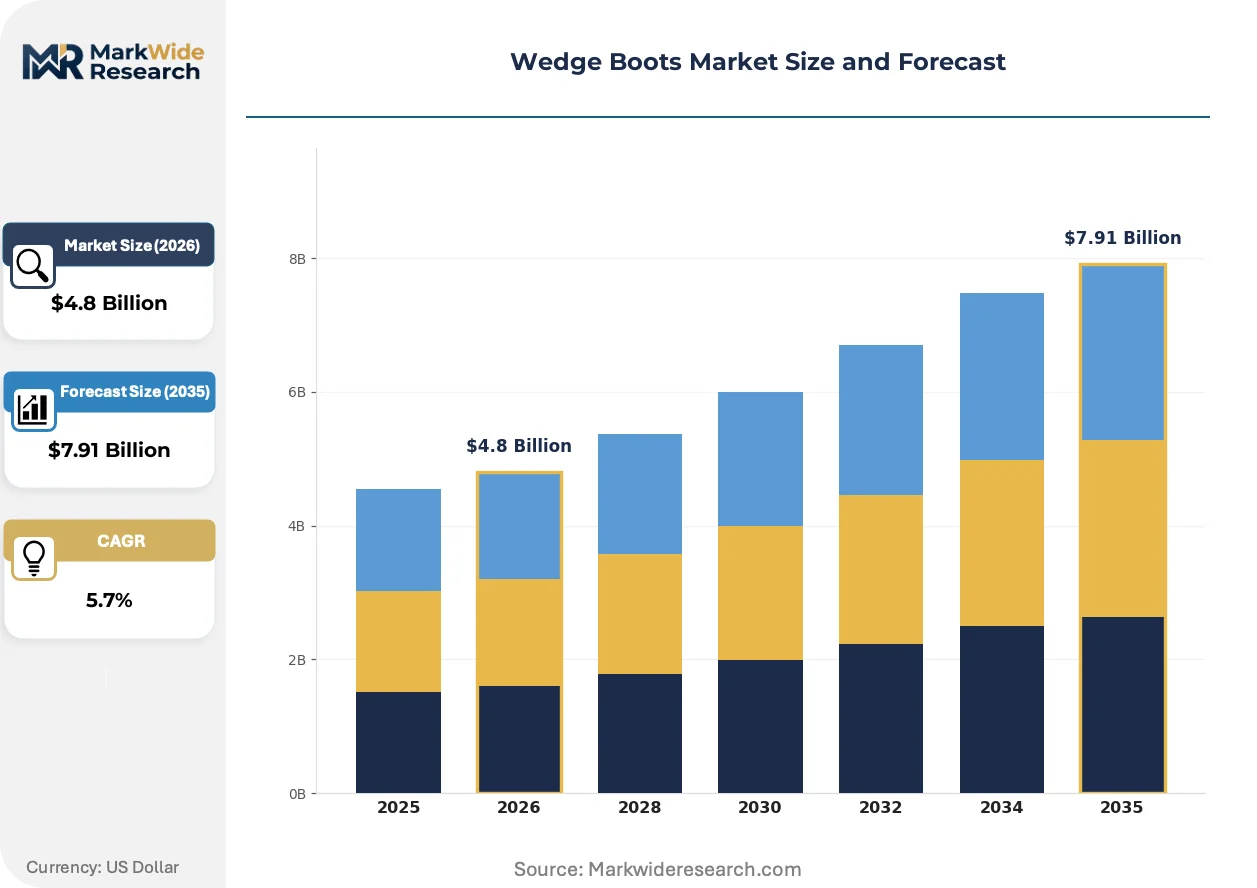
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ankle Boots, Knee-High Boots, Platform Wedges, Open-Toe Wedges Material: Leather, Suede, Synthetic, Canvas End User: Women, Men, Children, Unisex Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Dunlop Boots, COFRA S.r.l., Honeywell International, Inc., Hewats Edinburgh, Rahman Group, Rock Fall Ltd., Uvex Group, VF Corporation, Wolverine World Wide, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wedge Boots Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to redefine acceptable construction methods, while demand-side behavioral shifts reward transparency and lifecycle accountability.
Biobased polyurethane formulations derived from castor oil and agricultural waste streams are rendering obsolete petroleum-dependent microfiber uppers in European premium positioning. German and Dutch retailers are accelerating shelf placement of certified biobased products. This transition compresses synthetic suppliers lacking fermentation-derived alternatives into commodity pricing tiers.
REACH Annex XVII restrictions on persistent organic pollutants intensify enforcement through 2027, compelling compounders to document full material passports or forfeit EU market access. Italian manufacturers with captive tanning operations absorb compliance costs more efficiently than import-dependent competitors. Safety-rated occupational segments face the steepest requalification burdens as work-boot standards layer atop fashion chemistry rules.
Resale platform integration into primary retail is fragmenting traditional seasonal purchasing patterns as authenticated pre-owned wedge boots capture value-conscious urban professionals. United States metropolitan markets show the strongest platform adoption, with New York and Los Angeles inventory turnover rates exceeding conventional off-price channels. Brand-controlled refurbishment programs now compete with independent repair networks for aftermarket service revenue.
Wedge Boots Market Segmentation
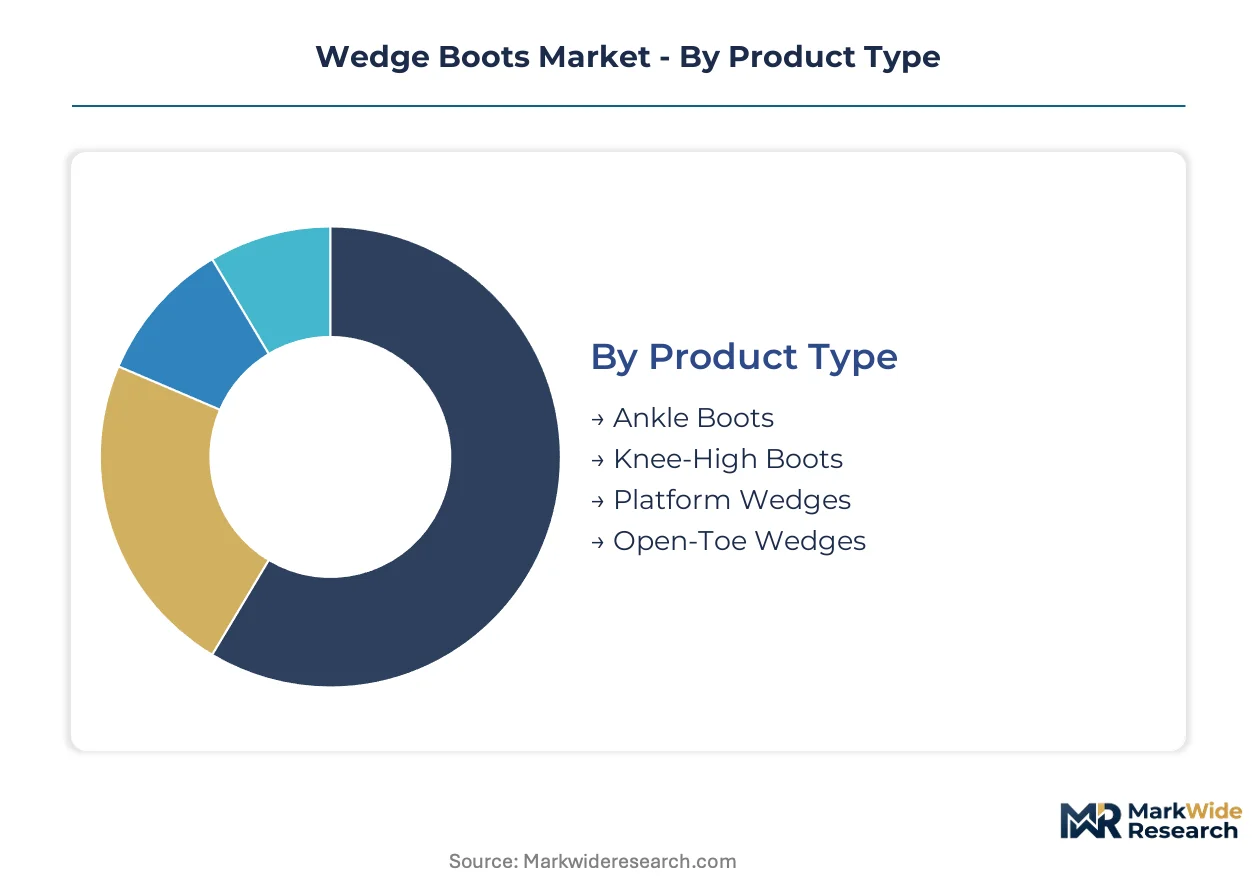
Wedge boot segmentation reveals how construction methods, material chemistry, and end-use occasions fragment demand across distinct purchasing contexts. Each dimension carries regulatory and margin implications that reshape competitive positioning.
Product Type:
Silhouette length and toe configuration determine weight distribution engineering and seasonal purchasing cycles.
- Ankle Boots:Shaft heights below 15 centimeters dominate office-to-street styling in United States metropolitan markets. Cemented construction with TPU midsoles sustains replacement cycles among urban professionals seeking elevation without instability.
- Knee-High Boots:Extended shaft construction demands reinforced quarter panels and specialized lasting techniques. Italian manufacturers with captive tanning operations capture margin premiums through certified leather sourcing that satisfies REACH Annex XVII requirements.
- Platform Wedges:Forefoot elevation above 3 centimeters requires density-graded EVA compounds for balanced flex.
- Open-Toe Wedges:Seasonal exposure to moisture necessitates antimicrobial lining treatments and drainage-channel outsole design.
Ankle boots command the established base. The steepest expansion runs through knee-high silhouettes as formal occasion styling absorbs wedge alternatives.
Material:
Feedstock origin and certification status separate premium positioning from commodity pricing tiers.
- Leather:Full-grain hides from REACH-certified tanneries in Northern Italy and Germany absorb compliance costs more efficiently than import-dependent competitors. Biobased tanning agents derived from agricultural waste streams are displacing chromium alternatives in Dutch and German retail placement.
- Synthetic:Polyurethane and microfiber compositions face petrochemical volatility that compresses unit economics in budget channels. Phthalate restrictions under REACH are forcing compound reformulation or forfeiture of EU market access.
- Suede:Napped surface treatment requires specialized finishing equipment concentrated in select Italian facilities.
- Canvas:Woven cotton uppers serve seasonal fashion cycles with lower capital intensity.
Leather retains the revenue concentration. Synthetic alternatives are gaining share fastest where certified biobased formulations penetrate premium positioning.
End User:
Demographic targeting shapes last design, sizing granularity, and safety certification requirements.
- Women:Absolute volume concentration with sizing runs from 35 to 42 EU and width variations that demand specialized mold libraries. United States retail cycles sustain consistent replacement demand across professional and casual occasion segments.
- Unisex:Gender-fluid styling expansion captures cross-demographic trial among younger cohorts in New York and Los Angeles metropolitan markets. Simplified SKU architecture reduces inventory carrying costs for mid-tier retailers.
- Men:Occupational safety ratings under ASTM standards drive specification-driven procurement in industrial segments.
- Children:US Consumer Product Safety Commission lead-content monitoring creates compliance thresholds that exclude uncertified imports.
Women's styling commands the established base. The steepest expansion runs through unisex lines as gender-fluid fashion disrupts traditional shelf segmentation.
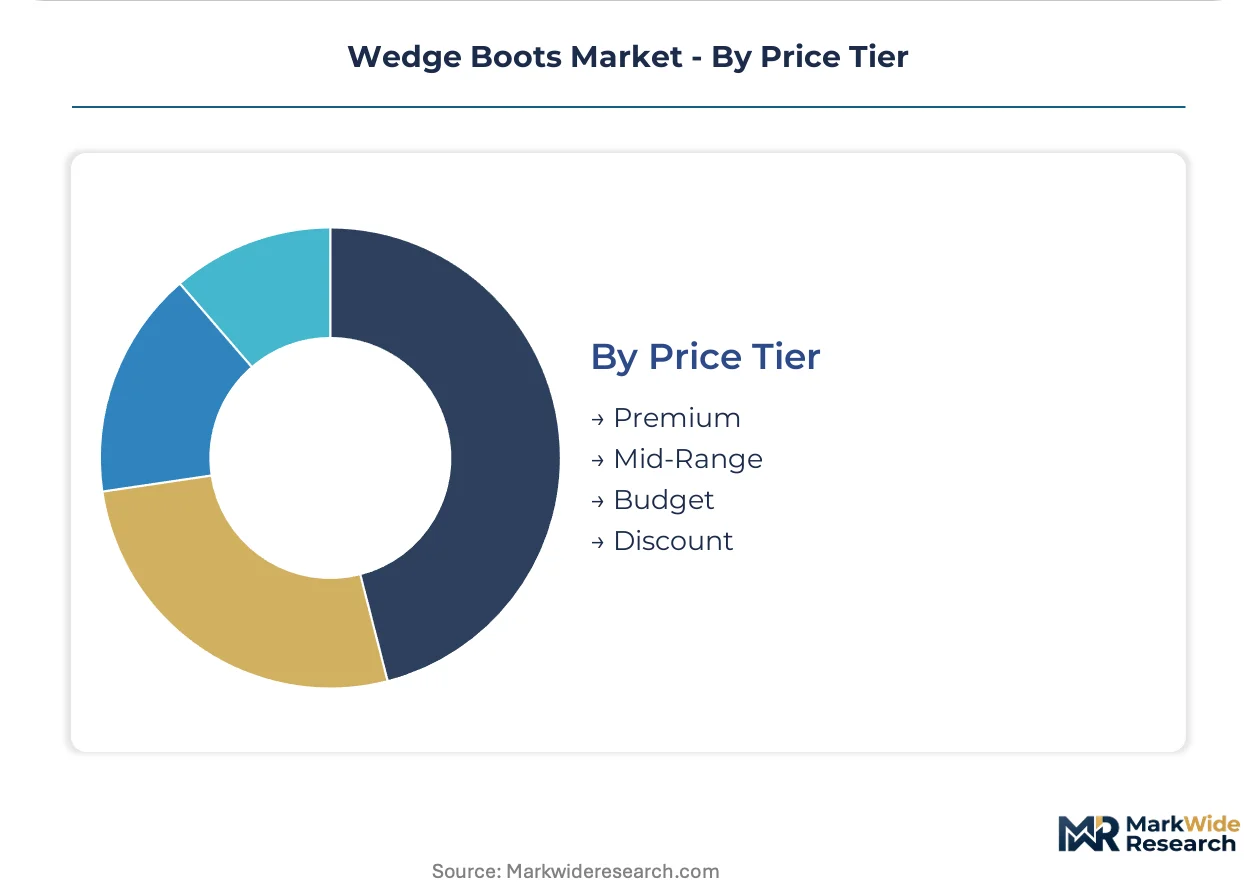
Price Tier:
Margin architecture separates certification-grade construction from disposable fashion economics.
- Premium:Full-grain leather uppers, biobased polyurethane alternatives, and certified tannery documentation justify price positioning above mass-market ceilings. German and Dutch retailers accelerate shelf placement of material-passport-compliant products.
- Mid-Range:TPU-EVA compounding advances in injection molding extend wear-time ratings and justify price premiums through technical specification rather than brand equity alone.
- Budget:Synthetic dominance locks unit economics to petrochemical feedstock volatility.
- Discount:Minimal quality assurance and uncertified imports face exclusion from regulated markets.
Premium tiers command the established base. The steepest expansion runs through mid-range positioning as technical performance claims displace pure brand premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive tanning operations in Northern Italy and certified compounders in Germany concentrate premium-grade supply. United States retail cycles sustain replacement demand through office-to-street styling norms. Chinese injection molding capacity serves mid-tier volume requirements with compressed lead times.
United States
Urban professional wardrobes in New York and Los Angeles drive consistent replacement cycles for ankle-height silhouettes. The US Consumer Product Safety Commission monitors lead content in children's footwear, excluding uncertified imports from mass-market distribution. Metropolitan platform adoption for authenticated pre-owned inventory exceeds conventional off-price channel turnover in both coastal cities.
Germany
Biobased polyurethane formulations from agricultural waste streams accelerate shelf placement in Dutch and German premium retail. ECHA enforcement of REACH Annex XVII restrictions intensifies through 2027, demanding full material passports for EU market access. Captive tanning clusters in Baden-Württemberg absorb compliance costs more efficiently than import-dependent competitors.
Italy
Knee-high formal occasion styling absorbs wedge alternatives from stiletto substitution, particularly in Milan and Florence fashion procurement. REACH-certified tannery documentation requirements favor Northern Italian manufacturers with backward integration into hide processing. Lombardy-based finishing facilities command margin premiums through specialized quarter-panel reinforcement techniques.
United Kingdom
Gender-fluid fashion lines capture cross-demographic trial among younger cohorts in London metropolitan markets. Post-Brexit regulatory divergence from EU chemical standards creates parallel certification burdens for synthetics suppliers. British mid-tier retailers simplify SKU architecture to reduce inventory carrying costs for unisex styling expansion.
China
Injection molding capacity for TPU-EVA compounds serves global mid-tier volume requirements with scale economics. MIIT standards for footwear manufacturing quality create baseline export thresholds that filter substandard production. Pearl River Delta mold fabrication clusters retool for density-graded compound specifications demanded by safety-rated occupational segments.
Wedge Boots Market Competitive Landscape
Multi-brand conglomerates and specialized safety-rated fabricators split the market across fashion and occupational end-uses. Consolidation pressure concentrates premium-tier shelf space among vertically integrated leather processors while mid-tier injection molders compete on technical specification claims. Three archetypes dominate: diversified apparel conglomerates with captive footwear divisions, European safety specialists with ASTM certification capabilities, and Asian volume manufacturers serving private-label programs. Competitive moves center on certified tannery partnerships and mold-fabrication capacity expansion for injection-molded construction.
Within the safety-specialist tier, COFRA S.r.l. and Uvex Group exemplify European occupational certification expertise. VF Corporation and Wolverine World Wide, Inc. occupy positions among diversified footwear conglomerates with multi-brand architecture. These named entities represent strategic archetypes rather than exhaustive market coverage, with each anchoring distinct competitive vectors across premium fashion, safety-rated industrial, and mid-tier volume positioning.
| Leading Market Players |
|---|
| Dunlop Boots |
| COFRA S.r.l. |
| Honeywell International, Inc. |
| Hewats Edinburgh |
| Rahman Group |
| Rock Fall Ltd. |
| Uvex Group |
| VF Corporation |
| Wolverine World Wide, Inc. |
| Others |
Value Network & Pricing Analysis
Pearl River Delta mold fabrication clusters anchor mid-tier injection capacity, translating density-graded TPU-EVA compound specifications into price-competitive positioning that undercuts Italian cemented construction by 30-40 percent at comparable wear ratings. This geographic concentration compresses margin capture for European manufacturers while creating procurement leverage for volume buyers negotiating long-term offtake agreements.
Pricing Analysis
Aftermarket service revenue from resoling, repair, and customization channels extends lifetime value beyond initial purchase, creating recurring income streams that offset margin erosion in first-sale transactions. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified leather constructions from injection-molded synthetics and uncertified imports. Pricing pressure stems from petrochemical feedstock volatility in polyurethane and microfiber compounds, squeezing unit economics in budget channels where synthetic dominance locks cost structures. Budget-tier buyers exhibit highest price sensitivity, while premium segments prioritize certified tannery documentation and biobased material passports over absolute cost.
Supply Chain Analysis
Petrochemical derivatives for polyurethane and microfiber uppers draw from crude-linked feedstock markets, tethering synthetic pricing to energy commodity cycles. Supply clusters concentrate in China for injection molding, Northern Italy for captive tanning operations, and Germany for REACH-certified compound formulation. Raw material dependencies span castor oil for biobased alternatives, chromium salts for conventional tanning, and TPU-EVA pellets for midsole construction. Single-source vulnerability concentrates in Baden-Württemberg tanning facilities serving EU compliance requirements. Distribution runs through multi-brand conglomerate shelf-space control, direct-to-consumer platform integration, and authenticated pre-owned resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among multi-brand conglomerates and platform-integrated retailers, fragmenting pricing leverage previously held by vertically integrated manufacturers. This shift demands defensive repositioning across stakeholder archetypes.
For Market Incumbents: Insulate margin capture through backward integration into captive tanning operations or certified compound partnerships that absorb REACH compliance costs more efficiently than import-dependent competitors. Defend shelf-space positioning by accelerating ASTM safety-rated product tiers that command specification-driven premiums in industrial and healthcare procurement. Counter stiletto substitution persistence with formal occasion styling investments in knee-high silhouettes that displace heeled alternatives.
For New Entrants and Emerging Players: Build out gender-fluid unisex lines that simplify SKU architecture and reduce inventory carrying costs for mid-tier retailers seeking cross-demographic trial among younger cohorts. Target authenticated pre-owned platform integration as a white-space channel where refurbishment expertise creates recurring revenue streams beyond conventional retail. Penetrate through biobased polyurethane positioning that captures Dutch and German premium retail shelf placement ahead of petroleum-dependent competitors.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because REACH Annex XVII enforcement intensification through 2027 will displace uncertified suppliers and concentrate margin capture among documented tannery operators. Acquisition target archetypes include Italian manufacturers with backward-integrated hide processing and German compounders with fermentation-derived biobased alternatives. Signal to watch: ECHA material passport documentation requirements triggering forced exits among import-dependent competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tanning Operation Acquisition | REACH-certified documentation absorbs compliance costs that exclude import-dependent rivals from EU market access. |
| Biobased Polyurethane Formulation Launch | Dutch and German retailers accelerate shelf placement of castor-oil-derived alternatives displacing petroleum synthetics. |
| ASTM Safety-Rated Product Tier Introduction | Industrial and healthcare procurement specifications command premiums unavailable to fashion-only competitors. |
| Authenticated Pre-Owned Platform Integration | New York and Los Angeles metropolitan inventory turnover exceeds conventional off-price channel velocity. |
| Gender-Fluid Unisex Line Expansion | Simplified SKU architecture reduces inventory carrying costs while capturing cross-demographic trial in London and Los Angeles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with footwear brand managers, category buyers at multi-brand retailers, captive tanning operation directors, injection molding facility engineers, and aftermarket service network operators. Secondary validation drew from customs and trade data, ECHA REACH enforcement disclosures, SEC 10-K filings from publicly traded footwear conglomerates, and ASTM International standards documentation. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to ensure cross-verified outputs.
Calibration against historical volume trajectories and material cost indices informed projections across the analysis window. Segmentation dimensions modeled encompassed silhouette length, material chemistry certification status, end-user demographic targeting, and price tier positioning. CAGRs were derived through regression analysis of replacement cycle frequencies, retail inventory turnover rates, and regulatory phase-in timelines. Forecast inputs incorporated petrochemical price volatility assumptions and REACH enforcement intensity scenarios specific to synthetic compound sourcing.
Stress conditions across crude derivative fluctuations, ECHA audit frequency, and tariff exposure on Chinese injection-molded components were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding urban professional wardrobe evolution and platform adoption rates for authenticated pre-owned inventory. Cross-checking against IHS Markit footwear production data and Circana retail audit benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Western Boots Market
Footwear
Leather Footwear Market
Footwear
Second Hand Designer Shoes Market
Footwear
Light Up Shoes Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Desert Boots Market
Footwear
Training Shoes Market
Footwear
PVC Footwear Market
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Sports Shoes Market
Footwear
Athletic Footwear Market
Footwear
Sneakers Market
Footwear
Shoe Rental Service Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Global Footwear Market