
 Asia Pacific Footwear Market | 2026-2036
Asia Pacific Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Footwear Market Analysis
The sports enthusiast segment is hardening as the dominant end-use vertical across Asia Pacific, displacing traditional casual consumption patterns. Nike Inc leverages its athlete endorsement architecture to sustain premium positioning in China and Southeast Asia. ASICS Corporation anchors technical running specialization through Japan-centric R&D pipelines that extend into regional markets. Skechers USA Inc competes on accessible price points while controlling broad retail distribution networks.
Footwear comprises wearable apparel designed for foot protection, locomotion support, and aesthetic expression, typically constructed from leather, synthetic polymers, textile weaves, or rubber compounds through injection molding, vulcanization, or cemented construction processes. Sneakers command the largest volume share within product type segmentation, though formal shoes retain concentrated margin pools in urban professional corridors. Synthetic materials are displacing leather in mid-market tiers due to cost scalability and performance customization, while textile innovations are gaining traction in sustainability-positioned lines.
China's SAMR enforces GB standards for chemical content in synthetic materials, while India's BIS mandates quality certification for domestic and imported footwear. Japan's METI oversees JIS-aligned product safety protocols that shape export eligibility for regional manufacturers. Stakeholders must monitor evolving material restrictions and e-commerce compliance frameworks as online retail channels expand their share of regional distribution.
Market Dynamics
Synthetic material substitution is compressing leather's traditional dominance across mid-market tiers while China's SAMR enforces stricter GB chemical standards and India's BIS certification tightens import compliance.
Growth Catalysts
- Sports Enthusiast Demand:Fitness culture penetration across Southeast Asian urban centers is pulling technical performance footwear into daily rotation beyond competitive use.
- GB Standards Enforcement:China's SAMR mandates on synthetic material chemical content are accelerating certified supplier consolidation and quality-tier differentiation.
- Tier-Two Urban Expansion:India's secondary cities are emerging as volume concentration points as organized retail and e-commerce logistics extend beyond Mumbai and Delhi corridors.
Market Restraints
- Petrochemical Input Volatility:Synthetic polymer feedstock costs tied to crude oil fluctuations are squeezing margin predictability for mid-market producers.
- Vietnam Manufacturing Concentration:Over-reliance on Ho Chi Minh City and Hanoi corridor facilities creates single-point vulnerability for regional supply continuity.
- Leather Substitution Ceiling:Premium formal segments in Japan and South Korea maintain material fidelity requirements that block full synthetic migration.
Strategic Opportunities
- Indonesia's Underpenetrated Archipelago:Logistics infrastructure gaps in secondary islands present first-mover advantage for direct-to-consumer digital-native brands.
- PLI Scheme Alignment:India's production-linked incentive frameworks for manufacturing offer cost-offset pathways for domestic capacity expansion.
- Textile-Rubber Convergence:Knitted uppers fused with injection-molded soles are enabling single-factory production models that compress lead times.
Industry Challenges
- Multi-Jurisdiction Certification Lag:Simultaneous BIS, GB, and JIS compliance timelines extend product launch windows by 8-14 months for cross-border portfolios.
- Specialized Footwear Engineering Talent:Biomechanics and materials science expertise pools concentrate in Japan and South Korea, creating recruitment friction for Southeast Asian facilities.
- Legacy ERP Integration:Established manufacturers face system architecture constraints when embedding traceability requirements for ESG reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Footwear Market |
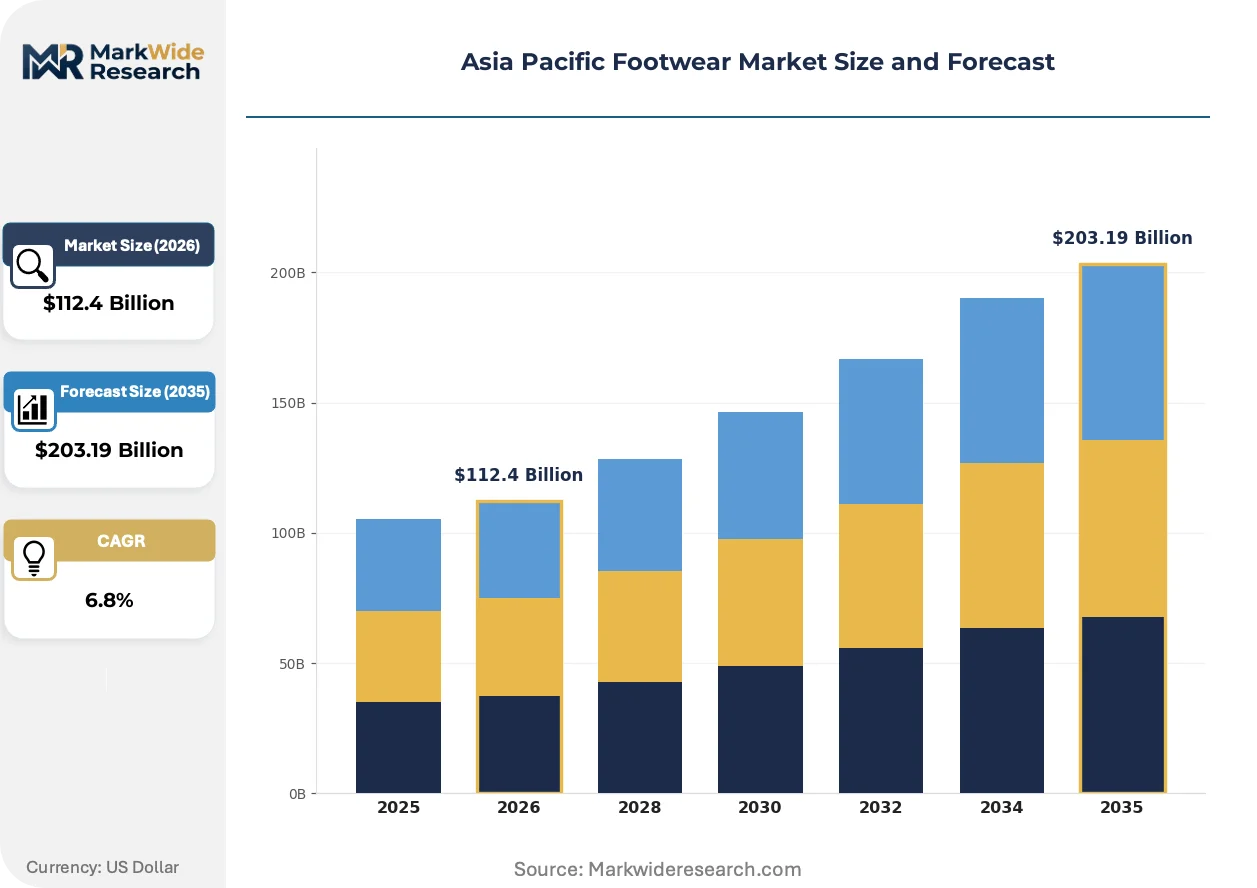
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sneakers, Boots, Sandals, Formal Shoes End User: Men, Women, Children, Sports Enthusiasts Material: Leather, Synthetics, Textile, Rubber Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | ASICS Corporation, Skechers USA Inc, Nike Inc, Belle International Holdings Limited, VF Corporation, Adidas AG, Under Armour Inc, Geox SpA, Puma SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Footwear Market Emerging Trajectories
Material science breakthroughs and regulatory compliance automation are converging to reshape product architecture and supply chain transparency across the region's production networks.
3D-printed midsole lattice structures are modularizing cushioning customization. Marathon training communities in Japan and Australia are adopting these geometries at accelerating rates. This technology is modularizing the traditional mold-investment barrier that once locked smaller brands out of performance categories.
China's GB standards for restricted substance lists are tightening testing protocols for phthalates and heavy metals in children's footwear. Manufacturers serving cross-border e-commerce channels must now maintain dual-certified inventory pools. The synthetic children's segment is absorbing the largest compliance cost increases while consolidating supplier relationships.
Direct-to-consumer subscription models for athletic shoe replacement are fragmenting traditional retail dependency. Running clubs in Singapore and Bangkok are piloting wear-based refresh programs that bypass multi-brand distributors. This pattern is most visible in premium technical categories where fit consistency reduces trial risk.
Asia Pacific Footwear Market Segmentation
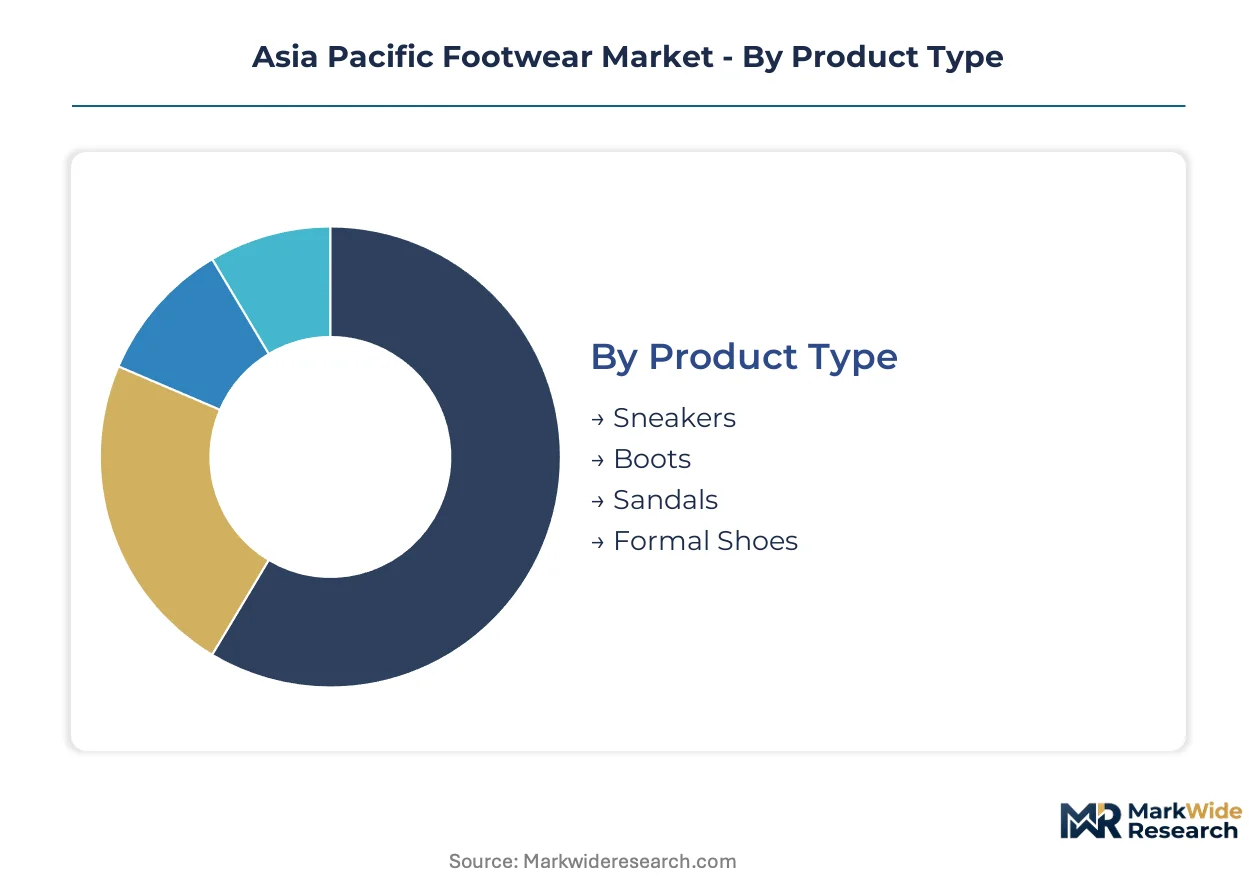
Segmentation in the Asia Pacific Footwear Market reveals how certification burdens, material restrictions, and channel economics reshape competitive positioning across distinct buyer clusters. Each dimension carries unique compliance obligations under China's SAMR, India's BIS, and Japan's METI frameworks.
Product Type:
Sneakers and formal shoes carry divergent certification loads under regional quality mandates, with synthetic-intensive categories facing heavier GB and BIS testing protocols.
- Sneakers:Athletic footwear constructed from engineered mesh uppers, EVA midsoles, and rubber outsoles through injection molding. Demand concentrates in China's tier-one cities and Vietnam's manufacturing corridors as fitness culture penetrates Southeast Asian urban centers. SAMR chemical testing for phthalates and heavy metals extends launch timelines for cross-border brands.
- Formal Shoes:Leather-dominant construction with cemented or Blake-stitched assembly for professional environments. Japan and South Korea maintain material fidelity requirements that block full synthetic substitution in premium segments, preserving margin pools despite slower volume growth.
- Boots:Ankle-to-knee coverage with reinforced toe caps and weather-resistant treatments, serving industrial safety and outdoor recreation applications.
- Sandals:Open-toe designs utilizing molded rubber soles and textile straps, dominant in India's tier-two cities and Indonesia's tropical climate zones.
Leading the category by volume: Sneakers. Growing fastest: Formal shoes in Vietnam's manufacturing corridors.
End User:
User-based segmentation maps directly to sizing standardization requirements and age-restricted substance testing under China's GB standards for children's footwear.
- Sports Enthusiasts:Technical performance buyers prioritizing biomechanical cushioning, breathability metrics, and durability under repetitive impact. Marathon training communities in Japan and Australia are adopting 3D-printed midsole geometries at accelerating rates, fragmenting traditional mold-investment barriers.
- Men:Volume concentration in formal and casual categories across India's secondary cities as organized retail extends beyond Mumbai and Delhi corridors.
- Women:Fashion-forward and athletic segments with higher channel fragmentation toward direct-to-consumer platforms.
- Children:Strictest regulatory burden under GB phthalate restrictions and BIS quality certification, absorbing the largest compliance cost increases while consolidating supplier relationships.
Expanding most quickly: Sports Enthusiasts. Largest absolute volume: Men.
Material:
Material selection determines feedstock cost exposure and cross-border certification complexity, with synthetics facing the steepest regulatory escalation.
- Synthetics:Polyurethane, polyester, and thermoplastic elastomers enabling performance customization and cost scalability. China's SAMR enforces GB standards for restricted substance lists that accelerate certified supplier consolidation.
- Leather:Full-grain and corrected-grain hides with traditional tanning processes, retaining dominance in Japan and South Korea premium formal segments where material fidelity blocks substitution.
- Textile:Knitted and woven uppers gaining traction in sustainability-positioned lines through recycled fiber integration.
- Rubber:Natural and synthetic compounds for outsole traction and sandal base construction, vulnerable to petrochemical input volatility.
Climbing the fastest: Synthetics. Maintaining premium price realization: Leather.
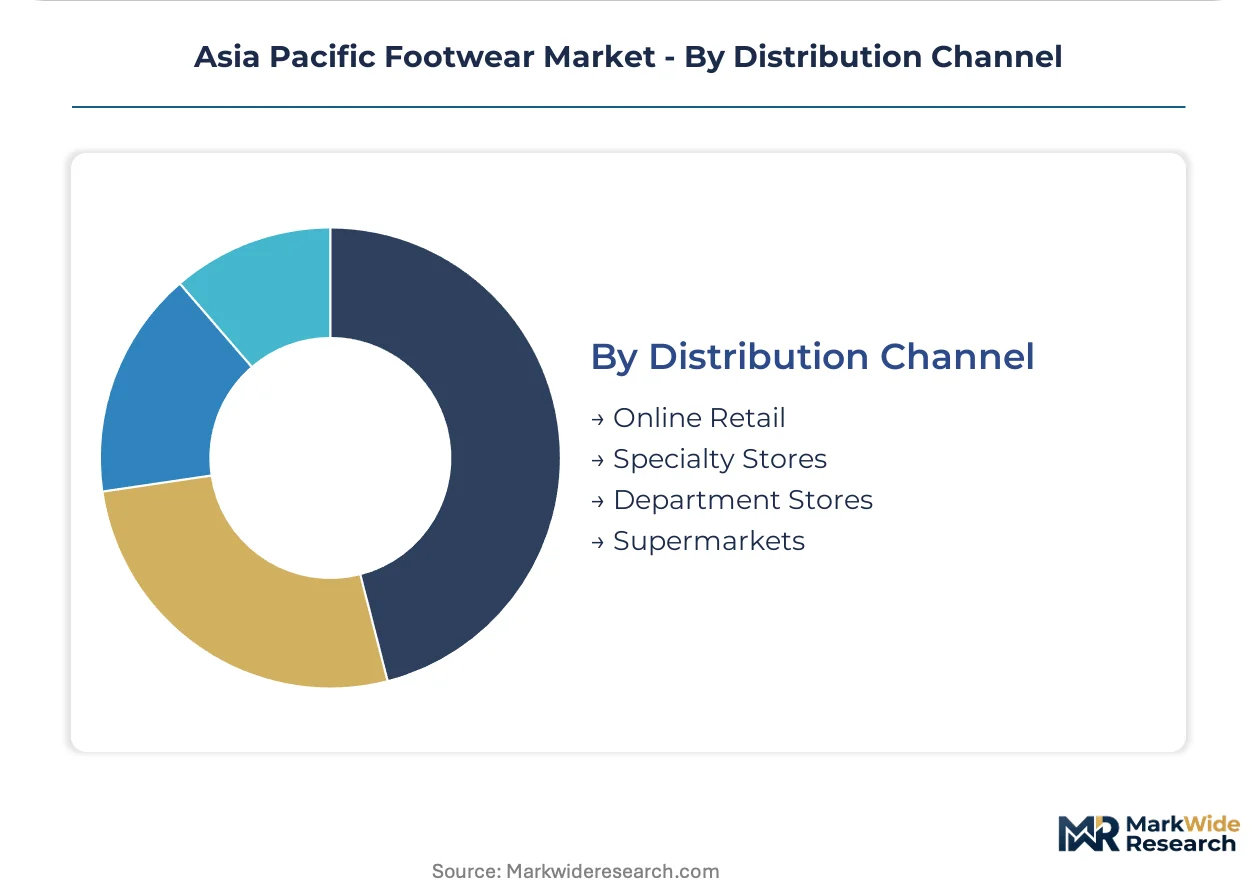
Distribution Channel:
Channel economics in the Asia Pacific Footwear Market reflect logistics infrastructure maturity and regulatory compliance automation for cross-border e-commerce.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators requiring dual-certified inventory pools for GB and BIS compliance. Running clubs in Singapore and Bangkok are piloting subscription-based refresh programs that bypass multi-brand distributors.
- Specialty Stores:Technical fitting services and brand-flagship experiences concentrated in Japan and Australia's marathon training corridors.
- Department Stores:Multi-brand aggregation with higher overhead structures facing compression from digital-native competitors.
- Supermarkets:Mass-market volume play with limited size runs and reduced service levels, dominant in India's tier-two urban expansion zones.
Gaining share fastest: Online Retail. Still capturing largest transaction volume: Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's footwear production-linked incentive zones and Vietnam's export processing corridors are concentrating manufacturing capacity as China's cost advantages erode. Special economic zones in Indonesia and Thailand are attracting relocation investments from contract manufacturers seeking tariff arbitrage. The regional distribution of final assembly now spans four distinct national ecosystems.
China
Domestic consumption in Guangdong and Zhejiang provinces absorbs premium athletic inventory while SAMR enforces GB chemical standards that extend certification timelines. The Yangtze River Delta retains mold-making and component fabrication despite final assembly migration. Dongguan's industrial corridor specializes in 3D-printed midsole prototyping for technical running lines.
India
Tier-two cities including Pune, Ahmedabad, and Lucknow are emerging as volume concentration points as organized retail extends beyond Mumbai and Delhi. BIS quality certification mandates tighten import compliance for synthetic children's footwear. The Agra-Kanpur leather belt maintains formal shoe production while Tamil Nadu's SEZs attract athletic contract manufacturing.
Vietnam
Ho Chi Minh City and Hanoi corridors host final assembly for export-oriented athletic brands serving North American and European markets. The country's EVFTA tariff advantages accelerate capacity expansion in Binh Duong and Dong Nai provinces. Specialized industrial parks in Hai Phong are developing synthetic material compounding capabilities to reduce Chinese feedstock dependency.
Indonesia
Java-based manufacturing clusters in Tangerang and Surabaya serve domestic archipelago distribution while facing logistics fragmentation in secondary islands. The footwear sector absorbs relocation investment from Bangladesh and Myanmar as labor costs diverge. Batam's free trade zone offers duty-free material import for re-export assembly.
Japan
Technical R&D concentrates in Kobe's footwear industrial district with METI-aligned JIS safety protocols shaping regional export standards. Domestic production focuses on premium formal segments where material fidelity requirements block synthetic substitution. Marathon training communities in Tokyo and Osaka drive adoption of biomechanically optimized performance lines.
Asia Pacific Footwear Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with athletic labels commanding premium positioning while OEMs capture volume in private-label distribution. The vendor base organizes into three tiers: global brand houses with athlete endorsement architectures, regional specialists with technical R&D differentiation, and scale-driven contract manufacturers serving multi-brand retail. Consolidation pressures favor players with certified supplier networks spanning BIS, GB, and JIS compliance regimes. Dominant competitive moves include backward integration into synthetic material compounding and geographic expansion into India's tier-two urban corridors.
Within the global brand house tier, Nike Inc and ASICS Corporation exemplify divergent positioning strategies. Nike anchors premium athletic distribution through China and Southeast Asia flagship networks. ASICS occupies a technical specialization position with Japan-centric biomechanics R&D extending into regional marathon communities. Skechers USA Inc sits within the accessible-price vector, controlling broad retail distribution across India's emerging urban centers and Southeast Asian multi-brand channels.
| Leading Market Players |
|---|
| ASICS Corporation |
| Skechers USA Inc |
| Nike Inc |
| Belle International Holdings Limited |
| VF Corporation |
| Adidas AG |
| Under Armour Inc |
| Geox SpA |
| Puma SE |
| Others |
Supply Flow & Price Mechanics
Biomechanics and materials science talent pools concentrated in Japan and South Korea widen labor-cost differentials between premium technical tiers and mass-market economy lines across the Asia Pacific footwear market.
Pricing Analysis
Lead-time premiums reward certified suppliers with compressed delivery windows while spot inventory in Vietnam's export corridors trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates technical performance lines with JIS-aligned safety protocols from BIS-certified domestic tiers and uncertified gray-market imports. Price differentiation hinges on GB chemical testing completion and SAMR registration status. Sports enthusiasts in Japan and Australia absorb the highest premiums, while India's tier-two urban expansion zones drive volume through price-sensitive supermarket channels.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape sourcing patterns by offsetting synthetic material compounding costs for manufacturers establishing Tamil Nadu SEZ capacity. Feedstock for polyurethane midsoles and rubber outsoles draws from Chinese petrochemical corridors and Thai natural rubber plantations, with Vietnam's Binh Duong province concentrating final assembly for export markets. Single-source vulnerability concentrates in Ho Chi Minh City and Hanoi manufacturing belts. Distribution runs through direct-to-consumer platforms requiring dual-certified inventory pools for cross-border e-commerce compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific footwear market reads as supply-constrained, with certified supplier consolidation under BIS, GB, and JIS regimes propping pricing power for compliant tier-one manufacturers.
For Market Incumbents: Lock in certified supplier relationships spanning BIS, GB, and JIS compliance regimes before multi-jurisdiction certification timelines extend further. Add synthetic material compounding capacity in Vietnam's Hai Phong industrial parks to reduce Chinese feedstock dependency. Control distribution through direct-to-consumer subscription models piloted in Singapore and Bangkok running clubs. For New Entrants and Emerging Players: Enter via Indonesia's underpenetrated secondary islands where logistics infrastructure gaps delay incumbent reach. Target digital-native direct-to-consumer positioning in the archipelago's emerging urban centers outside Java. Leverage textile-rubber convergence and single-factory production models to compress lead times against established multi-node networks. For Investors and Strategic Acquirers: Re-rating potential sits with contract manufacturers holding cross-border certification capabilities given India's PLI scheme acceleration and Vietnam's EVFTA tariff advantages. Long-term viability centers on players with backward integration into synthetic material compounding and captive biomechanics R&D pipelines. Watch for inflection signals in 3D-printed midsole adoption rates across Japan and Australia's marathon training communities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Compounding | Vietnam's Hai Phong parks reduce Chinese petrochemical feedstock dependency for EVA midsole production. |
| Direct-to-Consumer Platform Launch | Singapore and Bangkok running clubs pilot subscription refresh programs bypassing multi-brand distributors. |
| Cross-Border Certification Investment | Dual BIS-GB inventory pools enable e-commerce penetration into India's tier-two urban corridors. |
| 3D-Printed Midsole Prototyping Scale-Up | Dongguan's industrial corridor fragments mold-investment barriers locking smaller brands from technical categories. |
| PLI Scheme Manufacturing Footprint Expansion | Tamil Nadu SEZs attract athletic contract manufacturing through India's production-linked incentive frameworks. |
Methodological Framework
Independent corroboration across primary interviews with footwear brand managers, category buyers at multi-brand retailers, synthetic material procurement leads, and Vietnam-based contract manufacturing executives underwrites the qualitative findings. Secondary validation draws from BIS certification databases, SAMR GB standards filings, customs and trade flow records, and METI-aligned JIS safety protocol documentation. Bottom-up demand modeling triangulates against top-down production capacity assessments across China's Yangtze River Delta, Vietnam's export processing zones, and India's Agra-Kanpur leather belt.
Comparable-period anchoring to historical production volumes and certification timeline data establishes baseline trajectory assumptions across the projection horizon. Segmentation dimensions span product type, end-user archetype, material composition, and distribution channel, with additional modeling of regulatory compliance tier as a cross-cutting variable. CAGRs derive from fitted growth curves incorporating petrochemical input cost indices, logistics infrastructure development rates, and e-commerce penetration trajectories in secondary urban markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petrochemical price spikes, sudden BIS or GB regulatory tightening, or logistics disruptions in Vietnam's manufacturing corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Hiking Footwear Market
Footwear
Winter Footwear Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Self-Lacing Shoes Market
Footwear
Equestrian Footwear Market
Footwear
Women's Sneakers Market
Footwear
Indian Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
Custom Shoes Market
Footwear
UGG Boots Market
Footwear
Duck Boots Market
Footwear
Second Hand Designer Shoes Market
Footwear
GCC Footwear Market
Footwear
Global Footwear Market
Footwear
Sneakers Market
Footwear
White Sneakers Market