
 Kid Footwear Market | 2026-2036
Kid Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Kid Footwear Market Analysis
CE marking for children's footwear safety is collapsing the supplier base across Europe, forcing smaller manufacturers to absorb testing costs or exit. Nike, Inc. leverages its dedicated kids' innovation labs to sustain performance-grade designs for grade-school athletes. Adidas AG anchors its position through recycled ocean-plastic uppers that meet emerging EU Green Deal procurement criteria. Stride Rite specializes in podiatrist-certified toddler constructions that command premium shelf placement in North American specialty retail.
Kid footwear encompasses closed-toe and open-toe constructions engineered for developing feet, typically incorporating flexible rubber outsoles with sub-200g weights, breathable linings, and adjustable closures to accommodate growth spurts. The category serves both functional protection and identity-expression purposes for wearers aged zero to fourteen. Sneakers and sandals together occupy the dominant volume share, though boots generate disproportionate margin pools in cold-climate markets where waterproof membrane integration justifies price premiums. Synthetic materials lead on unit economics, while leather segments face pressure from vegan-certification requirements that reshape sourcing decisions for preschool and grade-school lines.
REACH and RoHS frameworks in Europe restrict phthalates and heavy metals in children's footwear, directly elevating compliance costs for synthetic-material suppliers. The US Consumer Product Safety Commission enforces sharp-object and small-parts standards that govern toddler-design specifications. Stakeholders must monitor evolving chemical-ban schedules and biobased-material certification pathways to preserve market access across jurisdictions.
Market Dynamics
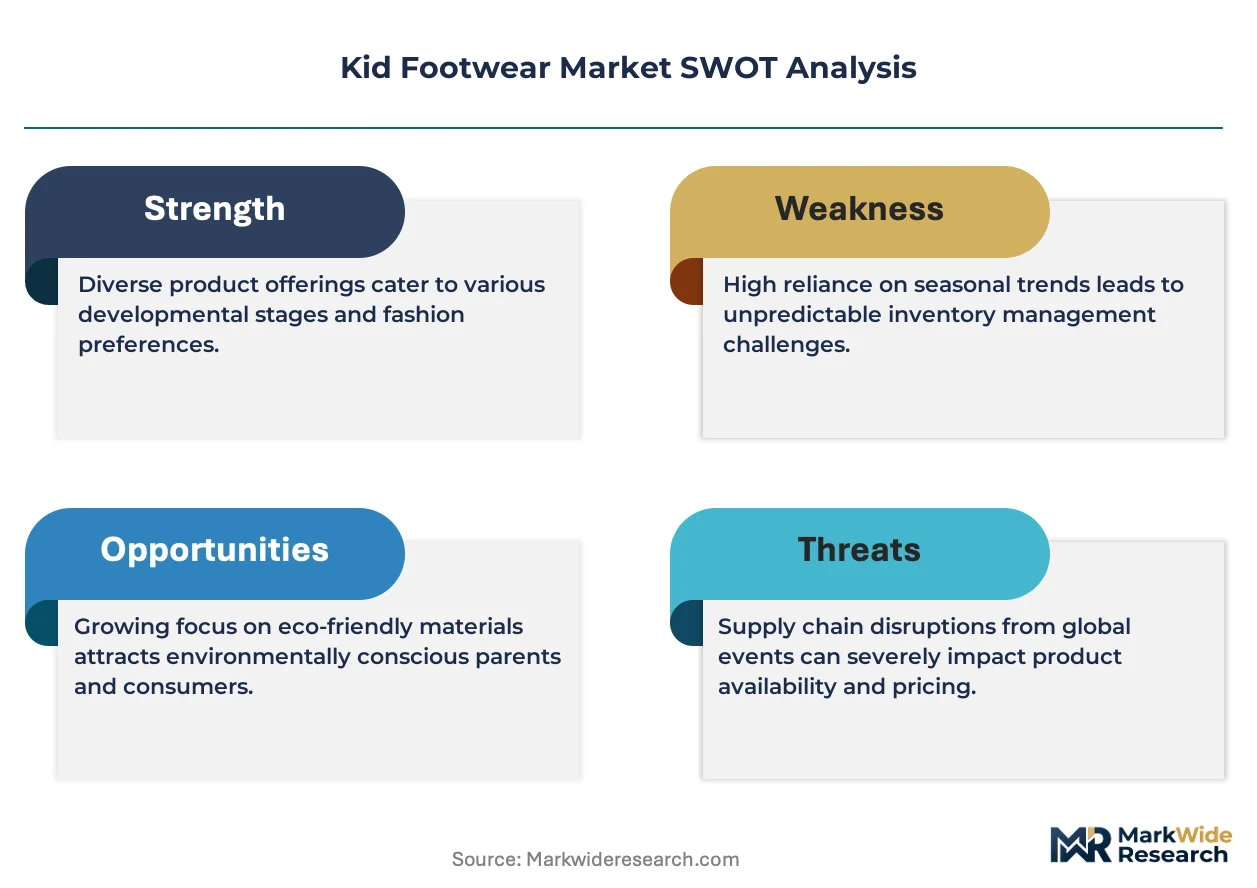
REACH compliance in Europe is compressing the synthetic-material supplier base while China domestic brands expand premium toddler lines, creating a bifurcation between chemical-regulated and volume-driven production ecosystems.
Growth Catalysts
- Preschool non-toxic certification:Parents of zero-to-four-year-olds prioritize REACH-compliant and phthalate-free constructions, pulling demand toward audited supply chains in Germany and France.
- EU Green Deal procurement criteria:Public-sector and institutional buyers now mandate recycled-content thresholds, accelerating ocean-plastic and bio-based material adoption in grade-school lines.
- Podiatrist-certified constructions:North American specialty retail channels reward biomechanically validated toddler footwear with premium shelf placement and reduced slotting fees.
Market Restraints
- Petrochemical input volatility:EVA and TPU resin prices fluctuate with crude-oil indices, squeezing margin predictability for synthetic-dominant manufacturers in Vietnam and Indonesia.
- CE-marking testing cost concentration:Smaller European suppliers absorb EUR 15,000–50,000 per SKU for safety certification, forcing exits and consolidating production among capitalized players.
- Leather substitution pressure:Vegan-certification requirements in preschool segments displace traditional bovine and ovine hides, requiring costly supply-base requalification.
Strategic Opportunities
- India underpenetration:Domestic organized retail and e-commerce fulfillment infrastructure remain nascent for premium toddler footwear, offering first-mover positioning in Mumbai and Delhi NCR.
- Brazil biobased-material convergence:Sugarcane-derived EVA and natural rubber outsoles align with emerging ANVISA pediatric-safety guidelines and local agricultural processing capacity.
- Direct-to-consumer channel innovation:Subscription-based sizing programs for growth-spurt intervals bypass wholesale margin compression and capture recurring revenue in North American urban households.
Industry Challenges
- Biomechanical engineering talent scarcity:Pediatric podiatrists and footwear-design hybrids command premium compensation, constraining R&D throughput for mid-tier manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous US CPSC small-parts testing, EU REACH chemical audits, and China GB standards create 8–14 month product-launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kid Footwear Market |
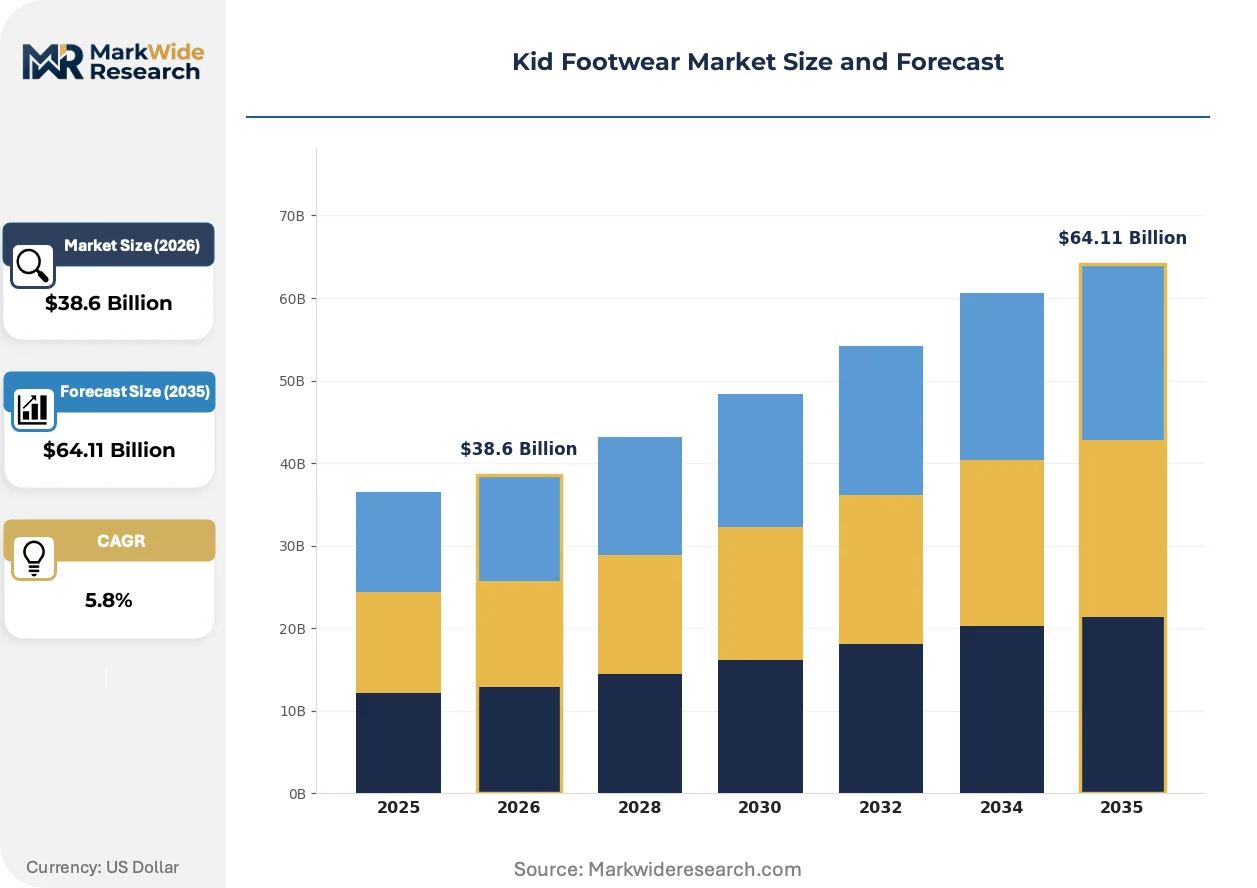
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sneakers, Sandals, Boots, Loafers Material: Leather, Synthetic, Canvas, Rubber Age Group: Toddlers, Preschoolers, Grade School, Preteens Gender: Boys, Girls, Unisex, Others |
| Companies Covered | Nike, Inc., Adidas AG, SKECHERS USA, Inc., Puma SE, New Balance, Crocs Retail, LLC, ASICS Corporation, Stride Rite, The Children's Place, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kid Footwear Market Emerging Trajectories
Material science and regulatory chemistry are compressing design cycles while digital fit technologies reshape how parents purchase for growing feet across channels.
3D-knitted uppers constructed from monofilament polyester yarns are miniaturizing ventilation zones to sub-millimeter precision, enabling zone-specific breathability maps that adapt to toddler foot-heat profiles. Grade-school athletic segments in Japan and South Korea adopt these constructions at 18-month replacement cycles. This compression of material-layer thickness is eliminating traditional cut-and-sew assembly steps and reducing finished-goods weight below 150 grams.
ECHA's 2023–2027 restricted-substances roadmap extends phthalate bans to 24 additional plasticizers and introduces nano-material notification requirements for antimicrobial footbed treatments. Footwear manufacturers serving EU member states must reformulate synthetic linings and outsoles by 2026 submission deadlines. Preschool segments face the steepest compliance burden, as small-part and chemical restrictions overlap in the same age-classified products.
Size-prediction algorithms using smartphone foot-scanning applications are displacing in-store Brannock-device fittings among millennial and Gen-Z parent cohorts. Specialty retail and mass-market e-commerce platforms in the United States and United Kingdom integrate these tools to reduce return rates for incorrectly sized toddler purchases. This channel migration concentrates data ownership with platform operators and erodes traditional wholesale relationships.
Kid Footwear Market Segmentation
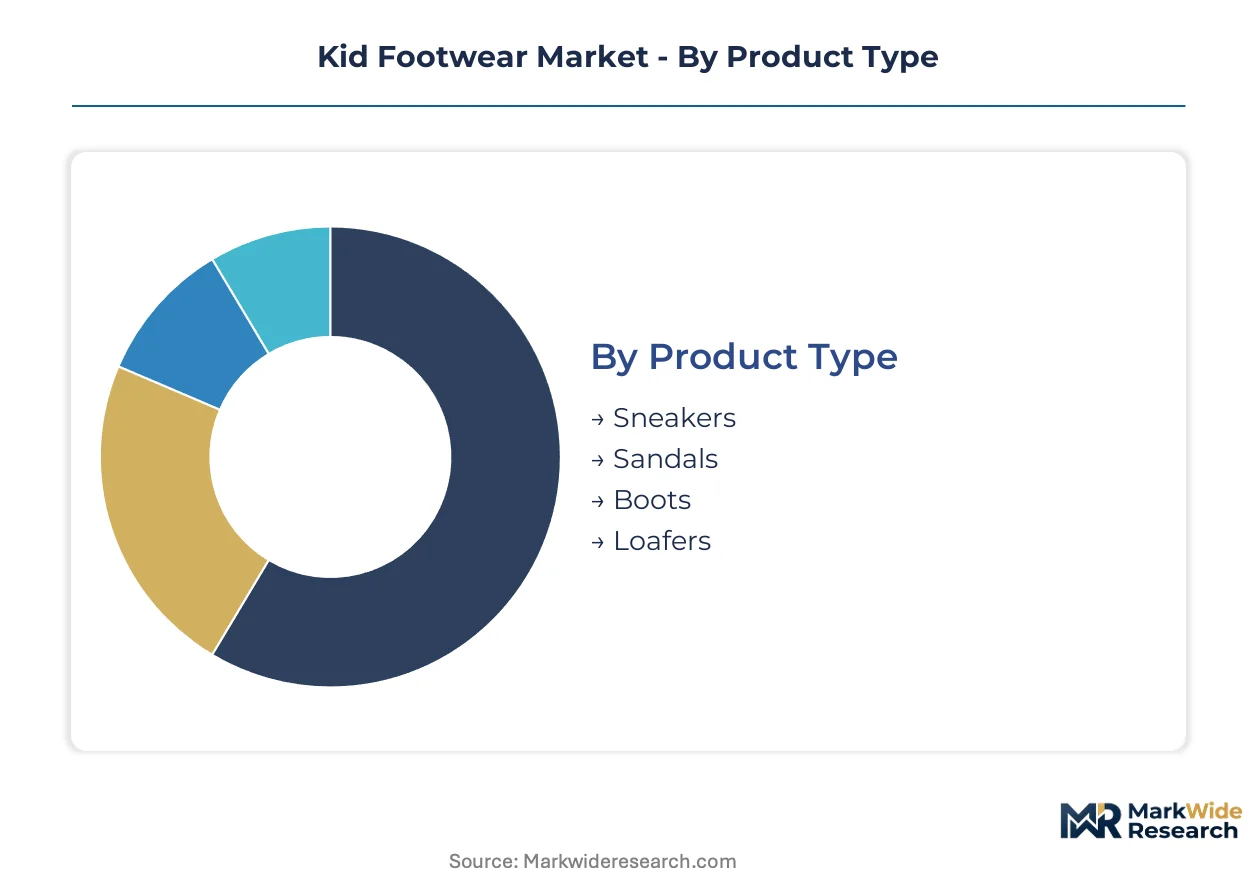
Segmentation in kid footwear reveals divergent compliance burdens and margin structures across age-classified products. Material choices and closure mechanisms shift dramatically between toddler safety requirements and grade-school performance demands. Understanding these splits enables targeted positioning against REACH chemical thresholds and podiatrist certification standards.
Product Type:
Export-led demand concentrates in sneakers and sandals shipped from Vietnam and Indonesia to North American and European retail channels, while boots serve domestic cold-climate markets with shorter supply chains.
- Sneakers:Closed-toe constructions with flexible rubber outsoles under 200g dominate volume. Demand concentrates in China as domestic brands expand premium toddler lines with podiatrist-certified midsoles. REACH compliance in Europe tightens chemical restrictions on synthetic uppers, elevating testing costs for export-oriented manufacturers.
- Sandals:Open-toe designs with adjustable hook-and-loop closures accommodate rapid foot growth. North American specialty retail channels reward biomechanically validated constructions with premium shelf placement. Parents of preschoolers drive adoption of certified non-toxic materials in Germany and France.
- Boots:Waterproof membrane integration justifies price premiums in cold-climate markets.
- Loafers:Slip-on leather constructions face pressure from vegan-certification requirements in formal preschool segments.
Sneakers holds the largest share; momentum sits with sandals.
Material:
Cost tier stratification separates premium leather lines from economy synthetic volumes, with bio-based alternatives climbing fastest on EU Green Deal procurement criteria.
- Synthetic:EVA and TPU resins deliver unit economics for mass-market grade-school lines. Petrochemical input volatility squeezes margin predictability for manufacturers in Vietnam and Indonesia. ECHA's restricted-substances roadmap forces reformulation of phthalate-containing plasticizers by submission deadlines.
- Leather:Traditional bovine and ovine hides command premium positioning in North American specialty retail. Vegan-certification requirements in preschool segments displace conventional sourcing, requiring costly supply-base requalification for tanneries.
- Canvas:Breathable cotton uppers serve warm-climate casual segments with lower compliance burdens.
- Rubber:Natural rubber outsoles align with emerging ANVISA pediatric-safety guidelines in Brazil's agricultural processing corridor.
Synthetic commands volume leadership; bio-based material adoption is climbing the fastest.
Age Group:
Customer type splits between institutional buyers for toddlers and individual parent decision-makers for older cohorts, with certification intensity inversely correlated with age.
- Toddlers:Zero-to-four-year-old footwear combines small-parts safety with chemical compliance. Parents prioritize REACH-compliant and phthalate-free constructions, pulling demand toward audited supply chains. CE marking collapses the European supplier base through EUR 15,000–50,000 per SKU testing costs.
- Preschoolers:Four-to-six-year-old lines balance growth-accommodating closures with identity-expression features. China domestic brands expand premium offerings in this segment. Size-prediction algorithms using smartphone foot-scanning displace traditional fittings among millennial parents.
- Grade School:Six-to-ten-year-old athletic segments adopt 3D-knitted uppers at compressed replacement cycles.
- Preteens:Ten-to-fourteen-year-old fashion-forward designs mirror adult trend cycles with shorter lifespans.
Toddlers drives certification innovation; preteens is expanding most quickly on fashion-cycle acceleration.
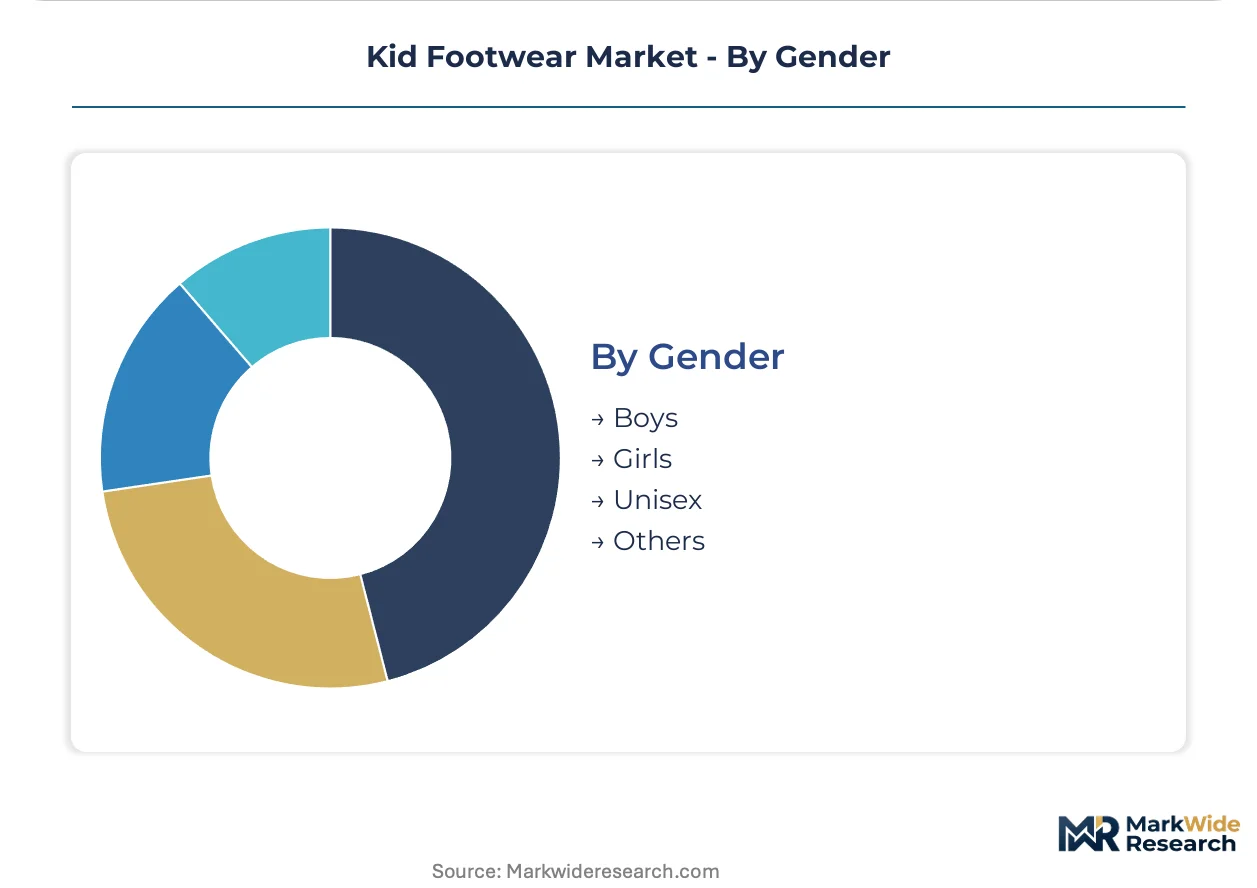
Gender:
Maturity differentiation separates established boys' athletic franchises from emerging unisex positioning that streamlines inventory for direct-to-consumer channels.
- Boys:Performance-grade designs for grade-school athletes sustain dedicated innovation investment. Nike leverages kids' innovation labs to maintain technical differentiation. Color and graphic treatments emphasize action-oriented themes.
- Girls:Identity-expression purposes dominate with broader style variety and seasonal pattern turnover. Subscription-based sizing programs capture recurring revenue in North American urban households.
- Unisex:Neutral color palettes and adjustable closures reduce SKU complexity for e-commerce fulfillment.
- Others:Gender-neutral marketing approaches gain traction among Gen-Z parent cohorts seeking inclusive positioning.
Boys retains volume concentration; unisex is gaining share fastest on inventory rationalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement criteria reshape sourcing decisions across developed markets while China domestic brands expand premium toddler lines, creating divergent compliance and growth trajectories.
United States
Millennial parents drive demand for podiatrist-certified toddler constructions through specialty retail channels. The US Consumer Product Safety Commission enforces sharp-object and small-parts standards that govern design specifications. Boston-based Stride Rite anchors biomechanical validation efforts for zero-to-four-year-old footwear.
China
Domestic brands capture premium positioning in grade-school athletic segments with dedicated innovation infrastructure. GB standards from SAMR establish chemical and mechanical safety baselines for local production. Yangtze River Delta manufacturing clusters supply both domestic retail and export channels with compressed lead times.
Germany
Parents of preschoolers prioritize REACH-compliant and phthalate-free constructions, pulling demand toward audited supply chains. ECHA's 2023–2027 restricted-substances roadmap extends phthalate bans to 24 additional plasticizers. Bavarian testing laboratories absorb EUR 15,000–50,000 per SKU certification costs for CE marking compliance.
Brazil
Sugarcane-derived EVA and natural rubber outsoles align with emerging ANVISA pediatric-safety guidelines. Local agricultural processing capacity supports bio-based material convergence in toddler segments. São Paulo industrial corridors develop integrated supply chains from feedstock to finished goods.
India
Domestic organized retail and e-commerce fulfillment infrastructure remain nascent for premium toddler footwear. BIS standards govern product safety for local manufacturing and import clearance. Mumbai and Delhi NCR clusters attract first-mover positioning for subscription-based sizing programs targeting urban households.
Kid Footwear Market Vendor Landscape
Player mix skews toward diversified athletic apparel conglomerates with dedicated kids' innovation infrastructure. Mid-tier specialists compete on podiatrist certification and biomechanical validation for toddler segments. Two strategic archetypes dominate: performance-grade athletic developers and certified-safety specialists. Competitive moves concentrate on recycled-content material transitions and direct-to-consumer channel expansion bypassing wholesale margin compression.
Within the athletic-apparel tier, Nike, Inc. and Adidas AG exemplify scale-driven innovation approaches. Nike leverages dedicated kids' innovation labs to sustain technical differentiation in grade-school performance segments. Adidas anchors positioning through recycled ocean-plastic uppers that meet EU Green Deal procurement criteria. Stride Rite represents the specialist archetype with podiatrist-certified constructions commanding premium shelf placement in North American specialty retail channels.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| SKECHERS USA, Inc. |
| Puma SE |
| New Balance |
| Crocs Retail, LLC |
| ASICS Corporation |
| Stride Rite |
| The Children's Place |
| Others |
Supply Flow & Price Mechanics
Sixty-day ocean freight lead times from Yangtze River Delta clusters to North American distribution centers compress margin buffers for synthetic-material suppliers while amplifying pricing power for Vietnam-based manufacturers with regional fulfillment contracts. This inventory velocity differential separates capitalized players absorbing CE-marking testing costs from smaller competitors forced into distressed pricing to maintain shelf presence.
Pricing Analysis
Certification level creates the primary spread across toddler segments, with REACH-compliant and podiatrist-validated constructions commanding premium positioning against uncertified imports. Three-tier pricing structure across premium, standard, and economy levels reflects compliance burden stratification, with CE-marking costs of EUR 15,000–50,000 per SKU forcing consolidation at the top. Cost compression in economy synthetic lines intensifies because petrochemical input volatility squeezes Vietnam and Indonesia manufacturers. Mass-market grade-school parents exhibit highest price sensitivity, while specialty retail channels serving zero-to-four-year-olds tolerate premium positioning for biomechanical validation.
Supply Chain Analysis
Forty-five to sixty-day finished goods inventory cycles dominate Yangtze River Delta and Vietnam export corridors, with Vietnam, Indonesia, and China supplying 80% of North American and European volume. EVA and TPU resins, natural rubber outsoles, and monofilament polyester yarns constitute critical input dependencies. Single-source vulnerability concentrates in Chinese synthetic-material feedstock suppliers subject to ECHA reformulation deadlines. Distribution runs through wholesale apparel importers, direct-to-consumer platforms, and specialty retail channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA's 2023–2027 restricted-substances roadmap compresses design cycles while smartphone foot-scanning applications displace traditional retail fittings, creating simultaneous regulatory and technological disruption vectors for incumbent and entrant positioning strategies.
For Market Incumbents: Fortify supply chain control through backward integration into audited synthetic-material suppliers in Germany and France to secure REACH-compliant feedstock access. Deepen podiatrist certification partnerships to defend premium shelf placement against direct-to-consumer entrants exploiting size-prediction algorithms. Channel control through exclusive specialty retail contracts remains critical as platform operators capture customer data ownership. For New Entrants and Emerging Players: Anchor in India's nascent premium toddler segments where organized retail infrastructure remains underdeveloped and subscription-based sizing programs can bypass wholesale margin compression. Brazil's sugarcane-derived EVA corridor offers white-space positioning against ANVISA guideline convergence. Direct-to-consumer launch with smartphone foot-scanning integration captures millennial parent cohorts seeking convenience. For Investors and Strategic Acquirers: Long-term, this sits as a certification-anchored consolidation play because REACH compliance and CE-marking cost concentration force exits among sub-scale European suppliers. Acquisition targets should display established podiatrist validation infrastructure and Yangtze River Delta manufacturing relationships. Watch ECHA submission deadline adherence as inflection indicator for supply chain viability.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Investment | ECHA reformulation deadlines force synthetic-material requalification by 2026, collapsing uncertified supplier base. |
| Direct-to-Consumer Channel Launch | Subscription sizing programs bypass wholesale margin compression and capture recurring revenue in urban households. |
| Podiatrist Certification Partnership | Biomechanical validation secures premium shelf placement and reduced slotting fees in North American specialty retail. |
| Bio-based Material Transition | EU Green Deal procurement criteria accelerate ocean-plastic and sugarcane-EVA adoption in grade-school lines. |
| Smartphone Foot-Scanning Integration | Size-prediction algorithms displace Brannock-device fittings and concentrate data ownership with platform operators. |
Methodological Framework
Initial hypotheses were tested against primary input from brand managers at athletic footwear conglomerates, category buyers at North American specialty retailers, supply planners at Vietnam-based manufacturers, and pediatric podiatrists consulting on biomechanical designs, then refined through secondary validation against customs records, Nielsen retail audit data, ECHA restricted-substances roadmaps, and SEC 10-K filings from publicly traded footwear companies. Bottom-up volume builds across age-group and material segments were triangulated against top-down macroeconomic drivers.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension: product type, material composition, age classification, and gender positioning. CAGRs were derived from logistic growth curve fitting anchored to observable adoption rates for certification-compliant constructions and digital fit technologies. Forecast inputs incorporate petrochemical price indices, ECHA enforcement timelines, and e-commerce penetration trajectories for toddler segments.
Decision-makers should treat outputs as directional under assumptions of continued REACH enforcement stringency and stable ocean freight rates; material deviation in regulatory timelines or logistics costs would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO