
 Sandals Market | 2026-2036
Sandals Market Size, Share, and Industry Trends Forecast 2026-2036
Sandals Market Intelligence
Subscription-based insole replacement and care services are consolidating how consumers engage with sandal brands beyond the initial purchase. Nike leverages its direct-to-consumer digital platform to sustain recurring revenue from accessory and replacement components. Birkenstock anchors its market position through proprietary cork-latex footbed technology that commands premium pricing and repeat purchases. Deckers Outdoor Corp., which controls the Teva and UGG sandal portfolios, competes across outdoor and fashion segments with distinct brand architectures.
Sandals are open-toe footwear constructed with straps or bands secured to a sole, typically manufactured through injection molding, compression molding, or hand-assembly processes using materials ranging from ethylene-vinyl acetate foam to vegetable-tanned leather. The primary commercial purpose spans casual leisure, athletic recovery, occupational safety, and fashion applications across climates and demographics. Slide sandals and sport sandals lead volume in the product type dimension, while leather and rubber split the material tier between premium positioning and mass-market scalability. The women's segment dominates absolute spend, though unisex styling is expanding fastest as gender-neutral design language crosses from runway to retail.
The US Consumer Product Safety Commission and California's Proposition 65 framework govern chemical disclosure and product safety for footwear sold in North America, while the EU's REACH regulation and CE marking requirements shape material compliance for brands accessing European retail channels. These standards elevate compliance costs for smaller manufacturers but create market access barriers that favor scaled producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving extended producer responsibility frameworks in footwear, as France and Italy advance textile recycling mandates that will reshape post-consumer collection and material recovery obligations across the value chain.
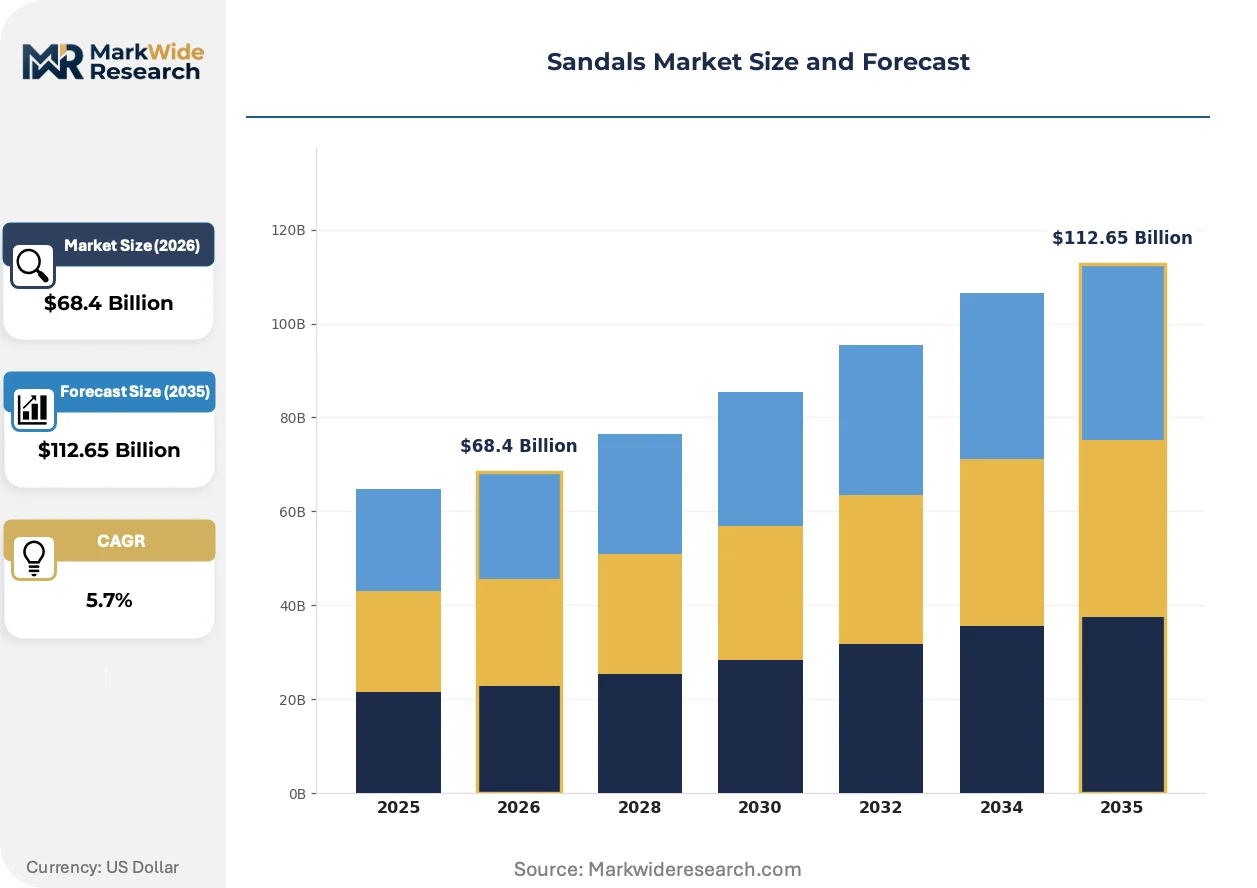
Market Dynamics
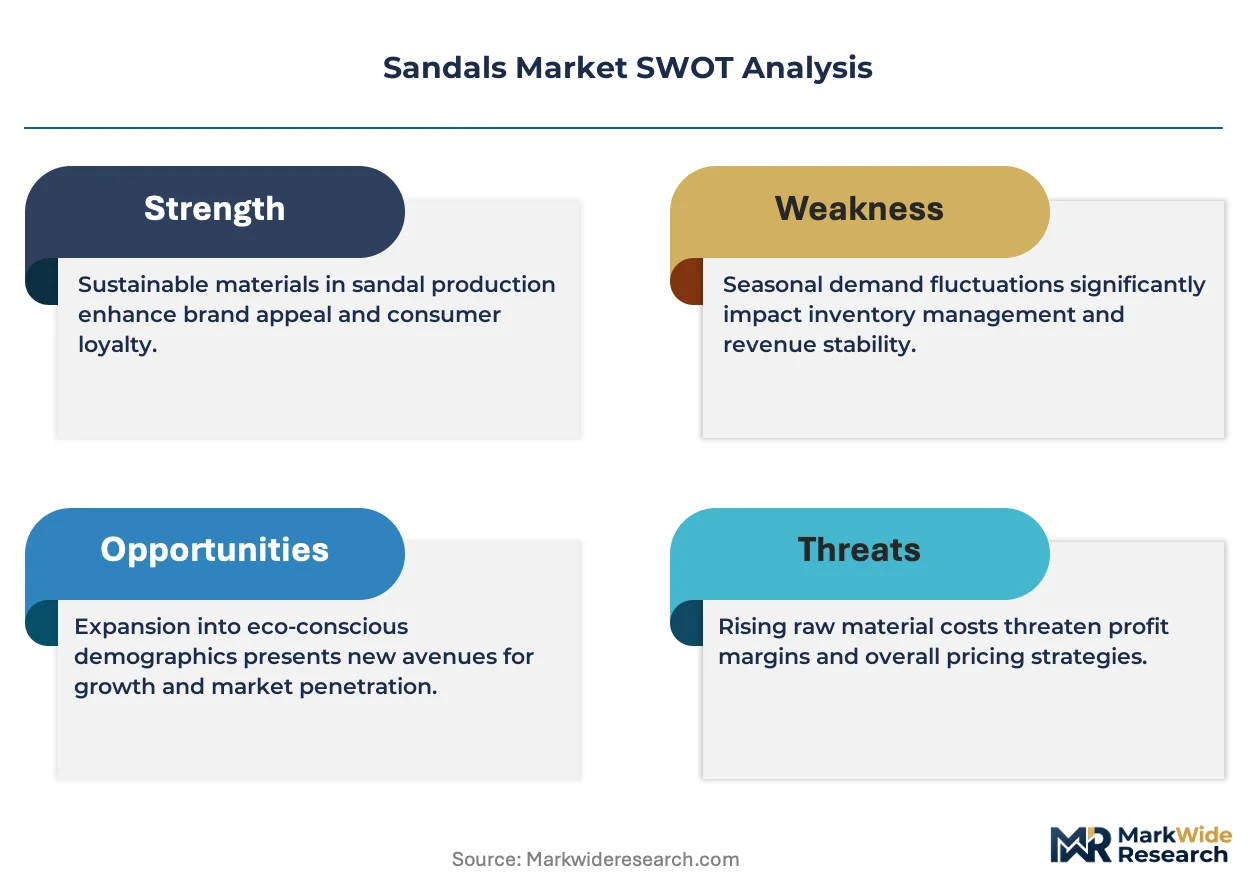
The sandals market is restructuring around chemical compliance mandates as REACH and Proposition 65 force reformulation of EVA foams, adhesives, and leather tanning agents, compressing margins for manufacturers lacking dedicated regulatory affairs teams while rewarding scaled producers with in-house testing laboratories.
Growth Catalysts
- Leisure travel recovery:Resort hospitality operators are restocking guest room amenities and retail inventory, driving bulk procurement of comfort-oriented footwear for vacation environments.
- REACH chemical disclosure:The EU's phased restrictions on chromium VI in leather tanning are accelerating adoption of vegetable-tanned alternatives among premium positioning brands.
- Southeast Asian production-consumption convergence:Vietnam and Indonesia now combine export manufacturing scale with rapidly expanding domestic middle-class demand for branded casual footwear.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian rubber futures fluctuate with monsoon patterns and plantation disease cycles, squeezing margin predictability for mass-market producers.
- Port concentration risk:Vietnam's footwear exports depend heavily on Ho Chi Minh City and Hai Phong container terminals, creating single-point vulnerability during labor disputes or weather events.
- Biodegradable sole durability limitations:Current bio-PU and algae-foam compounds degrade faster under UV exposure and saltwater, restricting their deployment in performance outdoor applications.
Strategic Opportunities
- India underpenetration:Per-capita sandal ownership remains below Southeast Asian levels despite comparable climate, presenting white space for organized retail expansion in tier-two cities.
- Extended producer responsibility tailwinds:France's textile recycling mandate and Italy's emerging footwear EPR framework will create first-mover advantage for brands with closed-loop collection infrastructure.
- Digital-physical channel fusion:Virtual try-on augmented reality tools are reducing return rates for direct-to-consumer sandal sales, lowering logistics costs for pure-play entrants.
Industry Challenges
- Footbed mold engineering talent scarcity:Cork-latex compound formulation and anatomical contouring expertise concentrates in German and Portuguese technical institutes, limiting replication speed.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of CE marking, US CPSC compliance, and California Proposition 65 safe harbor determinations extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandals Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip-Flops, Slide Sandals, Gladiator Sandals, Sport Sandals Material: Leather, Rubber, Synthetic, Fabric Target Audience: Men, Women, Children, Unisex Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Nike Inc., Adidas AG, Crocs Inc., Birkenstock, Skechers USA Inc., Deckers Outdoor Corp., Alpargatas, Clarks, ECCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandals Market Strategic Shifts & Innovations
Material science convergence with digital manufacturing is compressing traditional development cycles while regulatory chemistry mandates force supply chain transparency investments that reshape competitive differentiation mechanisms.
Algae-derived foam midsole technology is integrating into performance sandal construction as a petroleum-EVA replacement. Outdoor and athletic recovery segments are adopting the material fastest, with several brands requiring suppliers to certify bio-content percentages. This integration is compressing R&D timelines as compound suppliers co-locate technical staff with brand product teams to accelerate iteration cycles.
ECHA's SCIP database requirements under REACH Article 33 are mandating substance-of-concern disclosure across the full article composition. Footwear manufacturers must now map chemical inputs through tier-three suppliers, elevating audit costs but creating defensible positioning for brands with pre-existing supply chain visibility investments. The premium leather segment faces the steepest compliance burden due to tanning agent complexity.
Subscription-based insole replacement programs are displacing traditional transactional retail relationships. Direct-to-consumer platforms now capture recurring revenue through automated replenishment of footbed components, with the model penetrating deepest among consumers aged 25-40 in US and German urban markets. This behavior compresses customer lifetime value realization into predictable monthly patterns rather than episodic purchase events.
Sandals Market Segmentation
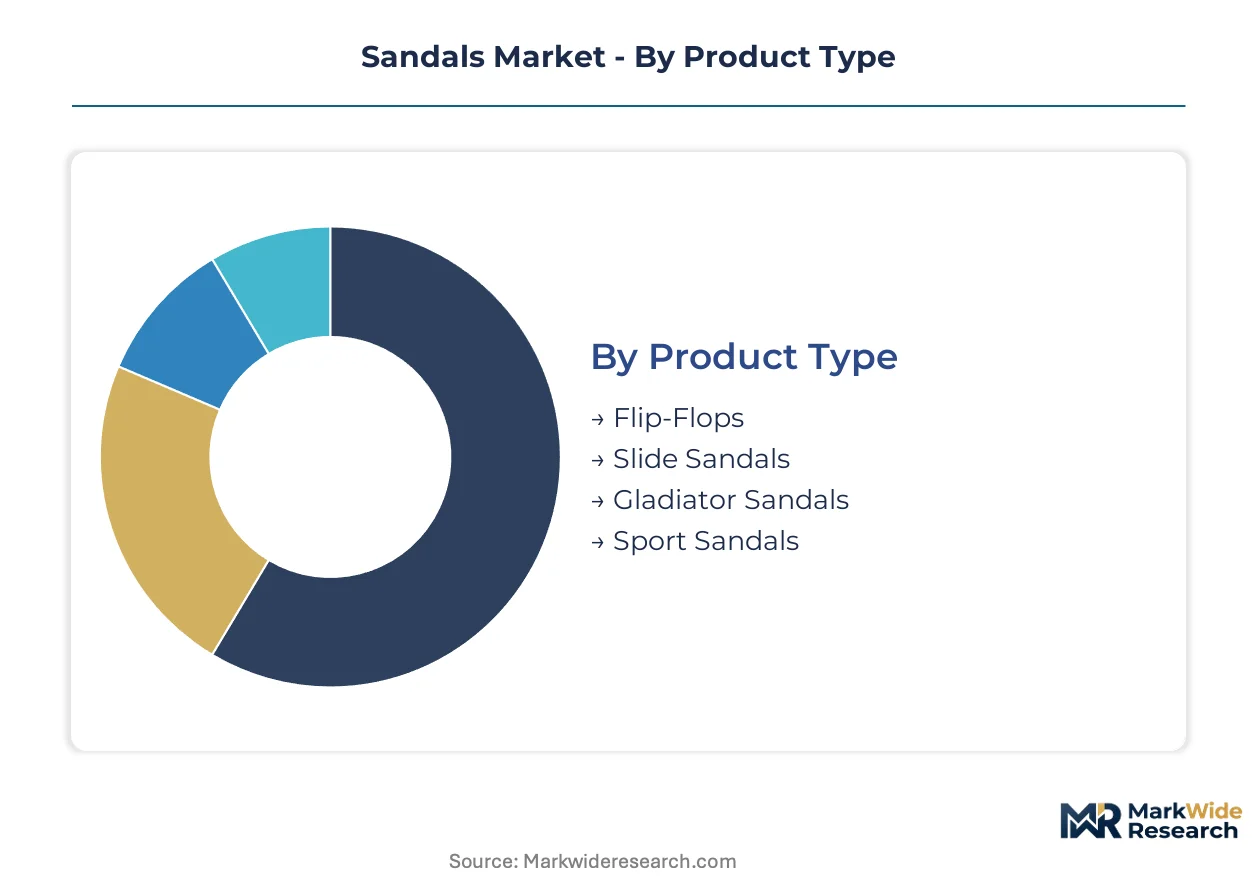
Sandal manufacturers configure production lines around distinct technical specifications and margin profiles. Segmentation reveals where capital deployment concentrates and which product architectures command pricing power across climate zones and use cases.
Product Type:
Slide sandals and sport sandals demand the heaviest mold investment and quality assurance infrastructure, while flip-flops and gladiator styles run on lighter equipment with faster changeover cycles.
- Slide Sandals:Single-strap or dual-strap constructions with contoured footbeds require precision injection molding for EVA midsoles and TPU outsoles. Demand concentrates in resort hospitality procurement and urban casual wear across Germany and the United States, where comfort positioning justifies premium placement. REACH-compliant adhesive systems add formulation complexity for European export batches.
- Sport Sandals:Multi-point strap systems with adjustable buckles and lugged outsoles serve hiking, water sports, and athletic recovery applications. Vietnam's outdoor footwear clusters supply North American specialty retailers, though biodegradable sole compounds face saltwater durability constraints in marine environments.
- Flip-Flops:Minimalist thong constructions using rubber or synthetic straps dominate Southeast Asian domestic consumption and mass-market export channels.
- Gladiator Sandals:Multi-strap leather uppers with ankle lacing or zip closures occupy fashion-forward positioning in Mediterranean and Middle Eastern markets.
Most installed capacity flows through slide sandals. Expansion is steepest in sport sandals.
Material:
Rubber and synthetic compounds absorb the majority of raw material procurement spend, while leather commands the highest per-unit working capital requirements due to tanning cycle times and chemical compliance documentation.
- Rubber:Natural rubber latex and synthetic polyisoprene formulations provide grip and flexibility for outsoles and straps. Thai and Indonesian plantation supply feeds mass-market production, though monsoon-driven price volatility compresses margin predictability for producers without forward-contract coverage.
- Synthetic:EVA, PU, and TPU compounds enable color consistency and performance tuning for athletic and outdoor segments. Algae-foam bio-content certification is accelerating adoption among sustainability-positioned brands in the United States and Germany.
- Leather:Vegetable-tanned and chrome-free hides serve premium and luxury tiers, with Portuguese and Italian tanneries supplying anatomical footbed constructions.
- Fabric:Woven textile uppers and recycled polyester webbing address lightweight casual and beachwear positioning.
Rubber maintains the largest production volume base. Synthetic materials are climbing the fastest as bio-content formulations mature.
Target Audience:
Women's styling historically anchored design investment, though unisex pattern engineering now absorbs disproportionate technical talent as gender-neutral silhouettes scale across direct-to-consumer platforms.
- Women:Fashion-forward and comfort-oriented collections spanning flats, wedges, and embellished casual styles. German and French markets drive premium leather footbed adoption, while Southeast Asian consumers prioritize value-positioned synthetics for everyday wear.
- Unisex:Adjustable strap systems and neutral colorways crossing demographic boundaries. Digital-native brands in the United States deploy virtual try-on tools to reduce fit-related returns in this segment.
- Men:Outdoor performance and minimalist casual architectures with emphasis on durability and arch support.
- Children:Molded constructions with closed-toe protection and rapid size-rotation requirements.
Women's collections retain the deepest SKU density. Unisex positioning is gaining share fastest among urban consumers aged 25-40.
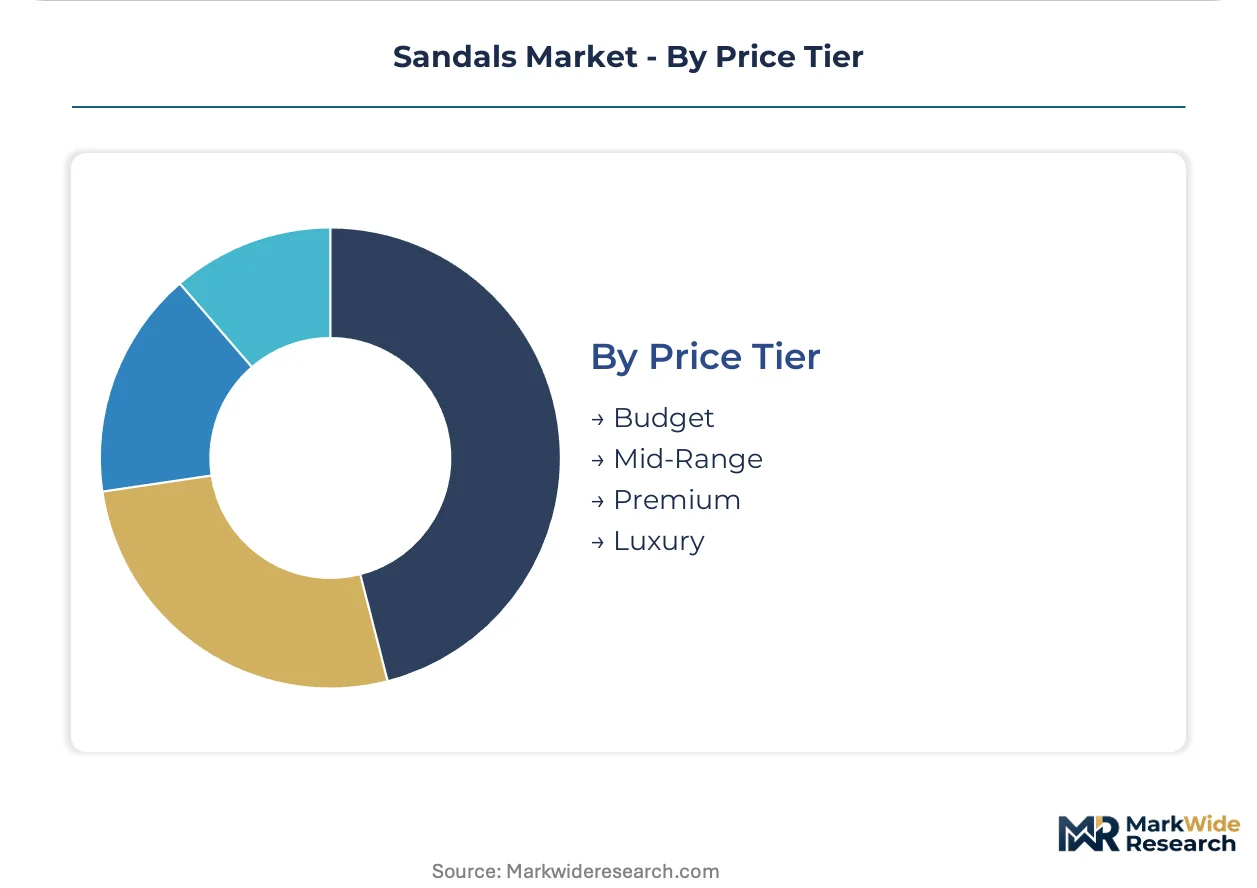
Price Tier:
Premium and luxury tiers concentrate supply chain transparency investment and regulatory documentation costs, while budget positioning depends on scale economies in Vietnamese and Indonesian manufacturing clusters.
- Premium:Proprietary footbed technologies, certified sustainable materials, and extended warranty programs. Birkenstock's cork-latex construction and Nike's subscription insole services exemplify recurring revenue capture in this tier across United States and German markets.
- Luxury:Hand-finished leather, limited distribution, and heritage positioning with Italian and Spanish craftsmanship authentication.
- Mid-Range:Branded synthetic constructions balancing performance features with accessible pricing for Southeast Asian emerging middle-class consumers.
- Budget:Unbranded or private-label flip-flops and slides for mass retail and hospitality bulk procurement.
Premium tier commands the highest margin per unit. Mid-range positioning is expanding most quickly as organized retail penetrates tier-two Indian cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping sandal manufacturing geography as REACH compliance costs in Europe push production toward Southeast Asian clusters with lower chemical disclosure burdens and faster certification timelines. Vietnam, Indonesia, and Thailand now combine export scale with rapidly expanding domestic middle-class demand.
United States
Resort hospitality restocking and direct-to-consumer subscription services drive demand concentration on the coasts. California's Proposition 65 enforces chemical disclosure thresholds that elevate compliance spend for imported footwear. Los Angeles and Miami host the largest wholesale distribution clusters for premium comfort brands targeting vacation and urban casual segments.
Germany
Anatomical footbed technology and vegetable-tanned leather positioning command sustained premium pricing in German retail channels. The EU's REACH regulation and ECHA SCIP database requirements impose tier-three supply chain mapping obligations on brands accessing European markets. Bavaria's technical institutes concentrate cork-latex formulation expertise that limits replication speed among competitors.
Vietnam
Export manufacturing scale and emerging domestic consumption converge in Ho Chi Minh City and Hai Phong manufacturing corridors. The country's footwear sector benefits from EU-Vietnam Free Trade Agreement tariff preferences for qualifying origin content. Port concentration risk at Ho Chi Minh City terminals creates vulnerability during labor disputes or monsoon disruptions.
Indonesia
Natural rubber plantation proximity and expanding organized retail penetration support mass-market production for domestic and export channels. The national industrial ministry promotes footwear sector investment through special economic zone incentives. Jakarta and Bandung industrial clusters absorb capacity migration from cost-pressured Chinese manufacturers.
India
Per-capita sandal ownership remains below Southeast Asian benchmarks despite comparable climate conditions, presenting white space for tier-two city retail expansion. The Bureau of Indian Standards enforces product safety labeling that elevates entry costs for unorganized producers. Maharashtra and Gujarat manufacturing belts concentrate injection molding capacity for domestic mass-market distribution.
Sandals Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with proprietary footbed technology holders commanding margin premiums while volume producers compete on scale economies in Vietnamese and Indonesian clusters. The market exhibits tiered concentration: global sportswear houses with direct-to-consumer platforms, heritage comfort brands with material science differentiation, and regional private-label suppliers serving hospitality bulk procurement. Strategic moves center on subscription-based recurring revenue capture and backward integration into captive cork-latex compound production.
Within the heritage comfort tier, Birkenstock anchors proprietary footbed positioning through German engineering authentication. Nike Inc. and Adidas AG exemplify sportswear-scale competitors leveraging digital platform infrastructure for accessory and replacement component monetization. These three entities represent distinct competitive archetypes: material-science heritage, athletic-performance scale, and lifestyle-fashion hybridization.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Crocs Inc. |
| Birkenstock |
| Skechers USA Inc. |
| Deckers Outdoor Corp. |
| Alpargatas |
| Clarks |
| ECCO |
| Others |
Cost & Logistics Intelligence
Premium cork-latex footbed certification and mass-market synthetic commoditization diverge sharply across the sandals market, with REACH-compliant vegetable-tanned constructions commanding five-to-tenfold unit premiums over injection-molded EVA alternatives while Vietnamese contract manufacturers absorb thin-margin bulk procurement from hospitality operators.
Pricing Analysis
Distributor margin layers compress most severely in the budget tier, where Ho Chi Minh City-based contract manufacturers compete for resort hospitality bulk orders at single-digit percentage markups. Three-tier pricing structure across premium, standard, and economy levels separates Birkenstock's proprietary footbed subscriptions from mid-range branded synthetics and unlabeled flip-flop commodities. Price differentiation hinges on chemical compliance documentation costs and after-sales component replacement bundling. Pricing pressure stems from Thai and Indonesian natural rubber futures volatility. Budget hospitality procurement managers exhibit highest price sensitivity, while German and US urban consumers aged 25-40 show lowest sensitivity to footbed technology premiums.
Supply Chain Analysis
Container freight cost spikes from Ho Chi Minh City and Hai Phong terminals to Los Angeles and Rotterdam have compressed landed margins for Vietnamese export batches by forcing inventory pre-positioning decisions. Supply concentrates in Vietnam, Indonesia, and Thailand, with manufacturing clusters drawing from natural rubber plantations, petroleum-based EVA feedstock, and Portuguese vegetable-tanned leather inputs. Supply chain risk centers on port concentration vulnerability during monsoon disruptions or labor disputes. Distribution runs through Los Angeles and Miami wholesale clusters for US premium brands, direct-to-consumer platforms for subscription insole services, and Jakarta organized retail for Indonesian domestic consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the sandals market rests on backward integration into captive cork-latex compound production and the shift toward recurring-revenue subscription models that capture customer lifetime value across replacement component cycles.
For Market Incumbents: Deploy proprietary footbed technology licensing as a defensive moat against direct-to-consumer entrants with algae-foam bio-content positioning. Incumbents should secure Portuguese and Italian tannery capacity through long-term offtake agreements before REACH Article 33 SCIP database requirements tighten further. Capacity addition in Vietnam's Hai Phong corridor protects against Ho Chi Minh City port concentration risk. Certification investment in CE marking and California Proposition 65 safe harbor determinations extends product launch timelines but creates regulatory access barriers. For New Entrants and Emerging Players: Begin with unisex styling and virtual try-on augmented reality deployment to reduce fit-related return rates in the US and German urban markets aged 25-40. White space concentrates in India's tier-two cities, where per-capita sandal ownership remains below Southeast Asian benchmarks despite comparable climate. The most penetrable segment is mid-range synthetic constructions for organized retail expansion. Go-to-market angle should emphasize sustainability-positioned algae-foam bio-content certification to differentiate from incumbent petroleum-EVA scale. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and ECHA SCIP database mapping requirements exceed smaller manufacturers' dedicated regulatory affairs capacity. Long-term viability favors brands with closed-loop collection infrastructure positioned for France's textile recycling mandate and Italy's emerging footwear EPR framework. Acquisition target archetype: regional private-label suppliers with Vietnamese manufacturing scale seeking premium tier migration through proprietary footbed technology licensing. Signal to watch is biodegradable sole compound durability breakthroughs in saltwater and UV exposure conditions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cork-Latex Production | Captive supply of footbed compounds secures margin control against Portuguese tannery capacity constraints. |
| Subscription Insole Replacement Launch | Recurring revenue capture compresses customer lifetime value realization into predictable monthly patterns. |
| REACH Compliance Certification Investment | ECHA SCIP database readiness creates market access barriers favoring scaled producers with tier-three supply chain visibility. |
| Algae-Foam Bio-Content Certification | Petroleum-EVA replacement accelerates adoption among sustainability-positioned brands in US and German markets. |
| India Tier-Two City Retail Expansion | Organized retail penetration captures white space where per-capita ownership trails Southeast Asian benchmarks. |
Research Approach
Coverage spans the United States, Germany, Vietnam, Indonesia, and India, with primary inputs from each market's manufacturing clusters and retail channels. The analysis combines primary interviews with brand product managers, Vietnamese contract manufacturing executives, German technical institute footbed engineers, US resort hospitality procurement directors, and Indian organized retail category buyers with secondary validation. Secondary sources include EU REACH regulatory filings, US Consumer Product Safety Commission guidance documents, customs and trade data from Vietnamese and Indonesian export authorities, and Nielsen retail audit data. Bottom-up unit economics triangulate against top-down category spend estimates.
Rate-of-change decomposition separates volume growth from mix-shift and pricing components across the analysis window. Segmentation dimensions modeled include product type, material composition, target audience, and price tier, with additional granularity on chemical compliance tier and channel structure. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and material substitution curves. Industry-specific forecast inputs incorporate natural rubber futures volatility patterns and EU-Vietnam Free Trade Agreement tariff preference utilization rates.
Several conditions sit outside the modeled scope, including force majeure disruptions to Vietnamese port operations, breakthrough biodegradable compound durability improvements, and unilateral regulatory acceleration in extended producer responsibility frameworks. Forecasts reflect assumptions about leisure travel recovery trajectory and REACH enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Kids Barefoot Shoes Market
Footwear
Orthopedic Footwear Market
Footwear
Football Shoes Market
Footwear
Luxury Footwear Market
Footwear
Waterproof Sneakers Market
Footwear
Asia Pacific Footwear Market
Footwear
Trail Running Shoes Market
Footwear
White Sneakers Market
Footwear
Riding Boots Market
Footwear
Running Shoes Market
Footwear
Global Men Leather Shoes Market
Footwear
Sneakers Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Casual Shoes Market
Footwear
Footwear Testing Services Market
Footwear
Driving Footwear Market