
 Indian Footwear Market | 2026-2036
Indian Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Indian Footwear Market Analysis
Ethylene-vinyl acetate foam is expanding its share in mid-sole construction across Indian sports and casual footwear, displacing conventional rubber compounds on cost and weight metrics. Bata India leverages its pan-India retail network to sustain distribution density in tier-three towns. Liberty Shoes anchors its position through captive leather tanning and in-house production of polyurethane soles. Relaxo Footwears dominates the mass rubber slipper segment with price points that compete against unorganized local makers.
Indian footwear encompasses finished goods manufactured from leather, synthetic polymers, textile uppers, or rubber compounds through processes including cementing, injection molding, and vulcanization, designed for protection, locomotion, or occupational safety across consumer and industrial applications. Sports shoes command premium positioning as athleisure adoption spreads beyond metropolitan gyms into semi-urban youth wardrobes. Formal footwear retains stable margin pools in corporate and ceremonial segments despite slower volume expansion. The unisex category is gaining shelf space as gender-neutral designs from Canvas and Synthetic materials attract younger demographics through online channels.
BIS mandates compulsory certification for footwear under IS 17043, while the PLI scheme for leather and footwear offers production-linked incentives contingent on minimum domestic value addition and export thresholds. CDSCO regulates medical and orthopedic footwear categories that intersect with therapeutic applications. State-level pollution control boards enforce tannery effluent norms that constrain unorganized leather processors around Agra and Kanpur. Stakeholders must weigh backward integration into synthetic material compounding against dependence on imported ethylene-vinyl acetate granules as tariff structures evolve.
Market Dynamics
PLI scheme disbursements and BIS certification mandates are restructuring competitive economics in Indian footwear, favoring organized manufacturers with capital reserves for compliance and scale investments while squeezing unorganized tanneries around Agra and Kanpur.
Growth Catalysts
- PLI scheme for leather and footwear:Production-linked incentives contingent on domestic value addition thresholds are accelerating capacity expansion among organized manufacturers with export orientation.
- Ethylene-vinyl acetate foam adoption:Mid-sole construction in sports and casual segments is shifting from conventional rubber compounds to lighter, cost-advantaged EVA formulations.
- Tier-two city demand:Women buyers in secondary urban centers are driving volume expansion as brand distribution networks extend beyond metropolitan retail footprints.
Market Restraints
- Imported EVA granule dependence:Tariff volatility on ethylene-vinyl acetate raw materials creates input cost instability for mid-sole compounders lacking backward integration into polymer synthesis.
- Tannery effluent compliance:Uttar Pradesh State Pollution Control Board enforcement of wastewater norms is idling unorganized leather processors lacking effluent treatment infrastructure.
- Natural rubber price cycles:Mass rubber slipper margins compress during commodity upswings, pressuring price-positioned competitors against informal local makers.
Strategic Opportunities
- Orthopedic footwear intersection:CDSCO regulatory pathways for therapeutic applications create white space at the medical-device boundary for certified manufacturers.
- Gender-neutral design expansion:Canvas and synthetic unisex categories are capturing shelf space through direct-to-consumer online channels targeting younger demographics.
- Synthetic material compounding:Captive polyurethane sole production and in-house tanning capabilities offer margin defense against imported input volatility.
Industry Challenges
- IS 17043 certification timelines:BIS compulsory certification processes create working capital strain and launch delays for new product introductions.
- Skilled pattern engineering scarcity:Technical footwear design capabilities for athleisure performance specifications concentrate in metro talent pools, constraining semi-urban facility staffing.
- Legacy vulcanization asset obsolescence:Cementing and injection molding technology transitions strand capital in aging rubber processing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indian Footwear Market |
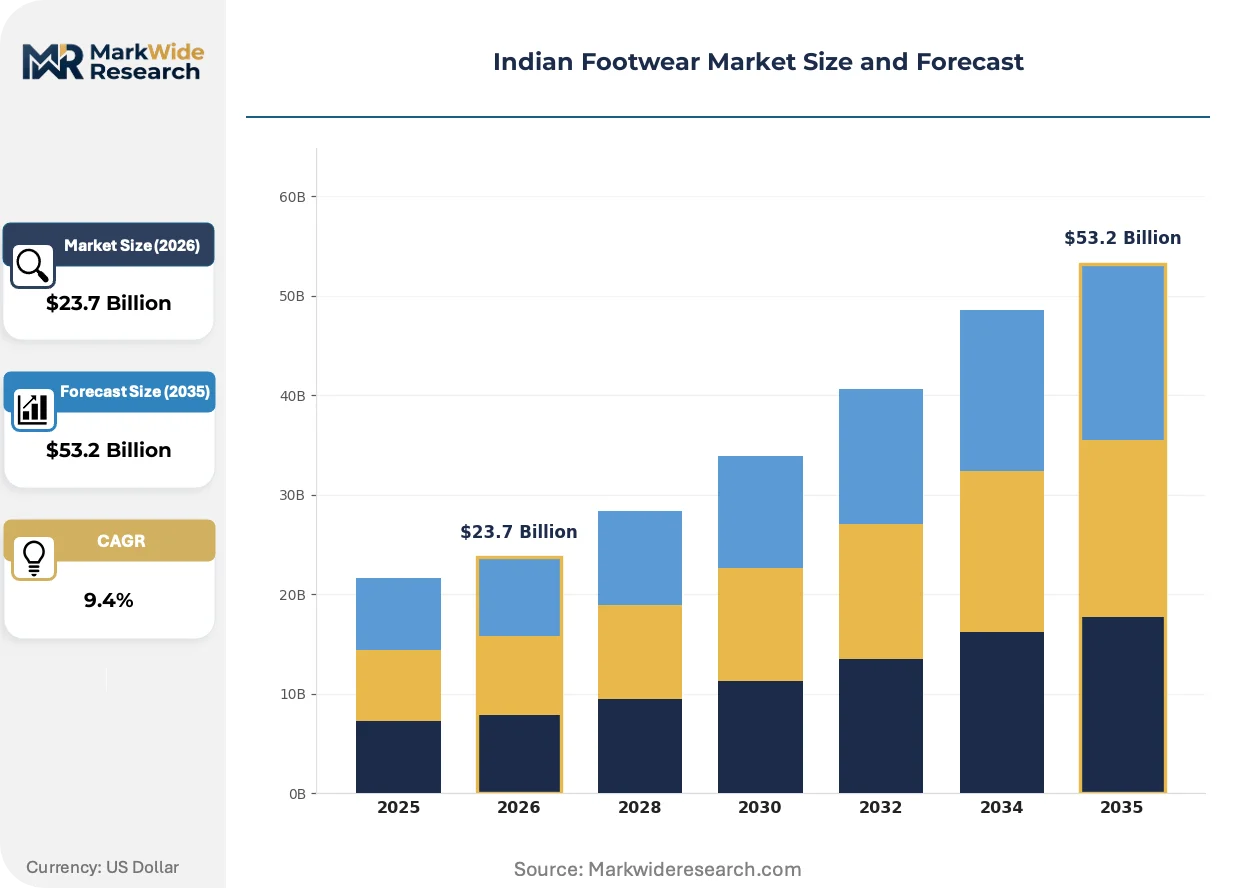
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Shoes, Sandals, Formal Footwear, Casuals Material: Leather, Synthetic, Canvas, Rubber End User: Men, Women, Kids, Unisex Distribution Channel: Online, Offline Retail, Department Stores, Supermarkets |
| Companies Covered | Redtape, Liberty Shoes, Metro Brands, Mayur Uniquoters, Khadim India, Bata India, Campus Activewear, Mirza International, Relaxo Footwears, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indian Footwear Market Emerging Trajectories
Material science convergence with regulatory compliance requirements is compressing product development cycles while reshaping procurement priorities across organized Indian footwear manufacturing.
3D knitting technology for seamless textile uppers is unifying structural and aesthetic functions previously requiring separate panel construction and stitching operations. Sports and athleisure specialists are piloting these systems for rapid style rotation. This unifying architecture is collapsing minimum order quantities and enabling micro-batch production economics previously unattainable at domestic scale.
BIS IS 17043 compulsory certification implementation is mandating testing infrastructure investments across the supplier base. Organized manufacturers with captive laboratories are absorbing compliance costs more efficiently than trading-dependent competitors. Formal and safety footwear categories face the steepest certification burden, accelerating consolidation toward integrated producers with quality control capabilities.
Direct-to-consumer channel maturation is fragmenting traditional wholesale-distributor hierarchies that historically controlled tier-two and tier-three access. Younger buyers are discovering gender-neutral and specialty designs through brand-owned digital storefronts rather than multi-brand retail. This disintermediation is most pronounced in canvas and synthetic casual segments where visual merchandising translates effectively to mobile commerce interfaces.
Indian Footwear Market Segmentation
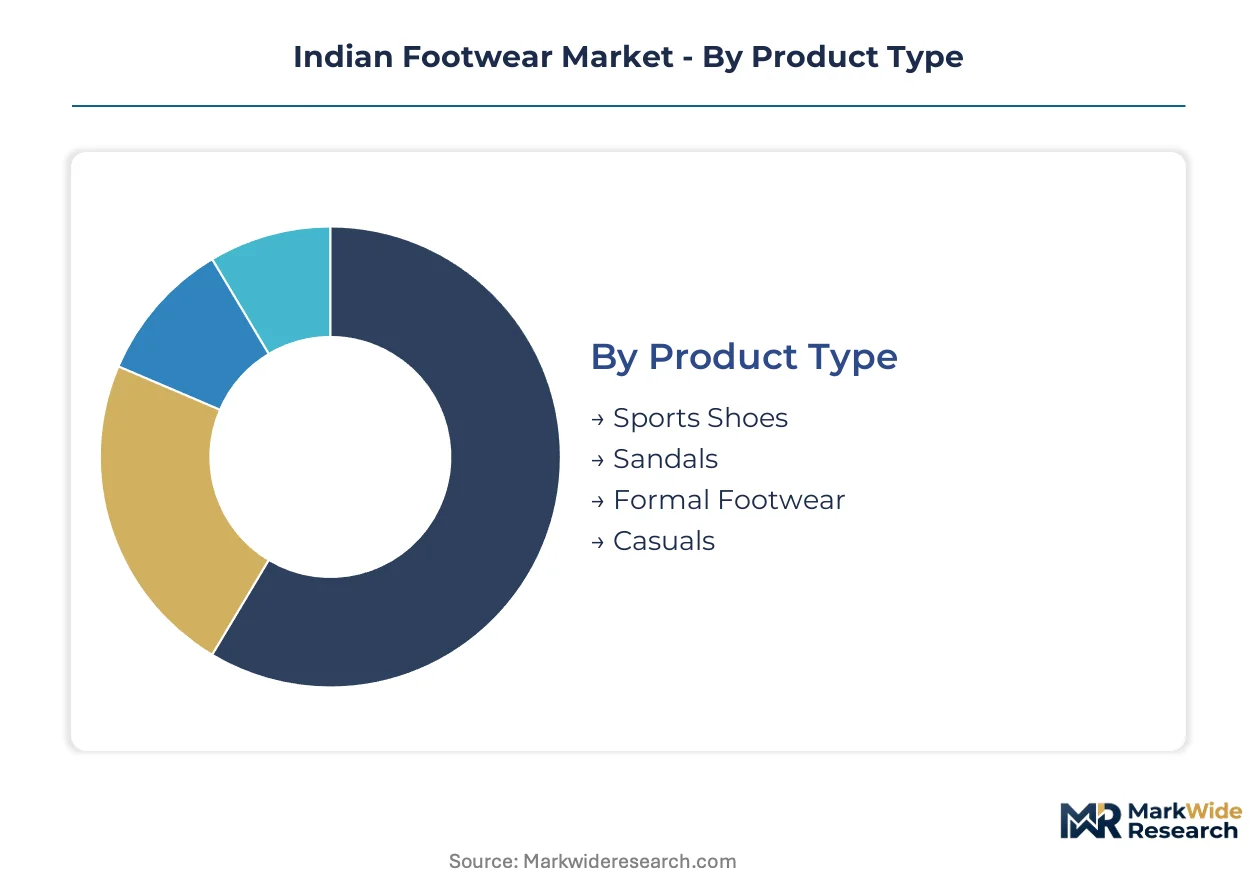
Segmentation in Indian footwear reveals how material science, channel economics, and demographic targeting intersect to create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure, shaping where organized manufacturers concentrate capital versus where unorganized players retain footholds.
Product Type:
Customization intensity varies sharply across this category, from engineered performance specifications demanding technical collaboration to standardized silhouettes permitting mass replication.
- Sports Shoes:Multi-layer constructions fuse ethylene-vinyl acetate mid-soles with engineered mesh uppers for weight reduction and impact absorption. Demand concentrates in metropolitan and tier-two urban youth segments as athleisure adoption spreads beyond gym contexts into daily wardrobes, with BIS IS 17043 certification creating compliance barriers for informal manufacturers.
- Formal Footwear:Cemented leather constructions with stacked heels and welted soles serve corporate and ceremonial occasions. Stable margin pools persist in premium leather grades despite slower volume expansion, with Uttar Pradesh's Agra-Kanpur corridor anchoring domestic tanning supply for organized producers.
- Sandals:Open-strap designs in leather, synthetic, or rubber compounds dominate mass-market summer consumption and ceremonial wear across rural and urban India.
- Casuals:Canvas and synthetic slip-ons, loafers, and moccasins bridge formal-informal boundaries through versatile styling and moderate price positioning.
Leading the category by volume: Casuals. Expanding most quickly: Sports Shoes.
Material:
Cost tier stratification dominates here, with input volatility and backward integration potential determining competitive stability.
- Leather:Full-grain and corrected-grain hides from bovine sources undergo chrome or vegetable tanning for durability and aesthetic finish. Agra and Kanpur tanneries supply organized manufacturers, though State Pollution Control Board effluent enforcement is idling unorganized processors lacking treatment infrastructure.
- Synthetic:Polyurethane and PVC compounds enable color consistency, water resistance, and lower unit costs compared to natural materials. Price-advantaged positioning drives mass-market penetration, with imported polymer granule dependence exposing margins to tariff fluctuations.
- Canvas:Cotton twill uppers with vulcanized rubber soles anchor heritage sneaker silhouettes and price-accessible casual lines.
- Rubber:Natural and synthetic rubber formulations dominate mass slipper production through injection molding and vulcanization processes, with commodity price cycles compressing margins for price-positioned competitors.
Widest margin stability: Leather. Fastest material transition: Synthetic compounds displacing natural inputs in mid-market tiers.
End User:
Customer type fragmentation reflects diverging purchase triggers across lifecycle stages and gender-specific design traditions versus emerging unisex adoption.
- Women:Heeled formal constructions, embellished ethnic designs, and fashion-forward casual silhouettes drive tier-two city volume acceleration as brand distribution extends beyond metropolitan retail footprints.
- Men:Formal leather oxfords and derby shoes retain stable corporate demand, while sports and casual categories capture style experimentation among younger demographics.
- Kids:Rapid size turnover and durability requirements favor synthetic and rubber constructions at accessible price points, with seasonal school-uniform cycles creating demand spikes.
- Unisex:Gender-neutral canvas and synthetic designs are capturing shelf space through direct-to-consumer online channels, attracting younger buyers seeking versatile styling outside traditional gendered merchandising.
Highest volume concentration: Men. Steepest expansion trajectory: Women buyers in tier-two cities.
Distribution Channel:
Channel maturity determines access economics, with digital disintermediation reshaping historical wholesale-distributor hierarchies controlling tier-two and tier-three penetration.
- Online:Brand-owned digital storefronts and marketplace platforms enable direct customer relationships, visual merchandising translation to mobile interfaces, and gender-neutral design discovery outside traditional retail constraints.
- Offline Retail:Exclusive brand outlets and multi-brand footwear chains sustain tactile evaluation for fit-sensitive categories like formal leather and sports performance constructions.
- Department Stores:Curated brand adjacencies in apparel-retail hybrids capture impulse purchases and gift-oriented buying occasions.
- Supermarkets:High-frequency foot traffic drives mass rubber slipper and basic sandal volume through grab-and-go placement adjacent to grocery baskets.
Deepest tier-three penetration: Offline Retail. Fastest channel shift: Online capturing share in canvas and synthetic casual segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Indian footwear concentrates in Uttar Pradesh's Agra-Kanpur corridor, where tannery clusters and manufacturing infrastructure anchor domestic supply. Women buyers in tier-two cities are accelerating volume expansion as brand distribution networks extend beyond metropolitan retail footprints. The PLI scheme for leather and footwear is redirecting investment toward organized producers with export orientation.
Uttar Pradesh
Women buyers in Lucknow and Kanpur drive tier-two demand acceleration for branded formal and casual segments. BIS mandates compulsory IS 17043 certification for all footwear categories, forcing compliance investments across the supplier base. The Agra-Kanpur corridor hosts India's densest concentration of leather tanneries and integrated footwear manufacturing, though State Pollution Control Board effluent enforcement is idling unorganized processors lacking treatment infrastructure.
Maharashtra
Mumbai and Pune metropolitan clusters sustain premium sports and athleisure consumption among younger demographics. CDSCO regulates medical and orthopedic footwear categories that intersect with therapeutic applications, creating compliance pathways for certified manufacturers. Thane and Nashik industrial zones concentrate synthetic material compounding and injection molding capacity for mid-sole construction.
Tamil Nadu
Chennai and Coimbatore anchor South Indian demand for rubber slippers and mass-market sandals through year-round warm climate consumption. State-level pollution control norms constrain small-scale vulcanization operations lacking emission controls. Ambur and Vaniyambadi tannery clusters supply finished leather to organized footwear producers, though effluent compliance investments favor larger integrated operators.
Haryana
Delhi-NCR spillover demand from Gurugram and Faridabad supports premium formal footwear consumption in corporate corridors. The PLI scheme's domestic value addition thresholds are accelerating capacity expansion among export-oriented manufacturers with integrated facilities. Bahadurgarh industrial area concentrates polyurethane sole production and cementing operations for organized brands.
West Bengal
Kolkata metropolitan and tier-two urban centers sustain stable demand for leather formal and ethnic footwear categories. BIS certification timelines create working capital strain for trading-dependent competitors lacking captive laboratories. Bantala leather complex represents eastern India's primary tanning and finishing concentration, with organized manufacturers absorbing compliance costs more efficiently than informal processors.
Indian Footwear Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with organized players capturing premium tiers while unorganized makers retain mass-market price positioning. The vendor base concentrates around three strategic archetypes: integrated leather producers with captive tanning, synthetic material specialists with in-house compounding, and retail-network distributors leveraging pan-India storefront density. Dominant competitive moves include backward integration into polymer synthesis to defend margins against imported EVA granule volatility, and direct-to-consumer channel expansion to disintermediate traditional wholesale hierarchies.
Within the integrated leather tier, Mirza International and Liberty Shoes exemplify producers combining captive tanning with finished goods manufacturing. Among retail-network operators, Bata India and Metro Brands anchor positions through storefront density in tier-three towns. At the mass-market synthetic end, Relaxo Footwears and Campus Activewear occupy positions defined by price-accessible positioning and sports-oriented segmentation respectively.
| Leading Market Players |
|---|
| Redtape |
| Liberty Shoes |
| Metro Brands |
| Mayur Uniquoters |
| Khadim India |
| Bata India |
| Campus Activewear |
| Mirza International |
| Relaxo Footwears |
| Others |
Supply Flow & Price Mechanics
Women buyers in tier-two cities anchor volume procurement for branded casual and formal segments, concentrating negotiating leverage with manufacturers pursuing BIS IS 17043 certification premiums. This buyer archetype's expansion beyond metropolitan retail footprints sustains three-tier pricing stratification across premium leather, standard synthetic, and economy rubber constructions.
Pricing Analysis
Volume concentration in mass rubber slippers compresses margins against unorganized local makers, while premium sports and formal leather tiers retain pricing power through BIS certification barriers and brand equity. Price differentiation rests on certification grade and captive tanning capability, with organized manufacturers commanding 15-20% premiums over trading-dependent competitors. Cost compression in synthetic mid-sole compounding intensifies as tariff volatility on imported ethylene-vinyl acetate granules feeds through input costs. Mass-market buyers exhibit highest price sensitivity, while corporate and athleisure segments absorb premium positioning with limited elasticity.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in Indian footwear, with end-of-life products typically cascading to secondary rural markets rather than formal reverse-logistics networks. Manufacturing concentration centers on India, China, and Vietnam for finished goods, while raw material dependencies encompass Brazilian natural rubber, Korean synthetic polymers, and domestic Agra-Kanpur tannery output. Single-source vulnerability in ethylene-vinyl acetate granule supply creates tariff exposure for mid-sole compounders lacking backward integration. Distribution runs through exclusive brand outlets and multi-brand chains in tier-three towns, with direct-to-consumer channels fragmenting traditional wholesale hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tannery effluent compliance investments act as the binding capacity constraint, idling unorganized processors and propping pricing for organized manufacturers with captive treatment infrastructure. This supply bottleneck sustains margin pools in leather formal and premium casual tiers despite volume competition from synthetic alternatives.
For Market Incumbents: Anticipate BIS certification timeline extensions and State Pollution Control Board enforcement intensification as regulatory threats compress competitor supply. Prioritize captive laboratory investments to absorb IS 17043 testing costs more efficiently than trading-dependent rivals, while accelerating polyurethane sole compounding integration to defend margins against imported EVA volatility. For New Entrants and Emerging Players: Tier-two women buyers in Lucknow, Kanpur, and Nagpur represent underserved demand concentration with limited organized brand penetration. Capture this white space through direct-to-consumer digital storefronts featuring gender-neutral canvas and synthetic designs, leveraging visual merchandising optimized for mobile commerce interfaces rather than traditional retail buildouts. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated leather producers with captive tanning and effluent treatment infrastructure in Uttar Pradesh's Agra-Kanpur corridor. Long-term viability hinges on export orientation qualifying for PLI scheme disbursements and domestic value addition thresholds. Monitor BIS certification completion rates among unorganized tanneries as inflection indicator for supply consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive EVA compounding insulates mid-sole margins from DGFT tariff volatility on imported granules. |
| BIS IS 17043 Certification Investment | Compulsory quality mandates create compliance moats that trading-dependent competitors cannot bridge. |
| Direct-to-Consumer Channel Expansion | Brand-owned digital storefronts disintermediate wholesale hierarchies controlling tier-two and tier-three access. |
| Effluent Treatment Infrastructure Buildout | Uttar Pradesh State Pollution Control Board enforcement idles unorganized tanneries lacking wastewater compliance. |
| 3D Knitting Technology Adoption | Seamless textile upper systems collapse minimum order quantities for rapid athleisure style rotation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across footwear brand managers, tannery operations heads, BIS certification consultants, multi-brand retail category buyers, and PLI scheme disbursement officers at the Department for Promotion of Industry and Internal Trade. Secondary validation drew from CDSCO medical device registrations, Uttar Pradesh State Pollution Control Board enforcement notices, DGFT import-export data, and BIS laboratory accreditation records. Bottom-up manufacturing capacity estimates triangulated against top-down consumption surveys across metropolitan and tier-two urban centers.
Product type, material composition, end-user demographic, and distribution channel dimensions were modeled at state-level granularity across the projection horizon. CAGRs derived from regression analysis against PLI scheme investment trajectories, BIS certification adoption curves, and synthetic material substitution elasticities in mid-sole applications. Forecast inputs incorporated ethylene-vinyl acetate import tariff schedules, natural rubber price cycles, and tannery effluent compliance cost absorption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PLI scheme renewal decisions, BIS certification timeline extensions, and tariff restructuring on Korean and Chinese polymer imports. Forecasts reflect documented assumptions on domestic value addition thresholds and export orientation requirements. Practitioners should monitor State Pollution Control Board enforcement intensity and unorganized tannery idling rates for early supply consolidation signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Tactical Footwear Market
Footwear
High Heels Footwear Market
Footwear
Equestrian Footwear Market
Footwear
Kids Barefoot Shoes Market
Footwear
Leather Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Driving Footwear Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
United States Footwear Market
Footwear
Slip on Shoes Market
Footwear
Refurbished Running Shoes Market
Footwear
Sneaker Identification Service Market
Footwear
North America Footwear Market
Footwear
PVC Footwear Market
Footwear
Tennis Shoes Market