
 Loafers Market | 2026-2036
Loafers Market Size, Share, and Industry Trends Forecast 2026-2036
Loafers Market Foresight
Corporate procurement of workplace footwear is consolidating as technology firms and financial services companies standardize business-casual dress codes across global offices. Gucci leverages its Italian manufacturing heritage to command premium positioning in leather dress loafers. Allen Edmonds anchors its competitive position through domestic production and recrafting services that extend product lifecycles. Cole Haan competes across the casual-to-dress spectrum with lightweight constructions that bridge office and travel use cases.
Loafers are slip-on shoes constructed without lacing systems, typically featuring a low heel, moccasin-style toe construction, and structural elements such as leather welting or cemented soles designed for comfort and rapid donning. Classic leather variants dominate commercial volume through heritage positioning and durability expectations, while chunky-soled casual styles capture faster growth among younger demographics prioritizing comfort aesthetics. Suede materials occupy a distinct margin pool tied to seasonal collections and limited-edition releases, whereas synthetic alternatives face structural pressure from tightening environmental compliance standards across European and North American supply chains.
REACH regulations in Europe govern chemical inputs in leather tanning and synthetic material production, directly shaping supplier qualification requirements for brands distributing across EU member states. The US Consumer Product Safety Commission and state-level frameworks such as California Proposition 65 impose parallel disclosure and material restrictions that influence product development timelines. Stakeholders must monitor evolving chemical compliance thresholds and traceability mandates to preserve market access across jurisdictions with divergent enforcement calendars.
Market Dynamics
Corporate dress-code liberalization at technology firms and financial services companies is redefining professional footwear procurement, compressing the formal-casual boundary that historically segmented loafer demand into rigid occasion-based categories.
Growth Catalysts
- REACH chemical standards:European material compliance mandates are accelerating supplier consolidation toward certified tanneries capable of traceable chromium-free processing, favoring incumbent brands with established audit relationships.
- Technology sector procurement:Business-casual standardization across software and fintech campuses is normalizing loafer-wearing in environments previously restricted to sneakers or formal oxfords.
- Portugal and Italy:Concentrated artisan manufacturing clusters in these countries provide heritage credibility and rapid sample-to-production turnaround for premium private-label programs.
Market Restraints
- Chrome-tanning input costs:Vegetable-tanning alternatives require 4-6 week processing cycles versus 24-hour chrome methods, constraining volume responsiveness during demand surges.
- Italian sole supplier concentration:Premium leather sole production clusters in Tuscany and Marche create geographic single-point vulnerability for heritage-positioned brands.
- Sneaker substitution:Allbirds, On Running, and similar comfort-tech footwear captures professional wardrobe spending among under-35 demographics prioritizing orthopedic support over leather aesthetics.
Strategic Opportunities
- India formalwear expansion:Domestic manufacturing incentives and rising white-collar employment in Bangalore and Mumbai create white space for mid-premium positioning below European import price points.
- Recrafting service monetization:Resole and refurbishment programs transform one-time transactions into recurring revenue streams while reinforcing sustainability credentials.
- Direct-to-consumer channel maturation:Owned e-commerce and showroom networks bypass wholesale margin dilution while capturing first-party fit-preference data for made-to-order pilots.
Industry Challenges
- Last-making artisan scarcity:Shoemaking trade schools in England and Italy graduate fewer wooden-last carvers annually than replacement demand requires, compressing new product development timelines.
- California Proposition 65 compliance:Leather tanning chemical disclosure requirements impose labeling complexity and liability exposure for brands distributing through West Coast retail partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loafers Market |
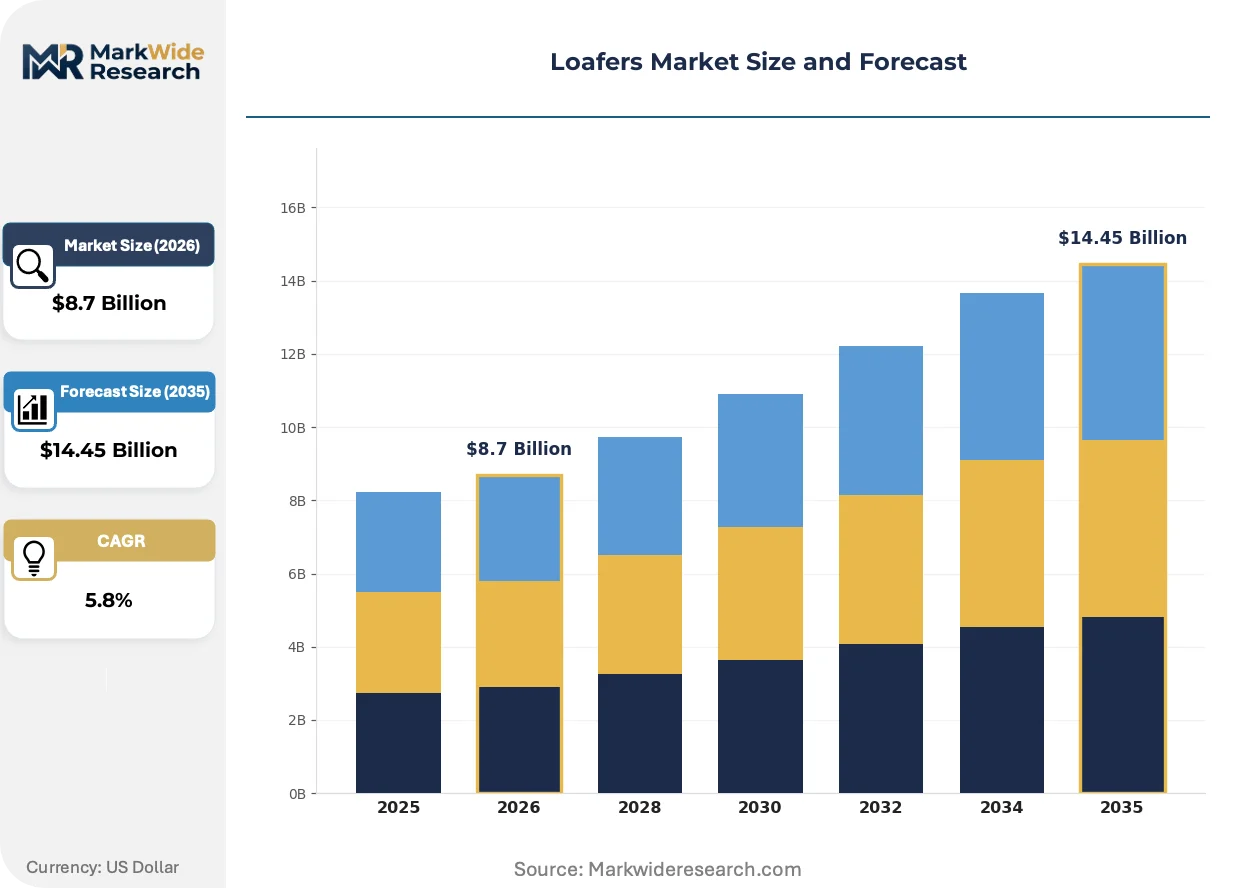
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Casual, Dressy, Chunky Material: Leather, Suede, Canvas, Synthetic Customer Type: Men, Women, Children, Unisex Closure Type: Slip-On, Loafer, Buckle, Moccasin |
| Companies Covered | Gucci, Allen Edmonds, Cole Haan, Rockport, Church & Co, Tod's, Clarks, Johnston & Murphy, Salvatore Ferragamo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loafers Market Shifts & Advancements
Material science convergence and regulatory transparency mandates are compressing traditional boundaries between heritage craftsmanship and industrial efficiency, forcing simultaneous investment in artisan credibility and scalable compliance infrastructure.
Biobased polyurethane foam midsole technology is unifying comfort engineering with leather upper construction, eliminating the structural compromise between formal aesthetics and all-day wearability. Technology sector buyers in Seattle and Austin are specifying this hybrid construction for campus-wide uniform programs. The technology is unifying previously separate supply chains, requiring tanneries to coordinate with athletic-footwear foam specialists.
REACH Annex XVII restrictions on chromium VI compounds are forcing tannery supplier requalification across EU member states. Brands must maintain parallel material streams for European and non-European production lots. Italian luxury houses with captive tannery operations absorb compliance costs more readily than brands dependent on third-party leather merchants.
Corporate uniform allowance consolidation is displacing individual expense reimbursement across financial services and consulting employers. Employees receive annual footwear credits redeemable through approved vendor portals rather than submitting receipts. This procurement compression is most visible in London and New York, where major accounting and law firms have centralized vendor selection to reduce administrative overhead.
Loafers Market Segmentation
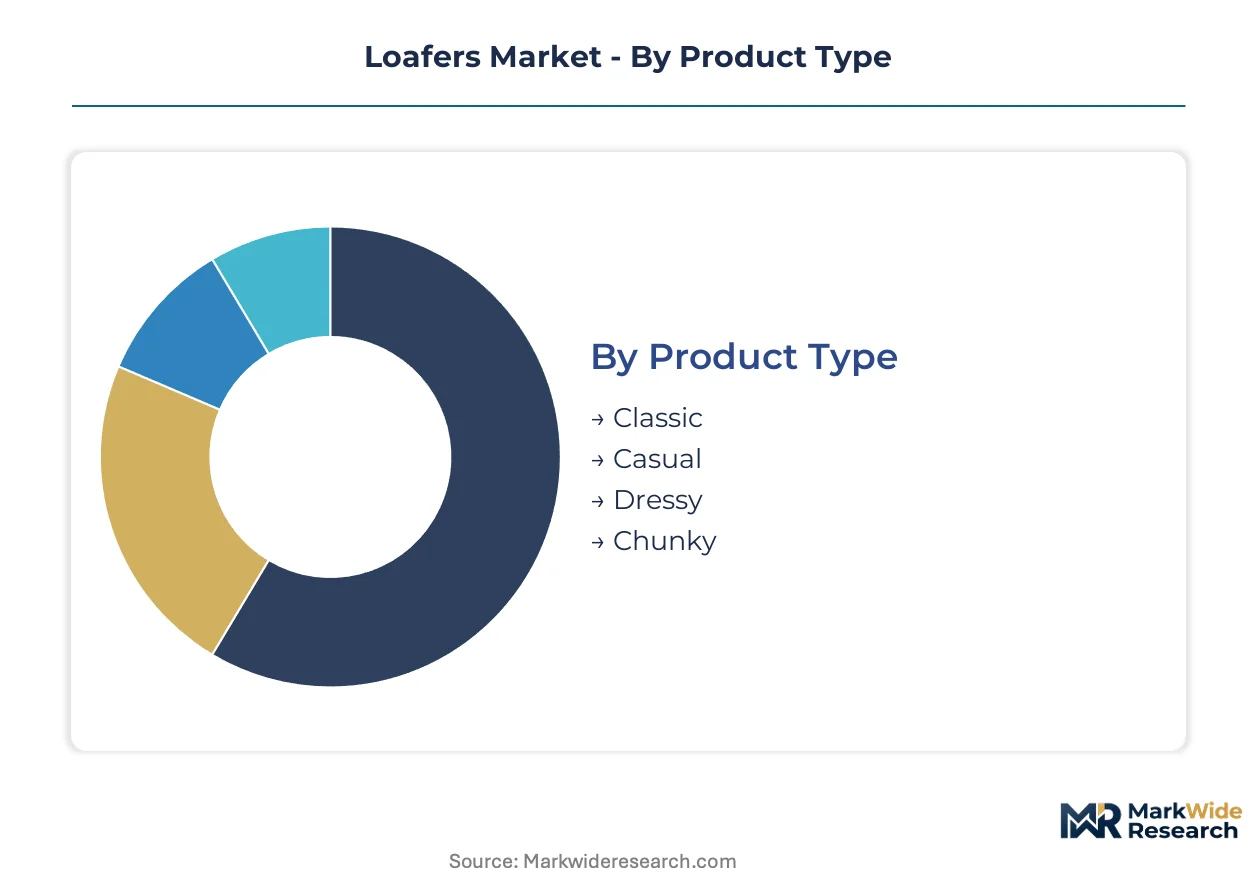
Loafer purchasing decisions hinge on occasion specificity, material durability expectations, and workplace dress-code requirements. Each segmentation dimension reveals distinct margin structures and supply chain configurations that shape competitive positioning across price tiers.
Product Type:
Buyer selection prioritizes occasion versatility and workplace appropriateness over pure aesthetic preference.
- Classic:Low-profile silhouettes with leather welting and minimal ornamentation dominate professional wardrobe procurement. Financial services and technology sector uniform programs in New York and London specify this construction for daily office wear, driving consistent replenishment cycles.
- Dressy:Refined lasts with elongated toes and polished finishes command premium positioning through Italian manufacturing heritage. Tanneries in Tuscany supply certified chromium-free leather to brands distributing under REACH compliance mandates.
- Casual:Soft unstructured uppers with rubber soles bridge weekend and remote-work environments.
- Chunky:Exaggerated lug soles and platform midsoles attract under-35 demographics prioritizing comfort aesthetics over traditional formalwear cues.
Volume sits with Classic; growth tilts toward Chunky.
Material:
Raw material selection determines regulatory compliance pathways and margin durability across geographic markets.
- Leather:Full-grain and top-grain hides processed through vegetable or chrome tanning supply heritage-positioned brands. REACH Annex XVII restrictions on chromium VI compounds force parallel material streams for European versus non-European production lots.
- Suede:Napped surface treatments from calfskin and goatskin occupy seasonal collection strategies with higher margin profiles and limited-edition release cadences.
- Canvas:Cotton and linen uppers with cemented construction reduce unit costs for entry-tier positioning.
- Synthetic:Polyurethane and microfiber alternatives face structural pressure from California Proposition 65 disclosure requirements and tightening environmental compliance standards.
Leather commands absolute volume; Suede delivers margin expansion.
Customer Type:
Demographic targeting shapes product development timelines and marketing channel allocation.
- Men:Conservative color palettes and traditional lasts dominate corporate procurement through established heritage brands.
- Women:Expanded width offerings and heel-height variations capture professional wardrobe spending across consulting and legal sectors.
- Children:Scaled-down lasts with adjustable fit systems address school uniform requirements and rapid size turnover.
- Unisex:Gender-neutral sizing and styling reduces SKU complexity for direct-to-consumer challengers targeting younger demographics.
Men's segment anchors revenue; Unisex positioning climbs fastest.
Closure Type:
Construction method defines manufacturing complexity and price-positioning flexibility.
- Slip-On:Elasticized gussets and minimal structural elements enable rapid production scaling for volume-oriented private-label programs.
- Loafer:Strap-and-saddle constructions with metal bit or tassel detailing require specialized last-making and hand-finishing capabilities concentrated in Portuguese and Italian manufacturing clusters.
- Buckle:Adjustable monk-strap variations extend wearability across foot-width variations.
- Moccasin:Hand-sewn toe construction with wraparound leather soles preserves artisan credibility for premium heritage positioning.
Slip-On construction dominates unit volume; Loafer detailing captures premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional wardrobe spending concentrates in the United States, where technology sector procurement and financial services uniform programs drive sustained replenishment cycles for leather dress footwear. REACH compliance mandates in Europe and California's Proposition 65 disclosure requirements reshape supplier qualification across major demand centers.
United States
Corporate dress-code liberalization at technology firms in Seattle and Austin normalizes loafer adoption in environments previously restricted to sneakers or formal oxfords. The US Consumer Product Safety Commission and California Proposition 65 impose parallel material restrictions that influence product development timelines. New York and Boston anchor financial services procurement, where major accounting and law firms have centralized vendor selection to reduce administrative overhead.
Italy
Italian manufacturing heritage commands premium positioning in leather dress loafers through concentrated artisan clusters in Tuscany and Marche. REACH Annex XVII restrictions on chromium VI compounds force tannery supplier requalification across EU member states. Luxury houses with captive tannery operations in Tuscany absorb compliance costs more readily than brands dependent on third-party leather merchants.
United Kingdom
London-based financial services and consulting employers drive corporate uniform allowance consolidation, displacing individual expense reimbursement with centralized vendor portals. ECHA enforcement of REACH chemical standards governs material inputs in leather tanning and synthetic alternatives. Northamptonshire preserves historic shoemaking craft, though trade schools graduate fewer wooden-last carvers annually than replacement demand requires.
India
Rising white-collar employment in Bangalore and Mumbai creates white space for mid-premium positioning below European import price points. BIS certification requirements and domestic manufacturing incentives under the PLI scheme reshape local production economics. Artisan manufacturing clusters in Agra and Kanpur supply scaled production capacity for private-label programs targeting formalwear expansion.
Portugal
Concentrated manufacturing clusters provide heritage credibility and rapid sample-to-production turnaround for premium private-label programs. EU Green Deal sustainability mandates and CSRD reporting requirements pressure tannery energy intensity and chemical traceability. Porto and Guimarães anchor footwear production networks that serve as alternative sourcing nodes to Italian supply chains.
Loafers Market Competitive Landscape
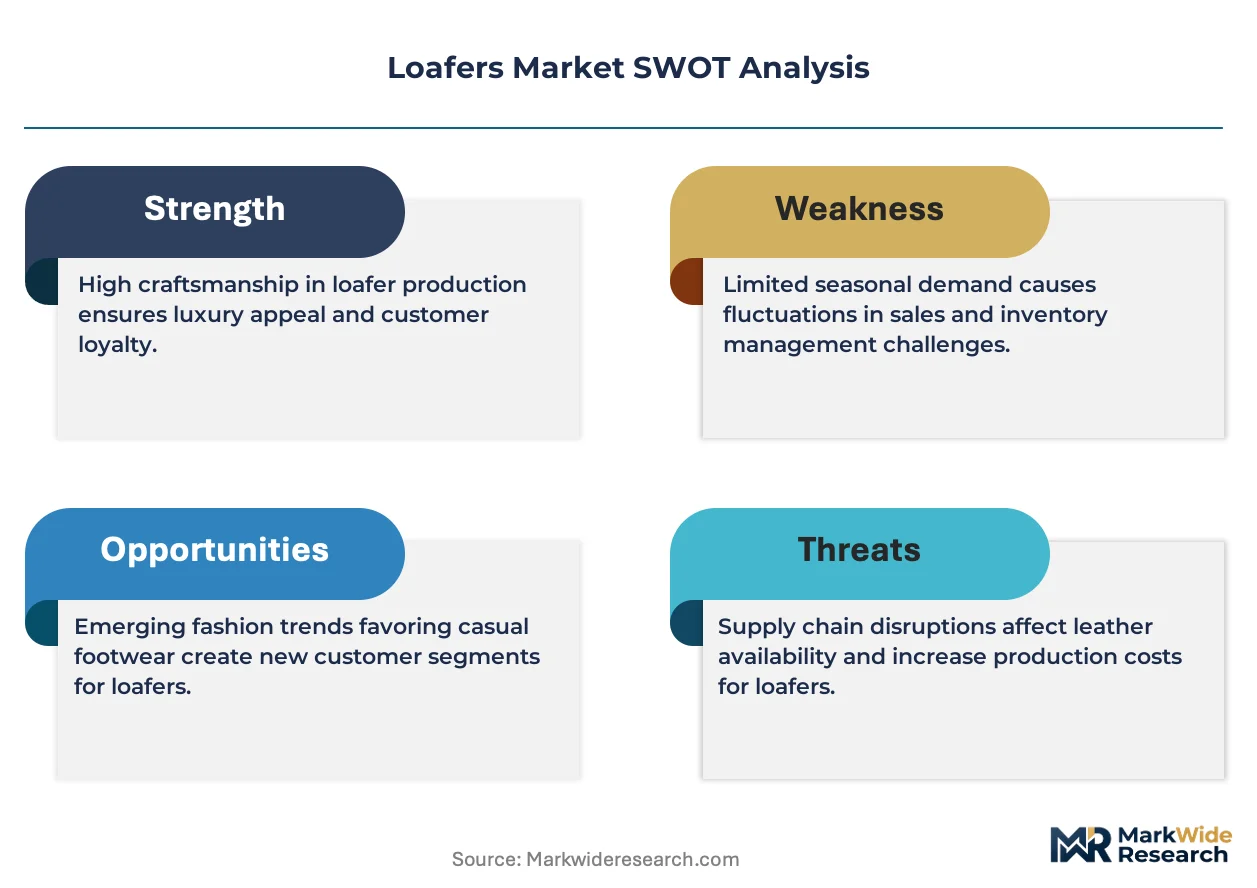
Italian producers anchor the premium heritage tier; Portuguese specialists hold the responsive mid-premium segment. The vendor base stratifies across three tiers: luxury houses with captive tannery operations, heritage brands emphasizing domestic production and recrafting services, and direct-to-consumer challengers leveraging owned e-commerce channels. Incumbents defend position through backward integration into sole manufacturing and refurbishment program monetization. New entrants bypass wholesale margin dilution through showroom networks and made-to-order pilots.
Within the heritage-brand tier, Allen Edmonds exemplifies domestic production anchoring and recrafting service infrastructure. Cole Haan occupies a position bridging casual-to-dress construction with lightweight engineering. Among Italian luxury houses, Gucci represents manufacturing heritage leverage and premium leather sourcing control. These three names illustrate the competitive archetypes—domestic heritage, hybrid engineering, and luxury verticalization—shaping procurement decisions across corporate uniform programs and individual professional wardrobes.
| Leading Market Players |
|---|
| Gucci |
| Allen Edmonds |
| Cole Haan |
| Rockport |
| Church & Co |
| Tod's |
| Clarks |
| Johnston & Murphy |
| Salvatore Ferragamo |
| Others |
Supply & Pricing Matrix
Corporate uniform procurement programs at financial services and technology firms concentrate buying power into annual vendor negotiations, compressing margins for heritage brands while elevating direct-to-consumer challengers with transparent pricing models. This buyer concentration forces suppliers to absorb REACH compliance costs or risk exclusion from approved vendor portals in London and New York.
Pricing Analysis
Volume concentrates in classic leather constructions with modest margins, while suede seasonal releases and limited-edition chunky styles capture margin expansion through scarcity positioning. Three-tier pricing structure across premium, standard, and economy levels separates Italian heritage positioning from Portuguese mid-premium responsiveness and Asian private-label entry tiers. Price differentiation rests on certification grade—chromium-free REACH compliance commands measurable premiums—and brand heritage credibility. Pricing pressure stems from sneaker substitution among under-35 demographics, eroding leather footwear's share of professional wardrobe spending. Entry-tier buyers exhibit highest price sensitivity, while corporate procurement officers prioritize total cost of ownership including recrafting service eligibility.
Supply Chain Analysis
Direct-to-retail channels handle volume-oriented private-label programs, while heritage brands maintain controlled distribution through owned e-commerce and selective wholesale partnerships. Manufacturing concentrates in Italy, Portugal, and India, with Tuscan tanneries supplying certified leather to REACH-compliant brands and Agra clusters serving cost-optimized production. Raw material dependencies include full-grain hides from European and North American processors, chromium-free tanning agents, and biobased polyurethane foam midsoles from athletic-footwear specialists. Single-source vulnerability concentrates in Italian sole manufacturing clusters in Tuscany and Marche, where artisan capacity constraints compress new product development timelines. Distribution runs through centralized corporate vendor portals in financial services and technology sectors, displacing traditional retail intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Last-making artisan scarcity constrains new product development timelines, propping pricing power for incumbent brands with captive last libraries and established Portuguese or Italian manufacturing relationships.
For Market Incumbents: Anchor competitive position through backward integration into captive tannery operations or exclusive sole supplier partnerships, mitigating geographic single-point vulnerability in Italian manufacturing clusters. Invest in recrafting service infrastructure to transform one-time transactions into recurring revenue streams while reinforcing sustainability credentials against sneaker substitution threats from Allbirds and On Running. For New Entrants and Emerging Players: Technology sector procurement officers in Seattle and Austin represent an underserved buyer archetype seeking hybrid comfort-formal constructions for campus-wide uniform programs. Bypass wholesale margin dilution through owned e-commerce and showroom networks, capturing first-party fit-preference data for made-to-order pilots targeting under-35 demographics prioritizing comfort aesthetics. For Investors and Strategic Acquirers: The window for entry favors vertically integrated Portuguese specialists with established REACH audit relationships and rapid sample-to-production turnaround capabilities. Monitor ECHA enforcement calendars and California Proposition 65 disclosure requirement expansions as inflection indicators for compliance cost absorption capacity across the vendor base.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tannery Acquisition | REACH Annex XVII compliance costs concentrate in third-party leather merchants, favoring houses with in-house tanning. |
| Recrafting Service Launch | Allen Edmonds demonstrates how resole programs transform transactions into recurring revenue with sustainability credentials. |
| Direct-to-Consumer Channel Buildout | Owned e-commerce bypasses wholesale margin dilution while capturing fit-preference data for customization. |
| Biobased Midsole Integration | Technology sector buyers in Austin and Seattle specify hybrid comfort-formal constructions for campus programs. |
| Portuguese Manufacturing Partnership | Porto and Guimarães clusters offer heritage credibility with faster turnaround than Italian alternatives. |
Research Methodology
Multi-period observation of corporate dress-code liberalization patterns, REACH enforcement calendars, and artisan graduation rates from English and Italian trade schools anchored the trend analysis, supplemented by interviews with brand managers at heritage footwear houses, procurement officers at financial services and technology firms, tannery technical directors, and direct-to-consumer channel heads. Secondary validation drew from ECHA regulatory filings, US Consumer Product Safety Commission guidance documents, Italian industrial association production statistics, and customs trade data. Bottom-up segment sizing triangulated against top-down macroeconomic spending indicators across professional wardrobe categories.
Input-output matrices mapped leather tanning capacity, last-making artisan supply, and corporate uniform program procurement volumes against price-positioning tiers across the analysis window. Segmentation dimensions modeled include product type, material certification grade, customer demographic, and closure construction complexity. CAGRs derived from regression analysis of historical replenishment cycles and projected white-collar employment growth in target metropolitan areas. Industry-specific forecast inputs incorporated REACH Annex XVII amendment timelines and California Proposition 65 disclosure expansion patterns.
Revisions become necessary when ECHA accelerates chromium VI compound restriction enforcement, when California expands Proposition 65 labeling requirements to additional tanning agents, or when sneaker substitution rates exceed modeled thresholds among under-35 demographics. Forecasts reflect documented assumptions regarding artisan training program expansion and corporate uniform allowance consolidation trajectories. Periodic stress-testing of base assumptions against tannery supplier requalification success rates and direct-to-consumer customer acquisition cost trends is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
E-Commerce Footwear Market
Footwear
Refurbished Running Shoes Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Global Footwear Market
Footwear
Cowboy Boots Market
Footwear
US Slip Resistant Shoes Market
Footwear
Custom Shoes Market
Footwear
Golf Footwear Market
Footwear
Men Formal Shoe Market
Footwear
Cowgirl Boots Market
Footwear
Winter Footwear Market
Footwear
Dance Shoes Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Ankle Boots Market
Footwear
Tactical Footwear Market