
 Tactical Boots Market | 2026-2036
Tactical Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Boots Market Analytics
Law enforcement procurement is expanding faster than military contracting as municipal agencies prioritize officer wellness and shift-duration comfort. Danner leverages domestic manufacturing scale to anchor supply contracts with federal agencies. Belleville Boot Company specializes in Berry Amendment-compliant production for Department of Defense requirements. Wolverine World Wide sustains broad distribution reach across commercial and institutional channels.
Tactical boots are ankle-to-mid-calf footwear engineered for load-bearing mobility, incorporating vulcanized rubber outsoles, ethylene-vinyl acetate midsoles, and breathable moisture-barrier membranes to prevent immersion foot and reduce metatarsal stress during extended wear. Combat boots retain the largest revenue share within product type segmentation due to entrenched military specification contracts, while lightweight boots are gaining fastest in law enforcement and private security applications where patrol-vehicle egress speed matters. Leather dominates material segmentation by value, though synthetic blends are capturing share in tropical and maritime deployments where dry-time and mold resistance outweigh traditional durability premiums.
Federal procurement officers reference Berry Amendment compliance and ASTM F2413 protective footwear standards when evaluating vendor qualification. The National Institute of Justice maintains testing protocols that shape product development roadmaps for domestic suppliers. Stakeholders must monitor evolving load-carriage ergonomics research and anticipate specification revisions that favor hybrid constructions over legacy all-leather designs.
Market Dynamics
The tactical boots market pivots on composite material substitution eroding leather's century-long dominance, as procurement officers rewrite specifications around ASTM F2413-18 protective standards that favor hybrid constructions over traditional builds.
Growth Catalysts
- ASTM F2413-18 Revision:Updated protective footwear standards now explicitly recognize composite toe-cap technologies, accelerating specification rewrites across municipal police departments and federal agencies in the United States.
- Officer Wellness Mandates:Law enforcement agencies prioritize shift-duration comfort and load-bearing ergonomics, expanding procurement budgets for advanced midsole technologies that reduce metatarsal stress during extended patrols.
- Gore-Tex Membrane Adoption:Breathable moisture-barrier laminates are displacing untreated leather in tropical and maritime deployment specifications, opening replacement cycles in coastal security units and naval expeditionary forces.
Market Restraints
- Petroleum-Derived Synthetic Volatility:Ethylene-vinyl acetate midsoles and vulcanized rubber outsoles face input cost pressure from crude oil price swings, compressing margin structures for manufacturers without backward integration into polymer compounding.
- Berry Amendment Compliance Concentration:Domestic sourcing requirements for Department of Defense contracts limit supplier pools to qualified U.S. manufacturers, creating bottlenecks during surge procurement periods.
- Legacy Equipment Interoperability:All-leather boot designs retain entrenched specification lock-in across certain military maintenance contracts, slowing hybrid construction adoption despite performance advantages.
Strategic Opportunities
- Private Security Expansion:Corporate campus protection and critical infrastructure guarding units in Texas and California represent underpenetrated demand for lightweight patrol-optimized designs emphasizing vehicle egress speed.
- NIJ Testing Protocol Alignment:National Institute of Justice certification pathways for law enforcement footwear create regulatory tailwinds for domestic suppliers investing in accredited testing facilities.
- Direct-to-Agency Digital Channels:Municipal procurement platforms are consolidating vendor access, enabling manufacturers to bypass traditional distribution markups and capture institutional margin.
Industry Challenges
- Composite Manufacturing Talent Scarcity:Specialized technicians for carbon-fiber toe-cap molding and membrane lamination remain concentrated in aerospace and automotive supply chains, forcing footwear producers to compete for limited skilled labor pools.
- Multi-Standard Certification Timelines:Simultaneous pursuit of Berry Amendment compliance, ASTM F2413 certification, and NIJ testing creates 18-24 month product qualification cycles that delay revenue recognition on R&D investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Boots Market |
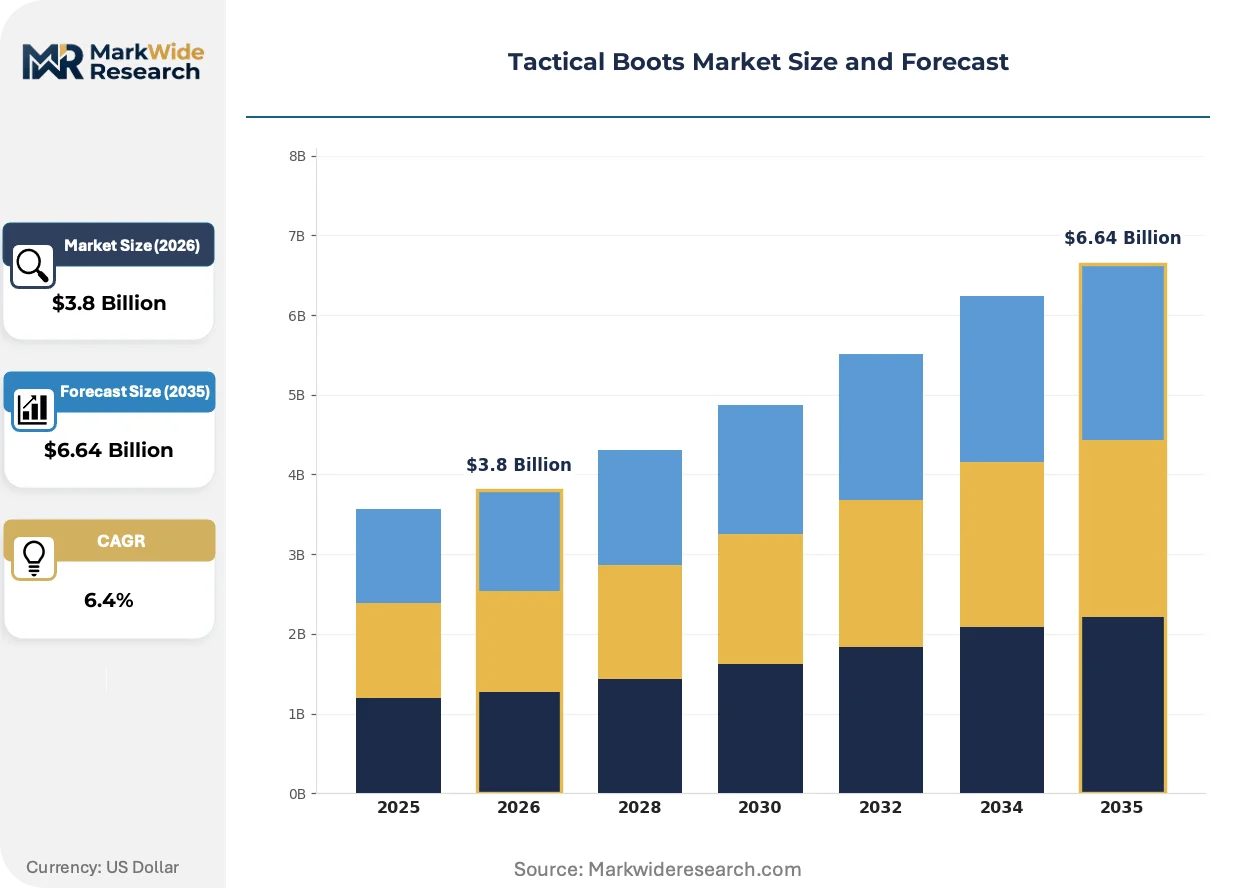
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combat Boots, Lightweight Boots, Waterproof Boots, Desert Boots Material: Leather, Nylon, Canvas, Synthetic End User: Military, Law Enforcement, Security Personnel, Outdoor Enthusiasts Closure Type: Lace-Up, Zipper, Slip-On, Buckle |
| Companies Covered | 5.11 Tactical, Under Armour, Bates Footwear, Danner, Belleville Boot Company, Wolverine World Wide, LaCrosse Footwear, VF Corporation, Magnum Boots International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Boots Market Evolving Landscape
Material science convergence with biometric load-analysis is redefining how tactical footwear gets specified, purchased, and worn across institutional and commercial channels.
Ethylene-vinyl acetate formulations with tuned density gradients are integrating into midsole architectures to distribute ground reaction forces across the plantar surface. Specialized law enforcement units in the United States are specifying these constructions for officers exceeding eight-hour standing patrols. The technology is integrating with orthotic-compatible lasts that accommodate custom insole prescriptions, compressing the distinction between medical-grade and occupational footwear categories.
REACH restrictions on per- and polyfluoroalkyl substances are compelling European suppliers to reformulate durable water-repellent chemistries applied to boot uppers. Industrial consequences include accelerated R&D timelines and qualification costs for membrane laminate partners serving NATO procurement frameworks. Combat boot specifications for expeditionary forces stationed in Germany and Belgium are most affected, with vendors responding through fluorine-free alternative submissions to the ECHA.
Agency-level consolidated purchasing is concentrating buyer power among metropolitan police departments and federal bureau procurement offices. Traditional distributor networks serving individual precincts are losing share to centralized state-contract vehicles and cooperative purchasing alliances. California and New York municipal procurement platforms exemplify this concentration, where multi-year blanket purchase agreements now lock in sole-source relationships with qualified domestic manufacturers.
Tactical Boots Market Segmentation
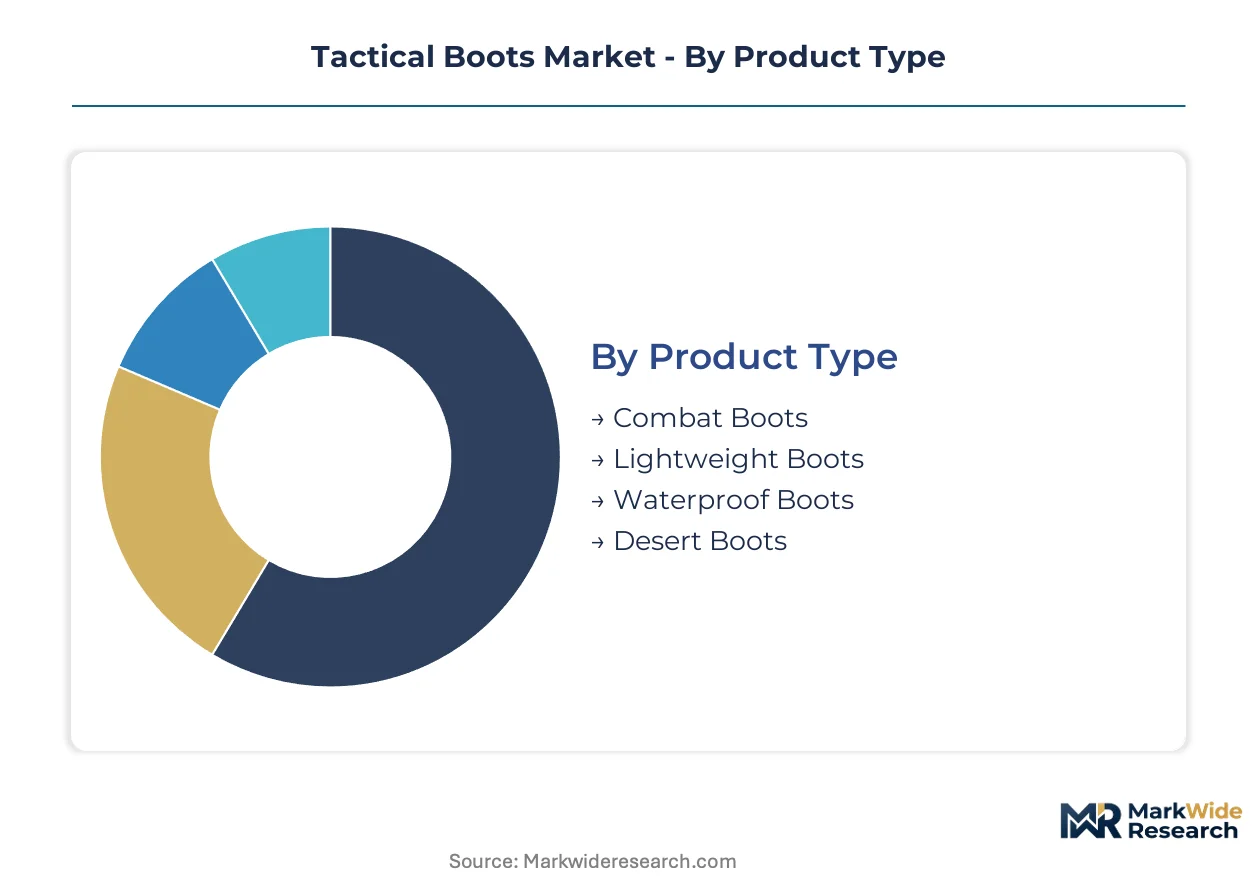
Procurement specification fragmentation across federal, state, and municipal tiers creates distinct demand pockets within tactical footwear. Each segment carries unique certification burdens and replacement-cycle dynamics that reshape supplier prioritization.
Product Type:
Supply concentration tilts toward specification-heavy institutional contracts, with military-grade designs anchoring volume while lighter patrol variants capture expansion.
- Combat Boots:Full-grain leather uppers with vulcanized rubber outsoles and steel or composite toe protection meet MIL-SPEC requirements for expeditionary forces. United States Department of Defense procurement sustains multi-year blanket agreements with Berry Amendment-compliant domestic manufacturers, though specification lock-in slows composite material adoption despite ergonomic advantages.
- Lightweight Boots:Ethylene-vinyl acetate midsoles and synthetic upper constructions reduce load burden for officers exceeding eight-hour patrol shifts. Municipal police departments in California and Texas prioritize these designs for vehicle-egress speed and shift-duration comfort, expanding procurement faster than traditional military contracting channels.
- Waterproof Boots:Gore-Tex membrane laminates prevent immersion foot in maritime and tropical deployments.
- Desert Boots:Suede and canvas hybrids optimize breathability for arid climate expeditionary forces.
Today's leader: Combat Boots. Tomorrow's challenger: Lightweight Boots.
Material:
Cost tier stratification separates premium full-grain constructions from synthetic alternatives competing on dry-time and mold resistance.
- Leather:Traditional full-grain and nubuck constructions retain dominance in value terms due to entrenched durability perceptions and legacy specification requirements. ASTM F2413-18 compliance pathways favor leather for federal procurement, though REACH restrictions in Europe are accelerating fluorine-free water-repellent formulation costs.
- Synthetic:Microfiber and engineered textile blends capture share in coastal security units and naval expeditionary forces where rapid dry-time outweighs abrasion resistance premiums. ECHA submissions for PFAS-free durable water-repellent chemistries are compressing margin structures for laminate partners serving NATO frameworks.
- Nylon:Cordura and ballistic nylon reinforcements reduce weight in hybrid upper constructions.
- Canvas:Cotton-duck and waxed canvas variants serve cost-sensitive commercial channels and ceremonial units.
Leather commands institutional budgets. Synthetic materials are climbing the fastest in tropical deployment specifications.
End User:
Application maturity diverges sharply between entrenched military maintenance cycles and expanding law enforcement wellness mandates.
- Military:Entrenched specification lock-in across Army, Marine Corps, and Air Force contracts sustains replacement cycles measured in fiscal years rather than calendar quarters. Berry Amendment compliance requirements limit qualified supplier pools to domestic manufacturers with proven scale, creating procurement bottlenecks during surge periods.
- Law Enforcement:Officer wellness mandates and shift-ergonomics research are accelerating midsole technology procurement faster than traditional equipment refresh timelines. NIJ testing protocol alignment creates regulatory tailwinds for domestic suppliers investing in accredited certification facilities.
- Security Personnel:Private campus protection and critical infrastructure guarding units in Texas and California represent underpenetrated demand for patrol-optimized designs.
- Outdoor Enthusiasts:Commercial channels serve hunting, hiking, and tactical training applications with reduced certification burdens.
Military contracts anchor volume stability. Law Enforcement procurement is expanding most quickly on wellness-driven specification rewrites.
Closure Type:
Customer type preferences split between institutional standardization and individual fit customization.
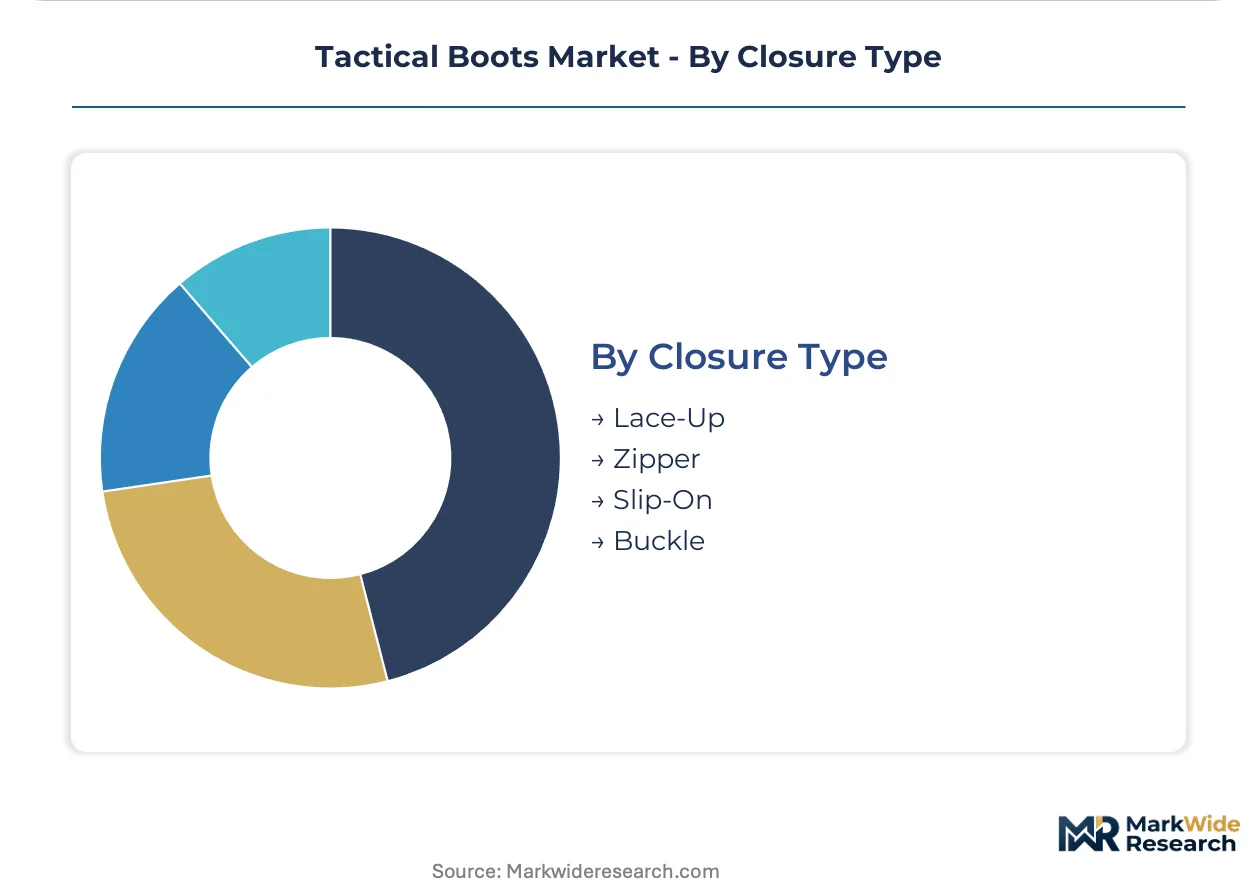
- Lace-Up:Traditional eyelet and speed-lace configurations dominate institutional procurement due to adjustable fit across varying foot volumes and orthotic accommodation. United States federal agencies specify lace-up designs exclusively for field deployment, creating specification inertia despite zipper convenience advantages.
- Zipper:YKK and proprietary side-zip constructions enable rapid donning for emergency response units and private security details. California municipal SWAT procurement is piloting zippered variants for vehicle-egress scenarios, though durability concerns limit specification expansion.
- Slip-On:Elastic gore and pull-tab designs serve administrative and ceremonial applications with minimal adjustment requirements.
- Buckle:Rigger-style and quick-release buckles appear in specialized mountaineering and rescue applications.
Lace-Up retains institutional lock-in. Zipper variants are gaining fastest in specialized response unit trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with streamlined compliance pathways for composite material certification. The United States maintains specification authority through Berry Amendment mandates, while European REACH restrictions on perfluorinated compounds accelerate reformulation costs for membrane suppliers serving NATO frameworks.
United States
Federal defense spending and municipal police modernization sustain replacement cycles across military and law enforcement channels. The National Institute of Justice maintains testing protocols that shape product development roadmaps for domestic suppliers. Berry Amendment-compliant manufacturers cluster in the Pacific Northwest and Midwest, where established leatherworking infrastructure supports hybrid construction transitions.
Germany
Expeditionary forces stationed in Germany and Belgium drive demand for REACH-compliant membrane laminates as ECHA restrictions on PFAS compounds accelerate. The country's national chemical regulator enforces fluorine-free durable water-repellent formulation requirements. Industrial concentration centers on Bavaria and Baden-Württemberg, where automotive composite expertise cross-pollinates into footwear manufacturing.
United Kingdom
Ministry of Defence procurement maintains specification continuity for expeditionary combat boots despite post-Brexit regulatory divergence from EU frameworks. The country's national standards body continues aligning with ASTM protective footwear benchmarks. Manufacturing presence concentrates in the Midlands and North England, where heritage leatherworking capabilities integrate with modern composite lamination.
China
Domestic security force expansion and export-oriented contract manufacturing sustain dual-track production capacity. The Ministry of Industry and Information Technology oversees GB standards alignment for protective footwear entering institutional channels. Yangtze River Delta industrial clusters specialize in ethylene-vinyl acetate midsole compounding and vulcanized rubber outsole production for global brands.
India
Paramilitary modernization and state police force upgrades drive procurement for tropical-deployment specifications emphasizing dry-time performance. The Bureau of Indian Standards maintains certification pathways for protective footwear serving defense and internal security applications. Tamil Nadu and Maharashtra host emerging manufacturing clusters where leatherworking heritage intersects with synthetic material processing investments.
Tactical Boots Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement favoring established domestic names while commercial channels accommodate private-label entrants. Market structure tilts toward moderate concentration at the premium tier, where Berry Amendment compliance and multi-standard certification create qualification barriers. Three archetypes dominate: heritage military suppliers with federal contract lock-in, diversified footwear conglomerates leveraging cross-brand manufacturing scale, and technical specialists commercializing aerospace-derived composite processes. Competitive moves center on backward integration into polymer compounding and strategic partnerships with membrane technology licensors.
Within the heritage supplier tier, Danner and Belleville Boot Company anchor positions through sustained federal agency relationships, exemplifying how domestic manufacturing scale secures specification-heavy procurement vehicles. Wolverine World Wide occupies a diversified position spanning institutional and commercial channels through portfolio breadth. These three entities represent distinct strategic postures: pure-play defense specialization, diversified multi-brand scale, and hybrid institutional-commercial reach.
| Leading Market Players |
|---|
| 5.11 Tactical |
| Under Armour |
| Bates Footwear |
| Danner |
| Belleville Boot Company |
| Wolverine World Wide |
| LaCrosse Footwear |
| VF Corporation |
| Magnum Boots International |
| Others |
Value Network & Pricing Analysis
Federal agency procurement officers anchor pricing power through multi-year blanket purchase agreements that compress distributor margins and lock in volume discounts for Berry Amendment-compliant domestic manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies according to certification grade, with ASTM F2413-18 and NIJ testing compliance commanding substantial premiums over commercial-grade alternatives.
Pricing Analysis
Direct-to-agency digital channels are displacing traditional distributor markups as municipal procurement platforms consolidate vendor access. Price differentiation hinges on certification level and volume scale, with federal contracts securing lowest unit economics while private security buyers absorb higher per-unit costs. Cost compression in synthetic material tiers is intensifying because petroleum-derived input volatility erodes margin structures for manufacturers lacking backward integration. Municipal police departments exhibit highest price sensitivity due to constrained annual equipment budgets, whereas Department of Defense procurement demonstrates lowest sensitivity given specification mandates.
Supply Chain Analysis
Ocean freight and domestic trucking costs for vulcanized rubber outsoles and ethylene-vinyl acetate midsole compounds feed directly into landed cost calculations for finished goods. Manufacturing concentrates in the United States, China, and India, with each hub serving distinct specification regimes. Raw material dependencies include petroleum-based synthetic polymers, full-grain leather hides, and Gore-Tex membrane laminates. Single-source vulnerability around carbon-fiber toe-cap molding technicians—concentrated in aerospace supply chains—creates bottlenecks during surge procurement periods. Distribution runs through institutional procurement platforms, cooperative purchasing alliances, and specialized tactical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tactical boots market functions as a stable compounder sustained by entrenched federal procurement cycles and municipal police modernization mandates that refresh equipment on predictable timelines.
For Market Incumbents: Lock in federal agency relationships through accelerated Berry Amendment compliance investments and captive membrane lamination capacity to defend against specialty composite entrants. Prioritize backward integration into ethylene-vinyl acetate compounding to buffer margin erosion from petroleum price volatility. Secure multi-year blanket purchase agreements before specification rewrites favor hybrid constructions over legacy leather designs. For New Entrants and Emerging Players: Direct-to-agency digital platforms offer the most viable route to bypass entrenched distributor networks and capture institutional margin. Target private security details in Texas and California corporate campus protection units, where patrol-optimized lightweight designs remain underpenetrated. Pursue NIJ certification alignment to establish regulatory credibility with municipal procurement officers rewriting specifications around officer wellness mandates. For Investors and Strategic Acquirers: Diversified footwear conglomerates with existing federal contract infrastructure are the most active acquirer in this space, seeking technical specialists with aerospace-derived composite capabilities. The long-term viability window favors targets with proven ASTM F2413-18 certification pathways and established relationships with membrane technology licensors. Watch for inflection signals in load-carriage ergonomics research publication rates, which anticipate specification revisions that accelerate hybrid construction adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive ethylene-vinyl acetate production buffers margin erosion from crude oil price swings. |
| NIJ Certification Facility Investment | Accredited testing capabilities accelerate municipal procurement qualification timelines. |
| Membrane Technology Licensing Partnership | Gore-Tex laminate access opens tropical and maritime deployment specifications. |
| Direct-to-Agency Digital Channel Launch | Municipal procurement platform integration bypasses traditional distributor markups. |
| Composite Toe-Cap Manufacturing Scale-Up | Carbon-fiber molding capacity addresses technician scarcity constraining surge production. |
Research Methodology
Multiple input streams — procurement officer interviews, manufacturing executive discussions, distributor channel assessments, and regulatory filing analysis — were reconciled to construct market estimates. Primary fieldwork engaged federal contracting specialists, municipal police equipment coordinators, Berry Amendment compliance officers, and composite material R&D directors. Secondary validation drew from Department of Defense procurement databases, NIJ testing protocol publications, ASTM standard revision records, and customs trade data for footwear imports. Bottom-up unit economics and top-down spending allocation models were triangulated against disclosed contract values.
Historical replacement cycle patterns were cross-referenced against panel input from procurement officers to project specification-driven demand across the analysis window. Segmentation modeling incorporated product type, material composition, end-user category, and closure configuration dimensions. CAGRs were derived from trend extrapolation of federal defense spending trajectories and municipal police budget allocations. Forecast inputs included load-carriage ergonomics research publication rates and REACH regulatory amendment timelines affecting membrane laminate formulations.
The model assumes a particular technology adoption path; alternative pathways for composite toe-cap displacement of steel would alter the outlook. Forecasts reflect underlying assumptions about specification revision timing and petroleum price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Bungee Cords and Accessories Market
Protective Gear
Helmets Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Equestrian Helmets Market
Protective Gear
Helmet Lining Market
Protective Gear
Safety Shoes Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Work Boots Market
Protective Gear
Pet Control Devices Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Earplug Distributor Market
Protective Gear
Europe Lanyards Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
Insect Repellent Market