
 Europe Athletic Footwear Market | 2026-2036
Europe Athletic Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Athletic Footwear Market Analysis
Trail runners and amateur marathoners are reorganizing demand across Europe, shifting volume from generalist trainers toward technical performance categories. Adidas AG leverages its German engineering heritage to dominate trail and road-running specialties. Nike, Inc. competes through its direct-to-consumer digital infrastructure, capturing premium price points in France and Italy. Puma SE anchors its position via motorsport-inspired cross-training lines that resonate with younger urban buyers in Spain and the Netherlands.
Europe athletic footwear encompasses performance-engineered shoes designed for running, training, crossfit, and sports sandal applications, typically constructed from mesh, leather, synthetic, or rubber materials with cushioned midsole systems for impact absorption and biomechanical support. Running shoes command the largest revenue pool due to marathon participation rates across Germany, the United Kingdom, and France, while training shoes and crossfit shoes are capturing faster growth as boutique fitness studios expand in metropolitan clusters. Mesh materials lead volume production for breathability in warm-climate Southern Europe, though leather retains premium positioning in formal-athletic hybrid segments across Northern European markets.
REACH restricts chemical inputs in synthetic uppers and adhesives, compelling reformulation of polyurethane and ethylene-vinyl acetate components across manufacturing networks. The EU Green Deal and CSRD disclosure requirements are accelerating scrutiny of Scope 3 emissions in Vietnamese and Indonesian contract factories supplying European brands. ECHA substance evaluations and France's AGEC anti-waste law collectively shape material substitution timelines and circular design obligations. Stakeholders must monitor evolving extended producer responsibility schemes and biocidal product regulations that will redefine acceptable material palettes and end-of-life recovery infrastructure before the decade closes.
Market Dynamics
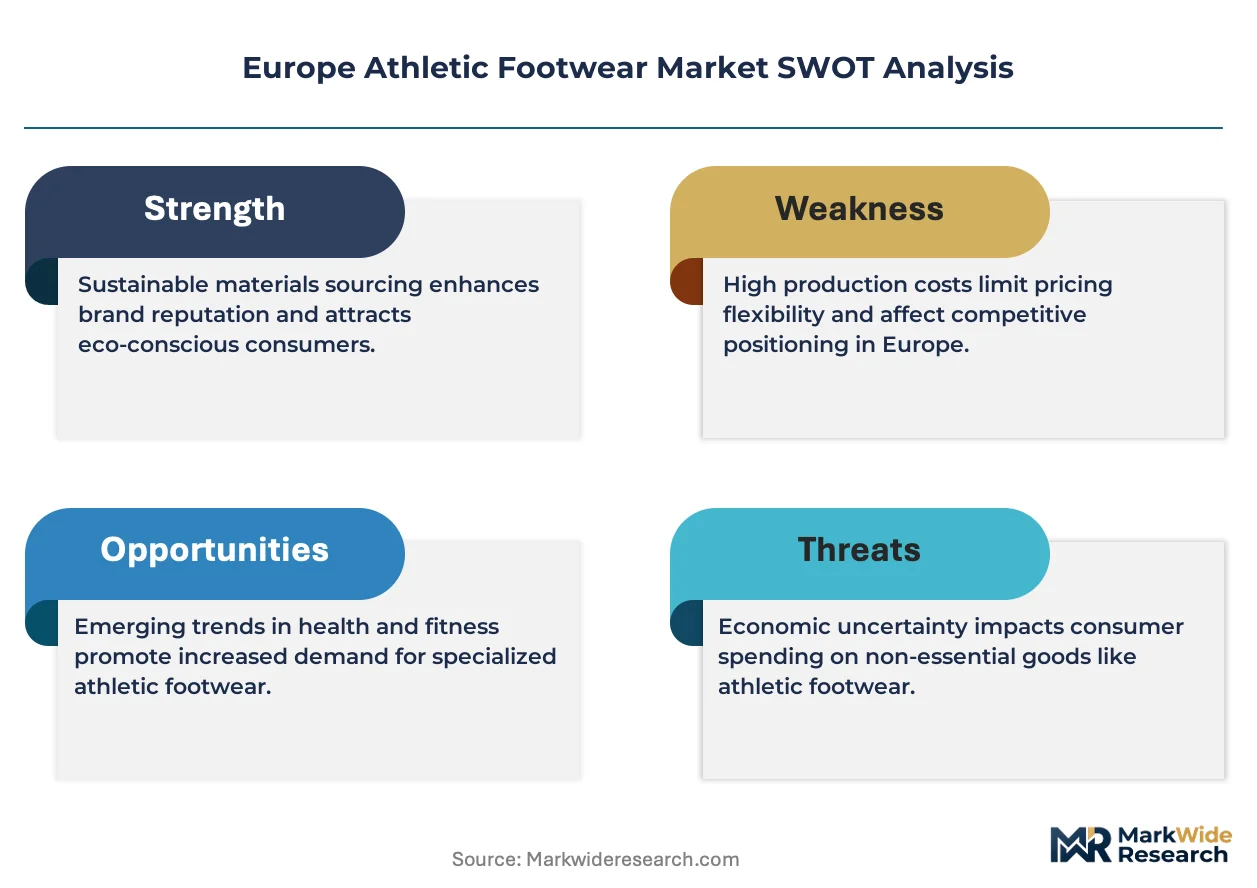
REACH chemical restrictions and the EU Green Deal are forcing wholesale material substitutions across European athletic footwear supply chains, compressing reformulation timelines while trail running and amateur marathon participation pull demand toward technical performance categories.
Growth Catalysts
- Amateur marathon participation:Germany, the United Kingdom, and France host expanding race calendars that drive replacement cycles for carbon-plated road racing shoes and structured stability trainers.
- REACH compliance deadlines:ECHA substance evaluations for restricted chemicals in polyurethane midsoles and synthetic uppers are accelerating bio-based foam adoption and recycled polyester integration across manufacturing networks.
- Boutique fitness studio expansion:Cross-training and HIIT facility growth in metropolitan clusters across Spain, Italy, and the Netherlands is lifting volume for multi-directional stability shoes with reinforced lateral support.
Market Restraints
- Petrochemical input volatility:Ethylene-vinyl acetate and thermoplastic polyurethane prices fluctuate with crude oil benchmarks, compressing margin predictability for midsole production.
- Vietnamese and Indonesian contract factory concentration:Scope 3 emissions scrutiny under CSRD disclosure requirements creates compliance exposure as European brands rely on concentrated Southeast Asian manufacturing.
- Leather substitute performance gaps:Bio-based alternatives to calfskin and nubuck in formal-athletic hybrid segments still exhibit durability and aesthetic limitations that constrain premium positioning.
Strategic Opportunities
- France's AGEC anti-waste law:Extended producer responsibility mandates for footwear end-of-life recovery are creating first-mover advantages for brands building circular collection and recycling infrastructure.
- Southern Europe heat adaptation:Breathable mesh constructions with moisture-wicking linings address underpenetrated demand in Spain, Portugal, and Italy where warm-climate performance specifications lag Northern European technical development.
- Direct-to-consumer digital platforms:Nike's app-based ecosystem and Adidas's Confirmed platform demonstrate how owned channels capture premium price points while reducing wholesale dependency in France and Italy.
Industry Challenges
- Bio-based foam formulation expertise:Chemical engineering talent capable of matching ethylene-vinyl acetate energy return in algae-derived or castor-oil midsoles remains concentrated among a narrow supplier base.
- CSRD Scope 3 data collection:Gathering verified emissions data from tier-two and tier-three Vietnamese and Indonesian material suppliers strains reporting infrastructure and audit capacity.
- Biocidal product regulation compliance:Antimicrobial treatments in performance liners and insoles face evolving ECHA evaluation criteria that threaten existing product registrations and require reformulation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Athletic Footwear Market |
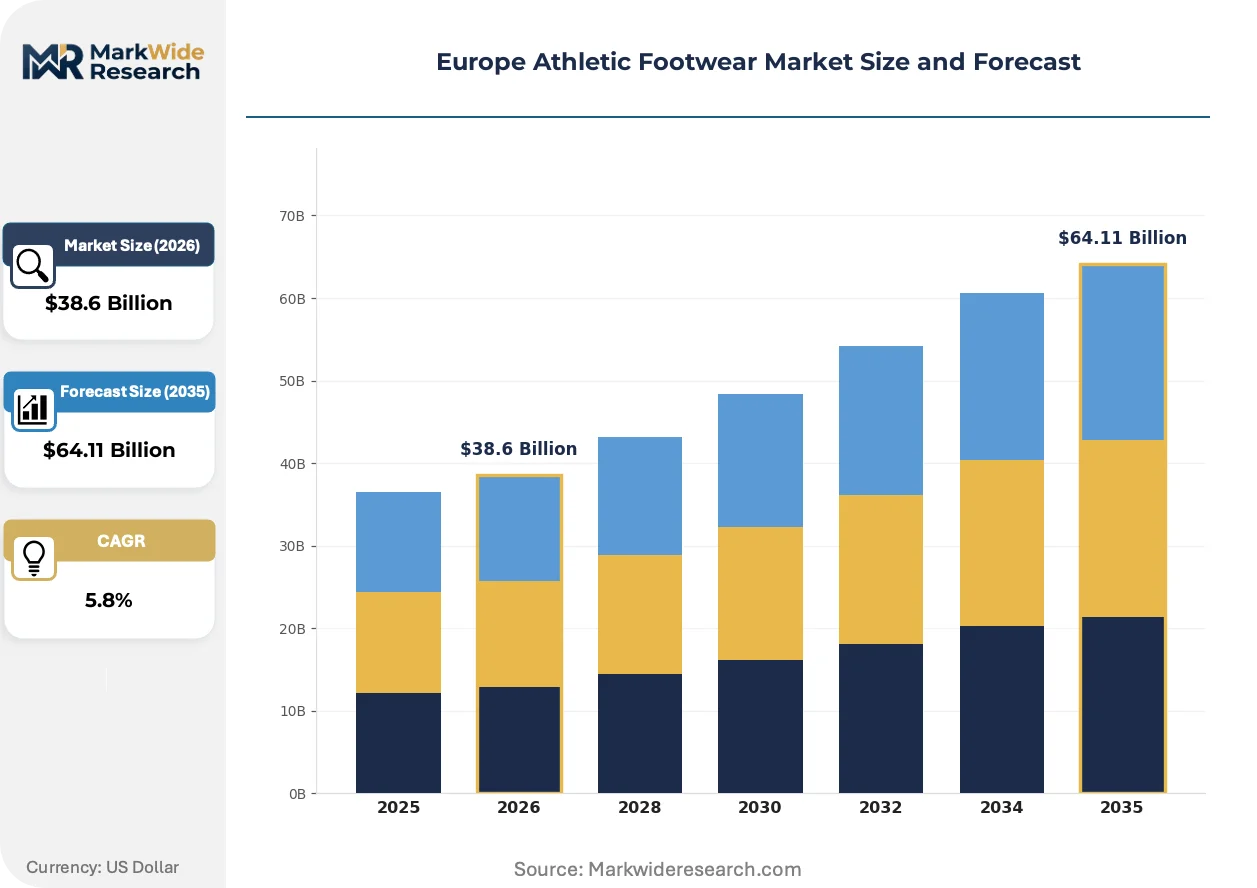
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running Shoes, Training Shoes, Crossfit Shoes, Sports Sandals End User: Men, Women, Kids, Unisex Distribution Channel: Online Retail, Specialty Stores, Department Stores, Hypermarkets Material: Mesh, Leather, Synthetic, Rubber |
| Companies Covered | ASICS Corporation, Under Armour Inc, Nike, Inc., VF Corp, Skechers USA Inc., Adidas AG, New Balance Athletics Inc., Lululemon Athletica Inc, Puma SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Athletic Footwear Market Emerging Trajectories
Bio-based material chemistry and circular design obligations are restructuring European athletic footwear manufacturing, while digital channel ownership and climate-adaptive specifications reshape competitive differentiation.
Algae-derived midsole foams and castor-oil based polyurethane systems are displacing petroleum-dependent ethylene-vinyl acetate in performance running shoes. Adidas and smaller technical specialists have integrated these materials into trail and road-running lines since 2022. The displacement is compressing reliance on fossil fuel feedstocks while creating new supplier dependencies on agricultural raw material streams.
France's AGEC anti-waste law and extended producer responsibility schemes are mandating footwear take-back and recycling infrastructure. Brands must fund end-of-life collection networks and meet material recovery targets by 2025. Running shoe categories face the steepest compliance costs due to complex multi-material construction that complicates mechanical recycling separation.
Specialty retail consolidation in Germany and the United Kingdom is compressing wholesale margins while direct-to-consumer platforms capture disproportionate volume. Adidas and Nike's owned digital ecosystems now handle significant transaction flow in France and Italy, displacing multi-brand sporting goods chains as the primary discovery channel for technical performance footwear. Southern European markets lag this transition, preserving wholesale relevance in Spain and Portugal.
Europe Athletic Footwear Market Segmentation
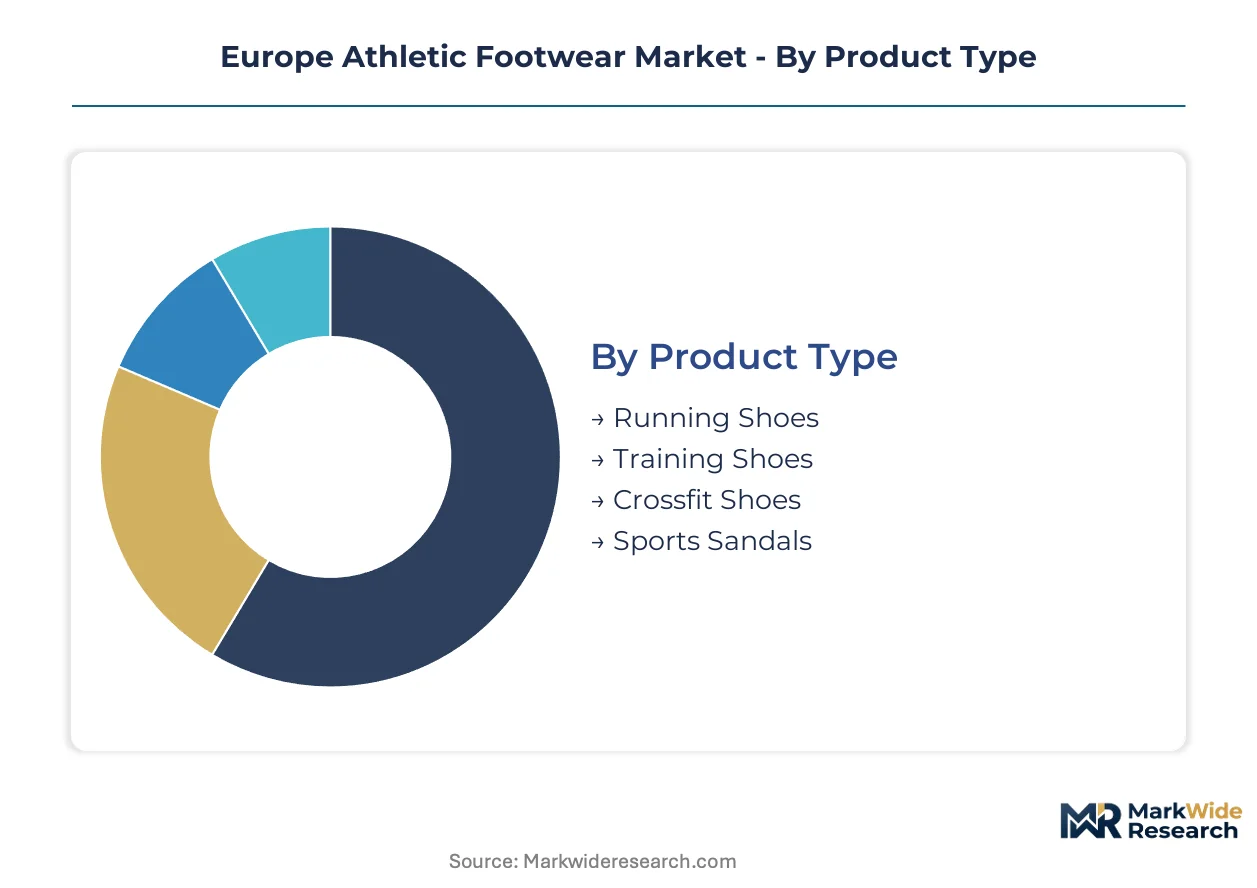
Segmentation reveals how marathon participation, boutique fitness expansion, and regulatory pressure on material chemistry are fragmenting demand across distinct product specifications and channel preferences. Understanding these divisions exposes where bio-based reformulation investments concentrate and which distribution architectures capture margin.
Product Type:
Domestic demand in Germany, France, and the United Kingdom drives volume for road-running specialties, while export-oriented production in Portugal and Romania supplies Southern European trail categories.
- Running Shoes:Carbon-plated midsoles and structured stability platforms dominate technical specifications for amateur marathoners across Germany and the United Kingdom. Race calendar density in Berlin, London, and Paris sustains replacement cycles for high-mileage road trainers.
- Training Shoes:Multi-directional outsoles with reinforced lateral support address HIIT and boutique studio expansion in Barcelona, Milan, and Amsterdam. Breathable mesh uppers with moisture-wicking linings target warm-climate Southern European specifications.
- Crossfit Shoes:Flat, stable platforms with rope-grip textures and reinforced toe caps serve box-training communities concentrated in Madrid and Rotterdam.
- Sports Sandals:Recovery-focused footbeds with arch support and adjustable strap systems capture post-run demand in coastal Portugal and Mediterranean resort markets.
Running Shoes holds the largest share; momentum sits with Training Shoes.
End User:
Gender-specific biomechanical engineering separates premium pricing tiers, while unisex minimalist lines compress margin through standardized last constructions.
- Men:Wider forefoot lasts and higher-density midsole foams address mass distribution patterns across German and British marathon demographics. Technical trail specifications with aggressive lug patterns dominate Alpine and Nordic outdoor retail.
- Women:Narrower heel cups and flexible forefoot platforms align with boutique fitness studio participation in French and Italian metropolitan clusters. Colorway diversity and seasonal collection velocity drive direct-to-consumer engagement.
- Kids:Growth-accommodating sizing systems and reinforced toe bumpers serve school sports programs and junior running clubs concentrated in suburban United Kingdom markets.
- Unisex:Simplified size runs and neutral color palettes reduce inventory risk for multi-brand retailers in Spain and Portugal where gender-segmented demand remains underdeveloped.
Men commands volume concentration; Women exhibits steepest expansion trajectory.
Distribution Channel:
Channel architecture separates markets by digital maturity, with Northern European direct-to-consumer penetration contrasting Southern European wholesale dependency.
- Online Retail:App-based ecosystems with AR fitting tools and subscription replenishment models capture premium price points in France and Italy. Nike and Adidas owned platforms displace multi-brand discovery for technical performance categories.
- Specialty Stores:Gait analysis services and local running club partnerships anchor community-based demand in Germany and the United Kingdom. Staff technical expertise justifies full-margin pricing for carbon-plated racing shoes.
- Department Stores:Curated athletic lifestyle presentations with formal-athletic hybrid positioning serve Northern European urban professionals seeking office-appropriate trainers.
- Hypermarkets:Volume-driven entry-level positioning with limited size ranges captures price-sensitive family demand in Spanish and Portuguese suburban retail parks.
Online Retail gains share fastest; Specialty Stores defend margin through technical service differentiation.
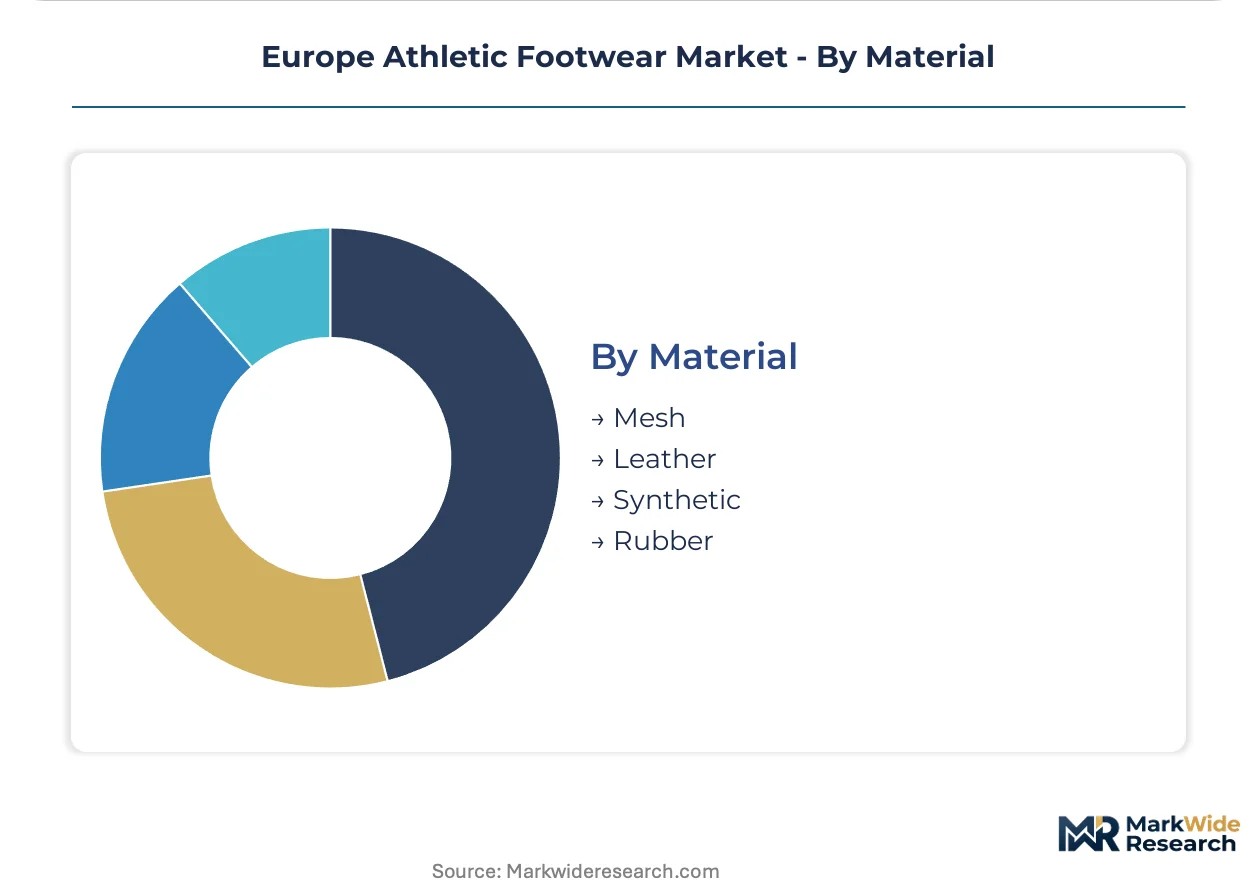
Material:
REACH compliance timelines and ECHA substance evaluations are accelerating substitution away from petroleum-dependent feedstocks toward agricultural raw material streams.
- Mesh:Engineered knit constructions with zonal ventilation patterns dominate warm-climate Southern European production. Recycled polyester integration satisfies France's AGEC anti-waste law material recovery thresholds.
- Leather:Calfskin and nubuck retain premium positioning in formal-athletic hybrid segments across Northern European markets. Bio-based alternatives exhibit durability gaps that constrain technical running applications.
- Synthetic:Polyurethane and thermoplastic polyurethane uppers face reformulation pressure under REACH chemical restrictions for restricted substances in adhesives and coatings.
- Rubber:Natural rubber blends with recycled content address outsole sustainability requirements, though petrochemical-derived compounds persist in high-abrasion trail applications.
Mesh leads volume production; bio-based synthetic formulations climb fastest as compliance deadlines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Dutch distribution dominance for athletic footwear imports entering continental Europe. Rail corridors from Rotterdam extend to German industrial zones and French logistics hubs. This infrastructure shapes how brands position inventory across Northern European markets.
Germany
Berlin Marathon and Frankfurt Marathon sustain replacement demand for carbon-plated racing shoes among amateur runners. REACH compliance deadlines from ECHA accelerate bio-based midsole adoption in Bavarian manufacturing zones. Herzogenaurach anchors technical development clusters where engineering talent concentrates.
United Kingdom
London Marathon participation drives volume for structured stability trainers across suburban running clubs. CSRD disclosure requirements pressure brands to verify Scope 3 emissions from Vietnamese contract factories supplying UK retail. Manchester and Birmingham host specialty retail consolidation that compresses wholesale margins.
France
Boutique fitness studio expansion in Paris and Lyon lifts demand for HIIT-optimized cross-training shoes. AGEC anti-waste law mandates extended producer responsibility for footwear end-of-life recovery by 2025. Lyon logistics clusters coordinate Southern European distribution for warm-climate mesh specifications.
Italy
Milan's design heritage supports formal-athletic hybrid positioning in premium leather segments. EU Green Deal carbon border adjustments influence sourcing decisions for synthetic upper materials. Tuscany manufacturing districts retain artisanal capacity for limited-edition performance collaborations.
Spain
Barcelona and Madrid box-training communities drive flat-platform Crossfit shoe specifications. Warm-climate breathability requirements lag Northern European technical development, preserving wholesale channel relevance. Valencia port infrastructure handles Mediterranean distribution for Portuguese and Italian retail networks.
Europe Athletic Footwear Market Vendor Landscape
Listed leaders compete with private specialists across digital channel ownership and material chemistry capabilities. The vendor base stratifies into three tiers: integrated sportswear conglomerates with owned manufacturing, digitally native specialists with direct-to-consumer platforms, and regional heritage brands with localized retail partnerships. Strategic moves concentrate on bio-based material partnerships and circular collection infrastructure deployment.
Within the integrated conglomerate tier, Adidas AG and Nike, Inc. exemplify divergent channel strategies—German engineering heritage against app-based ecosystem ownership. Puma SE occupies a position between these poles with motorsport-inspired cross-training lines. ASICS Corporation represents the technical specialist archetype, anchoring performance running credibility without full lifestyle portfolio breadth.
| Leading Market Players |
|---|
| ASICS Corporation |
| Under Armour Inc |
| Nike, Inc. |
| VF Corp |
| Skechers USA Inc. |
| Adidas AG |
| New Balance Athletics Inc. |
| Lululemon Athletica Inc |
| Puma SE |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles at Rotterdam port terminals concentrate pricing power with logistics-integrated brands while compressing margin buffers for wholesale-dependent competitors across German and French distribution networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates carbon-plated racing shoes from stability trainers from entry-level mesh constructions. Price differentiation rests on biomechanical engineering depth and REACH-compliant material certification. Pricing pressure stems from petrochemical input volatility in ethylene-vinyl acetate and thermoplastic polyurethane feedstocks. Hypermarket buyers in Spain and Portugal exhibit highest price sensitivity; marathon-specialty consumers in Berlin and London accept premium positioning for technical gait-matched products.
Supply Chain Analysis
Inventory concentration at Vietnamese and Indonesian contract factories creates lead-time vulnerability for European brands under CSRD Scope 3 disclosure mandates. Manufacturing draws from petroleum-derived midsole foams, recycled polyester knit uppers, and natural rubber outsole blends. Single-source vulnerability concentrates in algae-derived foam chemistry expertise held by narrow supplier bases. Distribution runs through Rotterdam port rail corridors extending to German industrial zones and French logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based shoe replenishment services and gait-analysis membership programs are expanding faster than unit hardware sales, transforming athletic footwear into a recurring-revenue platform anchored in biomechanical data retention.
For Market Incumbents: Secure bio-based foam formulation partnerships before REACH compliance deadlines compress supplier availability. Defend channel position by expanding owned digital ecosystems in France and Italy where Nike and Adidas platforms already displace multi-brand discovery. Vertical integration into circular collection infrastructure addresses France's AGEC anti-waste law mandates and creates competitor exclusion zones. For New Entrants and Emerging Players: Anchor in warm-climate mesh specifications for Spain, Portugal, and Southern Italy where breathable construction lags Northern European technical development. Target boutique fitness studio partnerships in Barcelona, Milan, and Amsterdam for HIIT-optimized cross-training shoes. Pursue direct-to-consumer launch with AR fitting tools to bypass wholesale margin compression in consolidated German and British specialty retail. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across circular recycling infrastructure as extended producer responsibility schemes mandate collection network buildout. Five-to-ten year viability favors brands with captive bio-based material supply or owned manufacturing in Portuguese and Romanian production zones. Monitor ECHA substance evaluation timelines as inflection indicators for forced reformulation waves that will strand petroleum-dependent inventory positions.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Material Partnership | Secures algae-derived foam supply ahead of REACH chemical restriction deadlines. |
| Circular Collection Infrastructure | Addresses France's AGEC anti-waste law extended producer responsibility mandates. |
| Direct-to-Consumer Platform Expansion | Captures premium price points while reducing wholesale dependency in Italy. |
| Regional Manufacturing Footprint | Shortens lead times from Portuguese production zones to German retail networks. |
| Sustainability Repositioning | Aligns product portfolios with EU Green Deal carbon border adjustment mechanisms. |
Methodological Framework
Cross-validation between primary interviews with footwear brand supply chain directors, specialty retail buyers, and ECHA regulatory affairs specialists and secondary validation through EU customs trade data, SEC footwear segment filings, and ECHA substance evaluation databases anchors the qualitative findings. Bottom-up demand modeling from marathon participation rates and boutique fitness studio expansion triangulates against top-down market sizing from retail audit data.
Sensitivity analysis across the projection horizon tests volume assumptions against petrochemical price volatility scenarios and regulatory compliance timeline shifts. Segmentation dimensions modeled include product type, end-user biomechanical specification, distribution channel architecture, and material chemistry compliance tier. CAGRs derive from replacement cycle analysis for carbon-plated racing shoes and expansion rates for HIIT-optimized cross-training categories.
Material uncertainties — ECHA substance evaluation outcomes, EU Green Deal implementation pacing, and Vietnamese contract factory emissions verification capacity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance cost pass-through and consumer willingness-to-pay for bio-based material premiums. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Barefoot Shoes Market
Footwear
Global Recovery Footwear Market
Footwear
Tennis Shoes Market
Footwear
Duck Boots Market
Footwear
Snow Boots for Women Market
Footwear
Wedge Boots Market
Footwear
Driving Footwear Market
Footwear
Running Shoes Market
Footwear
Snow Boots Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
Global Espadrille Flats Market
Footwear
Flip Flops Market
Footwear
UK Lifestyle Sneakers Market
Footwear
Indian Footwear Market
Footwear
Second Hand Designer Shoes Market
Footwear
Global Men Leather Shoes Market