
 Driving Footwear Market | 2026-2036
Driving Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Driving Footwear Market Foresight
Multi-source material procurement is recalibrating how driving footwear brands manage cost volatility and leather quality consistency. Alpinestars S.p.A leverages its Italian manufacturing heritage to sustain premium positioning in motorsport-specific designs. PUMA SE competes through global distribution scale and cross-category athletic technology transfer. Sparco S.p.A anchors its portfolio in Formula One heritage and professional racing credibility.
Driving footwear encompasses purpose-engineered shoes designed for enhanced pedal feel, featuring thin, flexible soles with reduced stack height and fire-resistant materials in motorsport variants. These products prioritize tactile feedback and ankle mobility over cushioning, serving amateur racers, track-day participants, and performance driving enthusiasts who require precise throttle and brake modulation. Leather Shoes command the highest margin pool due to Italian tannery partnerships and heritage positioning, while Sneakers represent the fastest-expanding category as casual styling merges with driving functionality. The Lightweight feature segment attracts technical buyers seeking reduced foot fatigue during extended track sessions.
REACH restricts chromium tanning processes and volatile organic compound emissions across European supply chains, elevating compliance costs for leather-dependent manufacturers. ECHA substance evaluations periodically ban specific dye chemistries, forcing reformulation of colored suede and synthetic uppers. ISO 11612 and FIA 8856-2000 standards govern flame resistance for competition-grade products, creating dual-certification requirements for brands serving professional and amateur segments. Stakeholders must monitor evolving chemical restrictions and motorsport federation rule changes that could abruptly obsolete existing material platforms.
Market Dynamics
Italian tannery concentration around Milan and Tuscany is reshaping how driving footwear brands secure premium leather supply, forcing multi-source procurement strategies to manage cost volatility and quality consistency across the value chain.
Growth Catalysts
- REACH Chemical Standards:European ECHA substance evaluations are accelerating reformulation of colored suede and synthetic uppers, pushing manufacturers toward compliant material platforms that command premium positioning.
- Motorsport Federation Standards:Dual-certification requirements under ISO 11612 and FIA 8856-2000 are creating technical moats for brands serving professional racing segments.
- Track-Day Participation:Amateur racing enthusiasts in Germany and Japan are demanding purpose-built performance footwear with fire-resistant materials and reduced stack-height soles.
Market Restraints
- Chromium Tanning Restrictions:REACH limits on chromium processes in European supply chains are elevating compliance costs for leather-dependent manufacturers sourcing from Italian tanneries.
- Artisanal Production Bottlenecks:Handmade construction methods in Tuscany and Marche regions constrain volume scalability for premium heritage brands.
- Synthetic Upper Substitution:Advanced microfiber materials from German chemical suppliers are displacing traditional leather in entry-level performance segments.
Strategic Opportunities
- Sustainable Material Convergence:Bio-based polyurethane foams from Netherlands chemical innovators are converging with recycled rubber outsoles to create circular product lines.
- Direct-to-Consumer Channels:Digital-native distribution models are bypassing traditional motorsport retail networks to capture margin from enthusiast communities.
- EU Green Deal Incentives:Carbon-neutral manufacturing investments in Portuguese and Spanish production facilities are unlocking green financing for supply chain relocation.
Industry Challenges
- Dual-Certification Timelines:Parallel ISO 11612 and FIA 8856-2000 approval processes are extending product development cycles for competition-grade footwear.
- Specialized Pattern-Making Talent:Scarcity of last-makers skilled in motorsport-specific anatomical fitting is constraining new product introduction rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driving Footwear Market |
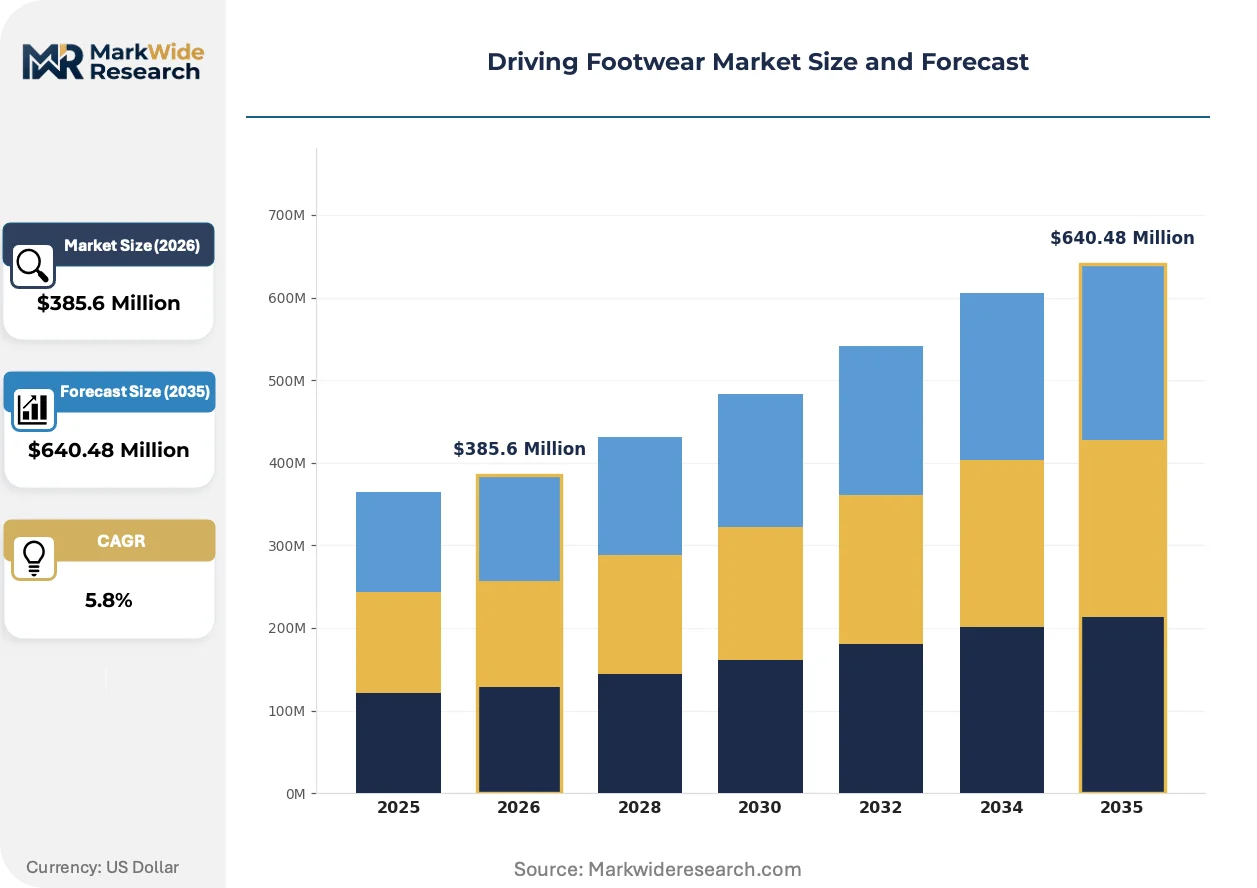
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leather Shoes, Sneakers, Driving Mocs, Sandals End User: Men, Women, Youth, Children Material: Leather, Canvas, Suede, Synthetic Feature: Water-Resistant, Cushioned Sole, Lightweight, Breathable |
| Companies Covered | PUMA SE, adidas AG, Alpinestars S.p.A, Dainese S.p.A, Nike Inc., Sparco S.p.A, Piloti Inc, SCOTT Sports SA, Fox Head Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driving Footwear Market Shifts & Advancements
Material science advances and shifting certification requirements are actively reconfiguring how driving footwear balances tactile performance with regulatory compliance across amateur and professional segments.
Knitted textile uppers with engineered compression zones are expanding into high-heat motorsport applications previously dominated by leather constructions. Professional racing teams in Italy and Germany are adopting these structures for their breathability and weight reduction. The technology is expanding into amateur track-day segments as price points compress toward accessible performance tiers.
REACH substance evaluations from ECHA are forcing systematic reformulation of dye chemistries across European manufacturing. Colored suede uppers face recurring bans on specific aromatic amines, compelling tanneries to validate alternative coloration processes. Motorsport brands serving both professional and amateur segments are responding by consolidating supplier relationships with REACH-compliant Italian tanneries.
Subscription-based footwear refresh programs are emerging among track-day enthusiasts seeking predictable equipment replacement cycles. Traditional retail channels with seasonal inventory models are losing share to direct membership services offering scheduled sole replacement and fit recalibration. Germany and the United Kingdom represent the most visible adoption geographies for this consumption-pattern shift.
Driving Footwear Market Segmentation
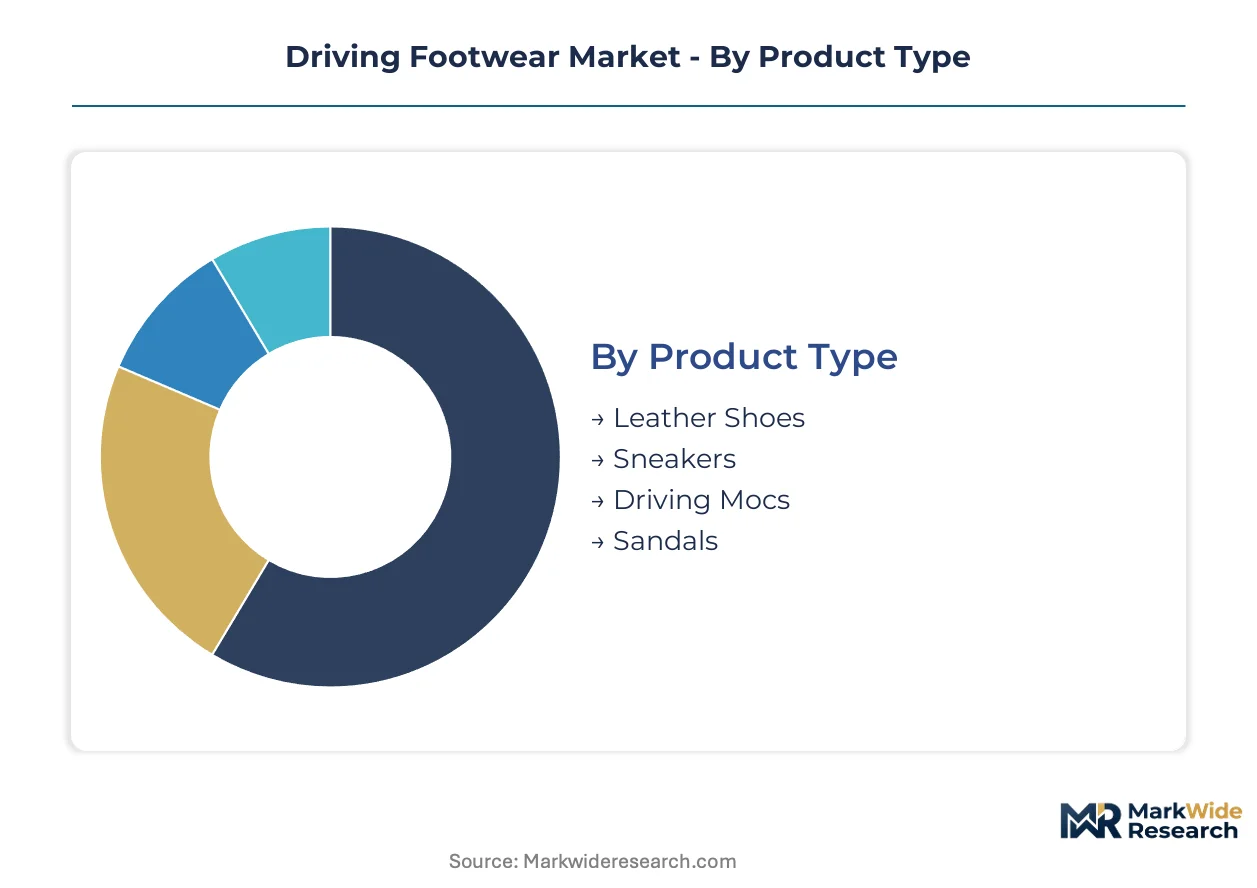
Driving footwear segmentation reveals how technical specifications diverge across amateur track-day participants and professional motorsport competitors. Product architecture, material selection, and feature prioritization each follow distinct demand curves shaped by certification requirements and regional manufacturing capabilities.
Product Type:
Standardization dominates entry-level categories while premium tiers embrace bespoke Italian craftsmanship calibrated to individual pedal-feel preferences.
- Leather Shoes:Full-grain Italian hides from Tuscan tanneries deliver the tactile precision professional racers demand for throttle modulation. REACH-compliant chromium-free tanning processes elevate unit costs while securing European market access for heritage manufacturers clustered around Milan.
- Sneakers:Knitted textile constructions with engineered compression zones are penetrating amateur track-day segments previously reserved for leather. German chemical suppliers provide advanced microfiber substrates that reduce weight without sacrificing FIA 8856-2000 flame-resistance certification.
- Driving Mocs:Traditional Venetian construction methods using pebble-grain leather serve casual enthusiasts prioritizing heritage aesthetics over competition-grade specifications.
- Sandals:Minimalist open-toe designs address warm-climate recreational driving in Mediterranean and Middle Eastern markets where breathability supersedes fire-protection requirements.
Leading the category by volume: Sneakers. Growing fastest: Leather Shoes.
End User:
Volume concentration skews toward male enthusiasts while female and youth segments show steepest expansion trajectories as motorsport participation broadens demographically.
- Men:Amateur racers in Germany and Japan constitute the core volume base, with professional-grade ISO 11612 certification driving replacement cycles among track-day regulars.
- Women:Purpose-engineered lasts addressing anatomical width and arch differential are gaining traction as female participation in amateur racing climbs across European circuits.
- Youth:Karting progression pathways in Italy and the United Kingdom are creating early-brand-loyalty opportunities for manufacturers offering scaled sizing with adult-equivalent safety ratings.
- Children:Junior motorsport programs in France and Spain require simplified fastening systems and growth-accommodating designs that prioritize safety over tactile precision.
Commanding the largest revenue pool: Men. Expanding most quickly: Women.
Material:
Supply geography dictates material selection, with Italian leather commanding premium positioning against German-engineered synthetics capturing volume tiers.
- Leather:Full-grain hides from Milan and Tuscany tanneries anchor premium positioning through heritage provenance and REACH-compliant processing validated by ECHA substance evaluations.
- Canvas:Cotton duck weaves serve casual styling segments where breathability and cost efficiency outweigh motorsport-specific performance requirements.
- Suede:Napped finishes from compliant Italian tanneries face recurring reformulation pressure as ECHA bans specific aromatic amines in dye chemistries.
- Synthetic:Advanced microfibers from German chemical suppliers are displacing leather in entry-level performance segments through consistent quality and predictable supply.
Highest margin capture: Leather. Gaining share fastest: Synthetic.
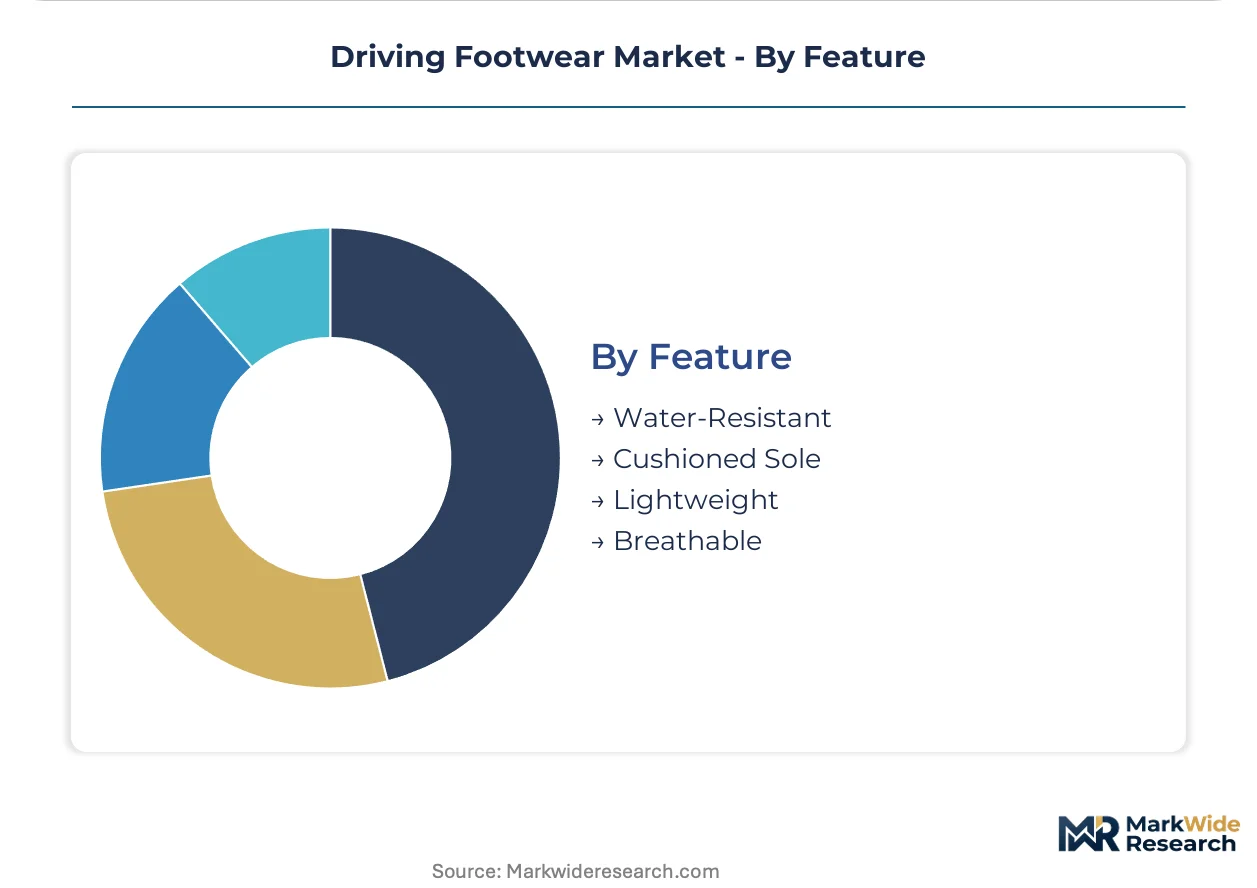
Feature:
Technical specifications bifurcate between competition-mandated safety features and comfort-oriented attributes for extended road use.
- Water-Resistant:Hydrophobic treatments on leather and synthetic uppers address all-weather amateur participation in Northern European climates.
- Cushioned Sole:Polyurethane midsole inserts serve touring-oriented drivers prioritizing fatigue reduction over the thin-stack-height precision that competition footwear demands.
- Lightweight:Reduced-mass constructions using carbon-fiber composite shanks attract technical buyers in Italy and Germany seeking diminished foot fatigue during endurance events.
- Breathable:Perforated leather panels and engineered mesh zones address heat management for track-day participants in Mediterranean and Middle Eastern conditions.
Dominating professional certification requirements: Lightweight. Climbing fastest in consumer preference: Breathable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian tannery clusters around Milan and Tuscany anchor raw-material supply for premium driving footwear, while manufacturing disperses across specialized European and Asian production zones to balance heritage craftsmanship with volume scalability.
Italy
Track-day participation in Lombardy and Emilia-Romagna sustains demand for FIA-certified competition footwear. REACH compliance from ECHA mandates chromium-free tanning processes that elevate production costs for Tuscan tanneries serving heritage manufacturers. Milan anchors design and pattern-making talent pools where artisanal last-makers calibrate motorsport-specific anatomical fits.
Germany
Amateur racing circuits in Bavaria and Baden-Württemberg drive replacement cycles for ISO 11612-certified products. KBA vehicle regulations indirectly shape safety-equipment standards adopted by track-day organizers. Chemical suppliers in the Rhine-Ruhr region engineer advanced microfiber substrates displacing leather in entry-level performance tiers.
United States
SCCA and NASA club racing participation concentrates in California and Texas, generating demand for fire-resistant motorsport footwear. OSHA workplace standards influence material handling protocols at domestic distribution centers. Southern California hosts styling studios where casual driving mocs merge track aesthetics with streetwear distribution channels.
Japan
Karting progression pathways in the Kanto region create early-brand-loyalty opportunities among youth segments. METI industrial standards support domestic manufacturing of lightweight carbon-composite shanks. Tokyo-based specialty retailers curate premium import selections from Italian heritage brands for enthusiast collectors.
United Kingdom
Historic motorsport circuits in Silverstone and Goodwood sustain heritage-brand visibility among amateur competitors. DVLA vehicle registration data informs regional demand forecasting for replacement-cycle planning. Northamptonshire retains traditional footwear manufacturing infrastructure repurposed for performance driving applications.
Driving Footwear Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance heritage positioning against technical innovation. The vendor base stratifies across three tiers: motorsport-specialist houses with FIA certification credibility, athletic-footwear multinationals leveraging cross-category technology transfer, and regional artisanal producers serving styling-conscious casual segments. Strategic archetypes include certification-driven specialists, scale-dependent global distributors, and heritage-positioned ateliers. M&A activity and direct-to-consumer channel expansion constitute the dominant competitive moves reshaping market access.
Within the motorsport-specialist tier, Alpinestars S.p.A and Sparco S.p.A exemplify Italian heritage positioning anchored in Formula One technical credibility. PUMA SE occupies the multinational athletic-footwear archetype, leveraging global distribution scale and cross-category material science capabilities. These three entities represent distinct strategic vectors—certification authority, manufacturing heritage, and operational scale—that collectively define competitive positioning thresholds.
| Leading Market Players |
|---|
| PUMA SE |
| adidas AG |
| Alpinestars S.p.A |
| Dainese S.p.A |
| Nike Inc. |
| Sparco S.p.A |
| Piloti Inc |
| SCOTT Sports SA |
| Fox Head Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FIA 8856-2000 competition footwear and casual driving mocs manifests in divergent pricing architectures and procurement geometries. Premium Italian heritage manufacturers command four-figure price points through captive tannery relationships in Tuscany, while entry-level synthetic constructions from German chemical suppliers compete on volume through modular sourcing.
Pricing Analysis
Warranty-bundled sole replacement programs now anchor premium positioning for track-day enthusiasts seeking predictable lifecycle costs. Three-tier pricing structure across premium, standard, and economy levels separates FIA-certified competition grade from ISO 11612 amateur tier and un-certified casual styling. Cost compression in synthetic entry segments is intensifying because German microfiber suppliers are scaling substrate production. Amateur racers in Germany exhibit highest price sensitivity, while professional teams demonstrate minimal elasticity for heritage-provenanced Italian leather constructions.
Supply Chain Analysis
Regional distribution centers in Milan, Stuttgart, and Los Angeles orchestrate hub-and-spoke fulfillment to motorsport retail networks and direct-to-consumer channels. Manufacturing concentrates in Italy, Portugal, and China, with full-grain hides from Tuscan tanneries anchoring premium tiers while Asian facilities handle volume synthetic assembly. Raw material dependencies include chromium-free leather from REACH-compliant Italian processors, bio-based polyurethane foams from Netherlands innovators, and carbon-fiber composite shanks from Japanese suppliers. Single-source vulnerability pervades the artisanal last-maker talent pool concentrated in Milan and Northamptonshire. Distribution runs through specialty motorsport retailers, brand-owned e-commerce platforms, and track-day event direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as REACH compliance costs and dual-certification timelines force sub-scale heritage brands toward strategic exit. ECHA substance evaluation cycles are accelerating material platform obsolescence for undercapitalized players.
For Market Incumbents: Hedge certification exposure by diversifying material platforms beyond leather-dependent constructions toward German-engineered microfiber partnerships. Secure captive supply through backward integration into Portuguese manufacturing facilities accessing EU Green Deal financing. Dual-certification investment in parallel ISO 11612 and FIA 8856-2000 approval streams protects against regulatory discontinuity while synthetic substitution technology from Rhine-Ruhr chemical suppliers threatens traditional leather positioning. For New Entrants and Emerging Players: Female amateur racers represent the most penetrable buyer archetype as purpose-engineered lasts addressing anatomical width differential remain under-supplied. Karting progression pathways in Italy and the United Kingdom offer white-space entry through scaled sizing with adult-equivalent safety ratings. Direct-to-consumer subscription models bypass established motorsport retail gatekeepers while capturing enthusiast community margin. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists given ECHA regulatory tightening and artisanal production bottlenecks in Tuscany. Long-term viability favors entities controlling both REACH-compliant tannery relationships and Portuguese carbon-neutral manufacturing capacity. Acquisition targets should demonstrate dual-certification completion and direct-to-consumer channel infrastructure. The signal to watch is consolidation activity among Milan-based pattern-making ateliers as talent scarcity intensifies.| Strategic Initiative | Industry Significance |
|---|---|
| FIA 8856-2000 Certification Investment | Professional racing credibility unlocks premium pricing tiers and team sponsorship pipelines. |
| REACH-Compliant Tannery Partnership | European market access depends on ECHA-validated chromium-free processing from Tuscan suppliers. |
| Direct-to-Consumer Channel Launch | Digital-native distribution captures margin from Germany and UK track-day enthusiast communities. |
| Portuguese Manufacturing Relocation | EU Green Deal incentives support carbon-neutral production facility development for supply chain resilience. |
| Subscription-Based Refresh Program | Predictable replacement cycles align with amateur racer equipment lifecycle preferences in Northern Europe. |
Research Methodology
Document review covered FIA technical regulations, ECHA substance evaluation databases, and ISO 11612 certification protocols, complemented by interviews with motorsport footwear design directors, Tuscan tannery procurement managers, track-day event organizers, and specialty retail buyers across Italy, Germany, and the United States. Secondary validation drew from customs trade data, SEC filings of athletic footwear multinationals, and motorsport federation participation statistics. Bottom-up unit economics triangulated against top-down market sizing from production capacity analysis.
Segment-level outputs across product type, end user, material, and feature dimensions were generated through driver-based modeling incorporating certification tier penetration, replacement cycle frequency, and regional track-day participation rates. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points and material substitution elasticities. Key inputs included REACH compliance cost curves, Italian tannery capacity utilization, and synthetic microfiber price convergence trends.
Revisions become necessary when ECHA substance bans extend to additional dye chemistries, FIA regulation updates modify flame-resistance testing protocols, or artisanal production capacity constraints intensify beyond current Milan and Northamptonshire thresholds. Forecasts reflect documented assumptions regarding certification adoption curves and material platform transition timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Light Up Shoes Market
Footwear
Shoe Rental Service Market
Footwear
Indian Footwear Market
Footwear
Riding Boots Market
Footwear
Outdoor Trail Running Shoes Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Refurbished Running Shoes Market
Footwear
Refurbished Sneaker Market
Footwear
Shoe Insoles Market
Footwear
Global Men Leather Shoes Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Dance Shoes Market
Footwear
Tennis Shoes Market
Footwear
Tactical Footwear Market
Footwear
Formal Shoes Market