
 Duck Boots Market | 2026-2036
Duck Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Duck Boots Market Foresight
The premium-commodity split in duck boots is rebalancing as heritage craftsmanship commands higher price points while mass-market rubberized alternatives flood discount channels. L.L.Bean leverages its Freeport, Maine manufacturing heritage to sustain authentic positioning. The Original Muck Boot Company anchors agricultural and industrial end-uses with specialized compound outsoles. Timberland competes through urban-styled hybrids that bridge worksite functionality with streetwear aesthetics.
Duck boots are waterproof footwear combining vulcanized rubber lower shells with leather or synthetic uppers, typically featuring sealed seams and insulating liners rated for sub-freezing temperatures; manufacturers employ injection molding for rubber bases and cemented or stitched construction for uppers to achieve watertight integrity. The primary commercial purpose spans outdoor labor, recreational hiking, and casual cold-weather wear where moisture protection intersects with thermal retention. Waterproof product types dominate volume shipments, though fashion-oriented variants capture expanding margin pools as streetwear collaborations elevate price ceilings. Rubber and leather materials retain the largest share of production inputs, yet synthetic blends represent the fastest-growing category as brands reduce weight and improve break-in comfort. Men's end-use still generates the highest absolute revenue, while women's and unisex segments accelerate through expanded sizing and colorway diversification.
The US Consumer Product Safety Commission oversees footwear flammability standards, while ASTM International publishes slip-resistance test methods that influence commercial and industrial procurement specifications. California's Proposition 65 labeling requirements affect rubber compound formulations for brands distributing in that state. European REACH restrictions on phthalates and heavy metals shape global supply chain chemistry decisions even for primarily North American brands. Stakeholders must monitor evolving PFAS regulations, as waterproofing treatments face intensifying scrutiny from EPA and state-level environmental agencies that could force reformulation investments across the sector.
Market Dynamics
PFAS-free waterproofing chemistry is forcing wholesale reformulation across duck boot manufacturing, as state-level bans in Maine and Minnesota pressure brands to abandon legacy DWR treatments ahead of anticipated EPA restrictions.
Growth Catalysts
- Outdoor recreation participation:Hiking and winter sports enthusiasts in wet-cold climates drive replacement cycles for insulated waterproof footwear.
- REACH chemical restrictions:European phthalate and heavy metal limits have accelerated global supply chain chemistry standardization, raising barriers for low-cost competitors.
- Bio-based rubber compounds:Guayule and dandelion-derived natural rubber substitutes are gaining traction in vulcanized shell production.
Market Restraints
- Petroleum-based input volatility:Synthetic rubber and neoprene prices fluctuate with crude oil markets, compressing margin predictability for mid-tier manufacturers.
- Chinese molding equipment concentration:Injection molding machinery for rubber bases relies heavily on Dongguan and Ningbo suppliers, creating geopolitical exposure.
- Thermal performance ceiling:Existing Thinsulate and Primaloft liners face physical limits at extreme sub-zero temperatures without bulk penalties.
Strategic Opportunities
- Indian outdoor retail expansion:Himalayan trekking tourism and emerging cold-weather apparel culture present first-mover positioning for waterproof footwear brands.
- Workplace safety mandates:OSHA slip-resistance specifications for commercial fishing and agriculture create specification-driven procurement channels.
- Digital fit technology:3D foot scanning and AI sizing recommendations reduce e-commerce return rates for fit-critical insulated boots.
Industry Challenges
- Specialized vulcanization technicians:The craft knowledge required for rubber-to-leather seam sealing is aging out of the workforce faster than apprenticeship pipelines refill.
- California Proposition 65 compliance:Reformulating rubber compounds to eliminate listed chemicals without sacrificing cold-flex performance demands extended R&D timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duck Boots Market |
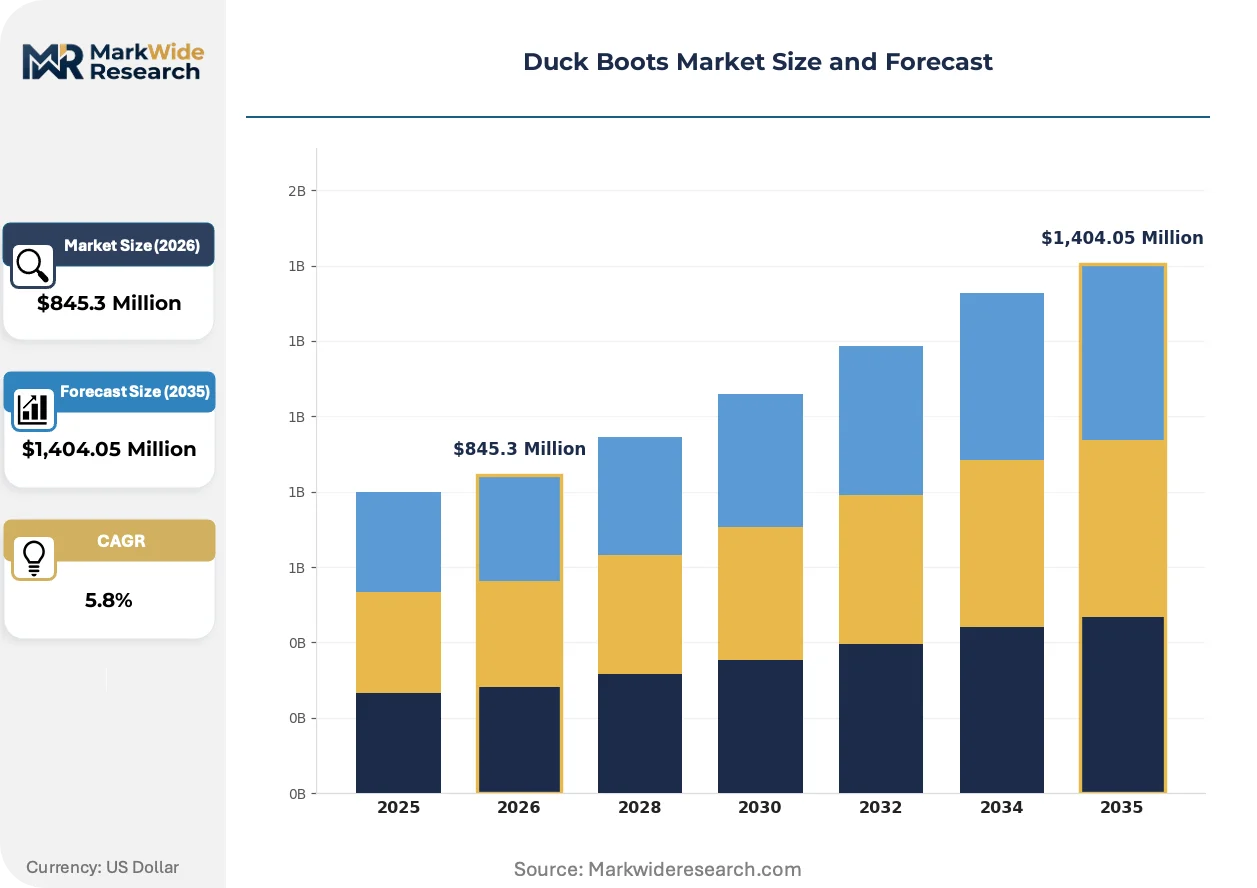
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $1,404.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterproof, Insulated, Fashion, Classic Material: Rubber, Leather, Synthetic, Canvas End User: Men, Women, Children, Unisex Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | L.L.Bean, The Original Muck Boot Company, Sorel, Kamik, Sperry, Timberland, Wolverine, Georgia Boot, Lands’ End, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duck Boots Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry pressures are reshaping how duck boots deliver waterproofing and thermal protection. Three distinct vectors are redefining product architecture and go-to-market approaches.
Recycled ocean plastics are converging with traditional nylon upper constructions. Marine debris-derived fibers now constitute 15-30% of synthetic duck boot uppers from premium manufacturers. Coastal conservation partnerships provide material traceability narratives that command retail price premiums in environmentally conscious consumer segments.
EPA PFAS scrutiny is accelerating fluorocarbon-free DWR development. The agency's 2024 drinking water standards and anticipated TSCA Section 6 restrictions are forcing brands to abandon long-chain water repellents. Small-batch outdoor specialists with early bio-based treatment adoption are capturing specification influence that cascades to mass-market suppliers.
Direct-to-consumer subscription models are disrupting seasonal retail patterns. Outdoor enthusiasts in the northeastern United States now access boot rental and replacement programs through specialty e-commerce platforms. This shifts inventory risk from retailers to manufacturers while compressing product development cycles to match annual weather variability rather than traditional fashion calendars.
Duck Boots Market Segmentation
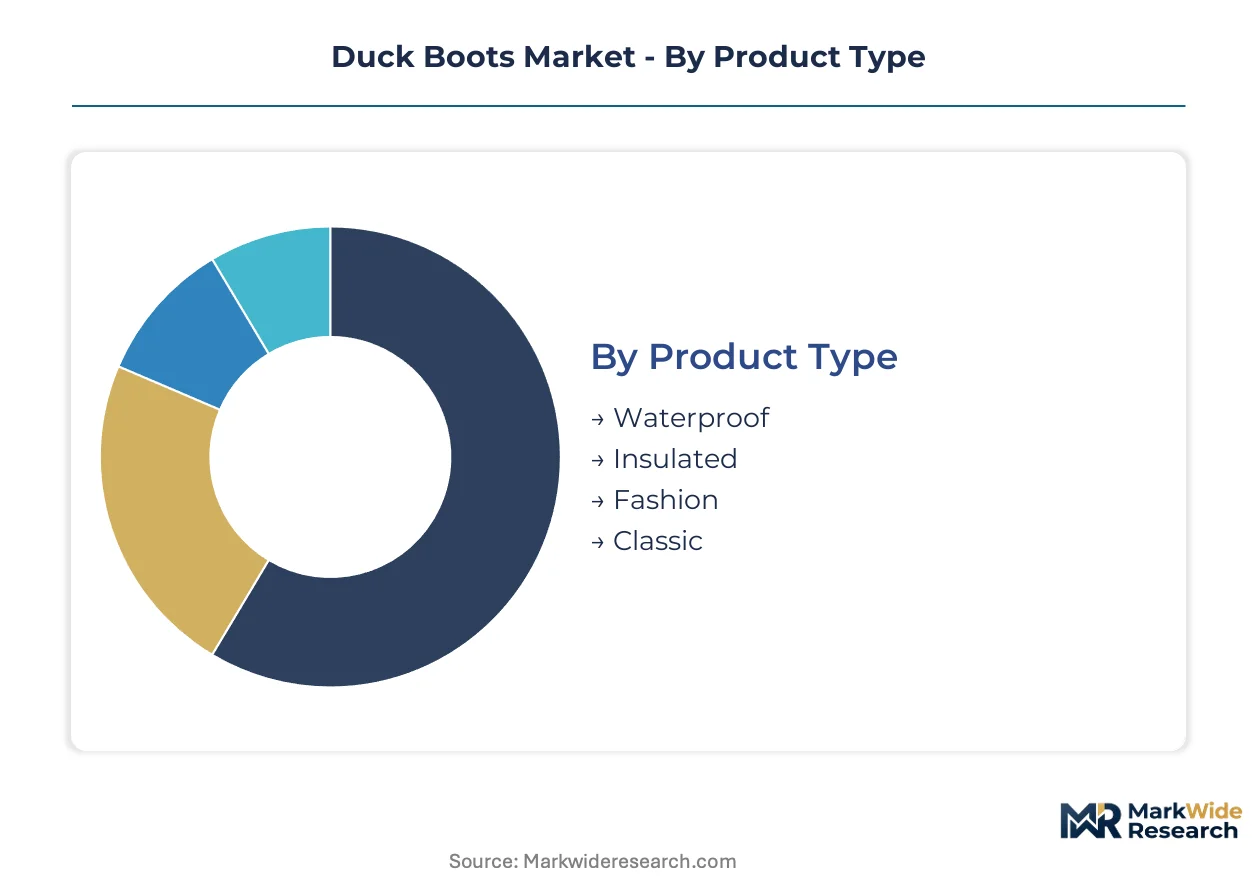
Duck boot manufacturers calibrate production lines, inventory depth, and marketing spend against four distinct slicing dimensions. Each category carries different certification burdens, margin profiles, and channel requirements that reshape competitive positioning.
Product Type:
Waterproof variants require ASTM slip-resistance certification for commercial procurement, while fashion SKUs face lighter regulatory loads but heavier trend-cycle risk.
- Waterproof:Gore-Tex membrane integration and sealed seam construction define performance specifications. Demand concentrates in Maine and Minnesota where wet-cold climates and pending PFAS regulations drive replacement cycles ahead of anticipated EPA restrictions.
- Insulated:Thinsulate or Primaloft liners rated to sub-zero temperatures add thermal retention layers. Agricultural workers in the Dakotas and commercial fishing operations in Alaska generate specification-driven volume through OSHA-aligned safety mandates.
- Fashion:Streetwear collaborations and heritage aesthetics command retail price premiums with reduced technical certification requirements.
- Classic:Traditional vulcanized rubber and leather combinations anchor heritage brand positioning with moderate regulatory exposure.
Leading the category by volume: Waterproof. Growing fastest: Fashion.
Material:
Raw material selection determines REACH compliance exposure, petroleum price sensitivity, and end-use durability expectations.
- Rubber:Vulcanized natural and synthetic compounds form the waterproof lower shell standard. Injection molding equipment concentration in Dongguan and Ningbo creates geopolitical supply risk for mid-tier manufacturers.
- Synthetic:Recycled ocean plastics and bio-based polymers represent the fastest-expanding input category. Marine debris-derived fibers now constitute 15-30% of premium synthetic uppers, with coastal conservation partnerships providing traceability narratives.
- Leather:Full-grain and oil-tanned hides retain heritage positioning despite higher break-in periods and moisture maintenance requirements.
- Canvas:Waxed cotton uppers serve fashion-oriented variants with reduced waterproofing performance but improved breathability.
Highest volume share: Rubber. Steepest expansion trajectory: Synthetic.
End User:
Size run complexity and colorway diversification requirements vary sharply across demographic targets.
- Men:Traditional work-boot lasts and width sizing (D, EE, EEE) dominate commercial and agricultural procurement channels with established fit standards.
- Women:Expanded size ranges and seasonal colorway rotations accelerate inventory turnover. Northeastern United States outdoor enthusiasts drive replacement program subscriptions through specialty e-commerce platforms.
- Children:Rapid outgrowth cycles compress replacement windows to single-season wear, demanding aggressive price positioning.
- Unisex:Streetwear aesthetics and sizing standardization bridge gender segments with simplified SKU management.
Absolute revenue leader: Men. Gaining share fastest: Women.
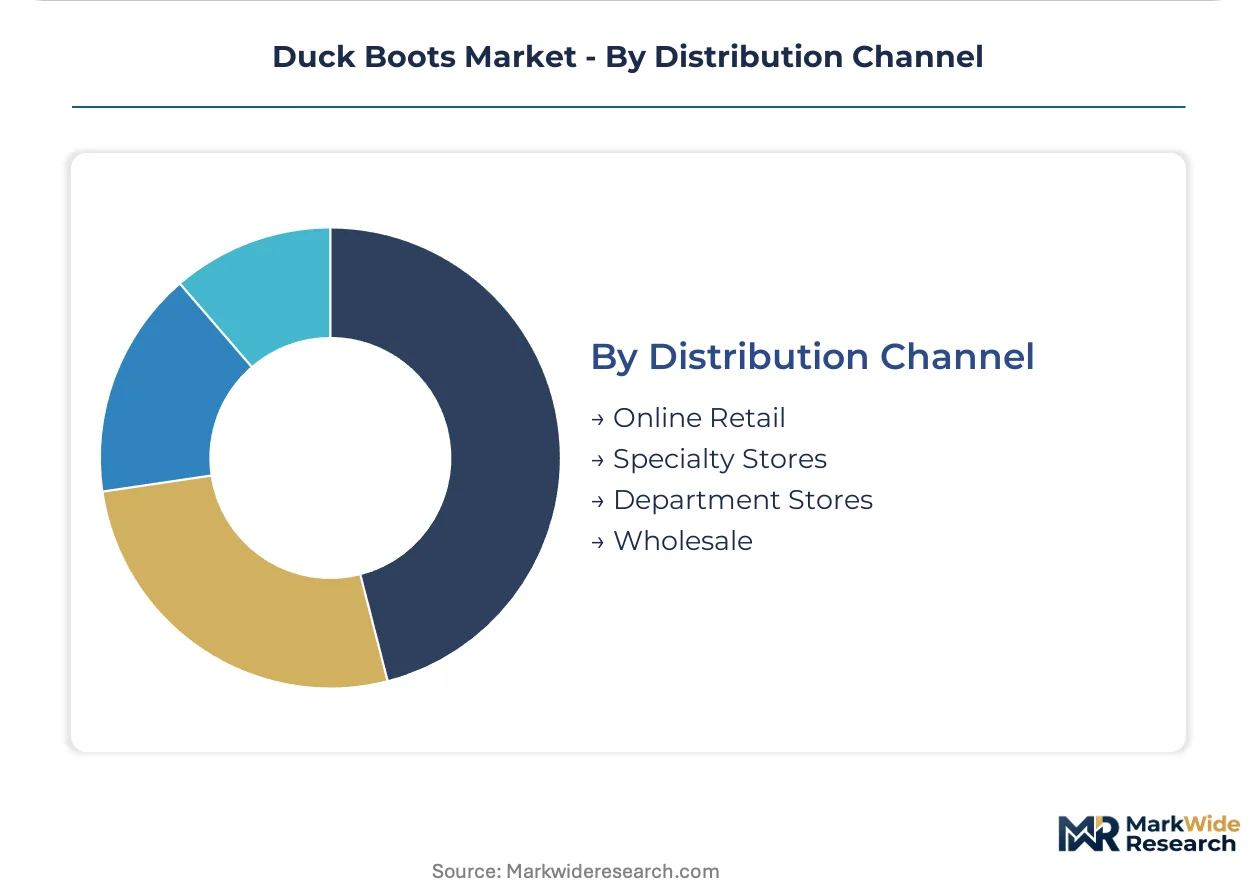
Distribution Channel:
Channel selection determines return rate exposure, margin retention, and inventory risk allocation between manufacturers and retailers.
- Online Retail:3D foot scanning and AI sizing recommendations reduce fit-critical return rates. Direct-to-consumer subscription models shift seasonal inventory risk from retailers to manufacturers.
- Specialty Stores:REI and regional outdoor chains provide technical credibility and staff expertise that justify premium positioning. Northeastern United States concentration aligns with core climate demand.
- Department Stores:Mass-market volume and fashion-variant placement depend on co-op marketing investments and seasonal calendar alignment.
- Wholesale:Agricultural and industrial procurement runs through specification-driven distributors serving OSHA-mandated workplace safety channels.
Highest volume throughput: Wholesale. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeport, Maine anchors heritage manufacturing for waterproof footwear, with L.L.Bean's original factory still producing vulcanized rubber boots using century-old seam-sealing techniques. Northeastern industrial clusters in the United States concentrate demand where wet-cold climates intersect with outdoor recreation culture.
United States
Outdoor recreation enthusiasts in New England and the Pacific Northwest drive replacement cycles for insulated waterproof footwear. EPA scrutiny of PFAS chemistry pressures manufacturers to reformulate durable water repellents ahead of anticipated TSCA Section 6 restrictions. Manufacturing concentration in Maine and Minnesota aligns with state-level bans on fluorinated compounds.
Canada
Commercial fishing operations in British Columbia and agricultural workers in the Prairie Provinces generate specification-driven procurement through cold-weather safety mandates. Health Canada coordinates with EPA on PFAS risk assessment timelines that shape North American reformulation schedules. Kamik maintains production facilities in Quebec serving domestic and export markets.
Germany
REACH restrictions on phthalates and heavy metals have accelerated global supply chain chemistry standardization for rubber compound formulations. ECHA's persistent organic pollutant assessments influence waterproofing treatment decisions across European manufacturing. Bavarian industrial clusters specialize in injection molding equipment for vulcanized footwear components.
China
Injection molding machinery for rubber bases concentrates in Dongguan and Ningbo, creating geopolitical exposure for mid-tier footwear manufacturers. MEE enforcement of dual carbon goals pressures energy-intensive vulcanization processes. Yangtze River Delta suppliers dominate synthetic upper material production for export-oriented brands.
India
Himalayan trekking tourism and emerging cold-weather apparel culture in Uttarakhand and Himachal Pradesh present first-mover positioning for waterproof footwear brands. BIS certification requirements for imported footwear create regulatory friction for foreign entrants. Maharashtra-based distributors are building outdoor specialty retail networks in Mumbai and Pune.
Duck Boots Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where heritage manufacturers maintain captive vulcanization facilities while contemporary brands outsource rubber shell production to Asian contract foundries. The vendor base splits between vertically integrated heritage operators and digitally native direct-to-consumer entrants. Three archetypes dominate: legacy Maine-based craftsmen, agricultural-specialist compound formulators, and urban-styled hybrid designers. Competitive moves concentrate on PFAS-free chemistry partnerships and direct-to-consumer fit technology investments.
Within the heritage craftsmanship tier, L.L.Bean and Sorel exemplify authentic positioning through manufacturing lineage and cold-climate specialization. The Original Muck Boot Company occupies a distinct position anchoring agricultural and industrial end-uses with specialized compound expertise. Among diversified outdoor footwear portfolios, Timberland represents the urban-styled hybrid archetype bridging worksite functionality with streetwear aesthetics.
| Leading Market Players |
|---|
| L.L.Bean |
| The Original Muck Boot Company |
| Sorel |
| Kamik |
| Sperry |
| Timberland |
| Wolverine |
| Georgia Boot |
| Lands' End |
| Others |
Supply & Pricing Matrix
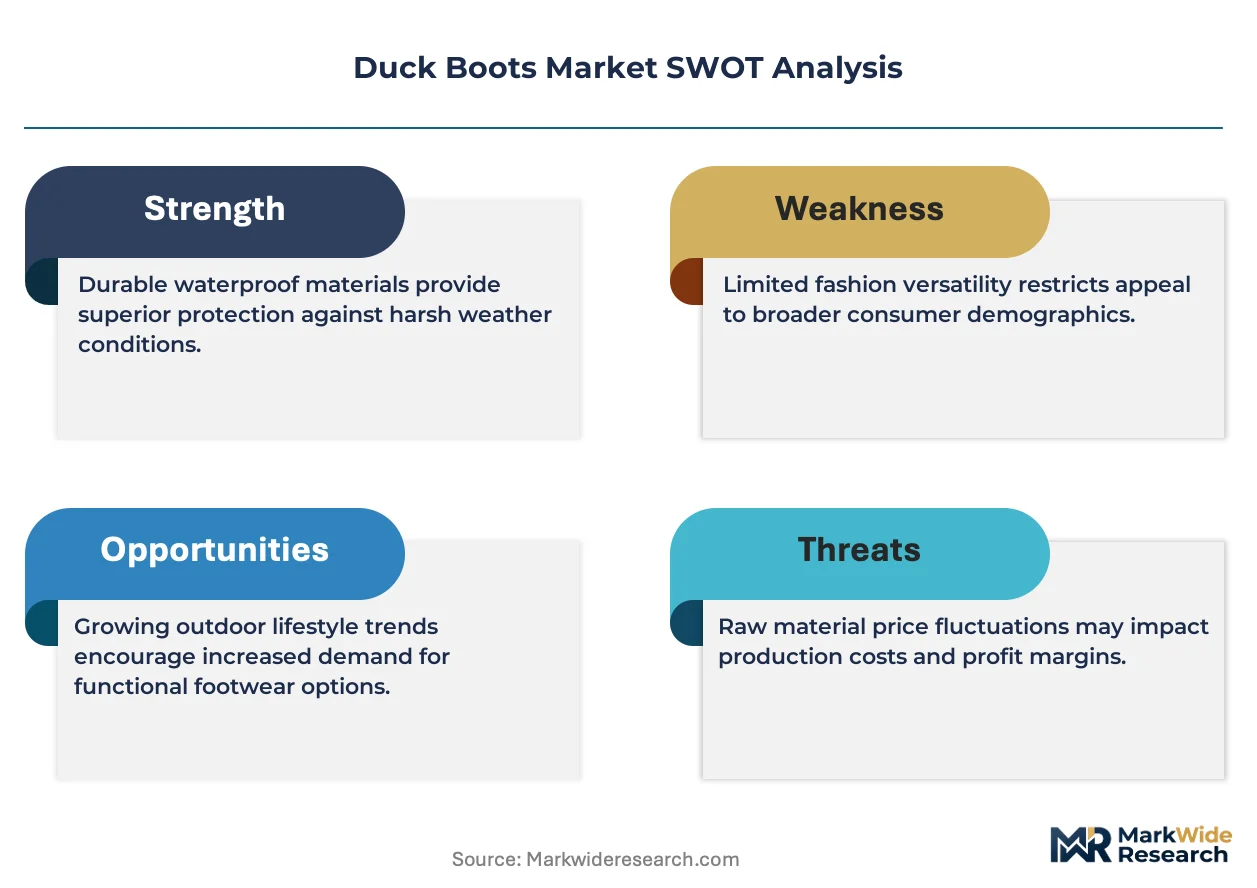
Family-owned heritage manufacturers in Maine and Minnesota anchor premium pricing through captive vulcanization facilities, while private-equity-rolled agricultural boot specialists compress mid-tier margins through Asian contract manufacturing. This ownership split concentrates supply discipline among legacy operators who control rubber-to-leather seam-sealing craft knowledge, forcing price premiums that mass-market brands cannot replicate without sacrificing cold-flex performance.
Pricing Analysis
Value-based pricing anchored to OSHA slip-resistance certification and sub-zero thermal performance defines the premium tier. Three-tier pricing structure across premium, standard, and economy levels separates Gore-Tex membrane integration from basic rubberized alternatives. Price differentiation rests on ASTM certification grade and heritage brand positioning. Cost compression in the standard tier intensifies because petroleum-based synthetic rubber inputs fluctuate with crude oil volatility. Agricultural procurement channels demonstrate lowest price sensitivity; discount-dependent casual wear segments exhibit highest.
Supply Chain Analysis
Specialized vulcanization technicians aging out of Maine and Minnesota manufacturing clusters constrain domestic production capacity. Geographic supply concentrates in China, Vietnam, and domestic US heritage facilities. Raw material dependencies draw from Guayule-derived natural rubber substitutes, recycled ocean plastics, and Thinsulate thermal liners. Single-source vulnerability runs through Dongguan and Ningbo injection molding equipment concentration. Distribution runs through specialty outdoor retail, direct-to-consumer subscription platforms, and agricultural specification-driven wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive rubber compound formulation and membrane lamination represents the decisive competitive race, as PFAS-free chemistry reformulation demands upstream control over waterproofing treatments.
For Market Incumbents: To counter PFAS regulatory bans in Maine and Minnesota, deepen backward integration into bio-based rubber cultivation partnerships and certify proprietary DWR formulations ahead of EPA TSCA Section 6 restrictions. Lock in Appalachian dandelion and Southwestern Guayule supply contracts to insulate against petroleum price volatility. For New Entrants and Emerging Players: Capture Himalayan trekking tourism growth in Uttarakhand and Himachal Pradesh through BIS-certified lightweight synthetic uppers targeting first-time outdoor enthusiasts. Deploy 3D foot scanning direct-to-consumer platforms to bypass established specialty retail gatekeepers in India's emerging outdoor markets. For Investors and Strategic Acquirers: State-level PFAS enforcement acceleration is the leading indicator that chemistry-compliant manufacturing assets will command scarcity premiums. Target vertically integrated heritage operators with captive Maine vulcanization facilities and established EPA pre-registration for fluorocarbon-free treatments. Watch EPA drinking water standard implementation timelines as the inflection signal for forced consolidation among reformulation-lagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Partnership | Secures regulatory runway ahead of EPA TSCA Section 6 restrictions in Maine and Minnesota. |
| Direct-to-Consumer Fit Technology | Reduces e-commerce return rates through AI sizing recommendations for insulated boot purchasers. |
| Bio-Based Rubber Cultivation | Insulates margin structure from petroleum volatility through Guayule and dandelion supply contracts. |
| Indian Distribution Expansion | Captures Himalayan trekking tourism growth through BIS-certified lightweight synthetic variants. |
| Workplace Safety Certification | Locks in OSHA-mandated procurement channels for commercial fishing and agricultural end-uses. |
Research Methodology
Multi-period observation of PFAS regulatory enforcement timelines and outdoor recreation participation rates anchored the trend analysis, supplemented by interviews with rubber compound formulators, specialty outdoor retail buyers, agricultural procurement officers, and vulcanization technicians. Secondary validation drew from EPA enforcement databases, ASTM International certification registries, customs import records for injection molding equipment, and BIS footwear import filings. Bottom-up SKU-level volume triangulation against top-down category spend estimates refined market sizing precision.
Input-output matrices mapped raw material flows from Guayule cultivation through vulcanized shell production to end-use segmentation across the analysis window. Modeled dimensions spanned product type, material composition, end-user demographic, and distribution channel, with regional regulatory clusters treated as distinct scenario inputs. CAGRs were derived from segment-level growth rate convergence against macroeconomic elasticity assumptions for discretionary outdoor spending.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA PFAS rulemaking finalization and petroleum price regime shifts. Projections reflect documented assumptions regarding state-level ban adoption timelines and outdoor participation trend persistence. A small set of named triggers—Maine PFAS enforcement acceleration, Dongguan equipment export restrictions, and Himalayan tourism infrastructure investment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Global Men Leather Shoes Market
Footwear
Women's Sneakers Market
Footwear
Leather Footwear Market
Footwear
Cyber-Shoes Market
Footwear
Sustainable Footwear Market
Footwear
Riding Boots Market
Footwear
Shoe Insoles Market
Footwear
Hiking Footwear Market
Footwear
Trail Running Shoes Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
GCC Footwear Market
Footwear
Sneakers Market
Footwear
PVC Footwear Market
Footwear
Shoe Rental Service Market
Footwear
High Heels Footwear Market
Footwear
Asia-Pacific Athletic Footwear Market