
 UGG Boots Market | 2026-2036
UGG Boots Market Size, Share, and Industry Trends Forecast 2026-2036
UGG Boots Market Insights
Buyer concentration is broadening beyond traditional female demographics toward unisex and male consumer segments in urban centers. Deckers Brands sustains its brand premium through controlled wholesale distribution and direct-to-consumer channel investment. EMU Australia leverages Australian sheepskin sourcing credentials to differentiate in markets where provenance commands price premiums. Koalabi Australia competes on heritage manufacturing narratives tied to regional craft traditions.
UGG boots are sheepskin-lined footwear constructed with twin-faced sheepskin, synthetic rubber outsoles, and fleece interiors engineered for thermal insulation in cold-weather conditions. The classic product type occupies the dominant revenue position due to established brand recognition and year-round styling versatility. Sheepskin material commands the highest margin pool despite synthetic alternatives gaining traction among price-sensitive segments. Women end users anchor volume demand, though unisex positioning now captures faster growth in direct-to-online channels.
The US Consumer Product Safety Commission enforces flammability standards for footwear textiles, while California's Proposition 65 mandates chemical disclosure labeling that raises compliance costs for imported sheepskin materials. REACH restrictions in Europe limit certain tanning agents and dyes, forcing reformulation of waterproofing treatments across supply chains. Stakeholders must monitor evolving material compliance requirements while evaluating regional manufacturing relocation to mitigate tariff exposure and shorten lead times.
Market Dynamics
California's Proposition 65 chemical disclosure mandates and the EU's REACH framework on restricted tanning agents are forcing wholesale reformulation of waterproofing treatments across sheepskin supply chains, compressing margin structures while extending product development timelines.
Growth Catalysts
- REACH-compliant material innovation:European tanneries investing in chromium-free alternatives are unlocking premium positioning in German and French retail channels previously closed to conventional sheepskin suppliers.
- Urban millennial clustering:Demand density in New York and Los Angeles is generating economies of scale for direct-to-consumer fulfillment infrastructure that lowers last-mile costs.
- Cold-weather performance engineering:Thermal insulation ratings now appearing on product labels are converting seasonal purchasers into year-round buyers across Nordic markets.
Market Restraints
- Australian sheepskin supply concentration:Overreliance on Merino wool belt processors exposes margins to drought-induced raw material volatility and currency fluctuation.
- Proposition 65 compliance friction:California's mandatory chemical disclosure labeling raises per-unit costs for imported materials and creates inventory segmentation complexity.
- Synthetic fleece substitution:Recycled polyester alternatives from Chinese textile mills are capturing price-sensitive volume in mass retail channels.
Strategic Opportunities
- Japanese premium retail penetration:METI-supported quality certification schemes for natural materials are opening department store placement previously dominated by domestic footwear brands.
- Circular take-back programs:Sheepskin recycling infrastructure development in the Netherlands is creating closed-loop brand differentiation opportunities.
- Direct-to-consumer channel expansion:Owned digital platforms bypass wholesale margin compression while capturing first-party behavioral data for personalization.
Industry Challenges
- Specialized tanning chemistry expertise:Shortage of technicians capable of reformulating waterproofing treatments to meet REACH restrictions without compromising durability is extending R&D cycles.
- Multi-jurisdiction labeling complexity:Simultaneous compliance with California Proposition 65, EU textile labeling directives, and Japanese consumer protection standards requires redundant testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UGG Boots Market |
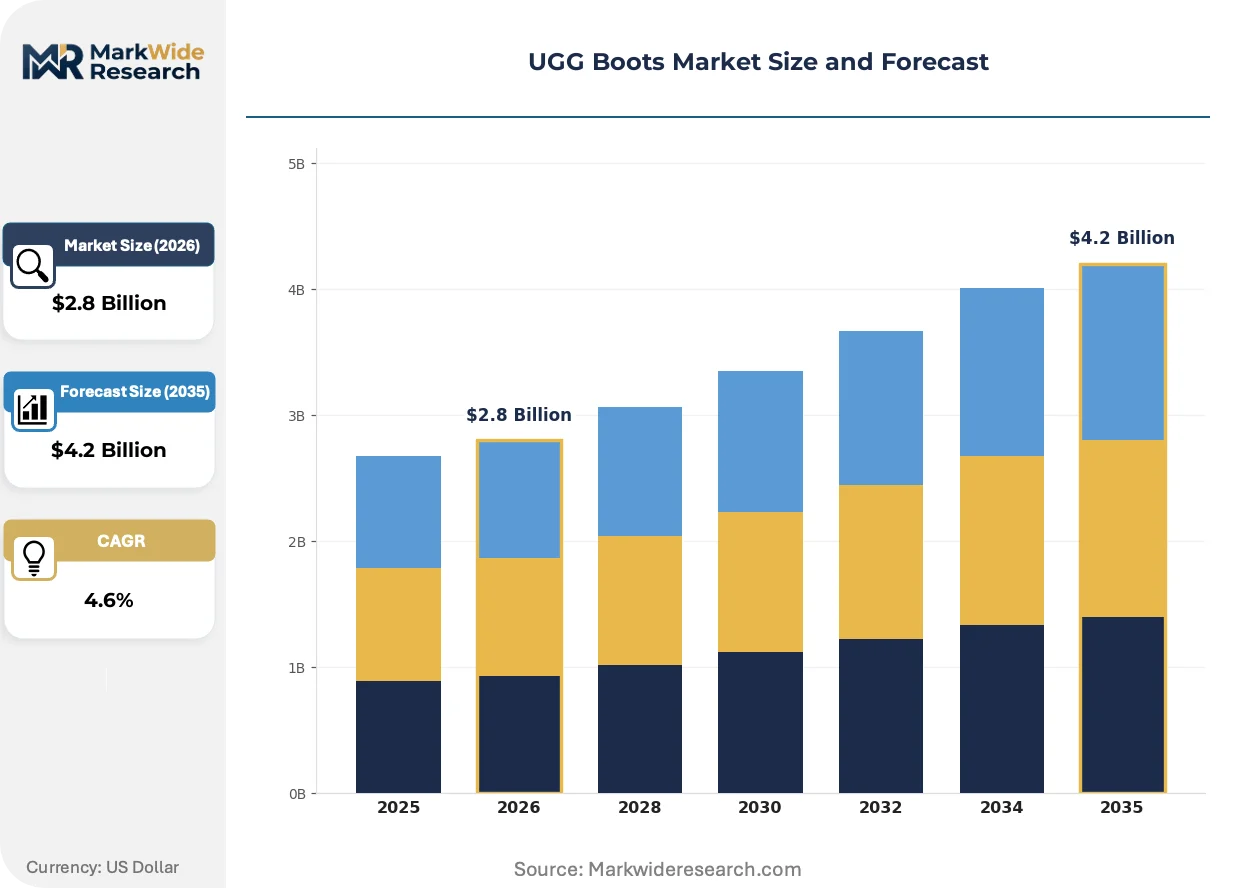
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Ultra, Ascot, Neumel Material: Suede, Leather, Sheepskin, Synthetic End User: Women, Men, Kids, Unisex Distribution Channel: Online, Retail Stores, Outlets, Wholesale |
| Companies Covered | Deckers Brands, Koalabi Australia, Mortels Sheepskin Factory, Sea Star Australia, Australian Sheepskin, Australian Ugg Boots, UGG Australia, EMU Australia, Jumbo Ugg Boots, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UGG Boots Market Trends and Innovations
Material science advances and regulatory pressure are converging to reshape how sheepskin footwear is sourced, processed, and sold across premium and mass channels.
Water-based polyurethane coatings engineered for sheepskin breathability are consolidating technical differentiation among mid-tier manufacturers previously reliant on conventional solvent-based treatments. Italian and Portuguese tanneries are adopting these systems fastest, enabling shorter production runs with reduced environmental liability. The technology is consolidating supplier relationships around fewer certified chemical partners capable of meeting dual REACH and Proposition 65 standards.
California's Proposition 65 enforcement expansion into footwear textiles is mandating explicit chemical disclosure on product tags and digital listings. The regulation is forcing reformulation of waterproofing agents and dye fixatives across Asian contract manufacturers serving US-bound production. Premium brands with in-house compliance teams are absorbing these costs more readily than private-label importers dependent on third-party testing.
Urban millennial buyers in New York and Los Angeles are migrating from seasonal retail purchases toward subscription-based footwear refresh models. Direct-to-consumer platforms are displacing department store seasonal buys with monthly styling services that rotate sheepskin product categories. This pattern is most visible among female consumers aged 25-34 prioritizing wardrobe versatility over single-item longevity.
UGG Boots Market Segmentation
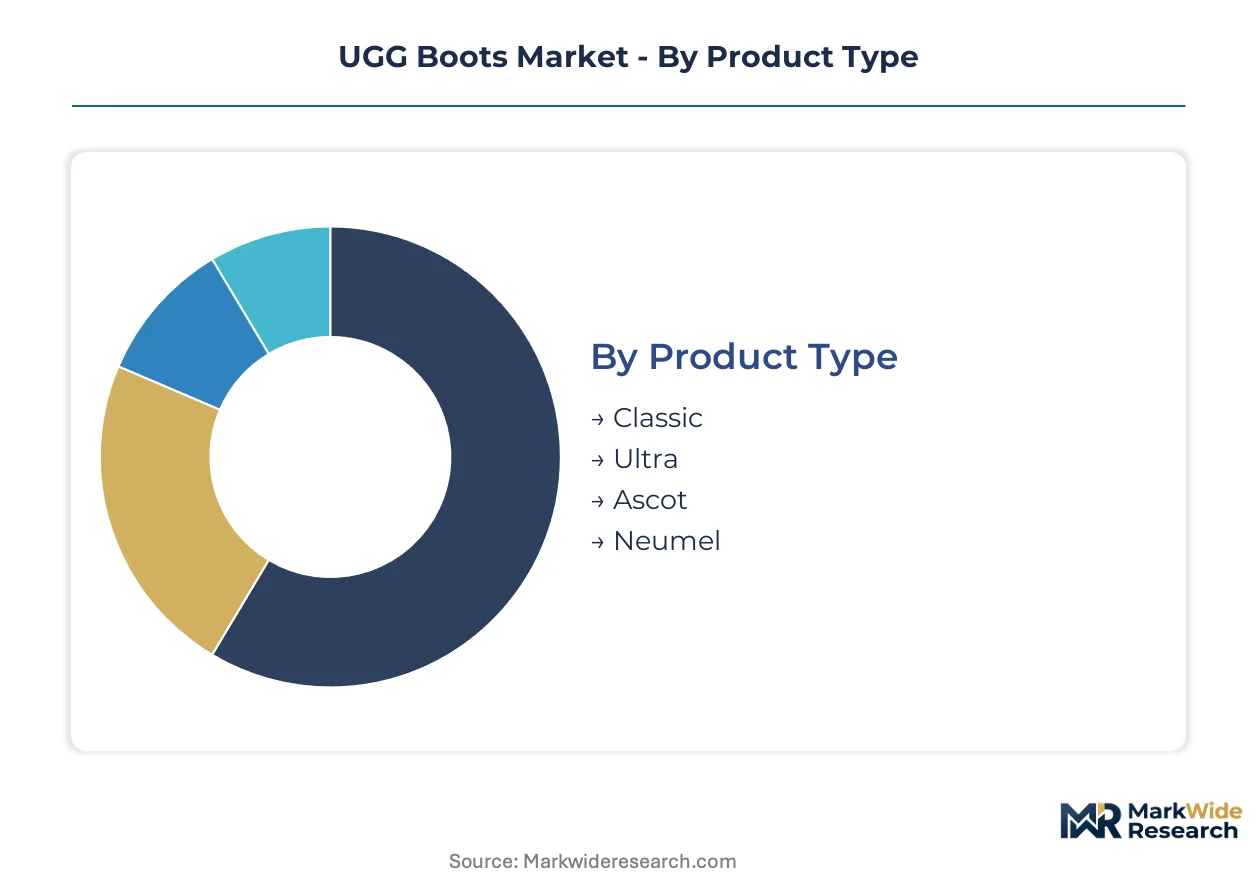
Segmentation in sheepskin footwear separates volume-driven commoditized tiers from margin-protected premium positioning. Distinct material specifications, distribution economics, and end-user behavioral patterns create divergent investment requirements across each dimension.
Product Type:
Capital deployment varies sharply across product architectures, with molded sole platforms demanding dedicated tooling investments distinct from hand-finished constructions.
- Classic:Twin-faced sheepskin construction with reinforced heel counters and EVA outsoles defines the technical baseline. Urban millennial buyers in New York and Los Angeles cluster around this silhouette for year-round styling versatility, though seasonal inventory cycles compress working capital efficiency.
- Ultra:Thicker fleece linings and weather-treated exteriors command premium positioning in Nordic markets where thermal insulation ratings drive purchase decisions. Direct-to-consumer channels capture disproportionate margin here due to lower price elasticity among cold-climate consumers.
- Ascot:Slipper-adjacent indoor-outdoor hybrid with lower profile outsoles.
- Neumel:Chukka-inspired ankle boot with lace-front closure and structured collar.
Classic absorbs the bulk of installed capacity; Ultra is expanding most quickly.
Material:
Raw material sourcing intensity separates segments, with live-animal fiber procurement requiring longer capital lockup than petroleum-derived alternatives.
- Sheepskin:Merino wool belt processors in Australia supply twin-faced hides with fleece retained on interior surfaces. REACH-compliant tanning chemistry investments in Italian tanneries are unlocking German and French retail placement previously restricted by chromium concerns.
- Synthetic:Recycled polyester fleece from Chinese textile mills is capturing price-sensitive volume in mass retail channels. California's Proposition 65 disclosure mandates create compliance friction for imported finished goods using solvent-based bonding agents.
- Suede:Split-grain leather with napped surface finish requiring specialized buffing equipment.
- Leather:Full-grain or corrected-grain hides with polymer topcoats for weather resistance.
Sheepskin commands the deepest supply chain investments; Synthetic is climbing the fastest among cost-optimized private-label entrants.
End User:
Customer acquisition economics diverge by demographic, with female-targeted marketing spend historically dominating but unisex positioning now reshaping channel allocation.
- Women:Volume anchor across North American and European premium retail, with subscription-based refresh models displacing seasonal department store purchases among 25-34 age cohorts. Wardrobe versatility priorities extend purchase frequency beyond traditional cold-weather replacement cycles.
- Unisex:Direct-to-online channels are capturing faster growth as sizing standardization and neutral color palettes reduce SKU complexity. Urban male consumers previously excluded from category marketing are entering through this positioning.
- Men:Heritage craft narratives and outdoor utility positioning.
- Kids:Size-scaled production with simplified construction and accelerated replacement cycles.
Women retain the largest share of marketing expenditure; Unisex is gaining share fastest through digital-native customer acquisition.
Distribution Channel:
Working capital intensity and margin capture potential vary dramatically by channel control, with inventory ownership and return liability creating distinct risk profiles.
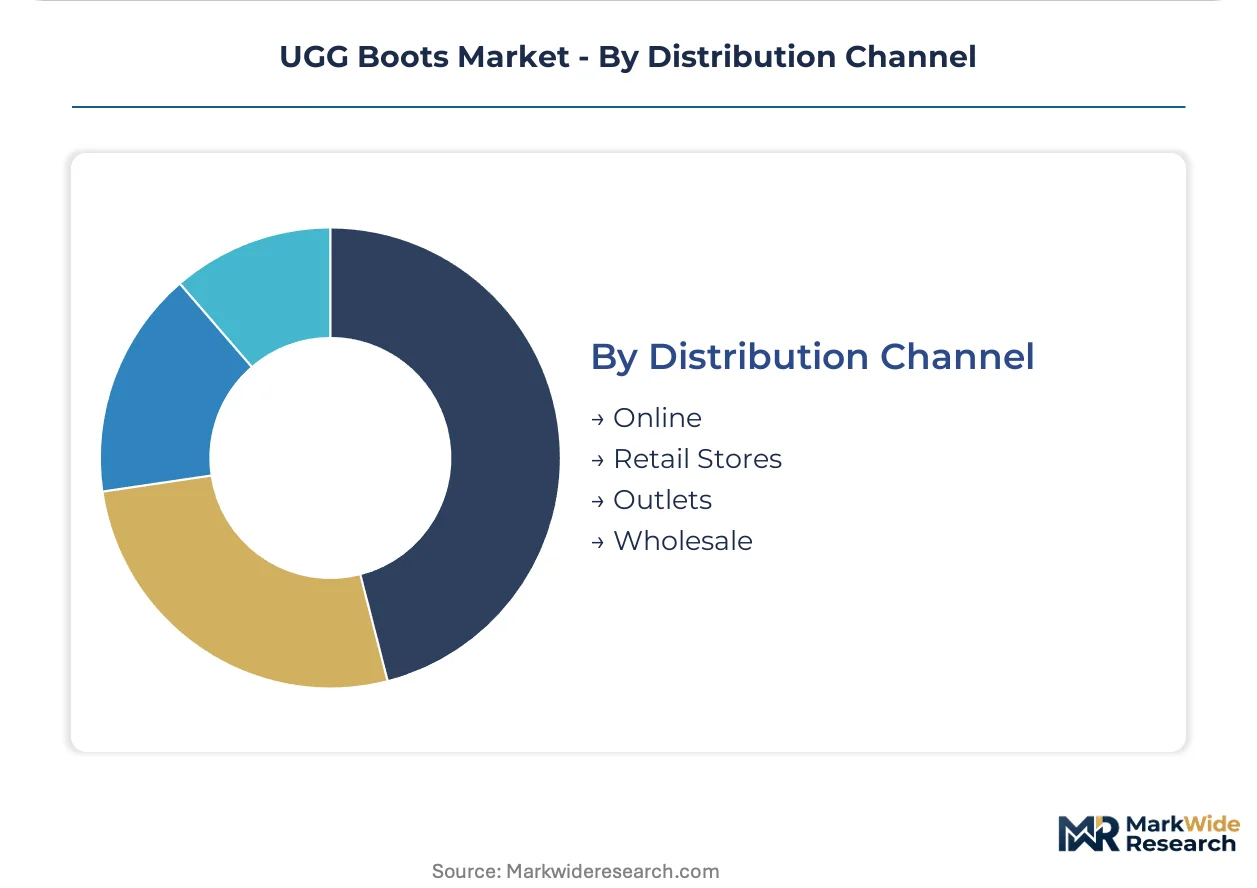
- Online:Owned digital platforms bypass wholesale margin compression while capturing first-party behavioral data for personalization. Last-mile fulfillment infrastructure in New York and Los Angeles density corridors generates economies of scale that lower per-unit logistics costs.
- Retail Stores:Full-price flagship locations in premium urban centers sustain brand equity but carry fixed cost burdens that strain smaller competitors.
- Outlets:Off-price clearance channels for end-of-season inventory liquidation.
- Wholesale:Third-party department store and specialty retail partnerships with inventory risk transfer.
Online is absorbing the majority of new capital allocation; Retail Stores face selective rationalization as lease renewals come due.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial consumers in the United States concentrate the highest demand density for premium sheepskin footwear, with subscription-based purchasing patterns now displacing traditional seasonal retail cycles in major metropolitan corridors.
United States
New York and Los Angeles generate the strongest direct-to-consumer fulfillment economies, with last-mile infrastructure investments lowering per-unit logistics costs in these density corridors. California's Proposition 65 mandates explicit chemical disclosure labeling on all imported sheepskin materials, raising compliance costs for Asian contract manufacturers. Deckers Brands anchors premium positioning through controlled wholesale distribution and owned digital platforms capturing first-party behavioral data.
Australia
Merino wool belt processors in New South Wales and Victoria supply twin-faced hides with fleece retained on interior surfaces, though drought-induced raw material volatility exposes margin structures. The country's national consumer protection framework enforces strict labeling requirements for natural fiber content claims. EMU Australia leverages Australian sheepskin sourcing credentials to differentiate in European markets where provenance commands price premiums.
Germany
Cold-climate consumers in Bavaria and North Rhine-Westphalia prioritize thermal insulation ratings on product labels, converting seasonal purchasers into year-round buyers. ECHA's REACH framework restricts chromium-based tanning agents, forcing reformulation of waterproofing treatments across Italian and Portuguese tannery suppliers serving German retail channels. Munich and Berlin department stores now feature REACH-compliant sheepskin collections previously closed to conventional suppliers.
Japan
METI-supported quality certification schemes for natural materials are opening premium department store placement in Tokyo and Osaka previously dominated by domestic footwear brands. The Ministry of Economy, Trade and Industry's standards for material traceability create entry barriers for uncertified imports. Urban consumers aged 25-34 in the Kanto region demonstrate the fastest adoption of subscription-based footwear refresh models among Asian markets.
United Kingdom
London and Manchester sustain year-round demand through styling versatility positioning rather than pure cold-weather functionality. The UK's textile labeling regulations align with EU directives on restricted substances, maintaining compliance continuity post-Brexit for sheepskin imports. Heritage craft narratives tied to regional manufacturing traditions resonate strongly with premium buyers in the Southeast and Midlands corridors.
UGG Boots Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent synthetic fleece and circular recycling spaces. The vendor base concentrates around three archetypes: premium heritage brands leveraging Australian provenance, mid-tier specialists optimizing REACH-compliant tanning chemistry, and private-label importers competing on price-sensitive volume. Dominant competitive moves include direct-to-consumer channel expansion bypassing wholesale margin compression, and backward integration into Australian sheepskin sourcing to secure raw material availability.
Within the heritage-provenance tier, Deckers Brands and EMU Australia exemplify positioning strategies that convert geographic sourcing credentials into retail price premiums. Koalabi Australia sits within the craft-specialist archetype, anchoring differentiation around regional manufacturing narratives. These three companies collectively represent how Australian-origin players defend margin structures against synthetic substitution and regulatory compliance cost pressures.
| Leading Market Players |
|---|
| Deckers Brands |
| Koalabi Australia |
| Mortels Sheepskin Factory |
| Sea Star Australia |
| Australian Sheepskin |
| Australian Ugg Boots |
| UGG Australia |
| EMU Australia |
| Jumbo Ugg Boots |
| Others |
Pricing and Supply Chain Analysis
Captive sourcing of Australian Merino twin-faced hides anchors supply positioning and pricing power for heritage-tier producers, while contract manufacturers dependent on spot-market sheepskin procurement face margin compression from drought-induced raw material volatility and currency fluctuation.
Pricing Analysis
Volume concentrates in commoditized synthetic fleece tiers while margins pool in sheepskin-certified premium positioning. Price differentiation hinges on REACH-compliant tanning chemistry and Australian provenance credentials. Cost compression in mass-market channels intensifies as recycled polyester alternatives from Chinese textile mills capture price-sensitive volume. Urban millennials in New York and Los Angeles show lowest price elasticity for heritage-provenance products, while private-label importers serving discount retailers face highest buyer sensitivity.
Supply Chain Analysis
Reverse-logistics infrastructure for sheepskin recycling in the Netherlands is creating closed-loop material flows that reshape downstream value capture. Raw material sourcing draws from Australian Merino wool belt processors, Italian REACH-compliant tanneries, and Chinese synthetic textile mills. Supply chain risk centers on drought-induced raw material volatility in New South Wales and Victoria. Distribution runs through direct-to-consumer digital platforms, premium urban flagship locations, and third-party department store partnerships with inventory risk transfer.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is forcing consolidation as smaller private-label importers lack capital to absorb multi-jurisdiction testing protocols and reformulation investments.
For Market Incumbents: Acquire captive sheepskin processing capacity in Australian Merino wool belt regions to secure raw material availability against drought volatility. Invest in in-house REACH and Proposition 65 compliance teams to absorb regulatory costs that burden smaller competitors. Control wholesale distribution selectively while expanding owned digital platforms to capture first-party behavioral data and bypass margin compression. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable channel for unisex positioning targeting urban male consumers previously excluded from category marketing. Target Nordic markets where thermal insulation ratings drive year-round purchase conversion and price elasticity remains low. Leverage water-based polyurethane coating partnerships with Italian tanneries to shortcut REACH-compliant material access without captive chemistry investments. For Investors and Strategic Acquirers: Exit pathways concentrate in heritage-provenance brand acquisitions by larger footwear conglomerates seeking Australian sourcing credentials. Long-term viability favors targets with backward-integrated sheepskin supply or certified compliant tanning partnerships rather than contract-manufacturing dependent models. Watch drought severity indices in Australian wool belt regions as inflection indicator for raw material cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Australian Sheepskin Sourcing | Captive supply of Merino twin-faced hides insulates margins from drought-induced volatility and currency fluctuation. |
| REACH-Compliant Tanning Chemistry Investment | Chromium-free alternatives unlock German and French department store placement previously closed to conventional suppliers. |
| Direct-to-Consumer Platform Expansion | Owned digital channels bypass wholesale margin compression while capturing first-party data for personalization in New York and Los Angeles density corridors. |
| Circular Take-Back Program Development | Sheepskin recycling infrastructure in the Netherlands creates closed-loop brand differentiation and material cost recovery. |
| Urban Millennial Subscription Model Launch | Monthly styling services displace seasonal department store purchases among 25-34 age cohorts prioritizing wardrobe versatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across brand managers at heritage footwear houses, category buyers at premium department stores, supply planners at Australian tanneries, and channel sales heads at direct-to-consumer platforms. ECHA REACH substance restriction databases, US CPSC flammability standard filings, California OEHHA Proposition 65 chemical listings, and Australian Bureau of Agricultural and Resource Economics wool production statistics provided validation layers. Bottom-up demand modeling triangulated against top-down macroeconomic consumption indicators.
Data-stream reconciliation across shipment volumes, retail audit panels, and consumer survey panels informed the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, material specification, end-user demographic, and distribution channel control. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for regulatory phase-in timelines and material substitution elasticities. Thermal insulation rating adoption curves in Nordic markets and subscription service penetration rates in US urban corridors served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Australian sheepskin tariff treatment, catastrophic drought events exceeding historical severity bands, and synthetic fleece technological breakthroughs achieving parity with natural thermal performance. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and consumer willingness-to-pay for provenance credentials. Material deviation in drought indices, REACH substance restriction expansions, or Proposition 65 enforcement patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Barefoot Shoes Market
Footwear
Europe Footwear Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Refurbished Sneaker Market
Footwear
Riding Boots Market
Footwear
Protective Footwear Market
Footwear
Trail Running Shoes Market
Footwear
Luxury Footwear Market
Footwear
Global Men Leather Shoes Market
Footwear
Cyber-Shoes Market
Footwear
Athletic Footwear Market
Footwear
Europe Barefoot Shoes Market
Footwear
Self-Lacing Shoes Market
Footwear
Platform Boots Market
Footwear
Ankle Boots Market
Footwear
Orthopedic Footwear Market