
 Running Shoes Market | 2026-2036
Running Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Running Shoes Market Analysis
Premium cushioning tiers is rotating toward carbon-plated super shoes and bio-based midsole foams. Nike sustains technology leadership through proprietary Air Zoom and React foam platforms. Brooks specializes in biomechanically tuned stability systems for overpronators. Hoka dominates maximalist geometry with oversized stack heights that absorb impact for ultra-distance runners.
Running shoes are athletic footwear engineered with differential-density midsole compounds, engineered mesh uppers, and outsole tread patterns optimized for gait biomechanics and surface contact. Manufacturers injection-mold ethylene-vinyl acetate and thermoplastic polyurethane foams to achieve targeted energy return coefficients and compression set resilience. Neutral shoes command the largest volume pool as everyday runners prioritize versatility over correction. Stability shoes retain margin concentration among specialty retailers serving injury-prone athletes. Online retail channels capture the fastest expansion as direct-to-consumer platforms bypass wholesale markups and enable customization tools.
The US Consumer Product Safety Commission enforces flammability and chemical exposure limits, while California's Proposition 65 mandates warning labels for substances like phthalates in synthetic uppers. The EU REACH regulation restricts per- and polyfluoroalkyl substances in water-repellent coatings, compelling reformulation of durable water repellent treatments. China's SAMR administers GB/T standards for footwear flex resistance and sole adhesion that factories must certify before domestic sale. Stakeholders must monitor how extended producer responsibility frameworks in the European Union and pending US state-level footwear recycling bills reshape material sourcing obligations and end-of-life collection infrastructure.
Market Dynamics
Carbon-plated super shoes are compressing price-performance tradeoffs across all cushioning tiers, forcing manufacturers to recalibrate midsole chemistry roadmaps and factory tooling investments simultaneously.
Growth Catalysts
- EU REACH chemical restrictions:Per- and polyfluoroalkyl substance bans on water-repellent coatings are accelerating bio-based durable water repellent formulation, opening premium positioning for compliant suppliers.
- Vietnam manufacturing clusters:Concentrated injection-molding capacity near Ho Chi Minh City is shortening lead times for ethylene-vinyl acetate midsole production.
- Trail running participation:Technical footwear demand from female ultra-distance runners is expanding the addressable market for maximalist geometry and aggressive outsole tread patterns.
Market Restraints
- Petrochemical feedstock volatility:Ethylene-vinyl acetate and thermoplastic polyurethane resin prices fluctuate with crude oil indices, compressing margin predictability for foam compounders.
- Single-region supply concentration:Vietnam hosts over seventy percent of branded athletic footwear assembly, creating vulnerability to port congestion and labor availability shocks.
- California Proposition 65 enforcement:Warning label mandates for phthalates in synthetic uppers impose litigation exposure and reformulation costs on brands distributing in the state.
Strategic Opportunities
- Extended producer responsibility frameworks:EU end-of-life collection infrastructure mandates create first-mover advantage for brands building closed-loop recycling partnerships with thermoplastic polyurethane reclaimers.
- Direct-to-consumer customization platforms:Online retail channels enable biomechanical data capture and made-to-order midsole density tuning, bypassing wholesale margin extraction.
- China domestic market expansion:GB/T flex resistance and sole adhesion certification requirements favor established manufacturers with in-country testing capabilities.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized gait analysis and computational modeling expertise concentrates at a handful of university programs and incumbent brands.
- Carbon plate integration complexity:Bonding dissimilar materials in high-stack midsole assemblies requires precision molding equipment and defect detection systems that smaller suppliers cannot access.
- Multi-jurisdiction compliance timelines:Simultaneous navigation of US CPSC flammability standards, EU REACH substance restrictions, and China SAMR GB certifications extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Running Shoes Market |
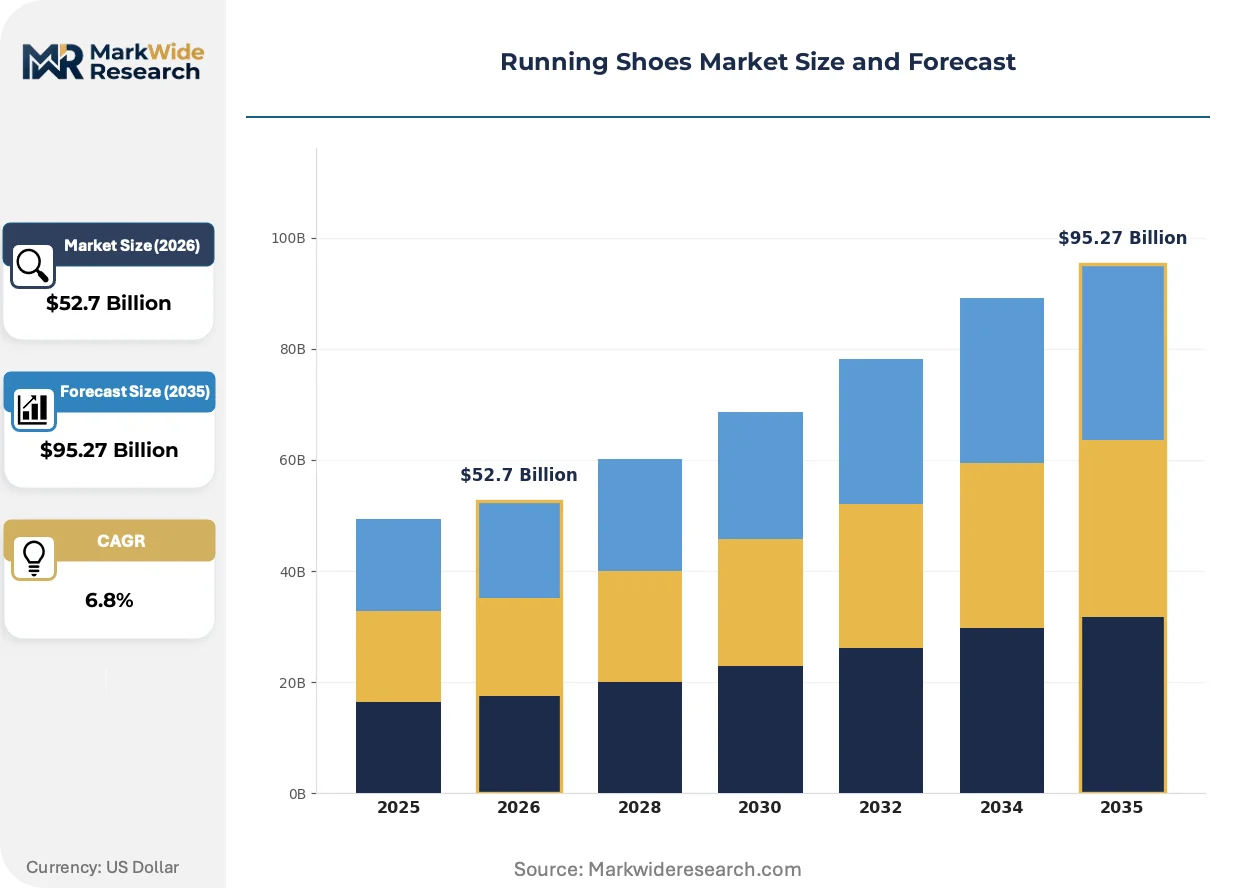
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neutral Shoes, Stability Shoes, Motion Control Shoes, Minimalist Shoes End User: Men, Women, Children, Seniors Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Stores Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Nike, Brooks, New Balance, ON Running, Saucony, Asics, Adidas, Hoka, Puma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Running Shoes Market Emerging Trajectories
Bio-based midsole foams and computational design tools are rewriting material specifications and manufacturing workflows. Three developments merit close attention.
Peba-based super foams are displacing traditional ethylene-vinyl acetate in performance tiers. Elite marathoners and competitive age-group athletes now expect energy return coefficients above eighty-five percent. This chemistry shift is compressing the viable shelf life of legacy midsole platforms and forcing wholesale retooling of injection-molding lines.
California's SB 657 supply chain transparency requirements are mandating factory-level disclosure of labor practices and environmental compliance. Brands must now map tier-two and tier-three suppliers for synthetic upper textiles and rubber outsole compounds. Specialty retailers serving injury-prone stability shoe buyers are prioritizing vendors with documented audit trails.
Subscription-based shoe replacement programs are emerging as an alternative to episodic retail purchases. Ultra-distance runners and high-mileage daily trainers value predictable footwear rotation without inventory management. This model is most visible in direct-to-consumer channels targeting runners logging over fifty miles weekly.
Running Shoes Market Segmentation
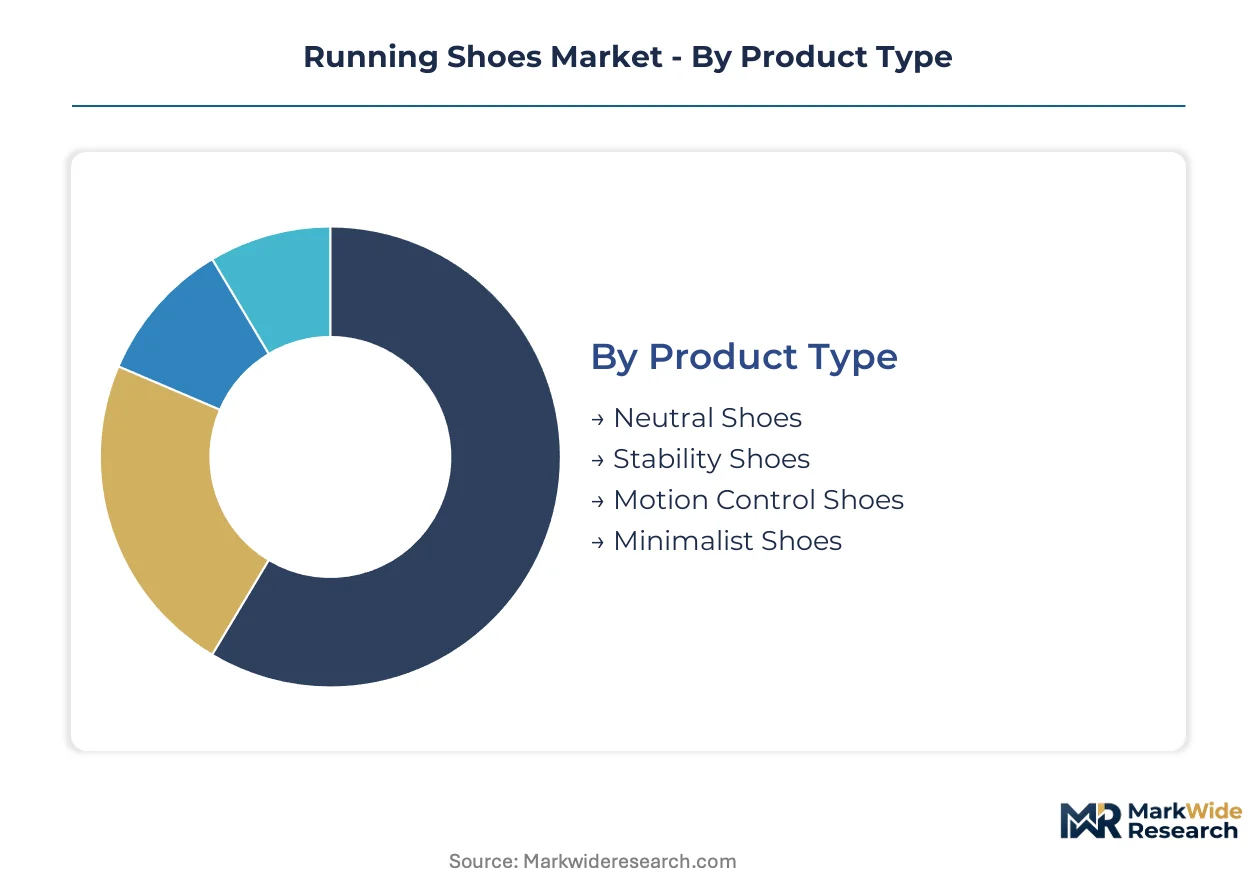
Running shoes manufacturers calibrate product portfolios across four intersecting dimensions. Each segmentation axis carries distinct margin profiles, channel requirements, and regional demand concentrations that shape factory capacity allocation and marketing spend deployment.
Product Type:
Domestic demand in the United States and China concentrates in neutral and stability constructions, while export-led growth from Vietnam targets carbon-plated super shoes for European and Japanese marathoners.
- Neutral Shoes:Engineered with single-density ethylene-vinyl acetate midsoles and flexible forefoot grooves for biomechanically efficient runners. Volume concentrates in North American daily training segments where versatility outweighs correction; specialty retailers in Germany and the United Kingdom report the strongest replenishment rates for this construction.
- Stability Shoes:Incorporate dual-density medial posts and guide rails to manage overpronation through gait cycle control. Demand clusters among injury-prone athletes in Japan and Australia's physiotherapy-linked retail channels; China's domestic market shows accelerating interest as first-time marathoners seek protective footwear.
- Motion Control Shoes:Maximum-support platforms with rigid heel counters and straight last shapes for severe overpronators.
- Minimalist Shoes:Low-drop, thin-soled designs emphasizing ground feel and natural foot strengthening.
Neutral shoes hold the largest share; momentum sits with stability constructions as aging runner demographics prioritize joint protection.
End User:
Cost tier separation is pronounced across gender and age brackets, with women's technical trail shoes commanding premium positioning and children's segments driving volume through replacement frequency.
- Women:Technical footwear with gender-specific lasts and narrower heel counters dominates ultra-distance trail participation. Demand from female runners in California and Colorado is reshaping maximalist geometry roadmaps; European retailers report faster inventory turns for women's carbon-plated racers than men's equivalents.
- Men:Traditional volume anchor with concentration in neutral daily trainers and competition super shoes. Japanese male marathoners sustain premium pricing for Peba-based midsole platforms; Chinese male runners are migrating from budget tiers toward mid-range stability constructions.
- Children:High replacement frequency driven by growth spurts and school sports participation.
- Seniors:Cushioning-focused demand emphasizing impact absorption and slip-resistant outsoles.
Men's segments retain volume leadership; women's technical footwear is climbing the fastest as trail participation accelerates across North America and Europe.
Distribution Channel:
Application context separates channels: online platforms capture data-rich customization, while specialty stores retain biomechanical fitting services for injury-prone athletes.
- Online Retail:Direct-to-consumer platforms with made-to-order midsole density tuning and subscription replacement programs. Growth concentrates in the United States and United Kingdom where runners log fifty-plus weekly miles; bypassing wholesale markups enables price competition against specialty retail.
- Specialty Stores:Gait analysis services and curated stability shoe assortments for injury-prone runners. German and Australian specialty channels maintain margin concentration through physiotherapist partnerships; California's SB 657 transparency requirements favor vendors with documented audit trails.
- Department Stores:Mid-range neutral shoes targeting casual runners and gift purchases.
- Discount Stores:Prioritized budget-tier liquidation and previous-season clearance.
Specialty stores hold the largest share in stability and motion control categories; online retail is gaining share fastest as direct-to-consumer platforms expand customization capabilities.
Price Tier:
Supply concentration shapes tier accessibility: Vietnam's injection-molding clusters enable mid-range volume, while carbon-plated super shoes concentrate premium manufacturing in China and Italy.
- Premium:Carbon-plated super shoes with Peba-based midsoles and engineered mesh uppers. Production concentrates in China's Dongguan cluster for domestic sale and Italy's Montebelluna district for European distribution; energy return coefficients above eighty-five percent define this tier.
- Mid-Range:Ethylene-vinyl acetate and thermoplastic polyurethane foam combinations with regional manufacturing in Vietnam. Volume production near Ho Chi Minh City serves North American and European wholesale channels; this tier captures the broadest runner demographic.
- Budget:Basic injection-molded constructions with simplified upper patterns.
- Luxury:Limited collaborations and fashion-forward aesthetics with minimal performance engineering.
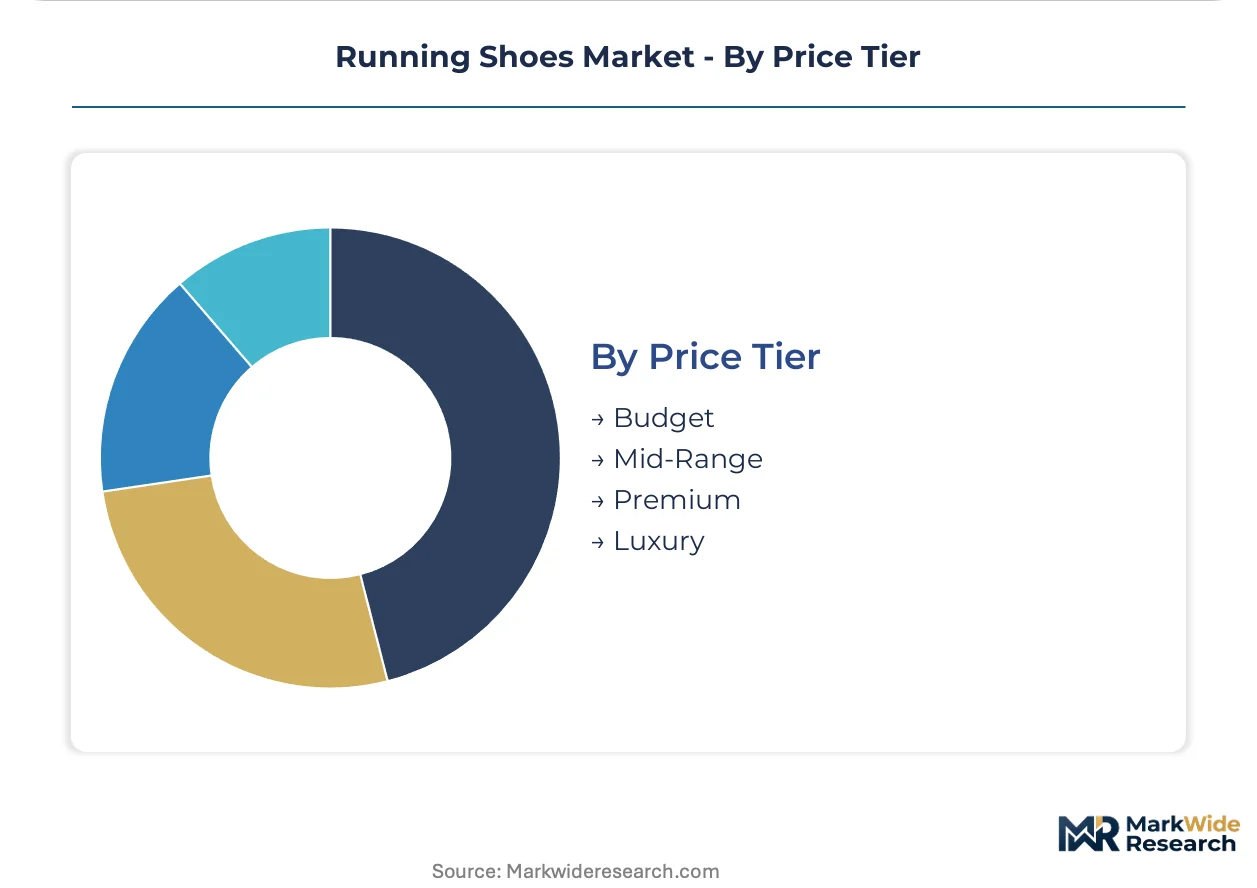
Mid-range tiers hold the largest share; premium constructions are expanding most quickly as competitive age-group runners upgrade from traditional cushioning platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Vietnamese buyers remain highly price-sensitive in mid-range neutral shoes, while Japanese marathoners absorb premium pricing for carbon-plated platforms with minimal volume contraction.
United States
Trail running participation among women in California and Colorado is accelerating purchases of maximalist geometry shoes with aggressive outsole treads. The US Consumer Product Safety Commission enforces flammability standards and chemical exposure limits that elevate compliance costs for synthetic uppers. Manufacturing concentrates in Boston and Boulder specialty retail clusters where physiotherapist-linked gait analysis services drive stability shoe margins.
China
Domestic demand from first-time marathoners is shifting toward mid-range stability constructions with protective cushioning platforms. SAMR administers GB/T standards for footwear flex resistance and sole adhesion that factories must certify before domestic sale. Production gravity centers on Dongguan injection-molding clusters serving both domestic distribution and export assembly for premium carbon-plated tiers.
Germany
Specialty retail channels in Munich and Frankfurt maintain margin concentration through curated stability assortments for injury-prone athletes. ECHA REACH restrictions on per- and polyfluoroalkyl substances in water-repellent coatings compel reformulation of durable water repellent treatments. The Montebelluna district in neighboring Italy supplies premium hand-finished uppers for German marathoner demand.
Japan
Male marathoners in Tokyo and Osaka sustain premium pricing for Peba-based midsole platforms with energy return coefficients above eighty-five percent. METI oversees industrial standards alignment with international footwear testing protocols. Osaka-based specialty retailers report faster inventory turns for women's carbon-plated racers than men's equivalents, reshaping import procurement patterns.
Vietnam
Export-led assembly for North American and European wholesale channels dominates Ho Chi Minh City manufacturing clusters. Over seventy percent of branded athletic footwear assembly concentrates in this single region, creating vulnerability to port congestion shocks. Nike, Adidas, and Puma anchor ethylene-vinyl acetate midsole production with shortened lead times relative to Chinese alternatives.
Running Shoes Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the running shoes market. The vendor base concentrates among a handful of vertically integrated multinationals with proprietary foam platforms and distributed Asian assembly networks. Three archetypes dominate: technology-led innovators with carbon-plated super shoe portfolios, biomechanical specialists tuning stability systems for injury-prone segments, and scale-driven assemblers optimizing Vietnam manufacturing clusters. Competitive moves center on direct-to-consumer platform expansion and closed-loop recycling partnerships with thermoplastic polyurethane reclaimers.
Among technology-led innovators, Nike and Adidas occupy positions defined by proprietary midsole chemistry roadmaps and injection-molding line investments. Brooks exemplifies the biomechanical specialist archetype with stability-focused construction expertise. Hoka represents maximalist geometry leadership through oversized stack height platforms. Asics, Saucony, and New Balance sit within the established multinational tier with diversified product portfolios spanning neutral, stability, and trail constructions. ON Running occupies a distinct position bridging Swiss design heritage with carbon-plated performance engineering.
| Leading Market Players |
|---|
| Nike |
| Brooks |
| New Balance |
| ON Running |
| Saucony |
| Asics |
| Adidas |
| Hoka |
| Puma |
| Others |
Supply Flow & Price Mechanics
EU REACH substance restrictions on per- and polyfluoroalkyl substances gate both supplier qualification and price tier separation, forcing brands to absorb reformulation costs for water-repellent coatings while premium-positioning compliant alternatives. California's Proposition 65 warning mandates for phthalates in synthetic uppers simultaneously elevate litigation exposure and create documented-audit premiums for transparency-verified vendors. This regulatory stacking compresses margin predictability for foam compounders while concentrating pricing power among vertically integrated multinationals with captive chemistry roadmaps.
Pricing Analysis
Subscription-based replacement programs for high-mileage runners now drive lifetime value, with direct-to-consumer platforms capturing recurring revenue from athletes logging fifty-plus weekly miles. Three-tier pricing structure across premium carbon-plated super shoes, mid-range ethylene-vinyl acetate constructions, and budget injection-molded tiers separates energy return coefficients above eighty-five percent from basic cushioning platforms. Price differentiation hinges on certification compliance with California SB 657 transparency requirements and proprietary foam chemistry ownership. Pricing pressure stems from petrochemical feedstock volatility compressing compounder margins, while Vietnamese buyers in mid-range neutral shoes exhibit highest price sensitivity and Japanese marathoners in Peba-based platforms show least elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate ethylene-vinyl acetate midsole production near Ho Chi Minh City, where Nike, Adidas, and Puma anchor shortened lead time operations against Chinese alternatives. Supply concentrates in Vietnam for branded athletic footwear assembly, China for premium carbon-plated component manufacturing, and Italy's Montebelluna district for hand-finished uppers. Raw material dependencies center on ethylene-vinyl acetate resins, thermoplastic polyurethane foams, and Peba-based super foam polymers. Single-region concentration above seventy percent in Vietnamese assembly creates vulnerability to port congestion shocks. Distribution runs through direct-to-consumer platforms bypassing wholesale markups alongside specialty retail channels retaining biomechanical fitting services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: multi-jurisdiction compliance timelines for US CPSC flammability standards, EU REACH restrictions, and China SAMR GB certifications extend product launch cycles and protect incumbent positions.
For Market Incumbents: Secure proprietary foam chemistry roadmaps through backward integration into Peba-based super foam production, insulating margin structures from petrochemical volatility. Control distribution channels by expanding direct-to-consumer platforms with biometric data capture capabilities, countering wholesale margin extraction. Priority lever rests on closed-loop recycling partnerships with thermoplastic polyurethane reclaimers ahead of EU extended producer responsibility mandates. For New Entrants and Emerging Players: Differentiate on biomechanical customization for female ultra-distance trail runners, where technical footwear demand accelerates fastest across California and Colorado markets. Target white-space in subscription-based replacement programs for runners exceeding fifty weekly miles, where inventory management friction creates switching costs. Go-to-market angle emphasizes made-to-order midsole density tuning bypassing wholesale markups entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across carbon-plated super shoe manufacturing, where precision molding equipment and defect detection systems concentrate capability among vertically integrated multinationals. Five-to-ten year viability favors brands with proprietary injection-molding line investments and documented supply chain audit trails. Acquisition target archetype: biomechanical specialists with stability-focused construction expertise and physiotherapy-linked retail channel relationships. Signal to watch is EU extended producer responsibility framework implementation timelines reshaping material sourcing obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Expansion | Bypasses wholesale markups through biometric data capture and customization tools for high-mileage runners. |
| Closed-Loop Recycling Partnership | Builds thermoplastic polyurethane reclaimer relationships ahead of EU extended producer responsibility mandates. |
| Proprietary Foam Chemistry Investment | Secures Peba-based super foam production capacity insulating margins from petrochemical feedstock volatility. |
| Supply Chain Transparency Certification | Maps tier-two and tier-three suppliers to meet California SB 657 factory-level disclosure requirements. |
| Biomechanical Customization Development | Captures female ultra-distance trail participation growth through gender-specific last engineering. |
Methodological Framework
Desk research of trade customs records, SEC footwear sector filings, and synthetic materials pricing databases preceded structured interviews with brand supply chain directors, specialty retail buyers, foam compounder procurement leads, and regulatory compliance officers at multinationals. Primary fieldwork captured factory-level production data from Vietnamese injection-molding clusters and Chinese Dongguan assembly operations. Secondary validation drew from EU ECHA substance restriction databases, US CPSC flammability enforcement records, and China SAMR GB standard certification registries. Bottom-up volume estimates from country-level retail audit data triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across product type, end user gender and age bracket, distribution channel, and price tier dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic demand elasticity assumptions. Industry-specific forecast inputs incorporated trail running participation rates among women in North American markets and carbon-plated super shoe adoption curves among competitive age-group marathoners.
Decision-makers should treat outputs as directional under assumptions of sustained petrochemical feedstock availability and stable Vietnam manufacturing cluster operations; material deviation would warrant model refresh. Forecasts reflect base-case regulatory enforcement timelines for EU REACH substance restrictions and California Proposition 65 warning mandates. Revision becomes warranted when single-region supply concentration in Vietnamese assembly crosses critical vulnerability thresholds from port congestion or labor availability shocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Global Recovery Footwear Market
Footwear
Luxury Footwear Market
Footwear
South America Athletic Footwear Market
Footwear
Barefoot Shoes Market
Footwear
Sandals Market
Footwear
Refurbished Running Shoes Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
Refurbished Sneaker Market
Footwear
Global Footwear Market
Footwear
Custom Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Waterproof Sneakers Market
Footwear
Wedge Boots Market
Footwear
Europe Footwear Market
Footwear
Women's Luxury Footwear Market
Footwear
Chunky Sneaker Market