
 Interlocking Boxes Market | 2026-2036
Interlocking Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Interlocking Boxes Market Foresight
Recycled corrugated fiberboard is recalibrating cost structures across the interlocking boxes category. DS Smith Packaging Limited leverages closed-loop paper sourcing to sustain margin stability in European operations. Smurfit Kappa anchors its competitive position through integrated containerboard-to-box manufacturing networks. Mondi Group differentiates via performance-engineered kraftliner grades that withstand multi-trip handling cycles.
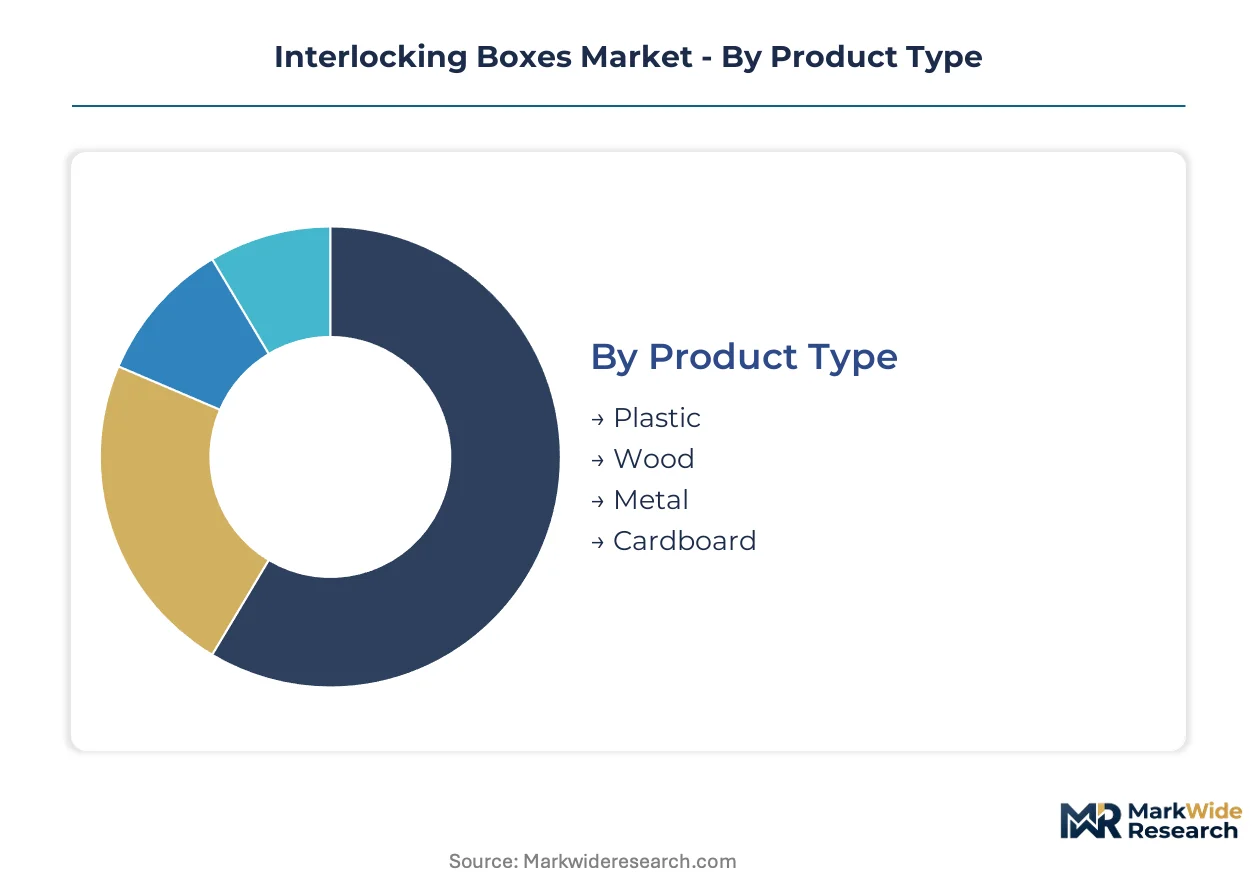
Interlocking boxes are rigid, modular containers engineered with complementary edge profiles or tab-slot mechanisms that enable tool-free assembly and stacking without adhesive or fasteners; wall thicknesses typically range from 3mm to 7mm depending on load-bearing requirements, with flute configurations in corrugated variants calibrated to ECT (Edge Crush Test) ratings. These structures serve primary industrial and commercial purposes in protective distribution, inventory densification, and point-of-purchase presentation. Cardboard variants command the largest volume share due to fiber cost efficiency and established recovery infrastructure, while plastic interlocking formats represent the fastest-expanding segment as warehouse automation demands dimensional consistency and washability across hundreds of use cycles. E-commerce end users concentrate margin pools through high-volume, long-term supply agreements with specification lock-in.
EPA guidelines on recycled content thresholds and the EU Packaging and Packaging Waste Regulation shape material sourcing obligations and extended producer responsibility frameworks for corrugated and plastic box manufacturers. FDA food-contact compliance requirements govern interlocking box specifications in cold-chain grocery distribution, particularly for wax-coated or polymer-lined barrier grades. Stakeholders must monitor how tightening recycled-content mandates in multiple jurisdictions interact with fiber availability constraints and virgin plastic substitution economics.
Market Dynamics
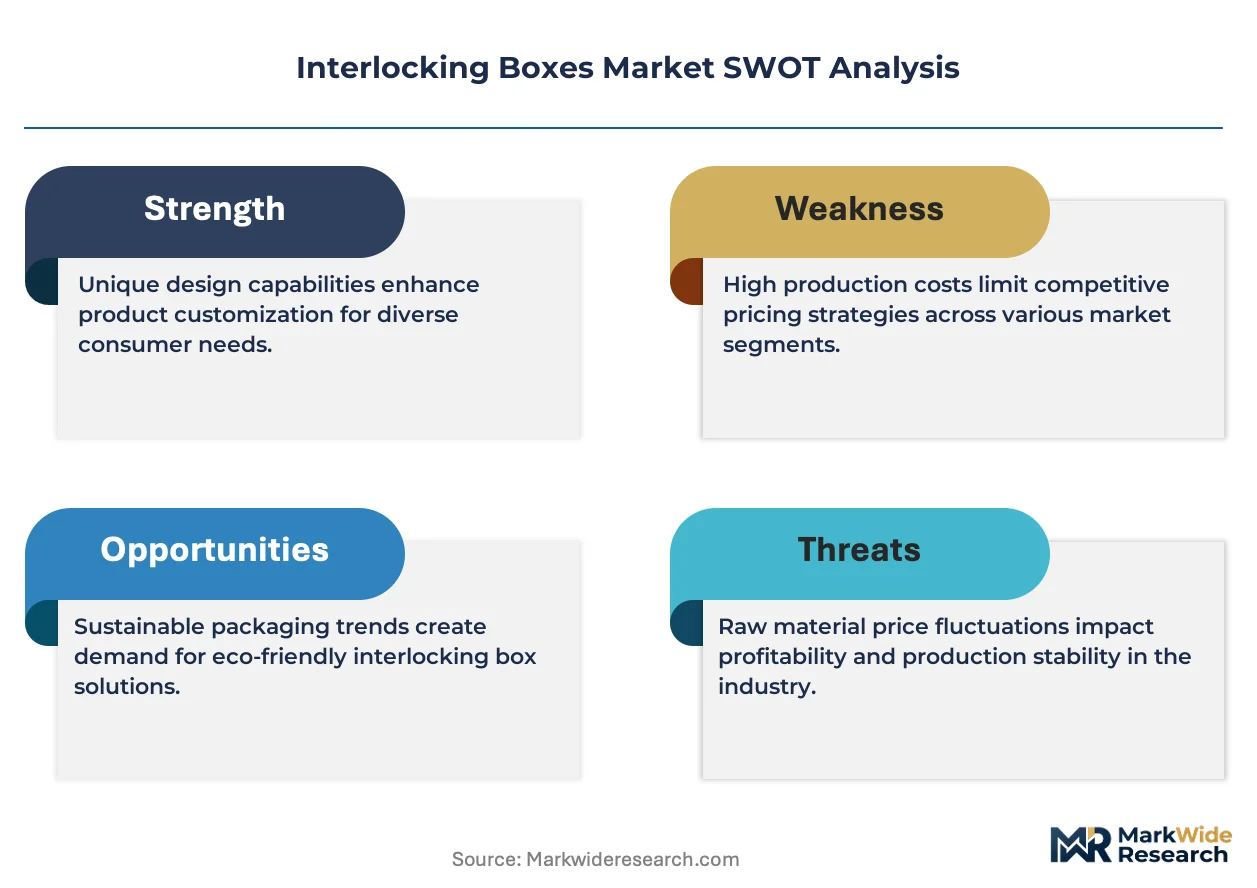
Reusable container standardization across automated fulfillment networks is compressing replacement cycles and forcing corrugated producers to defend specification lock-in through performance engineering rather than cost alone.
Growth Catalysts
- E-commerce fulfillment densification:Automated storage and retrieval systems in Germany's Ruhr logistics corridor demand dimensional tolerances that only precision-engineered interlocking formats deliver.
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds and extended producer responsibility frameworks are accelerating fiber recovery infrastructure investment across member states.
- Closed-loop plastic washing systems:Polypropylene interlocking containers with embedded RFID tracking now complete 200+ use cycles in temperature-controlled pharmaceutical distribution.
Market Restraints
- Old corrugated container availability constraints:Fiber collection rates in Southern Europe lag Northern European recovery infrastructure, creating raw material cost volatility for kraftliner producers.
- Chinese virgin polymer price arbitrage:Import parity fluctuations for polypropylene resin disrupt margin stability for European blow-molded container manufacturers.
- ECT rating ceiling in lightweighting:Current flute engineering limits single-wall corrugated to 32 ECT without transitioning to costlier double-wall construction.
Strategic Opportunities
- Cold-chain grocery expansion in France:Wax-coated and polymer-lined barrier grades for fresh produce distribution remain underpenetrated relative to Nordic markets.
- RFID-NFC convergence in asset tracking:Returnable packaging pools integrating near-field communication chips enable real-time location monitoring across fragmented logistics networks.
- US EPA recycled content procurement guidelines:Federal purchasing mandates create specification pathways for post-consumer fiber interlocking formats in government supply chains.
Industry Challenges
- Automated line integration complexity:E-commerce fulfillment centers require six-month validation periods for new box formats against existing case erectors and sealers.
- Food-contact compliance timeline compression:FDA migration testing for polymer-lined cold-chain formats extends qualification cycles beyond typical procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interlocking Boxes Market |
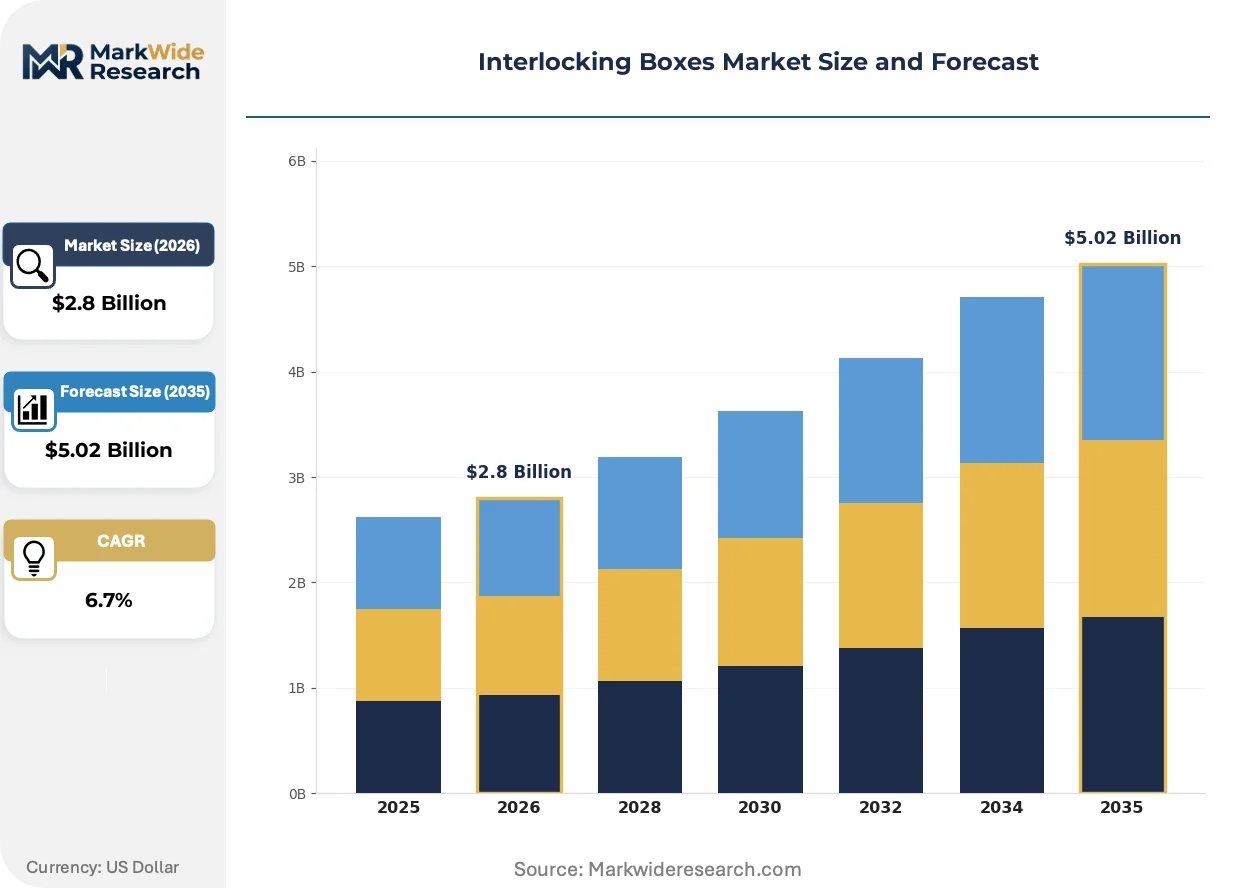
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Wood, Metal, Cardboard Application: Storage, Transportation, Display, Organization Size: Small, Medium, Large, Extra Large End User: Retail, E-Commerce, Industrial, Household |
| Companies Covered | DS Smith Packaging Limited, WestRock, Smurfit Kappa, International Paper Company, Mondi Group, Pratt Industries, Rengo Co., Georgia-Pacific, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interlocking Boxes Market Shifts & Advancements
Material science advances and regulatory compliance automation are converging to redefine performance benchmarks across fiber and polymer interlocking formats. Specification engineering now prioritizes multi-trip durability over single-use cost minimization.
High-performance kraftliner grades with enhanced moisture resistance are converging with automated case handling systems to enable direct-to-consumer shipment without secondary protective wrapping. Third-party logistics providers in the Netherlands and Belgium are specifying these formats for electronics and cosmetics verticals where unboxing experience drives brand equity. The structural consequence is compressing demand for traditional RSC shipping containers in premium e-commerce segments.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating oil and grease resistant coatings from food-contact corrugated specifications. German packaging converters are accelerating migration to bio-based barrier treatments derived from chitosan and alginate. Cold-chain grocery distributors in Bavaria and Baden-Württemberg face the most acute reformulation pressure given their concentration of ready-meal and fresh-produce distribution centers.
Asset-pooling models for returnable plastic containers are displacing single-use corrugated in closed-loop automotive component supply chains. Tier-one suppliers to Stuttgart and Wolfsburg manufacturing clusters now contract directly with pooling operators rather than purchasing disposable packaging. This behavioral shift concentrates procurement authority with fleet management specialists rather than plant-level packaging engineers.
Interlocking Boxes Market Segmentation
Interlocking box procurement splits sharply between standardized formats for high-velocity fulfillment and engineered specifications for specialized handling. Material selection, dimensional calibration, and end-use durability requirements create distinct margin pools across each segmentation axis.
Product Type:
Customization intensity spans from commodity fiberboard to precision-molded polymers, with standardization pressure tightening most aggressively in automated warehouse environments.
- Plastic:Polypropylene and HDPE formulations deliver dimensional tolerances within ±0.5mm for automated storage and retrieval systems. Pharmaceutical distributors in Germany's Rhine-Main logistics corridor specify RFID-embedded variants for 200+ cycle returnable pools. Demand concentrates where washability and barcode readability survive repeated handling.
- Cardboard:Corrugated fiberboard with ECT-calibrated flute structures dominates volume through cost efficiency and established recovery infrastructure. E-commerce fulfillment centers in the Netherlands specify moisture-resistant kraftliner grades for direct-to-consumer electronics shipment without secondary wrapping.
- Metal:Steel interlocking formats serve heavy-component manufacturing in Stuttgart's automotive cluster, where 500kg+ load ratings exceed polymer structural limits. Specifications prioritize stack stability over weight minimization.
- Wood:Plywood and engineered timber formats persist in artisan retail display and premium unboxing applications where tactile warmth supports brand positioning. Volume is contracting as fiberboard surface printing quality improves.
Most installed capacity flows through Cardboard. Expansion is steepest in Plastic.
Application:
Functional requirements diverge across handling intensity, with transportation applications demanding crush resistance and display segments prioritizing visual surface quality.
- Transportation:Multi-modal shipment subjects interlocking boxes to compression, vibration, and moisture exposure across extended distribution chains. Cold-chain grocery distributors in France specify wax-coated or polymer-lined barrier grades for fresh produce integrity during 48-hour transit windows.
- Storage:Static warehousing applications emphasize stack height optimization and inventory densification. Automated fulfillment networks in Belgium require precise external dimensions for robotic bin handling systems.
- Display:Point-of-purchase presentation demands printable surfaces and clean edge profiles for brand messaging. Cosmetics verticals in premium retail channels drive specification toward white-top kraftliner with high-resolution lithographic compatibility.
- Organization:Modular compartmentalization for workshop and backroom applications favors standardized small-format plastic containers with label holder integration. Demand fragments across industrial maintenance and household segments with limited volume concentration.
Transportation commands the largest revenue pool. Display is gaining share fastest in premium e-commerce verticals.
Size:
Dimensional standardization enables pallet optimization and automated handling, while non-standard sizes capture niche positioning in specialized logistics.
- Medium:Euro-pallet footprint compatibility (400mm × 600mm base dimensions) dominates procurement volume across European distribution networks. This format maximizes truck cube utilization while maintaining manual handling ergonomics.
- Large:Industrial component shipment and bulk retail replenishment drive demand for 800mm × 600mm formats. Automotive tier-one suppliers in Wolfsburg specify these dimensions for just-in-sequence line-feed compatibility.
- Small:Electronics accessories, pharmaceutical unit-dose distribution, and cosmetics sampling concentrate demand in sub-300mm formats. E-commerce pick-and-pack operations favor these sizes for single-item shipment efficiency.
- Extra Large:Furniture flat-pack and appliance component logistics require reinforced wall structures and extended tab-slot engagement lengths. Volume is constrained by manual handling limitations and specialized material requirements.
Medium formats carry the highest unit volume. Small formats are climbing the fastest as parcel shipment fragmentation accelerates.
End User:
Procurement authority and specification complexity vary sharply between centralized industrial buyers and fragmented household purchasers.
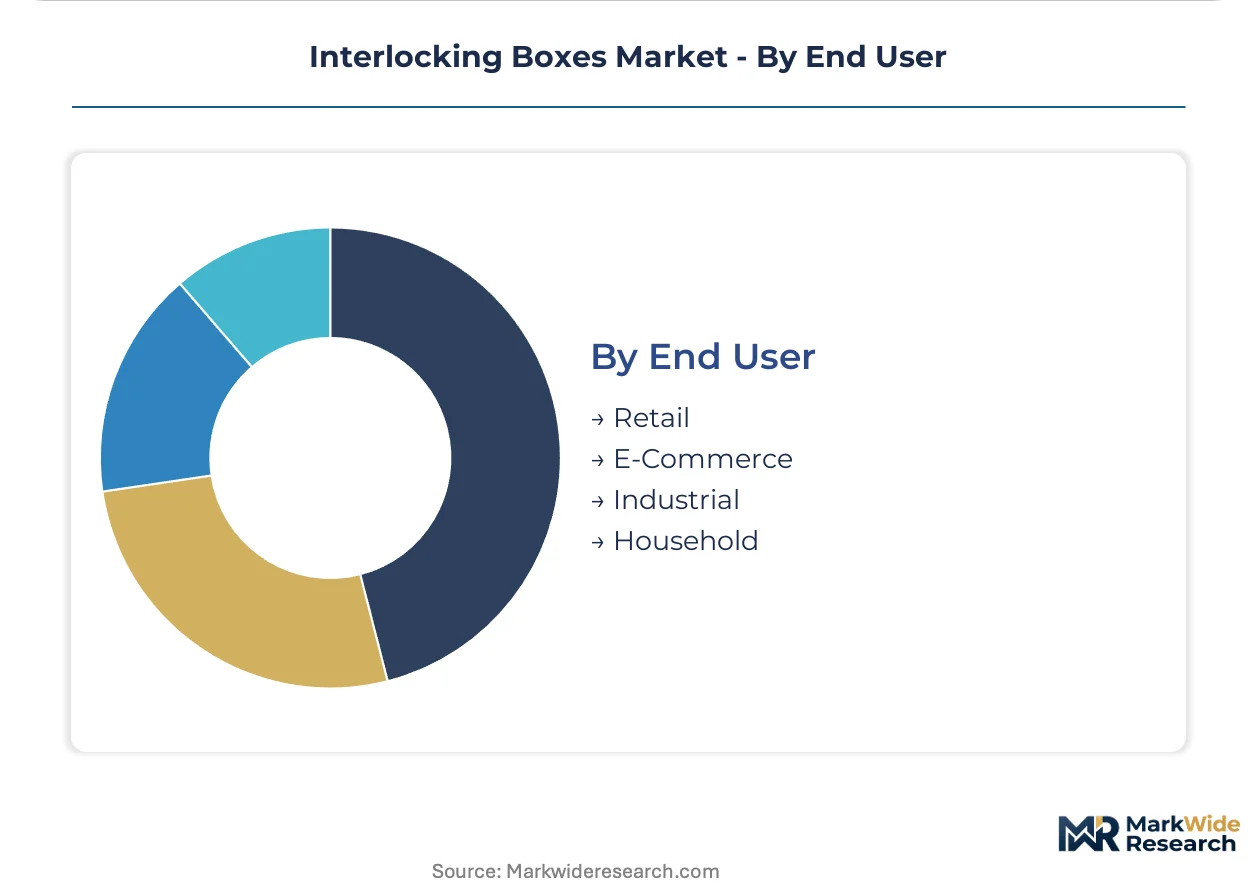
- E-Commerce:Platform operators and third-party logistics providers consolidate massive procurement volumes with multi-year specification lock-in. Germany's Ruhr logistics corridor hosts the densest concentration of automated fulfillment centers demanding precision-engineered interlocking tolerances.
- Industrial:Manufacturing and distribution operations specify returnable container pools with embedded tracking and wash-down compatibility. REACH compliance on barrier coatings constrains material selection for food-contact applications in Bavaria processing facilities.
- Retail:Mass merchandisers balance shelf-ready presentation with backroom storage efficiency. Private label penetration drives standardization toward supplier-agnostic formats.
- Household:Consumer purchasing through home improvement and office supply channels prioritizes visual appeal and ease of assembly over structural performance. Price sensitivity limits specification complexity.
E-Commerce channels concentrate the most procurement authority. Industrial segments are expanding most quickly as returnable container pools displace single-use corrugated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr logistics corridor concentrates the densest deployment of automated fulfillment infrastructure for interlocking box procurement. E-commerce densification and EU regulatory mandates are recalibrating demand patterns across multiple national markets. Procurement authority is consolidating around third-party logistics operators with multi-year specification lock-in.
United States
Federal purchasing mandates under EPA recycled content guidelines are opening specification pathways for post-consumer fiber formats in government supply chains. FDA food-contact compliance requirements govern cold-chain grocery distribution specifications. E-commerce fulfillment centers in the Pacific Northwest are expanding automated storage and retrieval system deployments.
Germany
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating oil and grease resistant coatings from food-contact corrugated specifications. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds and extended producer responsibility frameworks. Bavaria and Baden-Württemberg processing facilities face acute reformulation pressure for ready-meal distribution.
France
Cold-chain grocery expansion for fresh produce distribution drives specification of wax-coated and polymer-lined barrier grades. ECHA compliance timelines compress qualification cycles for migration-tested formats. Paris Basin logistics operators are consolidating procurement authority for temperature-controlled pharmaceutical distribution.
Netherlands
Third-party logistics providers specify high-performance kraftliner grades with enhanced moisture resistance for direct-to-consumer electronics shipment. The EU Green Deal accelerates fiber recovery infrastructure investment. Rotterdam-Antwerp port corridor facilities demand dimensional tolerances for automated case handling systems.
China
Virgin polymer price arbitrage for polypropylene resin disrupts margin stability for blow-molded container manufacturing. GB standards and MIIT industrial policy shape material sourcing obligations. Yangtze River Delta fulfillment centers are expanding reusable container standardization across automated networks.
Interlocking Boxes Market Competitive Landscape
Capacity expansion dominates the current landscape as producers defend specification lock-in through performance engineering investments. The vendor base clusters around integrated containerboard-to-box manufacturers, specialized barrier coating developers, and precision-molded polymer fabricators. Three archetypes define competitive positioning: fiber-based integrated producers, polymer returnable container specialists, and regional converters with logistics proximity advantages. M&A activity and strategic partnerships concentrate procurement authority with fleet management operators.
Among fiber-based integrated producers, DS Smith Packaging Limited and Smurfit Kappa exemplify the closed-loop sourcing archetype, while Mondi Group occupies a position emphasizing performance-engineered kraftliner grades. These entities represent the premium-tier vector where multi-trip durability specifications command margin premiums over commodity corrugated alternatives.
| Leading Market Players |
|---|
| DS Smith Packaging Limited |
| WestRock |
| Smurfit Kappa |
| International Paper Company |
| Mondi Group |
| Pratt Industries |
| Rengo Co. |
| Georgia-Pacific |
| Stora Enso |
| Others |
Supply & Pricing Matrix
RFID-embedded container standardization across German automated fulfillment networks compresses replacement cycles while simultaneously concentrating procurement authority with third-party logistics operators. This dual shift recalibrates cost economics toward multi-trip durability specifications and narrows supplier margins on commodity fiberboard formats.
Pricing Analysis
Input-cost pass-through from kraftliner and polypropylene resin governs interlocking box pricing dynamics. Three-tier pricing structure across premium performance-engineered, standard corrugated, and economy recycled grades differentiates by ECT rating and washability certification. Pricing pressure stems from Chinese virgin polymer arbitrage disrupting European blow-molded container margins. E-commerce fulfillment centers exhibit lowest price sensitivity due to specification lock-in, while household retail channels face acute cost compression.
Supply Chain Analysis
REACH compliance and FDA food-contact qualification gating constrain supplier entry across European and North American markets. Manufacturing concentrates in Germany, China, and the United States, with raw material dependencies on Swedish kraft pulp, Middle Eastern polypropylene resin, and recovered old corrugated containers. Single-source vulnerability runs through Yangtze River Delta virgin polymer supply. Distribution feeds through integrated containerboard-to-box manufacturers and regional pooling operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in interlocking boxes rests on specification engineering for multi-trip durability rather than fiber cost minimization. Premium-tier shifts toward RFID-embedded returnable pools concentrate value capture with fleet management specialists.
For Market Incumbents: Lock in specification lock-in through performance-engineered kraftliner grades that exceed ECT 32 thresholds without double-wall cost penalties. Defend against plastic returnable pool displacement by embedding IoT tracking in corrugated formats and securing multi-year e-commerce fulfillment contracts. For New Entrants and Emerging Players: Begin with cold-chain grocery barrier grades in France where wax-coated and polymer-lined specifications remain underpenetrated relative to Nordic markets. Target Bavaria processing facilities facing REACH-driven reformulation pressure for ready-meal distribution with bio-based chitosan barrier alternatives. For Investors and Strategic Acquirers: Roll-up economics work for regional converters with logistics proximity advantages because automated line integration complexity creates six-month validation barriers against new formats. Acquisition candidates with embedded RFID-NFC capabilities and EU Packaging and Packaging Waste Regulation compliance infrastructure offer defensive positioning. Watch for inflection when federal purchasing mandates under EPA recycled content guidelines accelerate specification pathways in government supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Engineered Kraftliner Investment | ECT ratings above 32 enable premium pricing in e-commerce direct-to-consumer shipment without secondary wrapping. |
| RFID-NFC Embedded Container Launch | Real-time location monitoring across fragmented logistics networks supports 200+ cycle returnable pool economics. |
| Bio-Based Barrier Coating Development | Chitosan and alginate treatments replace per- and polyfluoroalkyl substances under REACH substance restrictions. |
| Backward Integration into Recovered Fiber | Closed-loop paper sourcing insulates margin stability against old corrugated container availability volatility. |
| Cold-Chain Grocery Specification Partnership | Wax-coated and polymer-lined barrier grades capture fresh produce distribution expansion in France. |
Research Methodology
Bottom-up e-commerce fulfillment modeling reconciled against top-down containerboard production tracking forms the analytical core of this study. Primary interviews with packaging procurement managers at third-party logistics providers, plant engineers at automotive tier-one suppliers, regulatory affairs leads at barrier coating developers, and category buyers at mass merchandisers combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, EPA recycled content guidelines, FDA food-contact compliance databases, and customs trade data. Cross-referencing bottom-up demand estimates with top-down supply capacity triangulates volume and value outputs.
Input-output matrices map kraftliner grade production, polypropylene resin consumption, and automated storage and retrieval system deployment against end-use demand across transportation, storage, display, and organization applications. Segmentation dimensions include material type, application function, dimensional format, and end-user channel. CAGRs derive from regression analysis of historical substitution patterns between corrugated and plastic formats, calibrated against regulatory mandate implementation timelines. Forecast inputs incorporate EU recycled content threshold enforcement and RFID-embedded container adoption curves.
Caveats apply where virgin polymer price arbitrage, fiber collection rate divergence between Northern and Southern Europe, or accelerated REACH substance restriction timelines could materially shift the outlook. A model refresh is warranted upon material change in federal purchasing mandate implementation or automated line integration validation period compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
End Load Cartoning Machine Market
Cartons
Tablet Cartons Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Soap Boxes Market
Cartons
Beverage Cartons Market
Cartons
Pick and Place Carton Packers Market
Cartons
Microwaveable Carton Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
GCC Folding Carton Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Metallized Folding Cartons Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Carton Liners Market
Cartons
Digital Folding Cartons Market