
 Mono Carton Market | 2026-2036
Mono Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Mono Carton Market Analytics
The premium-commodity split in mono carton supply is recalibrating around print complexity and structural integrity specifications. Graphic Packaging International leverages in-house coating technology to dominate beverage multipack applications. International Paper sustains massive North American pulp-to-carton integration. DS Smith competes through lightweighting R&D for e-commerce shipment formats.
A mono carton is a single-wall paperboard container, typically 200–400 gsm, formed through cutting, creasing, and folding without corrugated fluting, designed primarily for retail shelf presentation and product protection. Folding cartons lead volume due to their dominance in food and pharmaceutical blister packs, while rigid boxes command margin pools in luxury personal care and electronics unboxing experiences. Recycled fiber grades are displacing virgin paperboard in European applications as EPR schemes tighten material provenance requirements.
US FDA food-contact regulations and EU REACH restrictions on mineral oil saturated hydrocarbons in recycled board are reshaping material sourcing decisions for multinational carton buyers. India's BIS packaging standards and China's GB/T standards for food contact paper impose divergent testing protocols that complicate unified product platforms. Stakeholders must monitor how Extended Producer Responsibility frameworks in Europe and pending US state-level packaging laws will alter cost allocation between brands and converters.
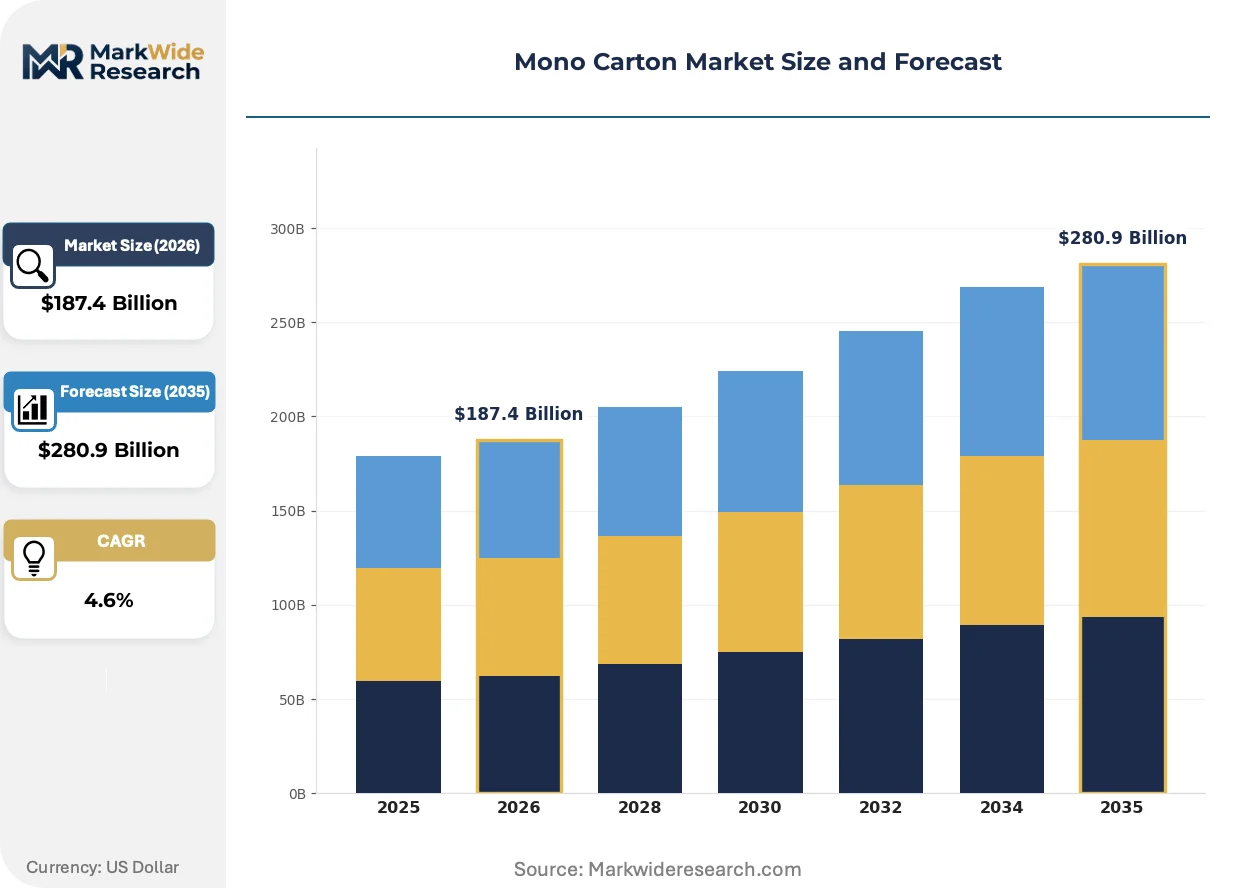
Market Dynamics
Serialization mandates in pharmaceutical packaging are forcing carton converters to integrate track-and-trace hardware with folding lines, compressing equipment replacement cycles and reshaping supplier qualification criteria.
Growth Catalysts
- EU REACH mineral oil restrictions:Recycled fiber substitution is accelerating as converters reformulate coatings to meet hydrocarbon limits, opening technical service revenue streams for chemical suppliers.
- India PLI scheme for food processing:Domestic carton demand is expanding as processed food manufacturers scale packaging localization to capture incentive-linked capacity.
- Blister pack serialization:Pharmaceutical packaging lines are retrofitting carton feeders with vision systems to comply with tightening unit-level traceability requirements.
Market Restraints
- Pulp cost volatility:Kraft linerboard pricing swings are compressing converter margins, particularly for virgin fiber grades in North American beverage multipack applications.
- Recycled fiber contamination thresholds:EU EPR schemes are tightening material provenance requirements, limiting feedstock availability for high-speed folding carton lines.
- Rigid box substitution in luxury:Molded fiber and reusable rigid formats are capturing share in premium personal care unboxing experiences.
Strategic Opportunities
- India CDSCO packaging regulations:Domestic pharmaceutical serialization infrastructure is underdeveloped, creating equipment and service gaps for integrated solution providers.
- E-commerce lightweighting:DS Smith and competitors are developing sub-250 gsm shipper formats that reduce dimensional weight penalties in parcel networks.
- Digital print convergence:Hybrid offset-inkjet lines are enabling run-length flexibility for regional brand SKU proliferation without plate changeover downtime.
Industry Challenges
- Serialization systems integration:Pharmaceutical converters face compressed timelines to validate hardware-software interfaces against evolving national traceability databases.
- Recycled fiber qualification:FDA food-contact notification processes for post-consumer content are extending material approval cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mono Carton Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $280.9 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cartons, Rigid Boxes, Slotted Containers, Die-Cut Boxes Material: Paperboard, Plastic, Recycled Fiber, Coated Paper End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Graphic Packaging International, International Paper, Westrock Company, Unipak Inc., Smurfit Kappa, Amcor, Sonoco, DS Smith, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mono Carton Market Evolving Landscape
Print and structural engineering are fusing as brand owners demand shorter runs with regional versioning, while regulatory chemistry constraints are forcing coating reformulation across the supply base.
Water-based barrier coatings are converging with conventional polyethylene extrusion as beverage and frozen food brands seek heat-seal performance without compromising fiber recyclability. Mid-size converters in Germany and the Netherlands are piloting these formulations for dairy and ready-meal applications. The technology is converging with existing board grades to maintain press speeds while eliminating plastic separation steps in recycling streams.
EU Extended Producer Responsibility frameworks are reallocating end-of-life costs from municipalities to packaging producers, with France's Citeo scheme and Germany's VerpackG imposing fee differentials based on recyclability scores. Carton converters are restructuring customer contracts to pass through EPR compliance costs. Food and personal care brands with pan-European distribution are most affected, consolidating supplier bases to simplify material certification.
Brand procurement teams are compressing supplier panels and demanding integrated design-to-delivery contracts that bundle structural engineering, print, and fulfillment logistics. Retailers in the UK and Scandinavia are pushing this consolidation through preferred supplier programs that penalize fragmented sourcing. Pharmaceutical and cosmetics verticals are the primary arenas where this behavior is visible, with converters investing in in-house design studios to capture upstream specification influence.
Mono Carton Market Segmentation
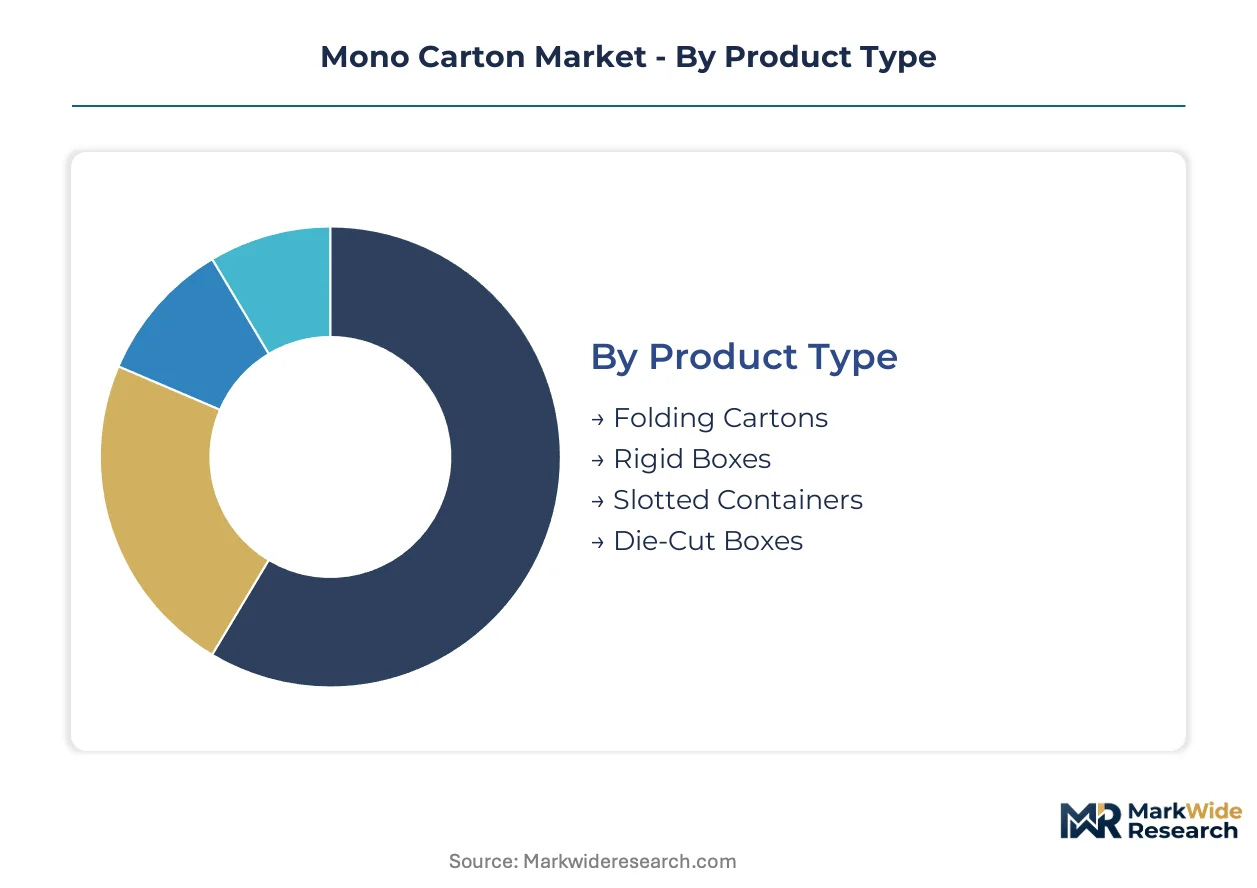
Mono carton segmentation reveals how certification burdens and performance specifications fragment procurement strategies across end-use verticals. Structural format, substrate choice, and channel access each impose distinct compliance and cost architectures that reshape supplier selection criteria.
Product Type:
Folding cartons and rigid boxes carry divergent regulatory loads — pharmaceutical serialization mandates hit folding formats hardest, while luxury rigid boxes face fewer traceability requirements but stricter material provenance rules.
- Folding Cartons:Single-wall paperboard structures formed through cutting, creasing, and folding without corrugated fluting, typically 200–400 gsm. Demand concentrates in pharmaceutical blister packs and food retail where EU FMD serialization and FDA food-contact notifications create dual compliance tracks for converters.
- Rigid Boxes:Thick paperboard or paper-wrapped chipboard constructions with separate base and lid components, engineered for structural rigidity without folding. Premium personal care and electronics unboxing experiences in Germany and France drive specification, with EPR recyclability scores now influencing material selection.
- Slotted Containers:Basic corrugated alternatives with scored folding lines, used for secondary shipping protection.
- Die-Cut Boxes:Custom-shaped formats with intricate cutouts for product display windows or handle integration.
Folding cartons sit at the top of the volume ranking, with rigid boxes climbing the fastest as premium brand owners invest in unboxing differentiation.
Material:
Substrate selection maps directly to end-use certification pathways — food contact approvals, pharmaceutical stability testing, and EPR recyclability scoring each favor different fiber grades and coating systems.
- Paperboard:Virgin fiber grades dominate pharmaceutical and high-moisture food applications where FDA food-contact notifications and EU mineral oil restrictions limit recycled content tolerance. North American beverage multipacks and Indian processed food packaging anchor demand.
- Recycled Fiber:Post-consumer content grades face tightening EU EPR provenance requirements and FDA notification delays of 12–18 months, compressing availability for high-speed folding lines. German dairy and ready-meal converters pilot water-based barrier coatings to maintain recyclability scores.
- Plastic:Polyethylene extrusion and laminated films used where heat-seal performance exceeds fiber-based alternatives.
- Coated Paper:Clay or polymer surface treatments enabling high-fidelity print for retail shelf impact.
Paperboard maintains the broadest certification acceptance, while recycled fiber gains share fastest where EPR fee differentials reward recyclability performance.
End User:
Vertical-specific regulations fragment demand — pharmaceutical serialization, food contact safety, and cosmetic labeling each require dedicated production line configurations and quality systems.
- Pharmaceuticals:Blister pack cartons and secondary packaging for prescription drugs, medical devices, and vaccines. EU FMD and US DSCSA serialization mandates force vision system integration on folding lines, with India's CDSCO regulations creating equipment gaps for domestic manufacturers.
- Food & Beverage:Primary retail packaging for processed foods, dairy, frozen meals, and beverage multipacks. India's PLI scheme for food processing accelerates domestic carton localization as manufacturers scale to capture incentive-linked capacity.
- Personal Care:Premium cosmetics and skincare packaging where unboxing experience drives rigid box specification.
- Electronics:Smartphone, accessory, and device packaging combining protection with retail presentation requirements.
Food and beverage commands the volume lead, with pharmaceuticals expanding most quickly as serialization infrastructure spreads across regulated markets.
Distribution Channel:
Channel choice reshapes run-length economics and print technology requirements — e-commerce shipper formats demand lightweighting R&D while retail channels prioritize shelf impact.
- Online Retail:Direct-to-consumer shipping formats where dimensional weight penalties drive sub-250 gsm specification. DS Smith and competitors develop lightweight shipper designs to reduce parcel network costs.
- Supermarkets:High-volume retail shelf presence requiring regional SKU versioning and promotional flexibility.
- Specialty Stores:Boutique and luxury retail channels where rigid boxes and premium print finishes dominate.
- Wholesale:Bulk distribution formats prioritizing cube efficiency and pallet optimization over shelf presentation.
Supermarkets anchor volume, with online retail gaining share fastest as e-commerce penetration reshapes secondary packaging requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled converter workforces in Germany, India, and the United States anchor regional production capacity. Technical talent concentration in folding carton engineering and pharmaceutical serialization integration shapes geographic competitiveness. Regulatory divergence across FDA, EMA, and CDSCO jurisdictions fragments material certification pathways.
Germany
Beverage multipack and dairy converters cluster around Hamburg and the Ruhr industrial corridor. ECHA REACH mineral oil saturated hydrocarbon limits are forcing coating reformulation across recycled fiber grades. The VerpackG EPR scheme imposes fee differentials based on recyclability scores, restructuring converter-brand contract economics.
India
Domestic carton demand accelerates as processed food manufacturers scale packaging localization. The PLI scheme for food processing incentivizes capacity expansion, while CDSCO pharmaceutical serialization regulations create equipment gaps for domestic converters. Mumbai-Pune and Ahmedabad industrial belts concentrate folding carton production for pharmaceutical blister packs.
United States
FDA food-contact notification processes for post-consumer content extend material approval cycles. Pulp-to-carton integration dominates the Southeast and Pacific Northwest, where International Paper and Westrock maintain captive fiber supply. Kraft linerboard pricing volatility compresses converter margins in beverage multipack applications.
China
GB/T standards for food contact paper impose testing protocols divergent from FDA and EU frameworks. Yangtze River Delta converters serve electronics and personal care brands with rigid box specifications. Dual carbon goals are pressuring energy-intensive coating operations toward water-based barrier formulations.
France
Citeo EPR compliance costs are reallocating end-of-life responsibility from municipalities to packaging producers. Île-de-France and Auvergne-Rhône-Alpes host luxury personal care carton specialists serving L'Oréal and LVMH supply chains. Recyclability scoring now influences rigid box material selection for premium cosmetics unboxing experiences.
Mono Carton Market Competitive Landscape
Top-tier vendors anchor integrated pulp-to-carton supply chains, while mid-cap specialists compete through coating technology and lightweighting R&D. The vendor base stratifies across three tiers: multinational integrated paperboard producers, regional folding carton converters with serialization capabilities, and niche rigid box fabricators serving luxury verticals. Two dominant competitive moves are reshaping positioning: backward integration into captive pulp supply and geographic expansion through acquisition of regional serialization-equipped converters.
Among North American integrated producers, International Paper and Westrock Company exemplify the captive fiber archetype, while Graphic Packaging International occupies a position emphasizing in-house coating technology for beverage applications. DS Smith represents the lightweighting-focused European competitor developing sub-250 gsm e-commerce shipper formats. These three anchors illustrate how scale, coating specialization, and structural engineering R&D define distinct competitive vectors.
| Leading Market Players |
|---|
| Graphic Packaging International |
| International Paper |
| Westrock Company |
| Unipak Inc. |
| Smurfit Kappa |
| Amcor |
| Sonoco |
| DS Smith |
| Huhtamaki |
| Others |
Value Network & Pricing Analysis
Water-based barrier coating adoption across German and Dutch dairy converters is compressing per-unit coating costs while consolidating procurement leverage among early formulation adopters. This production-method transition simultaneously reduces chemical input expenses and rewards integrated converters with scale advantages in EPR-scored material sourcing.
Pricing Analysis
Bundled design-to-delivery contracts versus unbundled component sourcing defines the dominant pricing split. Three-tier pricing structure across pharmaceutical serialization-ready, food-contact certified, and commodity folding grades separates converters by compliance burden. Price differentiation centers on FDA notification status and EU mineral oil certification tiers. Cost compression in commodity beverage multipacks is intensifying because kraft linerboard volatility passes through to spot-contract buyers. Generic pharmaceutical and processed food manufacturers exhibit highest price sensitivity; luxury cosmetics and vaccine packaging buyers show lowest.
Supply Chain Analysis
Regional distribution centers in Hamburg-Ruhr, Mumbai-Pune, and the US Southeast anchor hub-and-spoke patterns for just-in-time pharmaceutical and food-service delivery. Pulp-to-carton integration concentrates in the United States, Germany, and India. Raw material dependencies rest on northern bleached softwood kraft, recycled fiber post-consumer streams, and water-based barrier chemistry feedstocks. Single-source vulnerability runs through Brazilian eucalyptus pulp for virgin grades. Distribution runs through converter-direct brand relationships for pharmaceutical serialization, with food and beverage flowing through consolidated retail procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in coating technology substitution and pharmaceutical serialization service bundling, with water-based barrier adoption reducing chemical input costs by a fifth.
For Market Incumbents: Cement serialization integration advantages by acquiring regional Indian converters lacking CDSCO-compliant vision systems. Deepen captive pulp supply in the US Southeast to insulate against kraft linerboard volatility threatening beverage multipack margins. Molded fiber substitution in luxury unboxing represents the primary displacement threat requiring rigid box format innovation. For New Entrants and Emerging Players: Capture underdeveloped pharmaceutical serialization infrastructure gaps in India's domestic CDSCO compliance market. Target processed food carton localization around PLI scheme incentive zones near Ahmedabad and Mumbai-Pune. Lead with integrated design-studio capabilities to win preferred supplier status with UK and Scandinavian retail consolidation programs. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European converters with water-based barrier pilot capacity but unscaled pharmaceutical serialization lines. Long-term viability hinges on coating chemistry transition completion and EPR fee structure maturation. Monitor India's CDSCO enforcement timeline as inflection indicator for domestic equipment demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pulp Supply | International Paper and Westrock insulate beverage multipack margins from kraft linerboard volatility. |
| Pharmaceutical Serialization Hardware Integration | Vision system retrofitting captures EU FMD and US DSCSA compliance spending across folding lines. |
| Water-Based Barrier Coating Scale-Up | German and Dutch dairy converters meet ECHA REACH mineral oil limits while maintaining recyclability scores. |
| E-Commerce Lightweighting R&D | DS Smith develops sub-250 gsm shipper formats to reduce dimensional weight penalties in parcel networks. |
| Regional Converter Acquisition in India | CDSCO serialization gaps create equipment and service entry points for integrated solution providers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with folding carton plant managers, pharmaceutical packaging procurement leads, food brand supply chain directors, and coating technology R&D heads with secondary validation. Customs trade data, SEC 10-K filings, CDSCO regulatory notices, and ECHA REACH substance restriction updates anchored external benchmarks. Bottom-up capacity modeling and top-down demand estimation triangulated volume outputs.
Historical reference periods anchored the forecast window to pre-serialization mandate baselines and post-EPR implementation trajectories. Segmentation dimensions spanned structural format, fiber grade certification tier, end-use vertical regulatory cluster, and regional production hub concentration. CAGRs derived from regression against pulp cost indices, pharmaceutical packaging capital expenditure cycles, and processed food capacity expansion announcements. EPR fee differential schedules and FDA notification approval timelines fed compliance-cost modeling.
Pulp cost volatility, regulatory enforcement timing shifts, and coating formulation validation failures are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Beverage Cartoners Market
Cartons
Fluted Carton Trays Market
Cartons
Printed Folding Cartons Market
Cartons
Reverse Tuck Cartons Market
Cartons
MET-PET Cartons Market
Cartons
Global Hand Carton Sealers Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Global Cartonboard Market
Cartons
Interlocking Boxes Market
Cartons
Pizza Cartons Market
Cartons
Round Corrugated Box Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
End Load Cartoning Machine Market
Cartons
Japan Corrugated Boxes Market
Cartons
Litho Laminated Cartons Market
Cartons
Carton Bottle Market