
 Printed Folding Cartons Market | 2026-2036
Printed Folding Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Folding Cartons Market Analytics
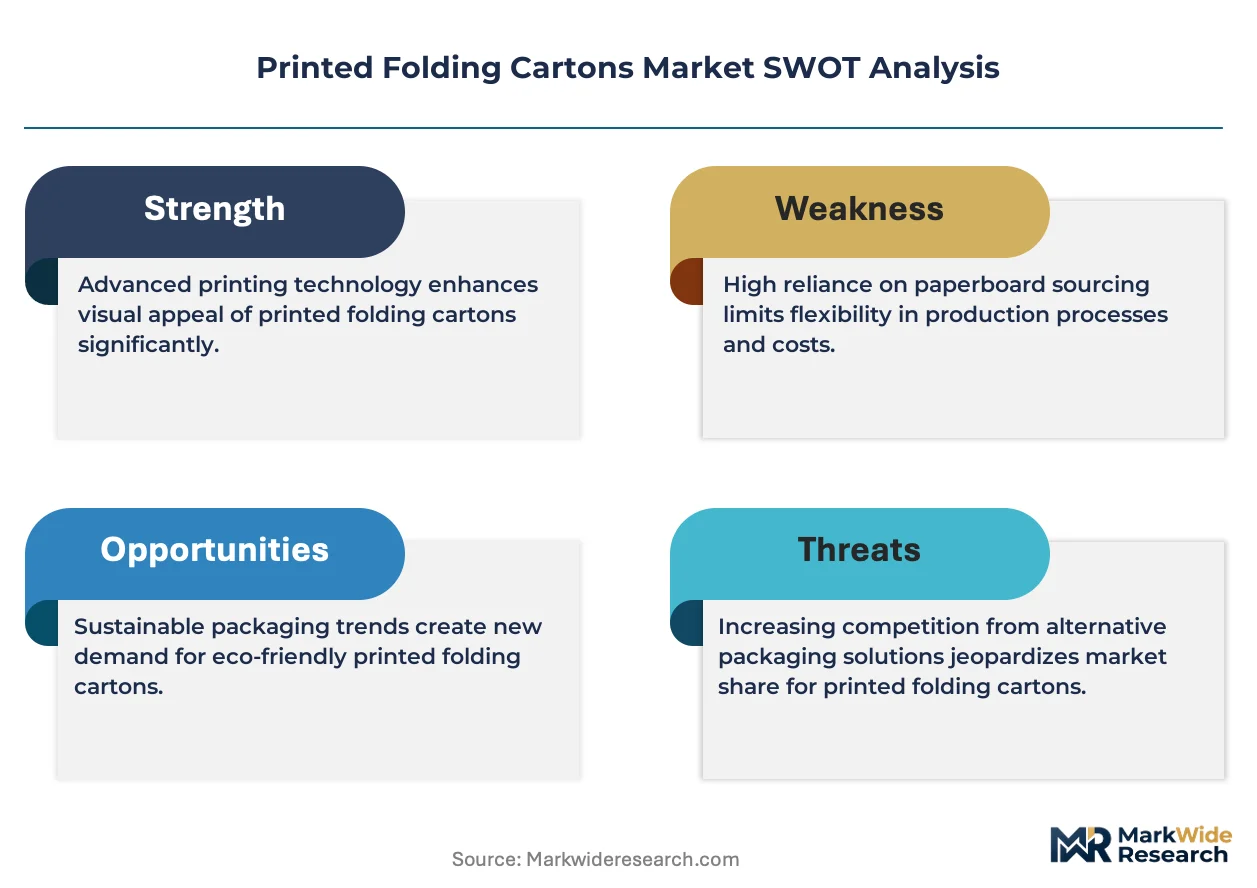
Digital printing integration with inline finishing is tilting production economics toward shorter runs and mass customization. WestRock Company leverages its North American mill network to anchor virgin paperboard supply for high-graphic cartons. Huhtamaki competes through specialized barrier coatings that extend shelf life for dairy and ready-meal applications. DS Smith Plc dominates the European corrugated-to-carton conversion segment with closed-loop recycling infrastructure.
Printed folding cartons are paperboard-based containers manufactured through die-cutting, creasing, and folding processes, typically ranging from 200 to 400 gsm in caliper, designed to protect, display, and dispense consumer goods at retail. Flexographic printing occupies the volume tier in food and beverage applications where brand consistency at scale matters most. Digital printing represents the fastest-expanding segment as pharmaceutical lot sizes shrink and brand owners demand versioned packaging for regional markets. Recycled paper content is maturing as a material category where margin pools compress due to fiber quality inconsistency and contamination control costs.
The FDA enforces strict labeling and child-resistant packaging standards that shape carton design for over-the-counter pharmaceuticals in the United States. The EU Packaging and Packaging Waste Regulation, alongside REACH chemical restrictions, forces material substitutions and recyclability claims verification across European supply chains. The EPA's recycled content guidelines and state-level extended producer responsibility laws in California and New York add compliance layers for domestically sourced paperboard. Stakeholders must monitor how dual-track regulatory evolution—safety mandates in pharmaceuticals versus circularity rules in fast-moving consumer goods—will force capital allocation between barrier technology and fiber recovery systems.
Market Dynamics
Digital printing infrastructure is compressing minimum order quantities from hundreds of thousands to single-digit thousands, fragmenting production economics and forcing carton converters to reconfigure die-cutting and finishing lines for rapid changeovers.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets and extended producer responsibility schemes in Germany, France, and Italy are accelerating fiber-based substitution for rigid plastics in dairy and ready-meal segments.
- Pharmaceutical serialization mandates:Track-and-trace requirements under FDA DSCSA and EU FMD are expanding demand for cartons with integrated variable data printing and tamper-evident features.
- Barrier coating advances:Specialized aqueous and extruded coatings that match plastic oxygen and moisture barriers are unlocking shelf-stable applications for fresh pasta, plant-based proteins, and premium pet food.
Market Restraints
- Virgin paperboard supply concentration:North American and Nordic pulp mill consolidation limits spot market availability during demand surges, forcing converters to accept longer-term offtake contracts with price volatility clauses.
- Recycled fiber quality degradation:Contamination rates in post-consumer mixed paper streams reduce mechanical strength and printability, increasing rejection rates at cartonboard mills and compressing margin pools for recycled-content grades.
- Flexible packaging substitution:Stand-up pouches and flow-wrap formats with high-definition gravure printing are capturing single-serve confectionery and snack applications where carton rigidity adds no functional value.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDMOs supplying regulated markets in North America and Europe require cartons with integrated anti-counterfeiting features and multi-language labeling, creating premium positioning for converters with serialization capabilities.
- Smart packaging convergence:Printed electronics combining NFC tags and conductive inks with conventional carton structures are enabling authentication and consumer engagement in cosmetics and spirits segments.
- Brazilian regulatory alignment:ANVISA's upcoming traceability requirements for prescription medicines will force domestic carton suppliers to upgrade variable-data printing infrastructure or cede share to imported capacity.
Industry Challenges
- Skilled press operator scarcity:Digital hybrid presses combining offset units with inkjet arrays require technicians fluent in both conventional color management and RIP workflow optimization, a profile rare in legacy folding carton workforces.
- Die inventory complexity:Shorter run lengths and version proliferation multiply active cutting forme counts, consuming warehouse space and complicating maintenance scheduling across multi-plant networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Folding Cartons Market |
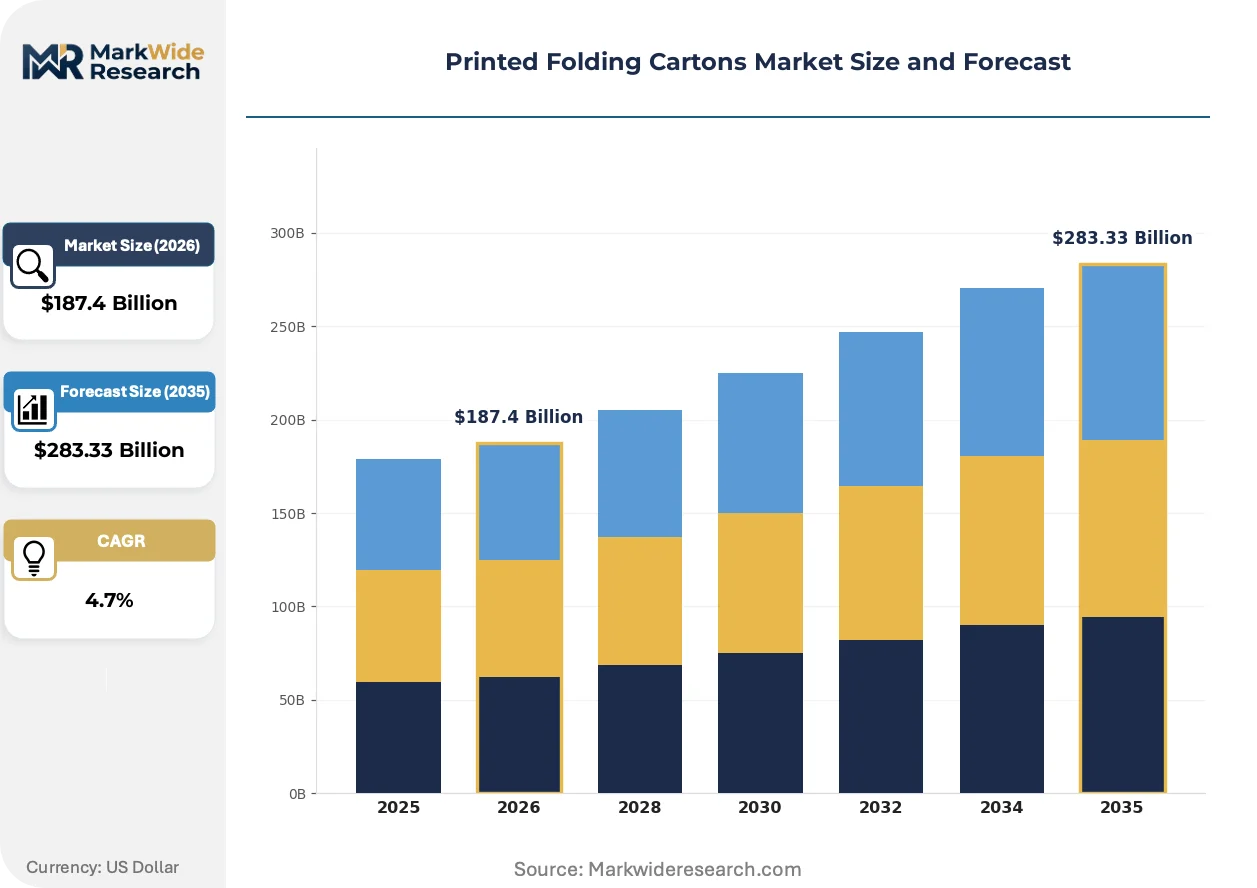
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $283.33 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Slotted Container, Die-Cut Boxes, Folding Cartons, Multi-Depth Boxes Material: Paperboard, Corrugated Fiberboard, Recycled Paper, Coated Paper End User: Food & Beverage, Pharmaceuticals, Cosmetics, Consumer Electronics Printing Technology: Flexographic Printing, Digital Printing, Lithographic Printing, Offset Printing |
| Companies Covered | International Paper Company, Huhtamaki, WestRock Company, DS Smith Plc, Mondi plc, Graphic Packaging International, Mayr-Melnhof Karton AG, Stora Enso Oyj, Smurfit Kappa Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Folding Cartons Market Evolving Landscape
Production workflows are fragmenting as brand owners demand versioned packaging for regional campaigns and limited-edition product drops, compressing lead times from weeks to days and redefining converter capacity planning.
Single-pass inkjet presses with inline coating and die-cutting modules are digitizing job onboarding and makeready processes. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these systems for lot sizes below ten thousand units. This capability is digitizing the economics of regional language variants and country-specific regulatory inserts that previously required dedicated offset campaigns.
REACH chemical restrictions and the EU Green Deal's packaging circularity targets are banning certain fluorinated barrier treatments and mandating design-for-recycling protocols. Carton producers are reformulating coatings and adhesives to maintain grease resistance without compromising fiber recovery yields. Premium chocolate and frozen food brands in Belgium and the Netherlands are switching suppliers to secure compliance ahead of enforcement deadlines.
Brand procurement teams are consolidating carton specifications across regional portfolios to reduce SKU complexity and leverage volume pricing. This concentration is squeezing mid-tier converters without scale or specialized barrier expertise. The shift is most visible in North American beverage and personal care segments where private equity-backed roll-ups are rationalizing supplier panels from dozens to single-digit preferred partnerships.
Printed Folding Cartons Market Segmentation
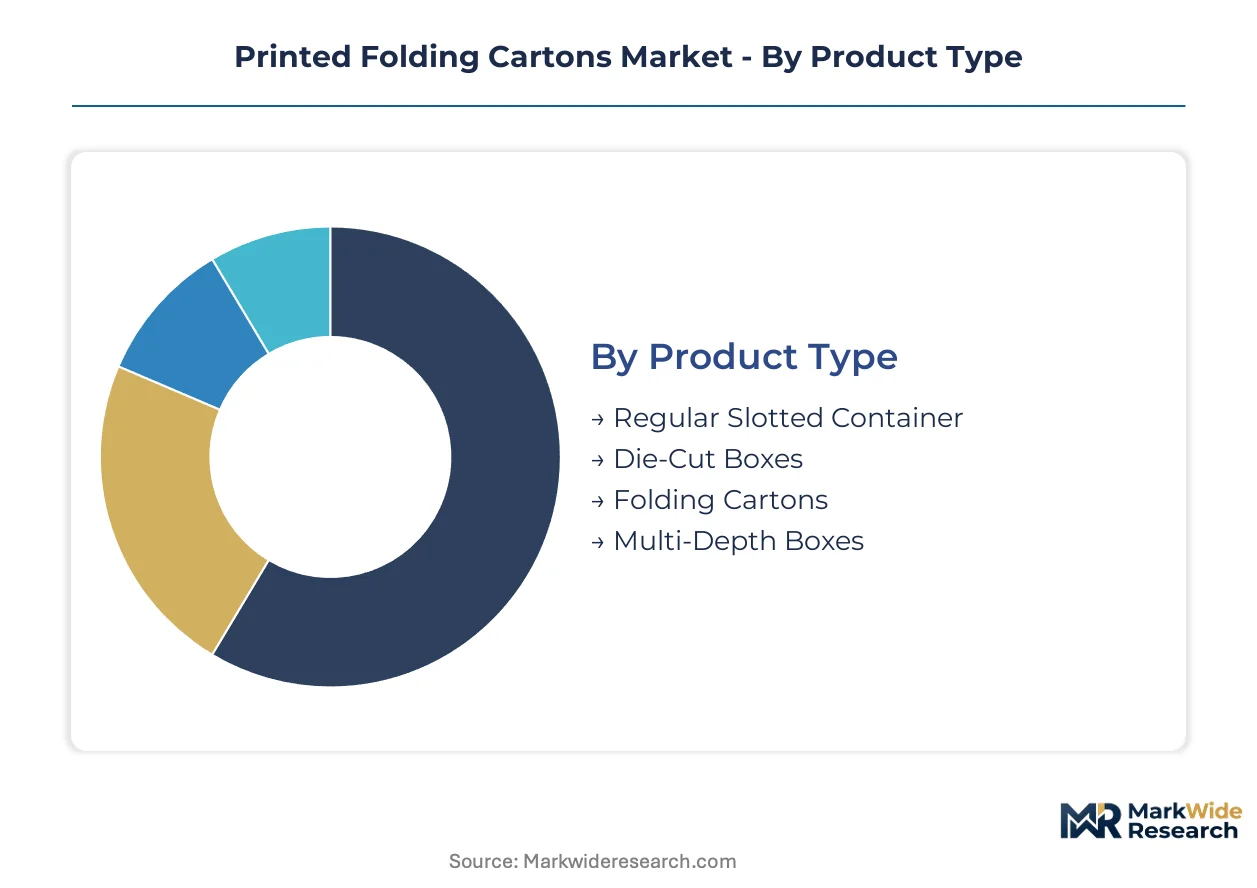
Segmentation in printed folding cartons reveals how substrate choices, conversion formats, and print technologies partition margin pools across radically different order economics. Brand owners select segments based on shelf visibility requirements, regulatory serialization needs, and run-length thresholds that determine per-unit cost structures.
Product Type:
Use-case spectrum spans commodity shipping protection through premium retail presentation, with die-cutting complexity and graphic real estate determining value capture.
- Folding Cartons:Paperboard structures between 200-400 gsm with creased fold lines enabling flat shipment and retail assembly. Pharmaceutical serialization mandates in Germany and Switzerland concentrate demand for cartons with integrated tamper-evident closures and variable-data print zones.
- Die-Cut Boxes:Custom-engineered paperboard containers with irregular perimeters and window apertures for product visibility. Premium chocolate brands in Belgium and the Netherlands specify these for gift-box applications where structural differentiation commands shelf price premiums.
- Regular Slotted Container:Standardized corrugated formats optimized for palletization and warehouse automation.
- Multi-Depth Boxes:Adjustable-height corrugated designs reducing void fill requirements for e-commerce fulfillment.
Established volume favors Regular Slotted Container; emerging adoption favors Folding Cartons.
Material:
Cost tier stratification separates virgin fiber grades with predictable printability from recycled-content alternatives where contamination control adds processing overhead.
- Paperboard:Bleached or unbleached virgin pulp sheets providing uniform surface for high-fidelity lithographic and gravure reproduction. North American beverage brands specify solid bleached sulfate for refrigerated juice applications requiring moisture resistance without plastic lamination.
- Recycled Paper:Post-consumer fiber streams mechanically pulped and de-inked for lower-specification applications. Quality inconsistency in mixed-paper collection systems elevates rejection rates at cartonboard mills, compressing margin pools for converters dependent on these feedstocks.
- Corrugated Fiberboard:Fluted medium sandwiched between linerboards for structural cushioning in distribution.
- Coated Paper:Clay or polymer surface treatments enhancing gloss and ink holdout for photographic reproduction.
Paperboard dominates current procurement volumes; Recycled Paper faces steepest expansion trajectory as EU circularity mandates tighten.
End User:
Customer type segmentation maps divergent regulatory exposure, with pharmaceutical and food applications subject to serialization and safety mandates that cosmetic and electronics packaging largely escape.
- Pharmaceuticals:Cartons engineered for child-resistant compliance, anti-counterfeiting features, and integration with track-and-trace infrastructure. FDA DSCSA enforcement and EU FMD deadlines are expanding demand for variable-data printing and tamper-evident constructions across North American and Western European supply chains.
- Food & Beverage:Barrier-coated paperboard containers protecting oxygen- and moisture-sensitive contents. Dairy and ready-meal brands in Germany, France, and Italy are converting from rigid plastics to fiber-based formats ahead of EU Packaging and Packaging Waste Regulation enforcement.
- Cosmetics:High-graphic cartons supporting brand storytelling and premium positioning.
- Consumer Electronics:Protective packaging with anti-static and shock-absorbing specifications.
Food & Beverage anchors installed capacity; Pharmaceuticals commands fastest value-per-unit expansion.
Printing Technology:
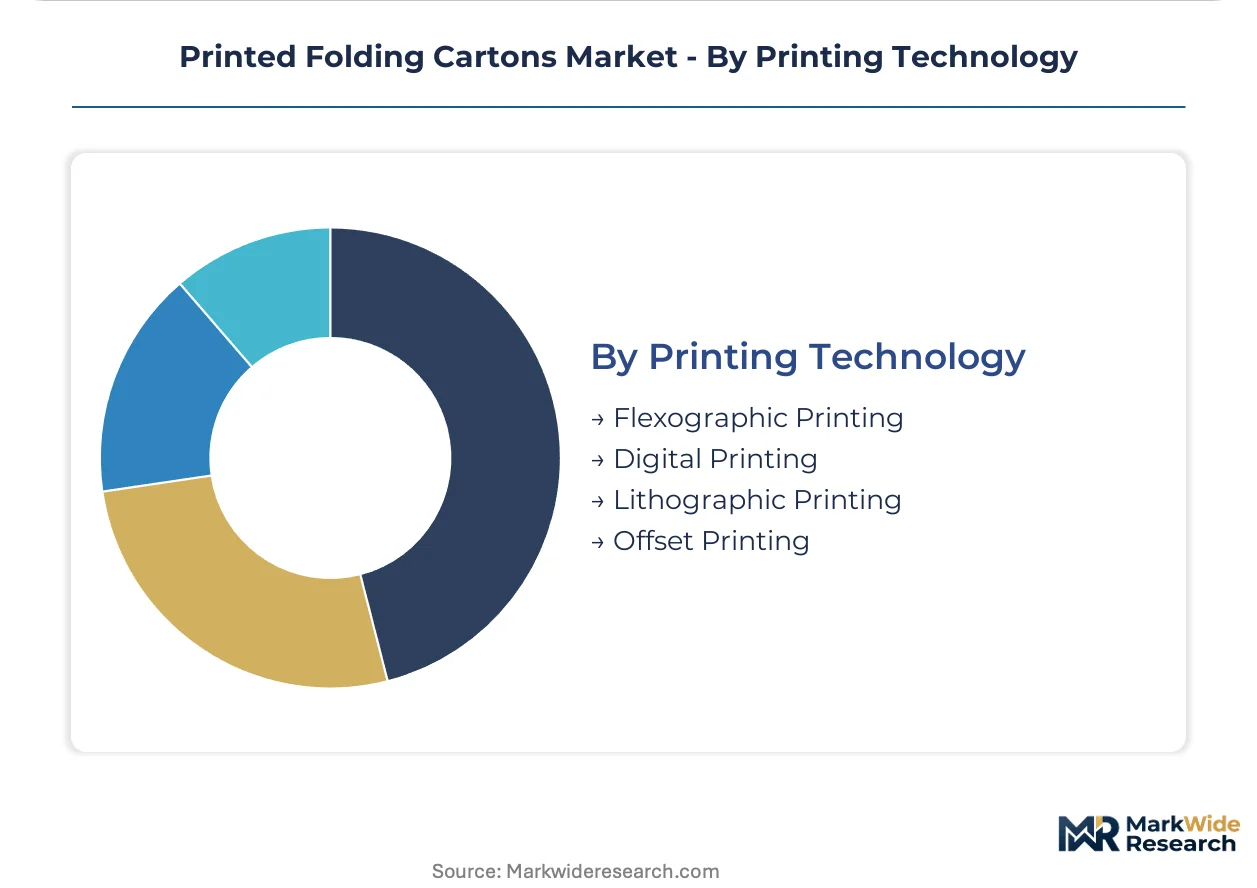
Volume-to-maturity distribution shows offset and flexographic platforms saturating long-run food and beverage applications while digital systems capture pharmaceutical lot-size fragmentation.
- Digital Printing:Inkjet or electrophotographic imaging eliminating plate costs and enabling lot-size-one economics. Pharmaceutical contract manufacturers in Switzerland and Germany deploy single-pass inkjet with inline finishing for serialized runs below ten thousand units, digitizing regional language versioning that previously required dedicated offset campaigns.
- Flexographic Printing:Rotary relief plates with anilox ink metering for high-speed, consistent brand reproduction. Beverage and snack applications across Brazil and India rely on flexographic volume tiers where brand consistency at scale outweighs unit-level customization value.
- Lithographic Printing:Planographic offset imaging delivering photographic quality on coated paperboard.
- Offset Printing:Conventional blanket-transfer lithography dominant in legacy folding carton infrastructure.
Flexographic Printing retains highest throughput volumes; Digital Printing gains share fastest as pharmaceutical lot sizes contract.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and dairy processors concentrate carton procurement in Germany, the United States, India, Brazil, and Switzerland. Each market exhibits distinct regulatory pacing and substrate preferences that shape converter investment cycles.
Germany
Ready-meal brands and dairy cooperatives drive fiber-based substitution away from rigid plastics. The EU Packaging and Packaging Waste Regulation enforces mandatory recyclability targets with 2025 compliance deadlines. The Rhine-Main cluster around Frankfurt hosts serialization-capable converters supplying pharmaceutical exporters.
United States
Over-the-counter pharmaceutical brands and refrigerated beverage processors anchor demand for child-resistant and moisture-resistant formats. FDA DSCSA enforcement expands track-and-trace carton requirements through 2024-2025. The Wisconsin-Illinois paperboard corridor supplies virgin fiber grades to Midwestern converters.
India
Contract development and manufacturing organizations serving regulated export markets require multi-language labeling and anti-counterfeiting features. CDSCO alignment with EU FMD standards pressures domestic carton suppliers to upgrade variable-data infrastructure. The Mumbai-Pune pharmaceutical belt imports specialized folding carton capacity for high-compliance shipments.
Brazil
Snack food processors and pharmaceutical distributors balance cost pressure with emerging traceability mandates. ANVISA's upcoming prescription medicine tracking requirements will force domestic suppliers to retrofit printing lines or cede share to imported cartons. The São Paulo industrial corridor concentrates flexographic volume for beverage and confectionery applications.
Switzerland
Specialty pharmaceutical packaging and premium chocolate gift formats command per-unit value premiums. Swissmedic serialization requirements intersect with EU FMD equivalence agreements. The Basel-Zurich corridor hosts single-pass inkjet installations serving lot sizes below ten thousand units.
Printed Folding Cartons Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Integrated paperboard producers with captive fiber supply anchor the premium pharmaceutical and food-grade segments. Independent converters without mill ownership concentrate in shorter-run, version-heavy applications. Strategic moves center on barrier coating R&D partnerships and serialization infrastructure acquisitions.
Among North American integrated producers, WestRock Company and International Paper Company exemplify scale-driven fiber supply positions. European specialists including DS Smith Plc and Mondi plc occupy closed-loop recycling and barrier technology vectors. Huhtamaki represents the coating-specialist archetype focused on shelf-life extension applications.
| Leading Market Players |
|---|
| International Paper Company |
| Huhtamaki |
| WestRock Company |
| DS Smith Plc |
| Mondi plc |
| Graphic Packaging International |
| Mayr-Melnhof Karton AG |
| Stora Enso Oyj |
| Smurfit Kappa Group Plc |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor links Nordic pulp mills to German pharmaceutical converters, and its container rate volatility amplifies cost-plus contract renegotiations while squeezing margin pools for mid-tier carton suppliers without captive fiber supply.
Pricing Analysis
Cost-plus contracts indexed to NBSK pulp futures dominate long-term offtake agreements between North American integrated producers and beverage brand procurement teams. Three-tier pricing structure across premium pharmaceutical serialization grades, standard food-grade barrier coatings, and economy recycled-content tiers separates margin capture by certification level and volume scale. Cost compression in economy recycled grades is intensifying because contamination-driven yield losses at cartonboard mills force converters to absorb fiber quality discounts. Generic pharmaceutical distributors exhibit highest price sensitivity; Swiss specialty pharma contract manufacturers show lowest sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Contract manufacturing concentration among Swiss and German pharmaceutical packaging specialists anchors high-compliance folding carton capacity for European export markets. Virgin pulp supply concentrates in Sweden, Finland, and Canada; recycled fiber processing clusters in Germany, France, and Italy. Raw material dependencies rest on softwood kraft pulp, aqueous barrier polymers, and cobalt-based drying agents for offset inks. Single-source vulnerability runs through Nordic pulp mill consolidation, where capacity rationalization limits spot market availability during demand surges. Distribution runs through converter-direct relationships with multinational FMCG procurement hubs and pharmaceutical CDMO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The printed folding cartons market functions as a regulatory-moat business where FDA DSCSA and EU FMD serialization mandates erect switching costs that protect incumbent positions.
For Market Incumbents: Build certification-entrenchment moats by acquiring serialization-capable converters in the Mumbai-Pune pharmaceutical belt before CDSCO alignment deadlines force capacity shortages. Consolidate barrier-coating R&D partnerships with dairy processors in Germany and France to preempt EU Packaging and Packaging Waste Regulation substitution demand. Threat: Stand-up pouch substitution in single-serve confectionery erodes volume tiers. Lever: Backward integration into aqueous coating chemistry. For New Entrants and Emerging Players: Brazilian pharmaceutical traceability underpenetration offers white-space entry before ANVISA enforcement mandates retrofit domestic capacity. Target Indian CDMO export packaging requiring multi-language variable-data capabilities as the most penetrable segment. Go-to-market angle: Partner with European serialization-technology licensors to shortcut infrastructure buildout. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital-hybrid press operators with pharmaceutical serialization workflows over legacy offset-dependent volume players. Long-term viability hinges on regulatory entrenchment durability across FDA and EU enforcement waves. Acquisition archetype: Swiss or German converters with single-pass inkjet installations and closed-loop pharmaceutical customer relationships. Signal to watch: ANVISA traceability rule finalization triggering Brazilian import dependency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Partnership | Huhtamaki's shelf-life extension chemistry enables dairy brands to meet EU circularity mandates ahead of enforcement. |
| Serialization Infrastructure Acquisition | Converters buying variable-data press capacity capture pharmaceutical lot-size fragmentation in Switzerland and Germany. |
| Recycled Fiber Quality Investment | DS Smith's closed-loop de-inking systems reduce contamination rejection rates at European cartonboard mills. |
| Digital Hybrid Press Deployment | Single-pass inkjet with inline finishing digitizes economics for regional language versioning below ten thousand units. |
| Geographic Expansion to Indian CDMO Belt | Mumbai-Pune pharmaceutical exporters require anti-counterfeiting cartons with EU FMD-equivalent compliance. |
Research Methodology
A standing panel of folding carton plant managers, pharmaceutical packaging procurement leads, dairy brand supply chain directors, and barrier-coating R&D chemists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA DSCSA guidance documents, EU FMD implementation reports, trade data from the American Forest and Paper Association, and SEC filings of integrated paperboard producers. Bottom-up capacity modeling at individual converter facilities triangulated against top-down demand aggregation by end-use segment and print technology.
Scenario-bracketing framed sensitivity analysis across regulatory enforcement pace, pulp price volatility bands, and digital press adoption curves. Segmentation dimensions modeled included substrate material tier, end-use regulatory exposure, printing technology platform, and geographic production cluster. CAGRs were derived from production volume reconciliations against brand-owner procurement survey data. Industry-specific forecast inputs encompassed pharmaceutical serialization mandate deadlines and EU Packaging and Packaging Waste Regulation recyclability target trajectories.
Practitioners should monitor ANVISA traceability rule finalization, Nordic pulp mill capacity announcements, and digital press installation rates at Swiss pharmaceutical converters for early signals of forecast revision. Assumptions underlying projections reflect current regulatory enforcement schedules and fiber supply continuity. Quarterly review of pharmaceutical lot-size trends, recycled fiber contamination indices, and barrier-coating substitution rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
GCC Folding Carton Market
Cartons
Carton Liners Market
Cartons
Microwaveable Carton Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Europe Corrugated Box Market
Cartons
Luxury Folding Carton Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Brick Liquid Carton Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Carton Form Fill Seal Machine Market
Cartons
Carton Sealer Machine Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Global Hand Carton Sealers Market
Cartons
Mailers Market
Cartons
Japan Corrugated Boxes Market
Cartons
North America Corrugated and Folding Carton Packaging Market