
 Polymer Vials Market | 2026-2036
Polymer Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Vials Market Analytics
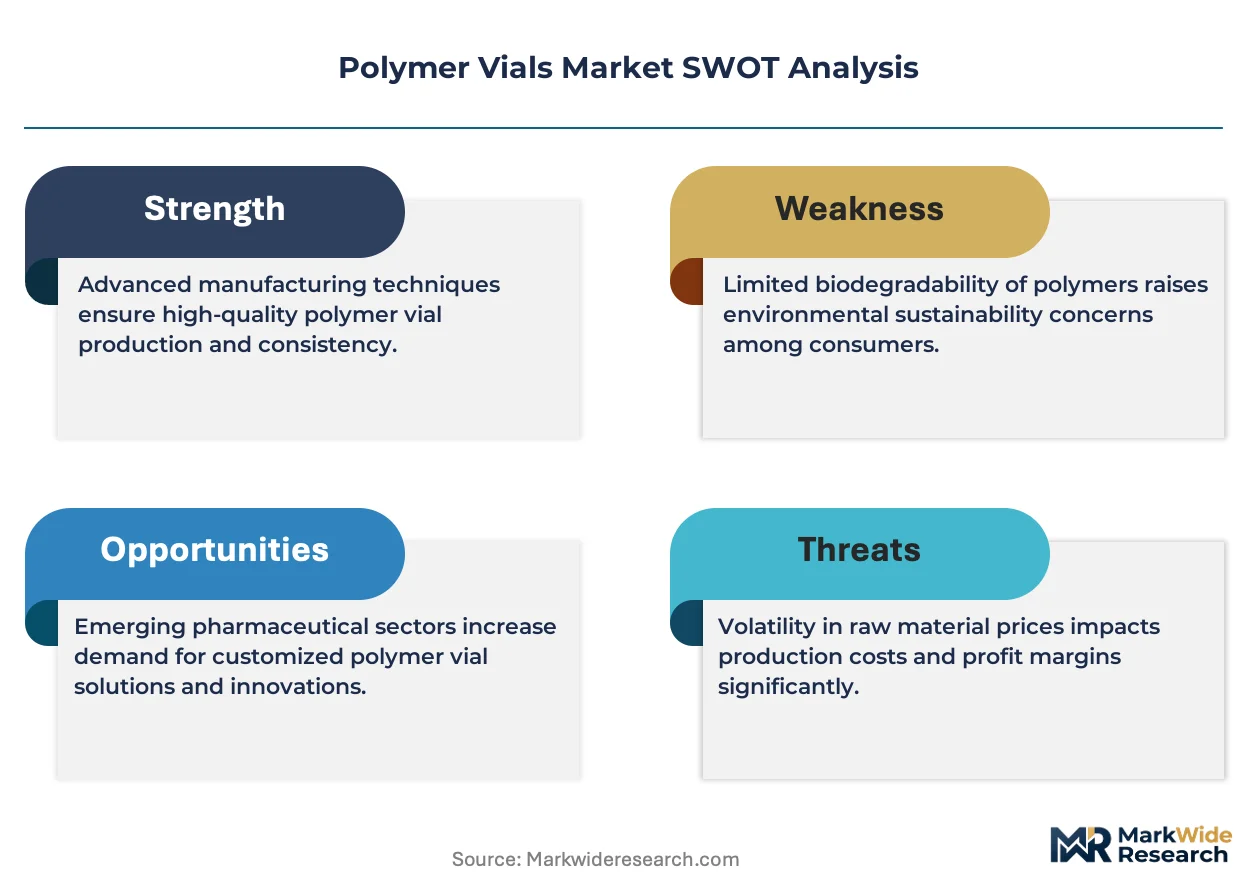
ISO 15378 certification for primary packaging materials is unwinding the competitive landscape, forcing smaller molders to upgrade quality management systems or exit pharmaceutical supply chains. Gerresheimer AG leverages its blow-fill-seal integration to control unit-dose polymer vial production from resin to finished sterile product. SCHOTT Pharma anchors European supply through its cyclic olefin polymer expertise, while West Pharmaceutical Services differentiates via its NovaGuard needle-free access platform paired with polymer containment. Stevanato Group competes through high-speed visual inspection systems that reduce particle rejection rates in COP vial lines.
Polymer vials are injection- or blow-molded primary containers fabricated from cyclic olefin polymers, polypropylene, or polyethylene, designed to store injectable drugs, vaccines, and biologics with moisture and oxygen barrier properties typically measured in water vapor transmission rates below 0.5 g/m²/day. Their industrial purpose centers on eliminating glass breakage risk in cold-chain distribution and enabling lightweight, design-flexible alternatives to borosilicate containers. Single-use polymer vials dominate volume in vaccine prefillable applications where contamination control overrides reuse economics, while multi-use configurations retain niche positions in compounding pharmacy workflows. Cyclic olefin polymer formulations command premium positioning due to their glass-like clarity and low extractable profiles, whereas polypropylene segments compete on cost in generic injectable markets where regulatory pathways permit broader material acceptance.
The US FDA enforces container closure integrity testing under USP <1207> for all polymer primary packaging, while the EMA's MDR and REACH frameworks govern extractables documentation and material biocompatibility across European submissions. ISO 10993 series standards for biological evaluation of medical devices further constrain material selection, creating compliance moats that favor established molders with dedicated regulatory affairs functions. Stakeholders must monitor evolving pharmacopeial chapters on plastic packaging systems as USP and EP alignment efforts accelerate, since divergent testing protocols could fragment qualification investments across Atlantic supply chains.
Market Dynamics
Biopharmaceutical contract manufacturing organizations are consolidating procurement around polymer vial suppliers capable of integrated blow-fill-seal sterile production, compressing qualification timelines and reshaping supplier tier structures.
Growth Catalysts
- Monoclonal antibody cold-chain expansion:Biologics storage requirements favor polymer vials for breakage resistance during ultra-low temperature distribution.
- ISO 15378 certification mandates:Pharmaceutical quality management standards for primary packaging materials are elevating compliant molders above commodity competitors.
- Cyclic olefin polymer clarity advantages:COP formulations deliver glass-like transparency with lower extractable profiles, accelerating adoption in high-value injectable segments.
Market Restraints
- Specialized resin supply concentration:Cyclic olefin polymer feedstock production clusters in limited chemical manufacturing regions, exposing molders to input volatility.
- USP <1207> container closure integrity testing costs:FDA-mandated validation protocols impose capital burdens on smaller packaging suppliers seeking market entry.
- Glass vial substitution persistence:Borosilicate containers retain cost advantages in generic injectable markets with less stringent barrier requirements.
Strategic Opportunities
- Prefillable vaccine unit-dose formats:Single-use polymer vials align with contamination control priorities in pandemic preparedness stockpiling programs.
- REACH extractables documentation alignment:EMA harmonization efforts create pathway for standardized European qualification investments.
- Needle-free access platform integration:Combination product configurations pairing polymer containment with administration devices open premium positioning.
Industry Challenges
- ISO 10993 biological evaluation expertise scarcity:Medical device biocompatibility testing capabilities concentrate among established regulatory affairs functions, constraining new entrant scaling.
- High-speed visual inspection system capex requirements:Particle rejection rate reduction demands specialized automated quality infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Vials Market |
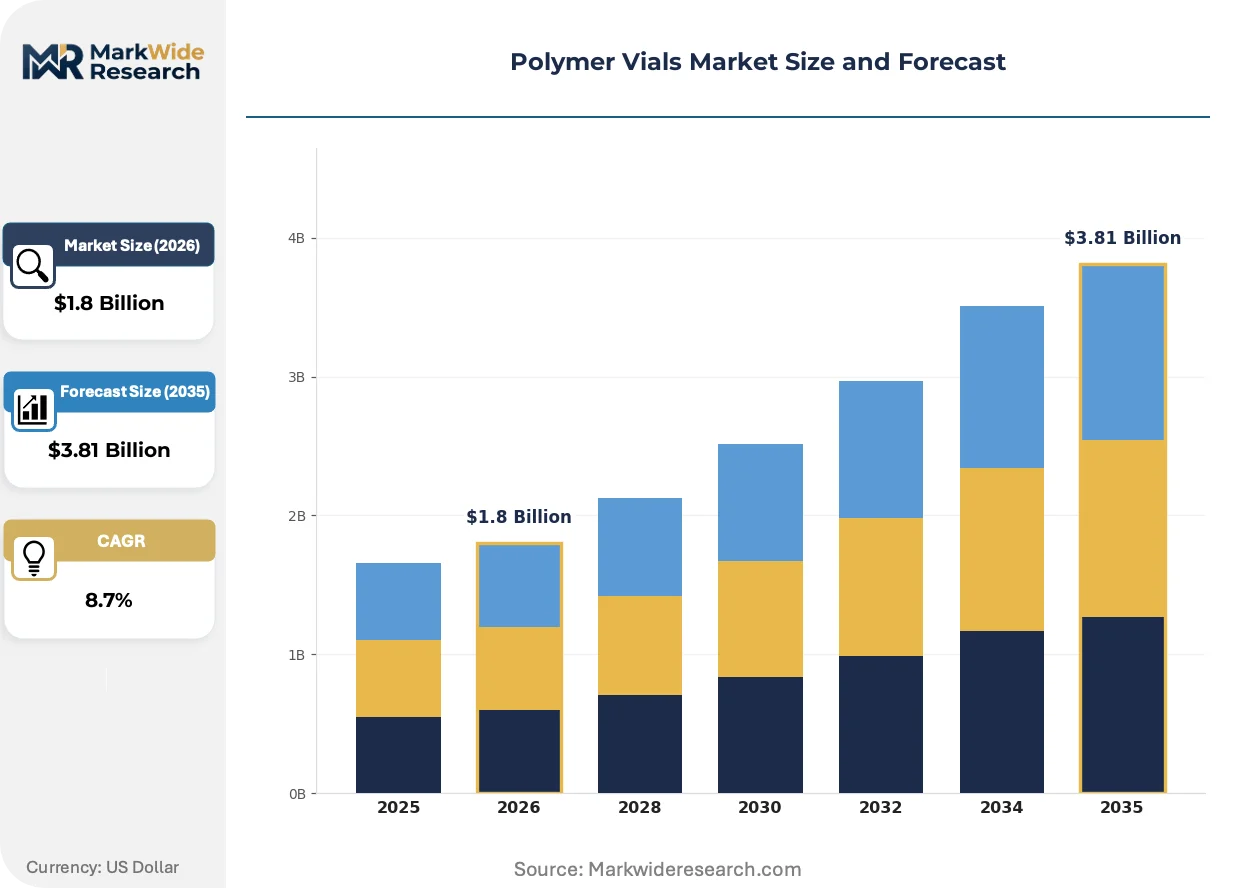
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use, Multi-use, Sterile, Non-sterile Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Pharmaceuticals, Biotechnology, Research Labs, Hospitals Capacity: 1ml, 5ml, 10ml, 20ml |
| Companies Covered | Gerresheimer AG, SCHOTT Pharma, Stevanato Group, West Pharmaceutical Services, Corning Incorporated, Bormioli Pharma, Nipro Corporation, Amcor Plc, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Vials Market Evolving Landscape
Material science advances and regulatory harmonization efforts are compressing development cycles for next-generation polymer containment, while procurement centralization among contract manufacturers reconfigures supplier relationships.
Blow-fill-seal integration is supplanting discrete molding and aseptic filling operations in unit-dose polymer vial production. Biopharmaceutical contract manufacturers are adopting this continuous processing approach to eliminate intermediate handling contamination risks. The technology is supplanting traditional batch-oriented supply chains with closed-system sterile production from resin to finished vial.
EMA's MDR and REACH frameworks are tightening extractables documentation requirements for plastic primary packaging submissions. Manufacturers must now generate comprehensive chemical characterization data across accelerated aging protocols. European biologics developers are responding by pre-qualifying COP and polypropylene grades with established toxicological profiles.
Centralized procurement through large contract manufacturing organizations is consolidating polymer vial supplier relationships around full-service molders with integrated regulatory support. Multi-year supply agreements with dedicated capacity allocation are displacing spot purchasing in high-volume monoclonal antibody programs. This concentration is most visible in Germany's specialized production clusters anchored by Gerresheimer and SCHOTT Pharma operations.
Polymer Vials Market Segmentation
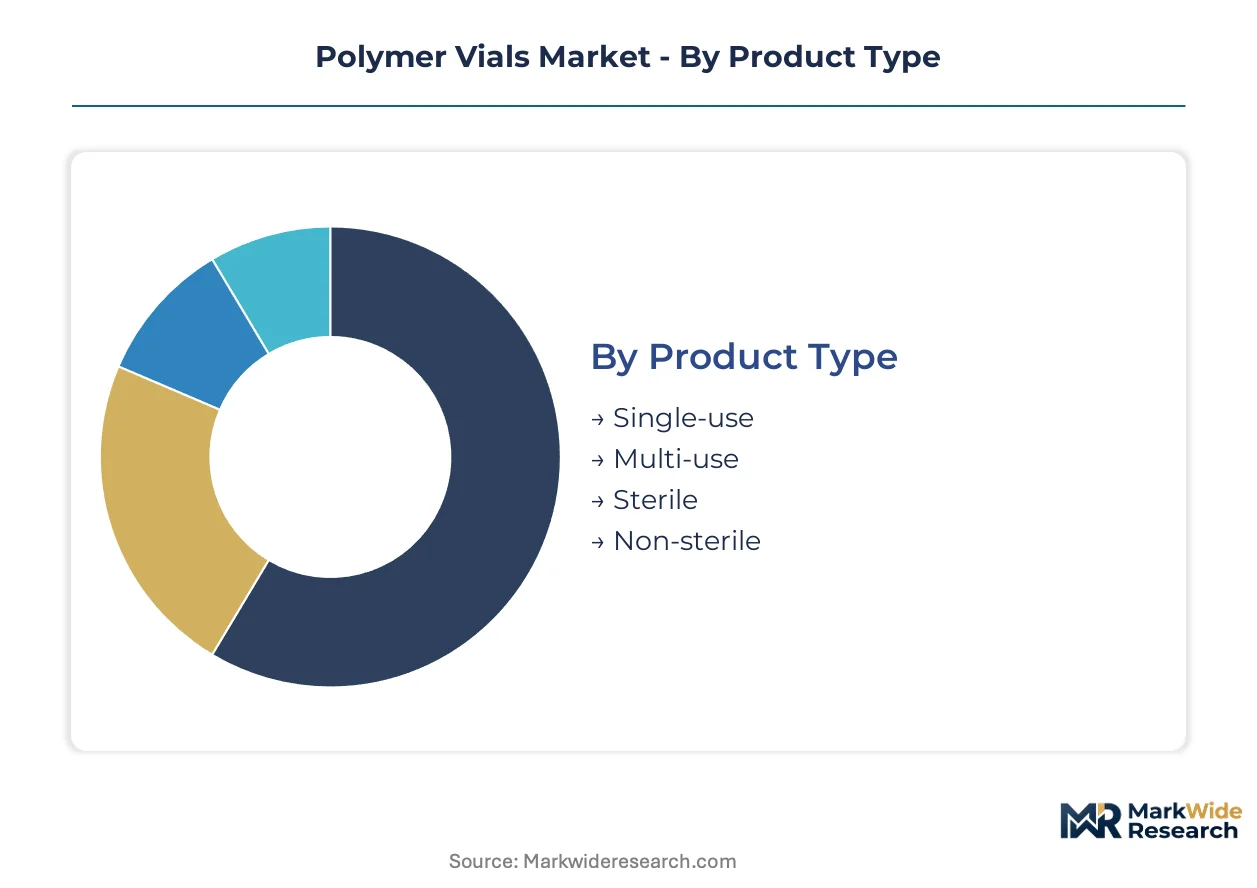
Polymer vial segmentation reveals divergent qualification pathways across pharmaceutical supply chains. Material selection and sterility status determine regulatory burden, while capacity configurations align with specific biologic dosing protocols.
Product Type:
Domestic procurement dominates multi-use configurations for compounding pharmacy workflows, whereas export-led demand concentrates in single-use formats serving contract manufacturing organizations across North American and European biologics networks.
- Single-use:Designed for one-time administration with sealed barrier systems eliminating cross-contamination risk. Demand concentrates in German and Swiss parenteral manufacturing clusters where FDA and EMA dual-qualification requirements favor pre-validated disposable formats. Pandemic preparedness stockpiling accelerates procurement timelines for unit-dose vaccine applications.
- Multi-use:Reusable configurations with resealable closure systems for compounding and repackaging operations. Procurement clusters in US hospital pharmacy networks and European central fill facilities where cost-per-dose economics override sterility assurance premiums. Regulatory documentation burdens limit adoption in commercial biologics distribution.
- Sterile:Terminal sterilization or aseptic processing yields SAL 10⁻⁶ assurance per ISO 11137 standards. Blow-fill-seal integration at Gerresheimer and SCHOTT Pharma facilities supplies pre-sterilized vials direct to fill-finish operations.
- Non-sterile:Bulk packaging for downstream sterilization by pharmaceutical manufacturers or third-party providers. Cost positioning serves generic injectable producers with captive sterilization capacity.
Single-use commands the established base. The steepest expansion runs through sterile configurations.
Material:
Cost tier stratification separates premium cyclic olefin polymer substitutes from commodity polyolefins, with extractable profile documentation requirements widening the gap between qualification-ready and general-purpose grades.
- Polyethylene:Low-density and high-density formulations provide moisture barrier performance with cost positioning below polypropylene. Generic injectable manufacturers in India and Brazil leverage PE vials for stable small-molecule parenterals where oxygen sensitivity remains moderate.
- Polypropylene:Superior chemical resistance and autoclave compatibility support terminal sterilization protocols. Demand concentrates in European vaccine production networks requiring steam sterilization validation per EMA guidelines. PP grades with USP Class VI certification command price premiums over uncertified alternatives.
- Polyvinyl Chloride:Plasticized formulations offer flexibility in blood bag derivatives and diagnostic containment. REACH plasticizer restrictions constrain European adoption, limiting PVC vials to specific regulated medical device applications with established toxicological profiles.
- Polystyrene:Crystal clarity supports visual inspection requirements in diagnostic and research applications. Brittleness limits pharmaceutical adoption to non-shipping laboratory workflows.
Polypropylene anchors the installed base. The steepest expansion trajectory belongs to cyclic olefin polymer substitutes displacing glass in high-value biologics.
End User:
Volume concentration follows biologics pipeline maturation, with biotechnology developers outpacing traditional pharmaceutical procurement in polymer vial specification rates.
- Pharmaceuticals:Large molecule injectables and vaccine portfolios drive specification of COP and PP vials for commercial distribution. FDA container closure guidance compliance timelines compress supplier selection windows.
- Biotechnology:Cell and gene therapy developers require ultra-low temperature stability validation from -80°C to cryogenic storage. Contract manufacturing organization procurement centralization favors integrated blow-fill-seal suppliers with dedicated regulatory affairs support.
- Research Labs:Non-GMP grade polymer vials serve preclinical and analytical applications with reduced documentation burdens. Academic and government research institutions in the US and Germany represent price-sensitive volume.
- Hospitals:Compounding pharmacy and point-of-care preparation workflows utilize multi-use configurations with immediate-turn procurement patterns distinct from commercial manufacturing supply agreements.
Pharmaceuticals command the established base. Biotechnology applications are gaining share fastest.
Capacity:
Volume scale determines automation compatibility, with 10ml formats achieving optimal throughput on high-speed filling lines while smaller capacities require specialized handling equipment.
- 1ml:Pediatric and ophthalmic dosing applications with precision fill requirements. Demand clusters in Japanese and South Korean specialty pharmaceutical manufacturing.
- 5ml:Vaccine unit-dose and diagnostic reagent containment. Pandemic influenza and COVID-19 stockpiling programs standardized 5ml polymer vial specifications across WHO-prequalified supplier networks.
- 10ml:Dominant format for monoclonal antibody and peptide injectables with fill volumes of 2-8ml. High-speed visual inspection system compatibility drives standardization across contract manufacturing organization platforms.
- 20ml:Lyophilization and bulk API storage applications requiring headspace for freeze-dried cake formation. Limited volume growth constrained by shift toward ready-to-use presentations.
10ml commands the established base. The steepest expansion runs through 5ml vaccine unit-dose formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA container closure guidance revisions and EMA MDR harmonization efforts are compressing qualification timelines across major pharmaceutical manufacturing regions. National regulators are accelerating sterile packaging validation protocols to align with biologics cold-chain expansion requirements.
United States
Monoclonal antibody pipeline maturation drives polymer vial procurement through contract manufacturing organizations concentrated in Greater Boston and the Research Triangle. FDA enforcement of USP 1207 container closure integrity testing elevates compliant suppliers above commodity competitors. New Jersey and Pennsylvania host specialized blow-fill-seal production clusters serving pandemic preparedness stockpiling programs.
Germany
EMA REACH extractables documentation requirements tighten material qualification for cyclic olefin polymer formulations in high-value injectables. Gerresheimer and SCHOTT Pharma anchor specialized production clusters in Bavaria and North Rhine-Westphalia. The country's national pharmaceutical regulator maintains accelerated pathways for ISO 15378-certified primary packaging materials.
Switzerland
Swissmedic oversight of combination products drives demand for needle-free access platform integration with polymer containment systems. Basel and Zürich biologics manufacturing networks specify COP vials for ultra-low temperature stability validation. The cantonal concentration of contract manufacturing organizations centralizes procurement around full-service molders with dedicated regulatory affairs functions.
India
CDSCO alignment with ICH Q3D guidelines on elemental impurities accelerates domestic polymer vial qualification for export-oriented generic injectable producers. Maharashtra and Gujarat host high-volume polypropylene vial manufacturing serving cost-sensitive vaccine markets. The country's national pharmaceutical regulator is harmonizing plastic packaging standards with USP and EP protocols to streamline international submissions.
Japan
PMDA emphasis on visible particle control in biologics packaging drives adoption of high-speed visual inspection systems in COP vial lines. Kanto and Kansai pharmaceutical manufacturing corridors specify glass-like clarity materials for ophthalmic and pediatric dosing applications. METI industrial policy supports domestic molding capacity expansion to reduce import dependency for primary packaging materials.
Polymer Vials Market Competitive Landscape
Player mix skews toward integrated pharmaceutical packaging specialists with captive blow-fill-seal sterile production capabilities. Tier structure separates ISO 15378-certified molders with dedicated regulatory affairs functions from commodity polyolefin converters serving generic markets. Strategic archetypes include full-service containment providers, cyclic olefin polymer specialists, and high-volume contract manufacturing suppliers. Dominant competitive moves center on multi-year supply agreements with dedicated capacity allocation and backward integration into specialized resin procurement.
Among Germany-based fabricators, Gerresheimer AG and SCHOTT Pharma occupy positions within the premium-tier integrated supplier archetype, exemplifying the concentration of blow-fill-seal expertise in specialized European production clusters. West Pharmaceutical Services represents the combination product configuration specialist tier, anchoring needle-free access platform development paired with polymer containment systems.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT Pharma |
| Stevanato Group |
| West Pharmaceutical Services |
| Corning Incorporated |
| Bormioli Pharma |
| Nipro Corporation |
| Amcor Plc |
| Berry Global |
| Others |
Value Network & Pricing Analysis
ISO 15378 certification gates simultaneously constrain supply qualification and enable price stratification, bifurcating the market between certified molders commanding premium positioning and uncertified converters competing on spot pricing in generic injectable segments.
Pricing Analysis
Certification level creates the primary spread between ISO 15378-validated suppliers and commodity molders. Pricing stratifies across premium COP formulations, standard polypropylene grades, and economy polyethylene alternatives. Cost compression in generic injectable tiers intensifies as Indian and Brazilian manufacturers expand polypropylene capacity. Contract manufacturing organizations exhibit lowest price sensitivity, while research labs and compounding pharmacies drive spot-market volatility.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes elevate inbound logistics costs for cyclic olefin polymer resin shipments. Production clusters in Germany, Switzerland, and the United States draw from Japanese and South Korean specialty chemical feedstock sources. Single-source vulnerability concentrates in cyclic olefin polymer monomer supply. Distribution runs through direct long-term supply agreements with integrated blow-fill-seal manufacturers rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologics pipeline maturation signals cyclical recovery as monoclonal antibody cold-chain expansion rebuilds demand momentum after pandemic stockpiling normalization.
For Market Incumbents: Shield market position through captive blow-fill-seal capacity expansion in Bavaria and North Rhine-Westphalia production clusters. Deepen backward integration into cyclic olefin polymer resin procurement to offset feedstock volatility. ISO 10993 biological evaluation expertise scarcity threatens margin compression if regulatory documentation demands accelerate. For New Entrants and Emerging Players: Differentiate on REACH-aligned extractables documentation for European biotechnology developers seeking pre-qualified COP alternatives. Target multi-use configurations in US hospital pharmacy networks where sterility assurance premiums remain negotiable. Pursue needle-free access platform integration as combination product qualification pathways open premium positioning. For Investors and Strategic Acquirers: FDA container closure guidance revisions reshape the acquisition landscape toward ISO 15378-certified molders with dedicated regulatory affairs functions. Five-to-ten year viability hinges on biologics cold-chain infrastructure buildout rates. Monitor EMA MDR harmonization progress as inflection indicator for European qualification investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Blow-Fill-Seal Integration | Gerresheimer and SCHOTT Pharma control sterile production from resin to finished vial, eliminating contamination risks. |
| ISO 15378 Certification Investment | Quality management system upgrades separate compliant molders from commodity competitors facing supply chain exclusion. |
| Cyclic Olefin Polymer Backward Integration | Captive resin procurement insulates margins against Japanese and South Korean feedstock price volatility. |
| Needle-Free Access Platform Development | West Pharmaceutical Services pairs polymer containment with administration devices for combination product positioning. |
| High-Speed Visual Inspection Deployment | Stevanato Group reduces particle rejection rates through automated quality infrastructure in COP vial lines. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with regulatory affairs directors, pharmaceutical packaging procurement managers, blow-fill-seal operations heads, and biologics supply chain planners; and secondary validation through FDA container closure guidance documents, EMA MDR submission databases, ISO 15378 certification registries, and USP pharmacopeial chapter revisions. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Across the projection horizon, the analytical framework segmented by material grade, sterility status, end-use application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating monoclonal antibody pipeline data and vaccine prefillable format adoption curves. Cyclic olefin polymer substitution rates and blow-fill-seal penetration served as primary industry-specific inputs.
Material uncertainties — regulatory harmonization delays, resin supply disruptions, and biologics cold-chain infrastructure buildout pace — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ISO 15378 certification timelines and EMA REACH extractables documentation alignment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market