
 Pharmaceutical Contract Packaging Market | 2026-2036
Pharmaceutical Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Contract Packaging Market Intelligence
Biodegradable polymers and fiber-based alternatives to conventional plastics is rebalancing unit economics for sustainable blister and sachet formats. PCI Pharma Services leverages integrated serialization infrastructure across North American and European sites. Gerresheimer AG anchors glass primary packaging demand through specialized vial and ampoule manufacturing for injectable applications. West Pharmaceutical Services, Inc. differentiates via elastomeric closure technology leadership in containment systems for biologics.
Pharmaceutical contract packaging encompasses outsourced primary, secondary, and tertiary packaging operations performed under GMP conditions, including serialization, labeling, and aggregation for regulated drug products; specifications typically require ISO 15378 certification for primary contact materials and adherence to USP <661> container closure system standards. Blister packs dominate oral solid dosage applications due to patient compliance features and moisture-barrier properties, while vials and ampoules command premium positioning in the injectable segment driven by biologics growth. Serialization services represent the fastest-expanding service category as regulatory deadlines for unit-level traceability compress implementation timelines across multiple jurisdictions.
FDA DSCSA requirements and EU Falsified Medicines Directive enforcement shape packaging provider qualification criteria, with EMA and national competent authorities conducting GMP inspections that determine market access eligibility. The EU AI Act introduces emerging compliance dimensions for automated inspection systems deployed in packaging lines. Stakeholders must evaluate provider investments in cold-chain infrastructure and digital thread capabilities as qualification thresholds tighten for complex biologic and cell therapy packaging requirements.
Market Dynamics
Serialization mandates across FDA DSCSA and EU FMD are compressing qualification timelines for contract packaging partnerships, forcing biologics manufacturers to consolidate vendor relationships around providers with pre-validated digital infrastructure and cold-chain capabilities.
Growth Catalysts
- EU MDR track-and-trace enforcement:Medical device and pharmaceutical convergence under EMA inspection protocols is expanding packaging service scopes to include combined drug-device combination product serialization.
- Biodegradable polymer adoption:Fiber-based blister alternatives are capturing oral solid dosage formats as European sustainability directives tighten plastic packaging restrictions.
- German CDMO cluster density:Concentrated packaging coordination hubs around Frankfurt and Munich are reducing logistics friction for European pharmaceutical distribution networks.
Market Restraints
- Aluminum foil supply volatility:Cold-form blister substrate costs fluctuate with energy-intensive smelting operations concentrated in specific production geographies.
- EMA GMP inspection backlog:Extended qualification timelines for new packaging line approvals delay market entry for contract providers expanding capacity.
- Glass vial import dependency:Specialized borosilicate tubing supply for injectable primary packaging concentrates among limited qualified manufacturers.
Strategic Opportunities
- Cell therapy cryogenic packaging:Ultra-low temperature logistics requirements for CAR-T and regenerative medicines create service white space beyond conventional cold-chain capabilities.
- EU AI Act automated inspection:Machine vision deployment in packaging lines qualifies for regulatory sandbox incentives while reducing manual inspection labor.
- Serialization-as-a-service models:Subscription-based compliance infrastructure lowers capital barriers for mid-tier pharmaceutical manufacturers outsourcing track-and-trace operations.
Industry Challenges
- Qualified serialization engineering talent:Scarce expertise in aggregation hierarchy design and EPCIS data exchange implementation constrains provider scaling.
- Legacy MES integration complexity:Brownfield packaging facilities face protracted validation cycles when connecting new serialization equipment to existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Contract Packaging Market |
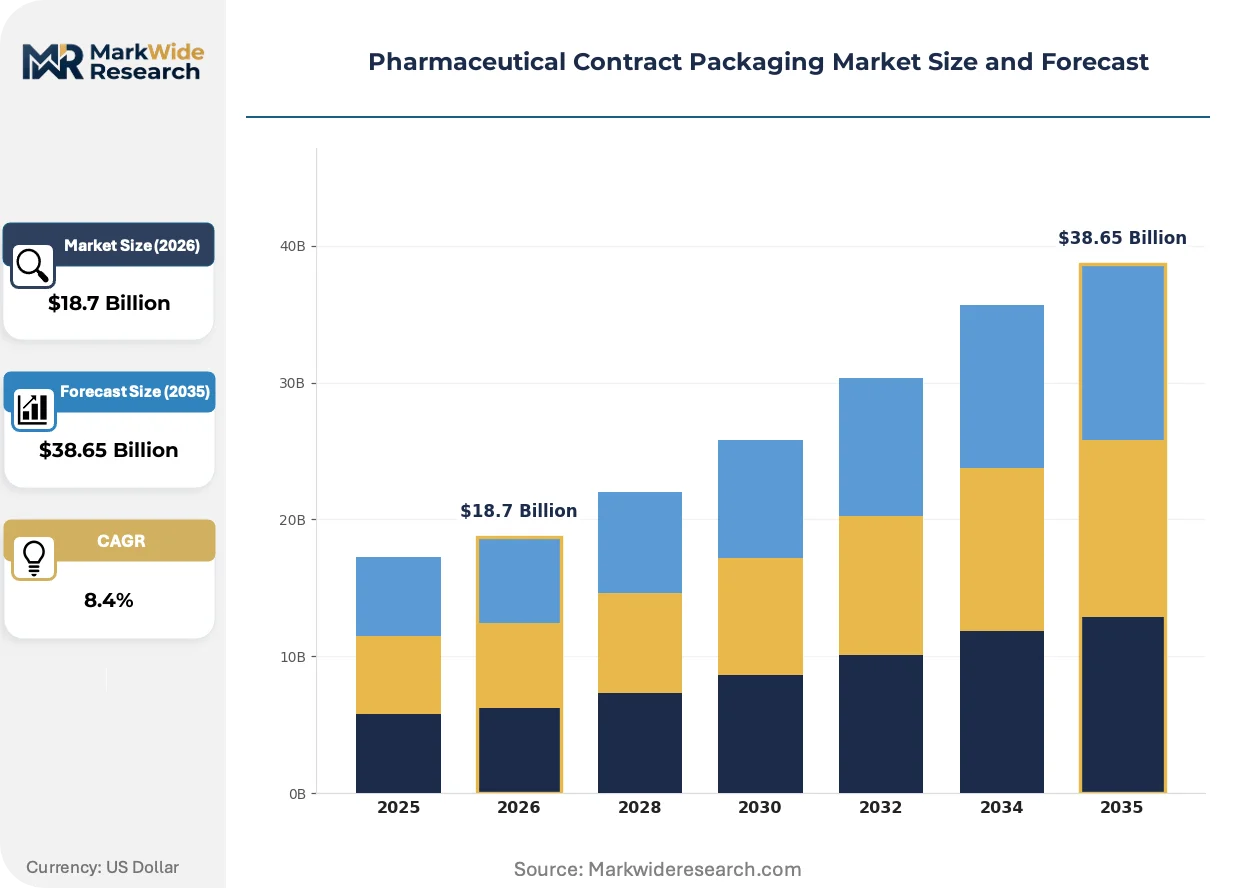
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Blister Packs, Sachets, Vials, Ampoules, Tubes Service Type: Primary Packaging, Secondary Packaging, Serialization, Labeling, Inspection, Repackaging Application: Oral Solid, Injectable, Topical, Inhalation, Ophthalmic, Nasal End User: Pharmaceutical Manufacturers, Biotechnology Firms, Generic Drug Makers, Research Organizations, Nutraceutical Companies |
| Companies Covered | PCI Pharma Services, Schott AG, West Pharmaceutical Services, Inc., Sharp Services LLC, CCL Industries, Nipro Corporation, Gerresheimer AG, Nelipak Healthcare, Catalent Pharma Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Contract Packaging Market Strategic Shifts & Innovations
Digital thread architectures and sustainable material transitions are restructuring how pharmaceutical packaging services are specified, priced, and audited across the value chain.
Blockchain-enabled verification networks are overtaking paper-based chain-of-custody documentation for high-value biologics shipments. Specialty pharmaceutical distributors in North America and Western Europe are piloting distributed ledger protocols for temperature excursion accountability. This shift is compressing dispute resolution timelines and reducing insurance premiums for cold-chain logistics providers.
EU AI Act risk classification frameworks are mandating human oversight protocols for automated visual inspection systems deployed in GMP packaging environments. Machine learning defect detection algorithms now require documented validation sets and algorithmic change control procedures. Injectable biologics manufacturers in Germany and Switzerland are restructuring quality agreements to specify AI system training data provenance.
Direct-to-pharmacy distribution models are fragmenting traditional wholesale channel dominance for specialty medications. Hospital systems and specialty pharmacies in the United States are negotiating direct packaging partnerships that bypass regional distribution centers. This channel compression is visible most acutely in oncology and rare disease therapeutic categories where product handling protocols require customized secondary packaging configurations.
Pharmaceutical Contract Packaging Market Segmentation
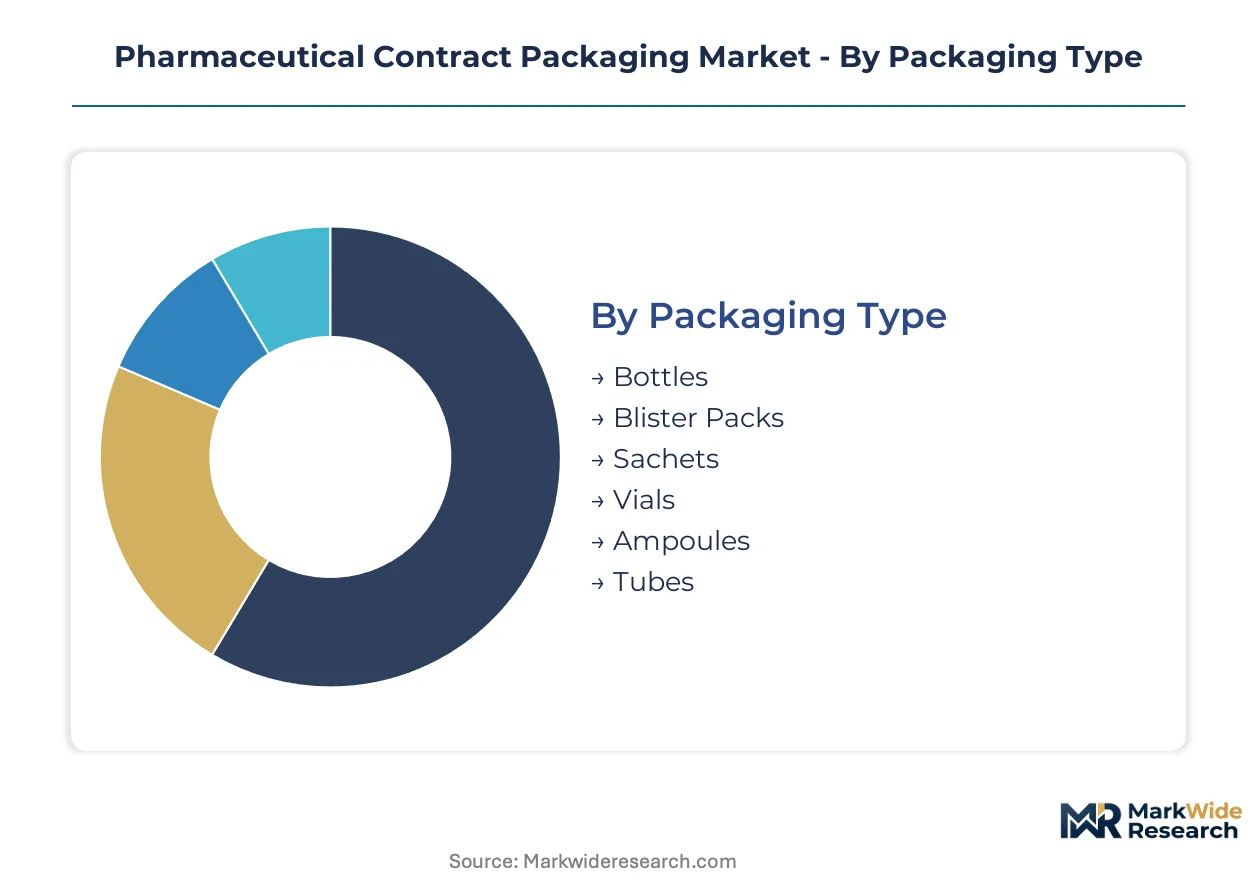
Segmentation in pharmaceutical contract packaging reveals how outsourcing decisions cluster around regulatory complexity, temperature sensitivity, and serialization readiness. Manufacturers select packaging partners based on format-specific GMP capabilities and end-use qualification requirements rather than generic capacity alone.
Packaging Type:
Customization intensity varies sharply across this category, from standardized bottle formats to patient-specific blister configurations requiring tool-less changeover systems.
- Blister Packs:Multi-layer aluminum-PVC-PVDC laminates provide moisture and oxygen barriers for oral solid dosage forms. Demand concentrates in Germany and Switzerland where high-value chronic medications require compliance-enhancing calendarized packaging designs.
- Vials:Borosilicate glass primary containers with elastomeric closures dominate biologics containment. Injectable manufacturers in the United States and Germany source these through qualified tubing suppliers with EMA and FDA pre-approval.
- Bottles:HDPE and PET containers with child-resistant closures serve high-volume oral solid and liquid formulations.
- Sachets:Single-dose flexible pouches capture powder and granule formats in emerging markets with cost-sensitive distribution.
- Ampoules:Glass break-seal containers retain niche positioning for emergency injectables and diagnostic reagents.
- Tubes:Collapsible aluminum and plastic extrusions package topical creams, ointments, and ophthalmic gels.
Leading the category by volume: Bottles. Growing fastest: Blister packs.
Service Type:
Margin structure inverts across this category, with commoditized primary packaging at the base and compliance-driven serialization commanding premium pricing tiers.
- Serialization:Unit-level aggregation with EPCIS data exchange and repository connectivity addresses FDA DSCSA and EU FMD mandates. Biologics manufacturers in the United States accelerate outsourcing as enforcement deadlines compress internal implementation timelines.
- Primary Packaging:Direct product contact operations including filling, sealing, and container closure under ISO 15378 standards. German CDMO clusters around Frankfurt coordinate pan-European distribution for oral solid and injectable formats.
- Secondary Packaging:Cartoning, leafleting, and bundle formation for shelf-ready presentation.
- Labeling:GMP-compliant printing and application with barcode verification and language adaptation.
- Inspection:Automated visual systems and manual quality checks for defect detection.
- Repackaging:Bulk-to-smaller-unit conversion for sample programs and market-specific configurations.
Highest margin capture: Serialization. Steepest expansion trajectory: Primary packaging for biologics.
Application:
Regulatory stringency escalates across this category, from standard oral solid GMP to cell therapy cryogenic packaging requiring validated ultra-low temperature protocols.
- Injectable:Vial, prefilled syringe, and cartridge formats for biologics and biosimilars. Demand clusters in Switzerland and Germany where EMA centralized procedures concentrate high-value product launches.
- Oral Solid:Tablets and capsules in blister, bottle, and sachet configurations. Generic drug makers in India outsource high-volume packaging to capture cost advantages in regulated export markets.
- Topical:Creams, ointments, and transdermal patches with specialized barrier and adhesion requirements.
- Inhalation:Dry powder and metered-dose devices with precise dose uniformity and device integration.
- Ophthalmic:Sterile single-use and multi-dose containers with preservative compatibility testing.
- Nasal:Spray pumps and drops with droplet size distribution validation for systemic absorption.
Dominant by revenue: Injectable. Expanding most quickly: Inhalation combination products.
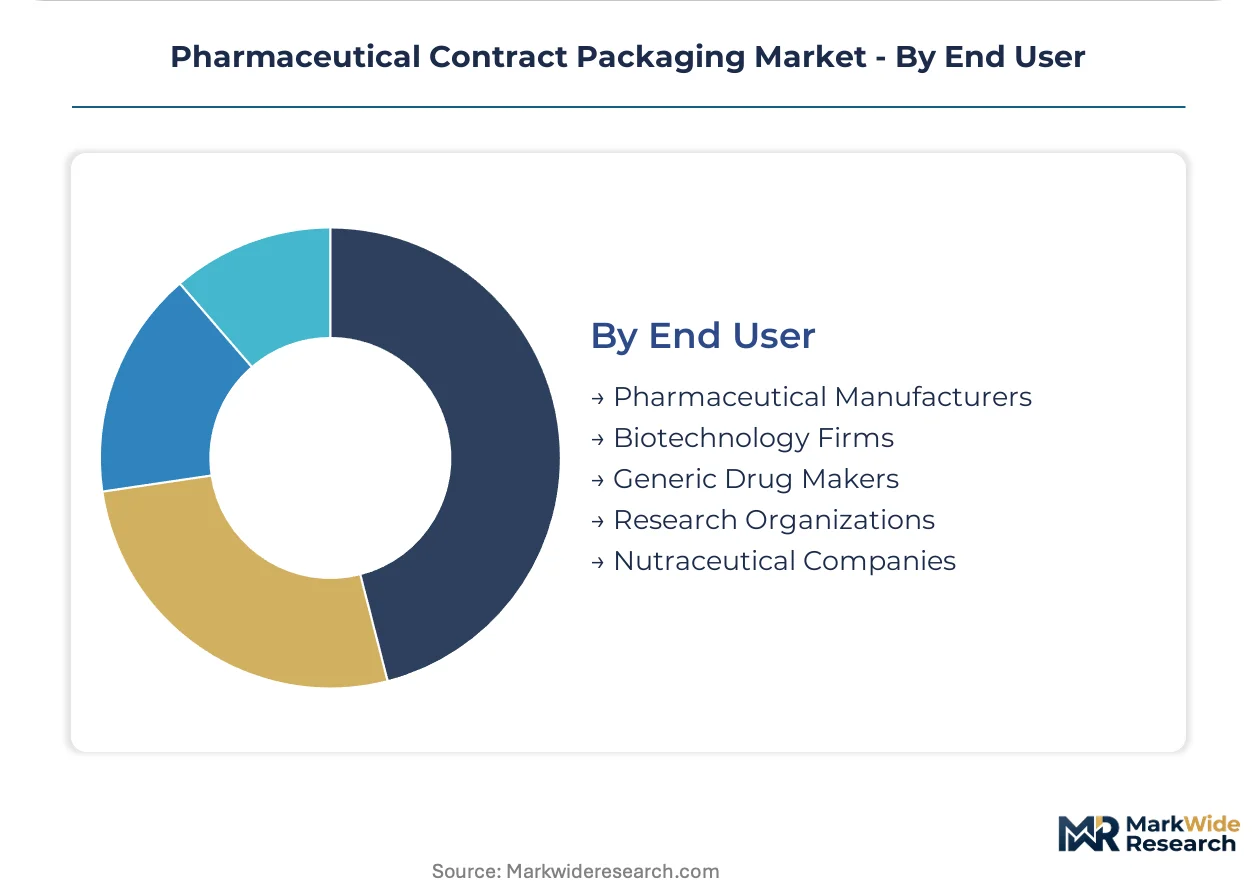
End User:
Outsourcing maturity diverges across this category, from fully integrated Big Pharma captive operations to emerging biotechs with no packaging infrastructure.
- Biotechnology Firms:Cell and gene therapy developers lacking cold-chain packaging capabilities. CAR-T manufacturers in the United States contract specialized providers for cryogenic logistics and chain-of-identity documentation.
- Pharmaceutical Manufacturers:Large-cap innovators consolidating vendor relationships around serialization-ready partners with multi-site redundancy.
- Generic Drug Makers:Cost-optimized high-volume producers sourcing standardized formats from low-cost contract hubs.
- Research Organizations:Clinical trial material packaging with investigator kit assembly and comparator sourcing.
- Nutraceutical Companies:Dietary supplement packaging with varying GMP adherence and label claim verification.
Largest contract value: Pharmaceutical manufacturers. Gaining share fastest: Biotechnology firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pharmaceutical contract packaging concentrates in jurisdictions with stringent serialization mandates and established biologics manufacturing infrastructure. Germany and the United States absorb disproportionate outsourcing volumes due to FDA DSCSA and EU FMD enforcement timelines. CDMO clustering around specific metropolitan areas reduces logistics friction for temperature-sensitive drug distribution.
United States
Biologics manufacturers in Massachusetts and California accelerate serialization outsourcing as FDA DSCSA enforcement deadlines compress internal implementation timelines. The FDA maintains aggressive inspection schedules for contract packaging facilities serving ANDA and NDA holders. Boston and San Francisco Bay Area biotech clusters drive specialized demand for cold-chain primary packaging and chain-of-identity documentation systems.
Germany
EMA centralized procedures for high-value drug approvals concentrate packaging demand among Frankfurt and Munich CDMO coordination hubs. The EU Falsified Medicines Directive enforcement shapes provider qualification criteria through intensified national competent authority inspections. Baden-Württemberg and Bavaria host dense networks of serialization-ready contract providers serving pan-European distribution networks.
Switzerland
Swissmedic oversight of biologics and biosimilars launches creates premium positioning for specialized vial and containment system packaging. The country's pharmaceutical regulator maintains rigorous GMP inspection protocols that filter market access for contract providers. Basel and Zurich regions anchor injectable primary packaging demand through proximity to major biologics innovators.
India
Generic drug makers in Maharashtra and Gujarat outsource high-volume oral solid dosage packaging to capture cost advantages in regulated export markets. CDSCO export certification requirements drive investments in ISO 15378-compliant primary contact material operations. Ahmedabad and Mumbai manufacturing corridors concentrate bottle and blister format capacity for North American and European generic supply.
United Kingdom
Post-Brexit MHRA regulatory autonomy creates parallel qualification pathways for contract packaging providers serving domestic and EU-27 markets simultaneously. The Medicines and Healthcare products Regulatory Agency maintains distinct serialization repository connectivity requirements. Southeast England and Greater Manchester clusters specialize in clinical trial material packaging and comparator sourcing for European studies.
Pharmaceutical Contract Packaging Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with serialization-capable providers commanding premium positioning against commodity primary packaging operators. Market structure tilts toward consolidation at the top tier where multi-site redundancy and pre-validated digital infrastructure determine qualification success. Three archetypes dominate: integrated CDMOs with captive packaging divisions, pure-play contract packaging specialists, and primary packaging material suppliers extending into secondary operations. Competitive dynamics center on M&A activity targeting serialization engineering talent and strategic partnerships securing cold-chain infrastructure access.
Among North American headquartered operators, PCI Pharma Services and Catalent Pharma Solutions occupy positions exemplifying integrated CDMO archetypes with multi-continental site networks. European specialists including Gerresheimer AG and Schott AG represent material-centric players leveraging glass primary packaging expertise into downstream contract service offerings. West Pharmaceutical Services, Inc. anchors the containment technology tier through elastomeric closure system specialization.
| Leading Market Players |
|---|
| PCI Pharma Services |
| Schott AG |
| West Pharmaceutical Services, Inc. |
| Sharp Services LLC |
| CCL Industries |
| Nipro Corporation |
| Gerresheimer AG |
| Nelipak Healthcare |
| Catalent Pharma Solutions |
| Others |
Cost & Logistics Intelligence
Captive serialization infrastructure investments by German and North American CDMOs anchor both supply security and premium pricing power for compliance-ready contract packaging services. This vertical integration pattern separates providers capable of FDA DSCSA and EU FMD track-and-trace execution from commodity operators exposed to margin compression.
Pricing Analysis
High-volume oral solid dosage packaging in bottles and sachets runs at thin margins, while serialization services and biologics cold-chain formats capture substantial premiums. Three-tier pricing structure across GMP-certified premium, standard ISO-compliant, and economy non-regulated tiers reflects certification grade and volume scale differentiation. Cost compression in standard blister and bottle formats is intensifying because Indian and Chinese contract hubs compete on scale for generic drug export markets. Generic drug makers exhibit acute price sensitivity, whereas biotechnology firms prioritize serialization readiness over unit cost.
Supply Chain Analysis
Direct-to-pharmacy channels for specialty biologics bypass traditional wholesale distribution, while conventional oral solid dosage formats flow through regional distribution centers and hospital procurement systems. Borosilicate glass tubing for injectable vials concentrates in Germany, the United States, and select Swiss manufacturers with EMA pre-approval. Aluminum foil cold-form substrates and elastomeric closure components feed from energy-intensive smelting and rubber processing operations concentrated in specific production geographies. Single-source vulnerability for specialized primary packaging materials creates supply continuity exposure during geopolitical trade disruptions or energy price spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified serialization engineering talent scarcity props pricing power for providers with pre-validated digital infrastructure, constraining rapid capacity expansion across the contract packaging sector.
For Market Incumbents: Lock in multi-site redundancy agreements with biotechnology firms facing compressed FDA DSCSA enforcement timelines. Prioritize backward integration into elastomeric closure and specialized glass tubing supply through strategic partnerships with German and Swiss material suppliers. Defend against emerging pure-play serialization specialists by embedding aggregation hierarchy design expertise into long-term quality agreements. For New Entrants and Emerging Players: Enter via cell therapy cryogenic packaging white space, where ultra-low temperature logistics requirements exceed capabilities of conventional cold-chain providers. Target CAR-T manufacturers in Massachusetts and California lacking validated chain-of-identity documentation systems. Pursue regulatory sandbox incentives under EU AI Act frameworks for automated visual inspection machine vision deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated CDMOs seeking serialization engineering talent and multi-site geographic coverage. Long-term viability favors providers with demonstrated EMA and FDA inspection success across the projection horizon. Acquisition target archetype: mid-cap specialists with validated cold-chain infrastructure and existing biotechnology firm relationships. Monitor EMA GMP inspection queue clearance rates as inflection indicator for qualification timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Investment | EPCIS-compliant aggregation systems enable FDA DSCSA and EU FMD qualification for biologics manufacturers. |
| Cold-Chain Capacity Expansion | Validated ultra-low temperature protocols address CAR-T and regenerative medicine packaging requirements. |
| Backward Integration into Primary Materials | Captive borosilicate tubing and elastomeric closure supply reduces import dependency exposure. |
| EU AI Act Compliance Pathway | Machine vision validation documentation qualifies automated inspection systems for regulatory sandbox incentives. |
| Direct-to-Pharmacy Distribution Partnership | Bypassing wholesale channels captures margin from oncology and rare disease specialty medication handling. |
Research Approach
Document review covered FDA DSCSA guidance documents, EMA GMP inspection reports, and EU FMD implementation guidelines, complemented by interviews with contract packaging operations directors, regulatory affairs leads at biologics manufacturers, hospital procurement managers, and serialization engineering specialists. Secondary validation drew from FDA 483 observation databases, EudraGMDP inspection records, ClinicalTrials.gov packaging protocol filings, and pharmaceutical customs trade data. Bottom-up capacity assessments at CDMO clusters around Frankfurt, Munich, Boston, and San Francisco were cross-referenced against top-down demand estimates from biologics pipeline analysis.
Historical volume trajectories for blister, vial, and bottle formats were cross-referenced against panel input from packaging procurement executives to establish baseline demand patterns across the projection horizon. Segmentation modeling incorporated packaging type, service tier, dosage form, regulatory jurisdiction cluster, and end-user outsourcing maturity. CAGRs were derived from slope-intercept analysis of qualification timeline compression and biologics launch frequency trends. Forecast inputs included EMA centralized procedure approval rates and FDA DSCSA enforcement phase transitions.
Revisions become necessary when EMA GMP inspection backlogs extend qualification timelines beyond modeled assumptions or when aluminum foil supply disruptions from energy-intensive smelting operations materialize. Forecasts reflect documented assumptions regarding serialization mandate enforcement consistency and cold-chain infrastructure investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market