
 North America Novel Drug Delivery Systems (NDDS) Market | 2026-2036
North America Novel Drug Delivery Systems (NDDS) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Novel Drug Delivery Systems (NDDS) Market Analytics
Biologics formulation science is fragmenting traditional small-molecule delivery paradigms across North American pharmaceutical development. Johnson & Johnson leverages its Janssen division's lipid nanoparticle expertise to anchor positions in oncology and immunology injectables. Pfizer sustains manufacturing scale through multi-site North American production networks for mRNA and protein-based platforms. Merck & Co. differentiates via specialized polymer conjugation capabilities that extend half-life profiles for chronic disease therapies.
Novel Drug Delivery Systems encompass engineered platforms that control the spatial and temporal release of active pharmaceutical ingredients through particle sizes typically ranging from 10 to 1000 nanometers, surface modification chemistries, or biodegradable polymer matrices. These systems serve the primary commercial purpose of improving bioavailability, reducing dosing frequency, and enabling targeting to specific tissues or cellular compartments. Injectable systems dominate current revenue pools due to biologics compatibility and hospital administration workflows, while transdermal patches represent the fastest-expanding technology segment driven by patient adherence advantages in pain management and chronic disease categories. Oral drug delivery retains the largest installed base but faces margin compression from generic competition in conventional formulations.
FDA review standards for combination products and the EPA's manufacturing emissions frameworks jointly elevate compliance costs for novel platform developers seeking North American market access. Health Canada and PMRA parallel-track requirements for cross-border product registrations create additional regulatory coordination burdens for multi-jurisdictional portfolios. Stakeholders must monitor evolving bioequivalence protocols for complex generics as these standards determine which platform innovations achieve interchangeable status versus specialty-tier reimbursement.
Market Dynamics
The FDA's accelerated approval pathways for complex generics and biologics are compressing traditional development timelines while fragmenting competitive positioning between established formulation houses and specialized platform developers.
Growth Catalysts
- Biologics expansion:Oncology departments across United States hospital networks are scaling nanoparticle-based platforms for targeted therapeutics. Injectable systems capture this demand through compatibility with mRNA and protein-based modalities.
- EPA emissions frameworks:Manufacturing compliance requirements are elevating entry barriers for novel platform developers, protecting incumbent positions for firms with validated green chemistry processes.
- Northeast corridor concentration:Contract manufacturing clusters spanning Boston and New Jersey serve cross-border pharmaceutical clients, creating network effects for platform technology transfer.
Market Restraints
- Specialized polymer feedstock volatility:PEGylation reagents and biodegradable polyester precursors face price instability from petroleum derivative linkages.
- Single-source equipment dependency:Nanoparticle manufacturing instrumentation concentrates among German and Swiss precision engineering suppliers.
- Health Canada-PMRA coordination burdens:Cross-border registration parallel-tracking creates timeline friction for multi-jurisdictional portfolios.
Strategic Opportunities
- Transdermal patch white space:Pain management and chronic disease categories in Canada show underpenetration relative to United States adoption curves.
- Lipid nanoparticle-mRNA convergence:Immunology applications beyond infectious disease prophylaxis represent unmapped territory for platform extension.
- IRA domestic manufacturing incentives:United States production tax credits favor onshoring of finished dosage form operations.
Industry Challenges
- Formulation scientist scarcity:Biologics-compatible delivery expertise outpaces North American graduate program output.
- ISO 13485 certification timelines:Combination product quality management system audits extend market entry schedules.
- Legacy ERP integration:Batch record systems for novel platforms require reconfiguration of established pharmaceutical manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Novel Drug Delivery Systems (NDDS) Market |
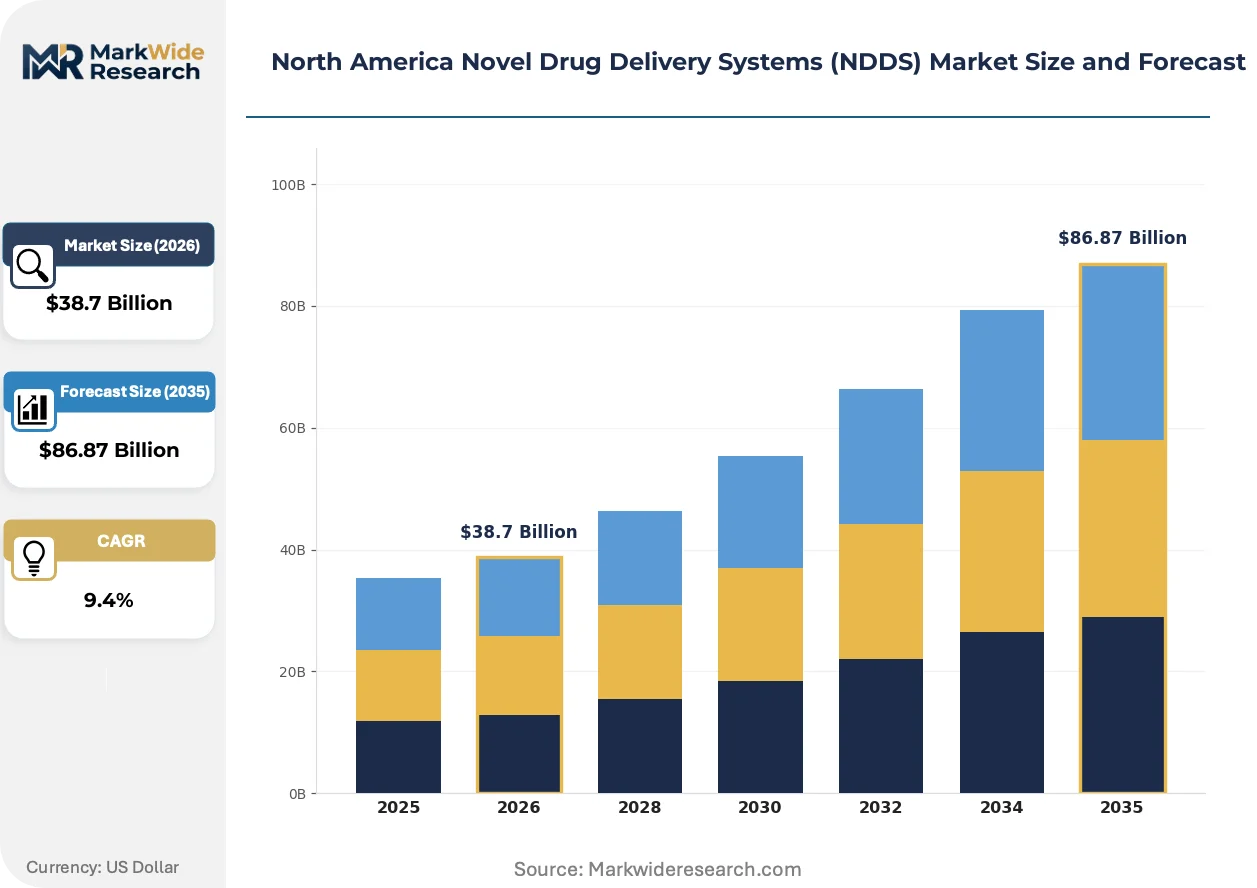
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomes, Micelles, Nanoparticles, Hydrogels Technology: Injectable Systems, Transdermal Patches, Implantable Devices, Oral Drug Delivery Application: Cancer Treatment, Vaccination, Pain Management, Chronic Diseases End User: Hospitals, Pharmacies, Research Institutions, Homecare Settings |
| Companies Covered | Johnson & Johnson, Pfizer, Novartis, Roche Holding AG, Merck & Co., AstraZeneca, GlaxoSmithKline, Bayer AG, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Novel Drug Delivery Systems (NDDS) Market Evolving Landscape
Platform engineering is fragmenting traditional delivery paradigms as biologics formulation science demands precision control over spatial and temporal release kinetics.
Lipid nanoparticle technology is migrating from infectious disease prophylaxis into oncology and immunology injectables. Hospital networks and specialty infusion centers are adopting these platforms at compressed timelines relative to historical biologic introductions. This migration is enabling targeted tissue accumulation while compressing conventional emulsion-based formulation margins.
The FDA's bioequivalence protocols for complex generics are tightening evidentiary standards for platform interchangeability. Generic developers must now demonstrate pharmacokinetic equivalence through specialized clinical study designs. United States reimbursement tiers increasingly hinge on these determinations, affecting specialty pharmacy dispensing patterns.
Hospital procurement committees are consolidating vendor relationships for injectable delivery systems around integrated platform-service bundles. Group purchasing organizations are displacing standalone device contracts with multi-year supply agreements covering formulation development through commercial fill-finish. This consolidation is most visible in Northeast corridor health systems managing high-volume biologic administration.
North America Novel Drug Delivery Systems (NDDS) Market Segmentation
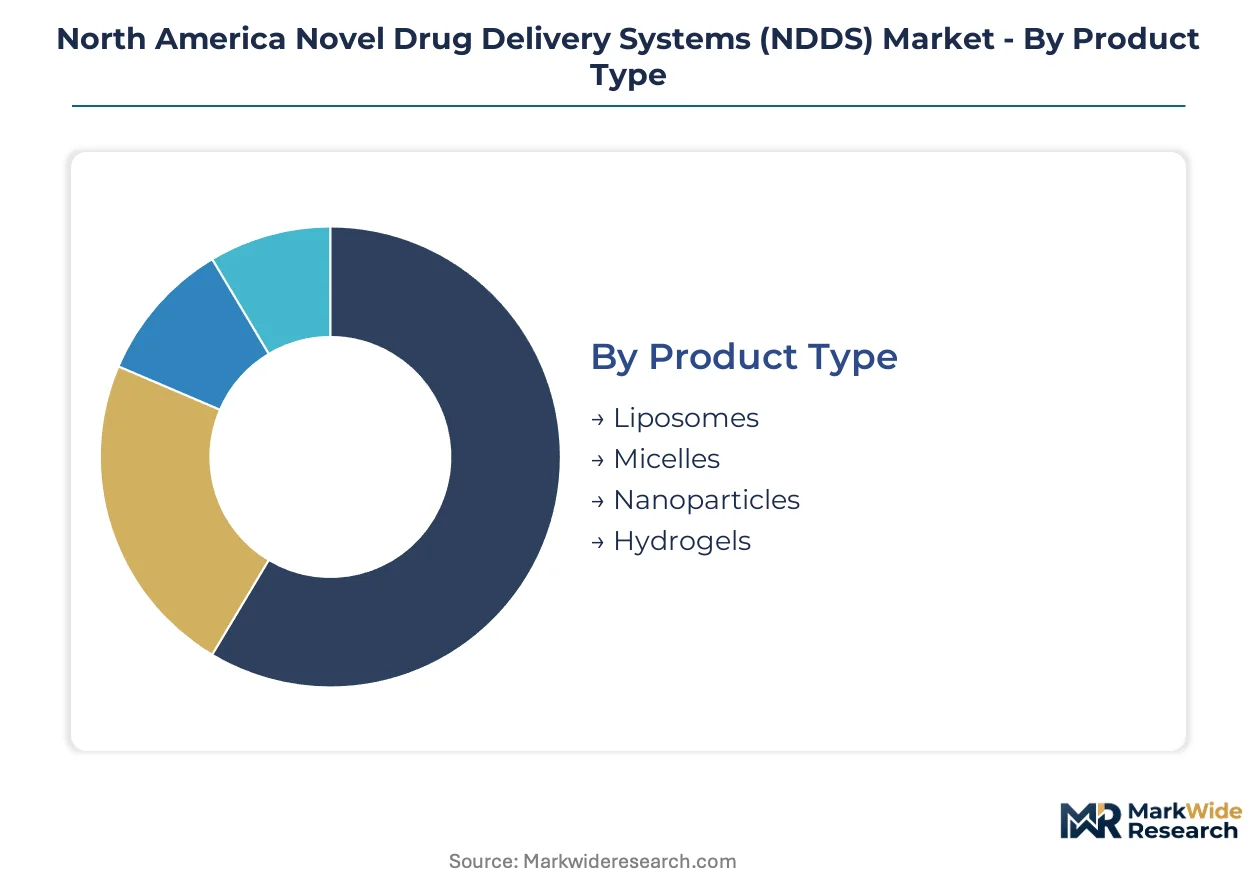
Segmentation in the North America NDDS market reveals how platform engineering aligns with distinct reimbursement pathways and administration workflows. Each dimension—product structure, delivery mechanism, therapeutic target, and care setting—carries different regulatory burdens and service intensity requirements that shape vendor economics.
Product Type:
After-sales service intensity varies sharply across these platforms, with lipid-based systems demanding specialized cold-chain logistics and polymer matrices requiring stability monitoring programs.
- Liposomes:Phospholipid bilayer vesicles encapsulate hydrophilic and hydrophobic APIs simultaneously. Northeast corridor oncology infusion centers concentrate demand for doxorubicin and paclitaxel formulations, driven by FDA-approved indications in breast and ovarian malignancies.
- Nanoparticles:Polymeric or lipid-based particulates ranging from 10-1000 nanometers enable passive targeting through enhanced permeability and retention effects. United States hospital networks scaling immuno-oncology protocols generate concentrated demand, constrained by single-source equipment dependencies for precision manufacturing.
- Micelles:Amphiphilic block copolymer assemblies solubilize poorly water-soluble drugs. These platforms serve niche applications in taxane delivery where conventional formulations fail.
- Hydrogels:Cross-linked polymer networks provide sustained release through three-dimensional matrix diffusion. Wound care and ophthalmic applications in Canadian provincial health systems show emerging uptake.
By volume, Nanoparticles leads. By growth pace, Liposomes is expanding most quickly.
Technology:
Cost tier differentiation separates these modalities, with implantable devices commanding premium pricing against commoditizing oral formulations.
- Injectable Systems:Parenteral platforms including prefilled syringes, auto-injectors, and infusion bags dominate current revenue pools. Biologics compatibility and hospital administration workflows in United States academic medical centers sustain this position, though ISO 13485 certification timelines extend market entry for new entrants.
- Transdermal Patches:Adhesive-backed matrix or reservoir systems enable non-invasive drug absorption through stratum corneum penetration. Pain management and chronic disease categories in Canada show underpenetration relative to United States adoption curves, creating white-space opportunity.
- Implantable Devices:Biodegradable or non-biodegradable depot formulations provide extended release over months to years. These systems serve long-acting contraception and hormonal therapy applications.
- Oral Drug Delivery:Conventional tablets, capsules, and emerging gastroretentive or colon-targeted platforms retain the largest installed base. Generic competition in conventional formulations compresses margins, pushing innovation toward complex modified-release architectures.
By revenue concentration, Injectable Systems dominates. By expansion trajectory, Transdermal Patches gains share fastest.
Application:
Customer type segmentation reveals how oncology biologics command specialized formulation services versus chronic disease categories emphasizing cost efficiency.
- Cancer Treatment:Targeted delivery platforms for cytotoxic agents, immune checkpoint inhibitors, and personalized cancer vaccines. United States hospital networks expanding CAR-T and antibody-drug conjugate programs drive formulation complexity, with FDA accelerated approval pathways compressing development timelines.
- Chronic Diseases:Long-acting injectables and implantable systems for diabetes, cardiovascular conditions, and autoimmune disorders. Medicare Part B reimbursement structures influence platform selection for elderly populations.
- Vaccination:Lipid nanoparticle and emulsion adjuvant platforms for infectious disease prophylaxis. Post-pandemic manufacturing capacity expansion has shifted toward seasonal influenza and RSV applications.
- Pain Management:Transdermal and implantable opioid and non-opioid delivery systems. DEA scheduling requirements and state-level prescription monitoring programs constrain product development.
By clinical trial volume, Cancer Treatment leads. By commercial maturity, Chronic Diseases shows steadiest expansion.
End User:
Supply concentration patterns favor integrated platform-service bundles for hospital procurement committees against fragmented retail pharmacy dispensing.
- Hospitals:Inpatient and outpatient infusion centers administering biologics through specialized pharmacy operations. Group purchasing organizations in the Northeast corridor consolidate vendor relationships around multi-year supply agreements.
- Homecare Settings:Self-administration of subcutaneous injectables and transdermal systems. Patient adherence advantages drive expansion in multiple sclerosis and rheumatoid arthritis categories.
- Pharmacies:Retail and specialty pharmacy channels for oral and select injectable formulations. Reimbursement tier determinations hinge on FDA bioequivalence protocols for complex generics.
- Research Institutions:Academic medical centers and contract research organizations conducting early-phase clinical trials. These users prioritize formulation flexibility over commercial scale.
By current revenue contribution, Hospitals dominates. By shift in patient volume, Homecare Settings is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border pharmaceutical trade flows from Canadian contract manufacturers serve United States hospital networks and specialty infusion centers, with Northeast corridor clusters mediating technology transfer between jurisdictions.
United States
Oncology departments in academic medical centers drive nanoparticle platform procurement for immuno-oncology protocols. FDA accelerated approval pathways compress development timelines for complex generics and biologics. The Boston-New Jersey corridor concentrates contract manufacturing capacity serving domestic and cross-border clients.
Canada
Transdermal patch adoption in pain management and chronic disease categories lags United States penetration curves, creating expansion headroom. Health Canada and PMRA parallel-track requirements add registration coordination burdens for multi-jurisdictional portfolios. Ontario and Quebec host formulation development clusters serving North American pharmaceutical clients.
Mexico
Injectable manufacturing capacity expansion targets United States export demand under nearshoring strategies. COFEPRIS regulatory alignment initiatives streamline cross-border product registrations. Baja California and Mexico City metro areas attract fill-finish investments from multinational platform developers.
North America Novel Drug Delivery Systems (NDDS) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation development, manufacturing scale, and regulatory navigation capabilities. The vendor base clusters around three archetypes: diversified pharmaceutical conglomerates with captive delivery platforms, specialized contract development and manufacturing organizations, and emerging platform technology licensors. Consolidation pressures favor integrated service bundles over standalone device or formulation contracts. Dominant competitive moves include strategic partnerships for lipid nanoparticle capacity and vertical integration into polymer feedstock supply.
Within the diversified pharmaceutical tier, Johnson & Johnson, Pfizer, and Merck & Co. occupy positions reflecting distinct platform specialization strategies. Johnson & Johnson leverages lipid nanoparticle expertise through its Janssen division. Pfizer sustains manufacturing scale across multi-site North American production networks. Merck & Co. differentiates via polymer conjugation capabilities. These three exemplify how incumbent pharmaceutical conglomerates anchor competitive positioning through formulation science investments rather than device manufacturing alone.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer |
| Novartis |
| Roche Holding AG |
| Merck & Co. |
| AstraZeneca |
| GlaxoSmithKline |
| Bayer AG |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Undercapacity in lipid nanoparticle manufacturing across the Northeast corridor is compressing supplier margins while elevating pricing power for validated platform developers serving United States hospital networks. FDA compliance timelines and EPA emissions frameworks jointly determine which contract manufacturers can absorb cost pressures versus passing them through to biologics sponsors.
Pricing Analysis
Next-generation lipid nanoparticle platforms command 40-60% premiums over conventional emulsion-based formulations, while legacy polymer conjugation systems face commoditization in chronic disease categories. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified clinical-grade supply from research-use materials and compounding pharmacy tiers. Cost compression in standard-tier injectables is intensifying because of Health Canada-PMRA parallel-track registration requirements extending development timelines. Hospital procurement committees demonstrate lowest price sensitivity due to bundled platform-service contracts, while emerging biotech sponsors exhibit highest sensitivity to fill-finish minimum order thresholds.
Supply Chain Analysis
German and Swiss export-control restrictions on precision nanoparticle manufacturing instrumentation limit equipment flows into North American production facilities, constraining capacity expansion timelines. Active pharmaceutical ingredient supply concentrates in United States, Switzerland, and India for lipid precursors and polymer feedstocks. PEGylation reagents and biodegradable polyester precursors draw from petroleum derivative markets, creating raw material cost volatility. Single-source dependency on German precision engineering suppliers represents the dominant structural risk. Distribution runs through Northeast corridor contract manufacturing clusters serving cross-border pharmaceutical clients with integrated formulation-to-fill-finish service bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering fragmentation across oncology, immunology, and chronic disease applications is creating specialized niches as hospital procurement consolidates around integrated vendor relationships rather than standalone formulation contracts.
For Market Incumbents: Pre-empt emerging platform developers by securing captive lipid nanoparticle capacity through multi-year offtake agreements with Northeast corridor contract manufacturers. Backward integration into polymer feedstock supply protects margin structures against petroleum-linked reagent volatility. ISO 13485 certification investments for combination product quality management systems extend competitive moats as FDA evidentiary standards tighten.
For New Entrants and Emerging Players: Build out transdermal patch formulation capabilities targeting Canadian provincial health systems where pain management and chronic disease penetration lags United States adoption curves. White-space concentration in lipid nanoparticle-mRNA immunology applications beyond infectious disease prophylaxis offers fastest market entry. Go-to-market execution through specialty pharmacy channel partnerships bypasses hospital GPO consolidation pressures.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lipid nanoparticle manufacturing as multi-site North American production networks require validated cold-chain infrastructure and EPA-compliant green chemistry processes. Acquisition targets with Health Canada-PMRA dual-registration capabilities and established United States hospital network relationships command strategic premiums. Signal to monitor: FDA bioequivalence protocol revisions for complex generics determining interchangeability status and reimbursement tier placement.
| Strategic Initiative | Industry Significance |
|---|---|
| Lipid Nanoparticle Capacity Expansion | Addresses undercapacity in Northeast corridor serving United States oncology infusion centers. |
| Health Canada-PMRA Dual Registration | Enables cross-border technology transfer for multi-jurisdictional biologics portfolios. |
| Green Chemistry Process Validation | Satisfies EPA emissions frameworks elevating entry barriers for novel platform developers. |
| Hospital System Partnership Agreements | Secures preferred vendor status with group purchasing organizations consolidating procurement. |
| Polymer Conjugation R&D Investment | Extends half-life profiles for chronic disease therapies differentiating against emulsion-based competitors. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings against secondary validation through FDA filings, Health Canada submissions, ClinicalTrials.gov records, and hospital GPO contract databases. Bottom-up and top-down triangulation reconciles formulation platform adoption rates with biologics pipeline progression across the analysis window.
Calibration against historical capacity utilization rates and reimbursement tier placement outcomes informs the analytical framework across product type, technology, therapeutic application, and end-user segmentation dimensions. CAGRs were derived from modeled patient volume trajectories and platform substitution elasticities, incorporating IRA domestic manufacturing incentive impacts and EPA compliance cost pass-through assumptions.
Stress conditions across FDA review timeline variability, polymer feedstock price volatility, and Health Canada-PMRA registration coordination friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding biologics expansion rates and hospital procurement consolidation trajectories. Material shifts in FDA bioequivalence protocol stringency or IRA incentive program modifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Anti-Radiation Drugs Market