
 Pentoxyverine Market | 2026-2036
Pentoxyverine Market Size, Share, and Industry Trends Forecast 2026-2036
Pentoxyverine Market Insights
The EU Green Deal is pivoting pharmaceutical manufacturing toward carbon-accounted supply chains, altering how antitussive APIs are sourced and validated across European markets. Mylan N.V. leverages backward integration into API production to secure cost advantages in generic cough suppressants. Teva Pharmaceutical Industries anchors its position through sustained R&D spending on respiratory formulation technologies. Sun Pharmaceutical Industries dominates South Asian supply with manufacturing scale across multiple dosage platforms.
Pentoxyverine citrate functions as a centrally acting cough suppressant with anticholinergic properties, typically administered at 25–100 mg doses to suppress the cough reflex through direct medullary action. Tablet and capsule formats command stable demand in institutional settings where precise dosing and extended shelf life matter, while syrup formulations lead in pediatric and homecare segments where swallowing compliance drives preference. The hospital end-user channel concentrates procurement volume through tender-based contracts, whereas online retail distribution is expanding fastest as direct-to-patient pharmacy platforms gain regulatory traction.
FDA bioequivalence standards and EMA manufacturing practice inspections shape product approval timelines and facility qualification requirements for pentoxyverine suppliers. India's CDSCO enforces sequential quality benchmarks that filter out substandard API producers, tightening market access for non-compliant manufacturers. Stakeholders must monitor evolving pharmacovigilance reporting obligations across FDA, EMA, and CDSCO jurisdictions to anticipate compliance cost shifts.
Market Dynamics
Hospital procurement centralization and API manufacturing localization are compressing supplier margins while elevating quality compliance thresholds for pentoxyverine citrate producers.
Growth Catalysts
- India's PLI scheme:The production-linked incentive program for active pharmaceutical ingredients is redirecting capital expenditure toward domestic API synthesis, reducing import dependency for cough suppressant raw materials.
- Respiratory care protocol tightening:Institutional antitussive procurement volumes are expanding as hospitals standardize cough management pathways across emergency and post-operative settings.
- Maharashtra-Gujarat cluster concentration:Pharmaceutical manufacturing scale in these western Indian states is generating API supply efficiencies that propagate through generic formulation value chains.
Market Restraints
- API input cost volatility:Piperidine derivative feedstock prices fluctuate with petrochemical base rates, squeezing margin predictability for citrate salt producers.
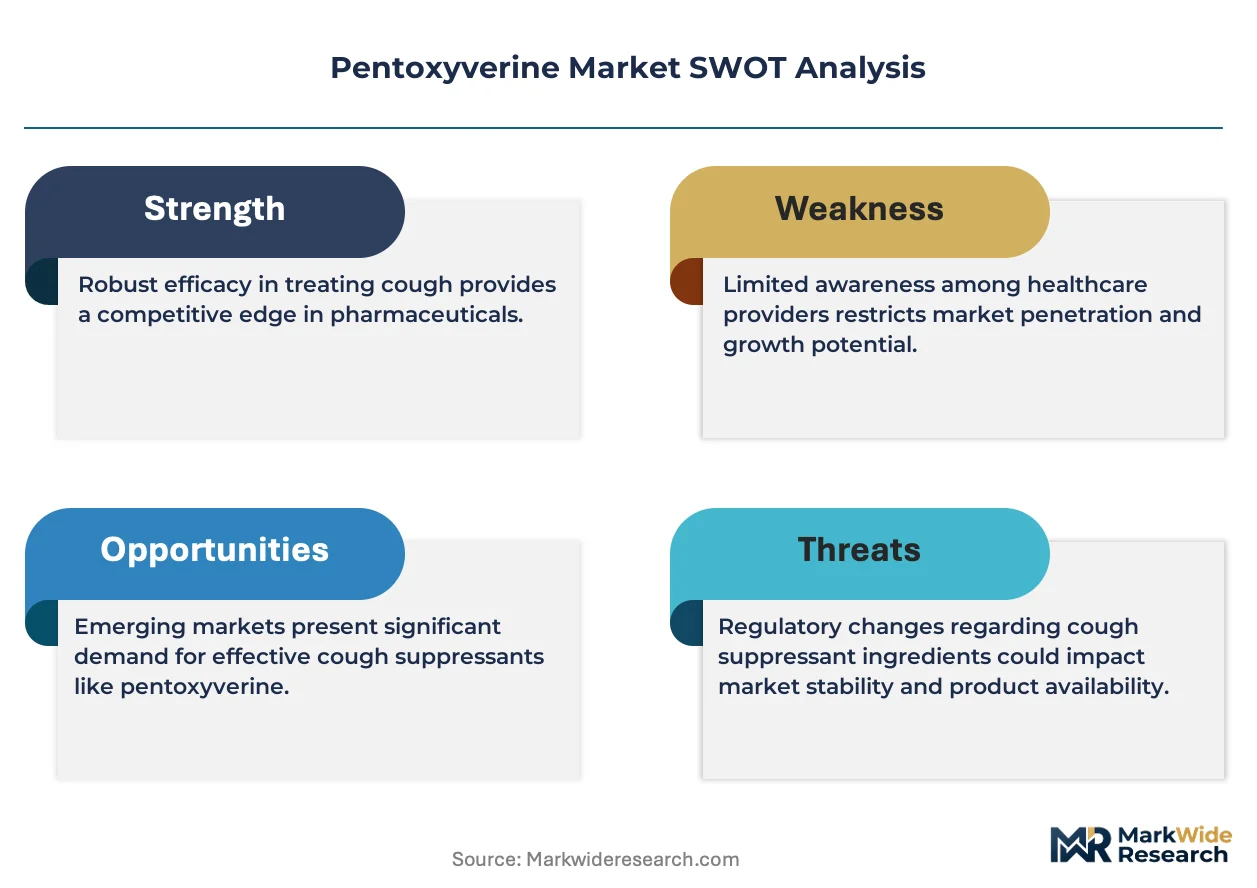
- Single-region supply concentration:China's dominance in intermediate chemical manufacturing creates chokepoint vulnerability for European and North American formulators.
- Anticholinergic side-effect profile:The compound's dry mouth and urinary retention liabilities limit pediatric and geriatric dosing flexibility compared to peripherally acting alternatives.
Strategic Opportunities
- Direct-to-patient pharmacy platforms:Online retail distribution channels are capturing volume from traditional wholesale as regulatory frameworks for e-pharmacy mature.
- Sustained-release formulation development:Extended-action tablet technologies could differentiate commoditized portfolios in tender-based hospital procurement.
- EU Green Deal carbon accounting:Early alignment with pharmaceutical supply chain emissions verification standards positions suppliers for preferential qualification in European tenders.
Industry Challenges
- Bioequivalence study capacity:FDA statistical power requirements for generic antitussive approvals strain specialized clinical pharmacology unit availability.
- Multi-jurisdiction pharmacovigilance:Sequential reporting obligations across FDA, EMA, and CDSCO systems fragment adverse event database management for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pentoxyverine Market |
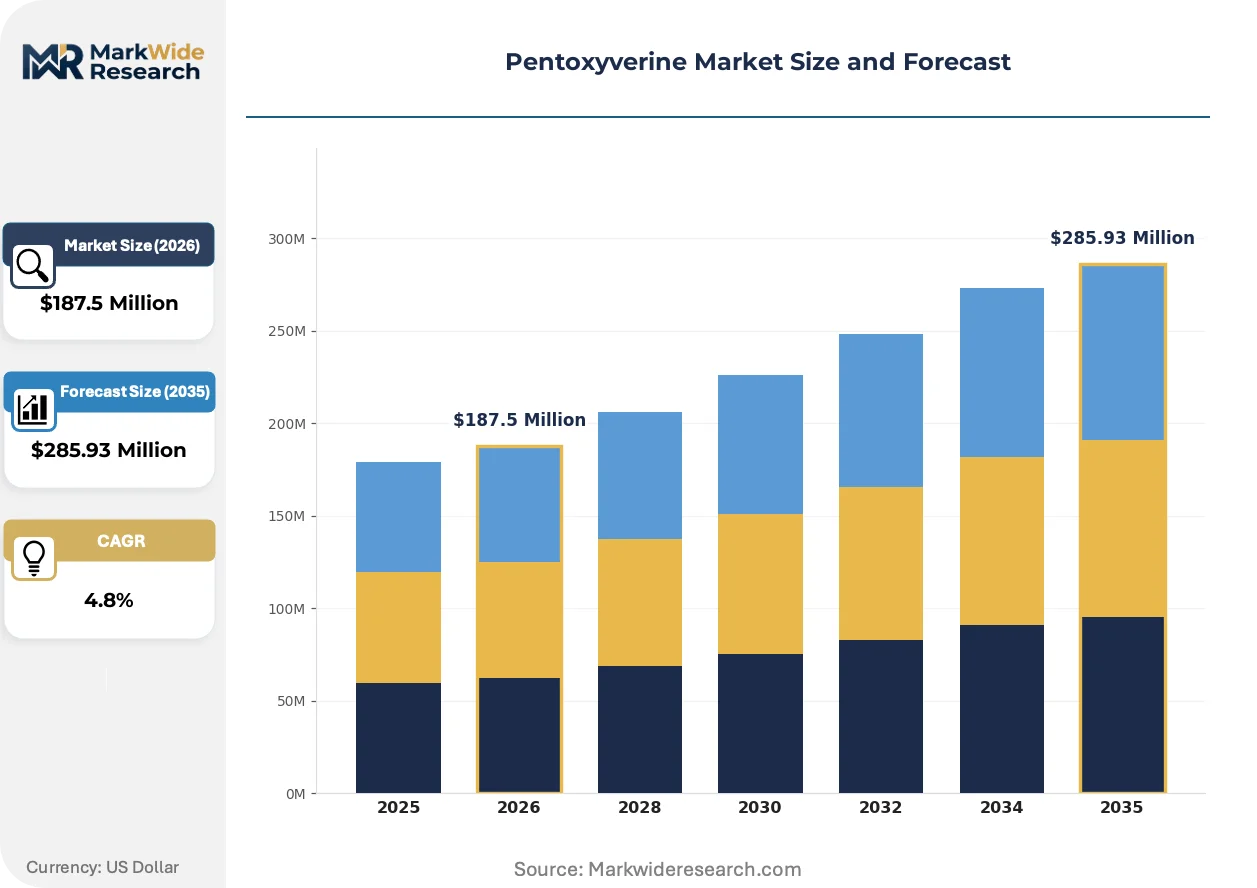
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $285.93 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Tablet, Capsule, Syrup Application: Cough Suppressant, Antitussive, Antispasmodic, Respiratory Aid End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Mylan N.V., Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Sanofi, Bausch Health Companies, Cipla Limited, Apotex, Upsher-Smith Laboratories, Zydus Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pentoxyverine Market Trends and Innovations
Continuous manufacturing technologies and carbon-accounted sourcing protocols are reconfiguring how pentoxyverine citrate API is synthesized, validated, and distributed across institutional and retail channels.
Continuous flow chemistry is modularizing batch pharmaceutical synthesis into compact, reconfigurable production units. Indian API manufacturers in Hyderabad and Visakhapatnam are piloting these systems for antitussive intermediates. The technology is modularizing capital deployment timelines from multi-year facility builds to 12-18 month installation cycles.
EMA's updated Good Manufacturing Practice Annex 1 for sterile products is tightening environmental monitoring requirements for respiratory formulation facilities. This revision elevates cleanroom validation costs for syrup producers serving European markets. German and Italian contract manufacturers are responding with isolator technology upgrades that compress personnel intervention in aseptic filling operations.
Hospital pharmacy consortiums are consolidating antitussive procurement through multi-year framework agreements that displace spot-market purchasing. These aggregated tenders concentrate volume among suppliers demonstrating dual-source API security and real-time inventory visibility. The shift is most pronounced in France and Spain where regional health authorities are unifying pharmaceutical procurement across public hospital networks.
Pentoxyverine Market Segmentation
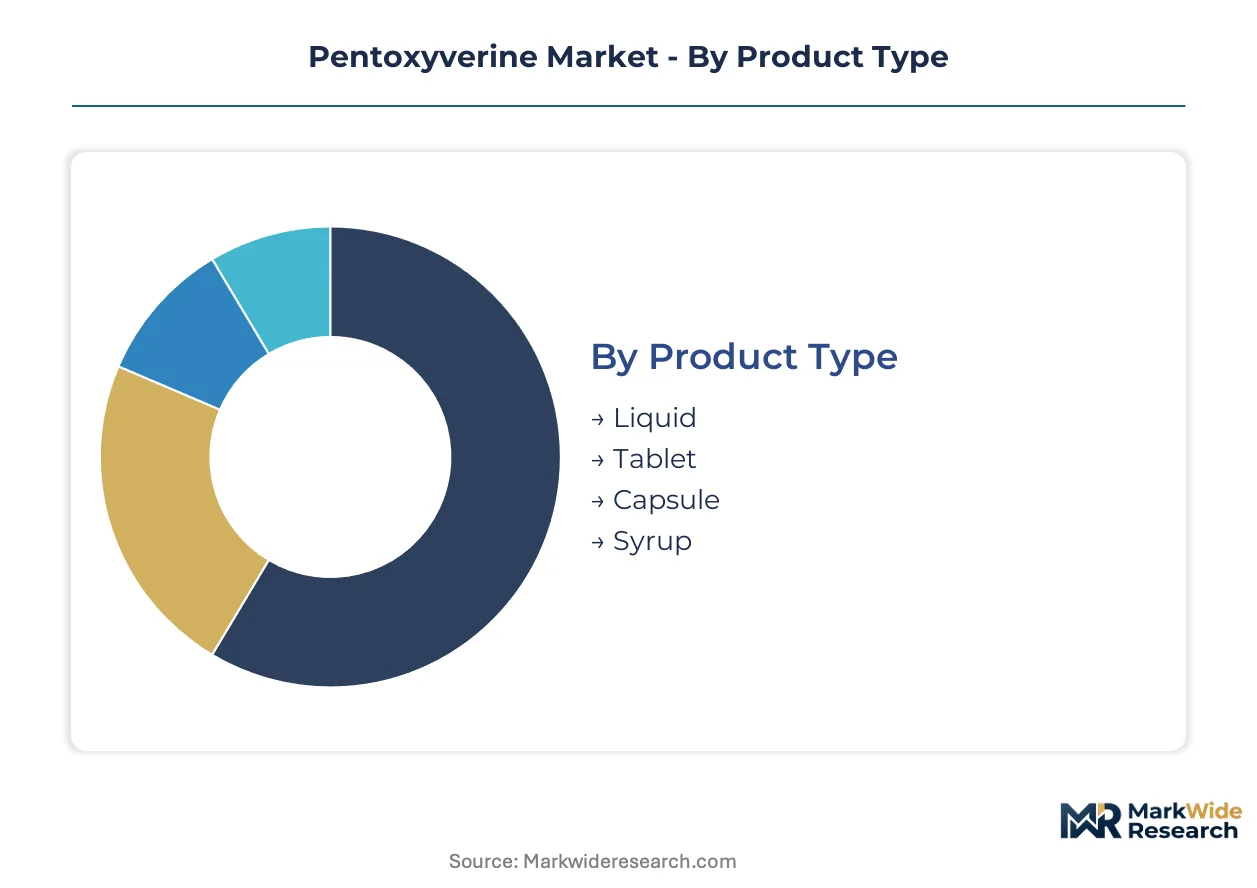
Pentoxyverine citrate formulation choices hinge on patient compliance requirements, dosing precision needs, and procurement channel economics. Each segment carries distinct margin profiles and regulatory validation burdens that reshape supplier positioning across institutional and retail channels.
Product Type:
Cost tier determines procurement channel alignment and shelf-life economics for finished formulations.
- Tablet:Compressed citrate salt formulations offer precise unit dosing and extended stability under ambient storage. Hospital pharmacy tenders in Maharashtra and Gujarat favor tablets for standardized antitussive protocols where inventory turnover predictability reduces waste.
- Syrup:Aqueous solutions with flavor masking dominate pediatric and geriatric segments where swallowing compliance limits solid dosage acceptance. CDSCO stability requirements for aqueous formulations elevate validation costs for Indian manufacturers serving domestic retail.
- Liquid:Oral solutions provide dose flexibility for weight-adjusted pediatric prescribing. Maharashtra pharmaceutical clusters supply liquid formats to Southeast Asian export markets.
- Capsule:Gelatin-shell encapsulation protects hygroscopic API from moisture degradation during monsoon distribution. Gujarat-based formulators leverage capsule technology for premium positioning in direct-to-patient channels.
Volume sits with Tablet; growth tilts toward Syrup.
Application:
Clinical indication breadth shapes reimbursement coding and prescriber targeting strategies.
- Cough Suppressant:Centrally acting medullary depression of the cough reflex represents the primary therapeutic claim. Emergency departments in Indian tertiary hospitals standardize pentoxyverine for post-extubation cough management.
- Antitussive:Mechanism-specific labeling aligns with EMA pharmacovigilance categories for respiratory actives. European formulators emphasize antitussive classification to secure preferential tender scoring.
- Antispasmodic:Smooth muscle relaxation properties extend prescribing to bronchospasm-associated cough. This secondary indication captures volume in Indian chest medicine clinics.
- Respiratory Aid:Broad symptomatic positioning supports over-the-counter retail placement. Online pharmacy platforms in India promote respiratory aid labeling for consumer self-selection.
Prescription volume clusters in Cough Suppressant; retail expansion favors Respiratory Aid positioning.
End User:
Customer type dictates compliance infrastructure requirements and procurement decision speed.
- Hospitals:Centralized pharmacy committees execute multi-year framework tenders with dual-source API mandates. French and Spanish regional health authorities aggregate hospital procurement into single negotiating entities.
- Homecare:Patient-directed administration outside clinical settings demands child-resistant packaging and clear dosing instructions. Indian e-pharmacy platforms capture homecare volume through same-city delivery guarantees.
- Clinics:Outpatient prescribing concentrates in respiratory and general practice settings. Clinic procurement runs through distributor stockist networks rather than direct manufacturer contracts.
- Pharmacies:Community retail channels balance prescription fulfillment with over-the-counter recommendation. Maharashtra pharmacy chains maintain pentoxyverine syrup inventory for monsoon season demand spikes.
Revenue concentrates in Hospitals; Homecare is expanding most quickly.
Distribution Channel:
Supply chain configuration determines working capital intensity and price transparency exposure.
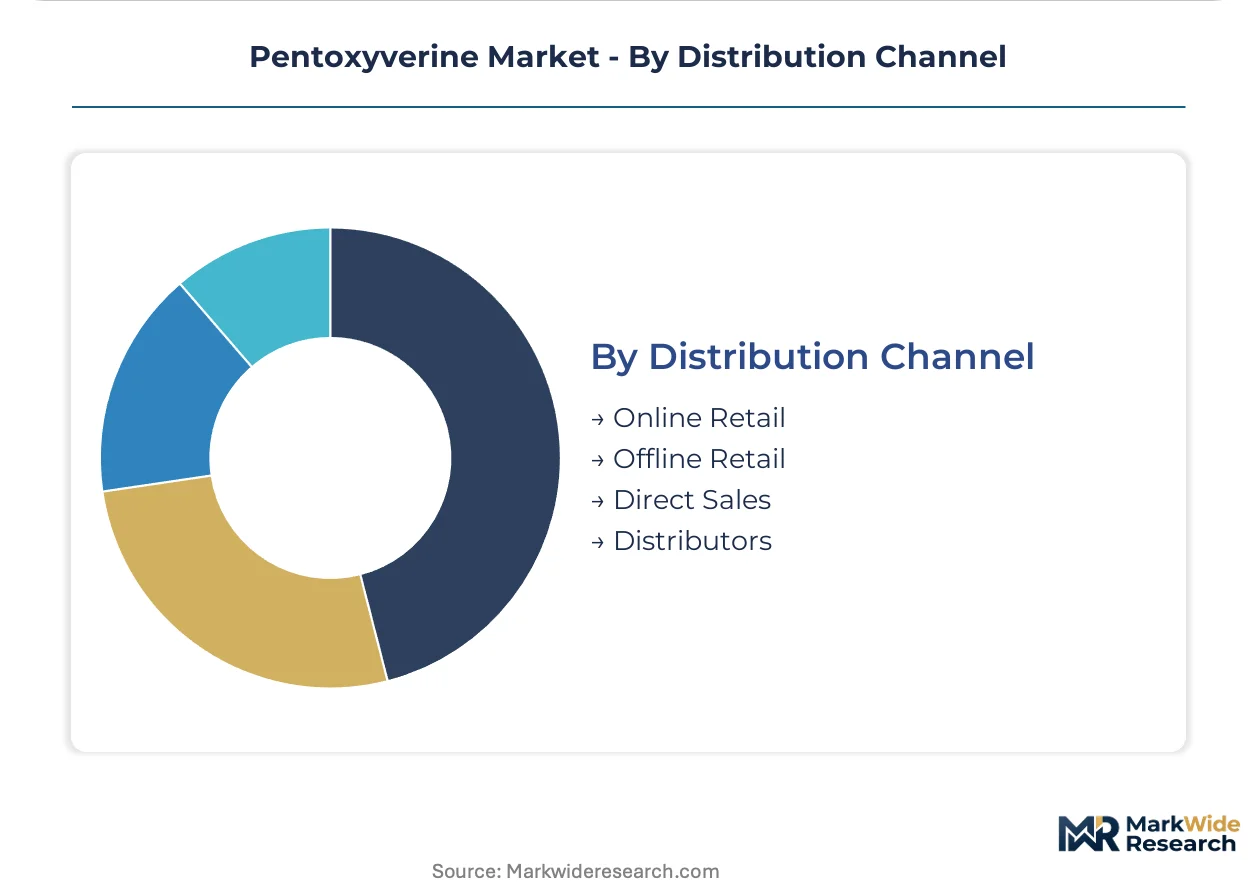
- Online Retail:Direct-to-patient pharmacy platforms bypass wholesale markups while capturing prescription upload compliance. Indian regulatory frameworks for e-pharmacy are maturing, enabling platform-based volume aggregation.
- Direct Sales:Manufacturer-to-institution contracts eliminate distributor margins for high-volume hospital tenders. German contract manufacturers deploy direct sales teams for European hospital consortium penetration.
- Offline Retail:Brick-and-mortar pharmacy networks remain dominant for acute cough purchases requiring immediate fulfillment. Gujarat pharmacy associations maintain offline retail preference for generic antitussive stocking.
- Distributors:Stockist networks extend geographic reach into tier-2 and tier-3 Indian cities where manufacturer direct presence is uneconomical. Distributor credit terms support pharmacy inventory financing.
Transaction volume flows through Offline Retail; margin expansion favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis concentrates in western Indian pharmaceutical clusters while European and North American markets absorb formulated finished goods through hospital procurement channels.
India
Domestic antitussive formulation demand expands through Maharashtra and Gujarat manufacturing corridors. The CDSCO enforces sequential quality benchmarks that filter substandard API producers from export eligibility. Hyderabad and Visakhapatnam clusters pilot continuous flow chemistry systems for antitussive intermediates.
United States
Hospital pharmacy consortiums consolidate pentoxyverine procurement through multi-year framework agreements. FDA bioequivalence standards shape generic antitussive approval timelines and facility qualification requirements. Indian API suppliers navigate FDA pre-approval inspection protocols to maintain US market access.
Germany
EMA manufacturing practice inspections elevate cleanroom validation costs for respiratory formulation facilities serving European markets. The EU Green Deal carbon-accounted supply chain protocols alter how antitussive APIs are sourced and validated. German contract manufacturers deploy isolator technology upgrades that compress personnel intervention in aseptic filling.
France
Regional health authorities aggregate hospital pharmaceutical procurement into single negotiating entities across public hospital networks. EMA pharmacovigilance categories for respiratory actives shape antitussive labeling strategies. Lyon and Paris pharmaceutical service hubs coordinate tender-based volume concentration.
Spain
Public hospital network unification drives antitussive procurement centralization through aggregated tenders with dual-source API mandates. EMA updated GMP Annex 1 requirements tighten environmental monitoring for sterile respiratory products. Barcelona and Madrid manufacturing zones adapt formulation facilities to meet elevated European standards.
Pentoxyverine Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with backward integration into API production. Market concentration remains moderate with tiered positioning between research-intensive innovators and scale-driven generic specialists. Three archetypes dominate: vertically integrated API-to-formulation producers, respiratory-focused portfolio specialists, and broad generic platform operators. Capacity expansion in Indian manufacturing clusters and strategic partnerships for sustained-release formulation technology represent the dominant competitive moves.
Among vertically integrated API producers, Mylan N.V. exemplifies backward integration strategies that secure cost advantages in generic cough suppressants. Teva Pharmaceutical Industries occupies a position as a respiratory formulation technology anchor through sustained R&D infrastructure. Sun Pharmaceutical Industries represents the scale-driven generic platform archetype with manufacturing presence across multiple dosage platforms in South Asian supply corridors.
| Leading Market Players |
|---|
| Mylan N.V. |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Sanofi |
| Bausch Health Companies |
| Cipla Limited |
| Apotex |
| Upsher-Smith Laboratories |
| Zydus Lifesciences |
| Others |
Pricing and Supply Chain Analysis
Backward integration into API production anchors both supply security and pricing leverage for pentoxyverine citrate manufacturers. Mylan N.V. and Teva Pharmaceutical Industries leverage captive piperidine derivative supply to buffer margin erosion from petrochemical feedstock volatility while commanding preferential tender positioning in hospital procurement channels.
Pricing Analysis
Margin tightening in generic tablet formulations reflects Maharashtra-Gujarat cluster overcapacity and tender-based volume aggregation. Three-tier pricing structure across premium capsule, standard tablet, and economy syrup levels segments buyers by compliance infrastructure and dosing precision requirements. Hospital pharmacy committees exhibit lowest price sensitivity due to dual-source API mandates, while direct-to-patient platforms face acute cost compression from same-city delivery guarantees. Pricing pressure intensifies in syrup segments as CDSCO stability requirements elevate validation costs for aqueous formulations.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients is redirecting capital expenditure toward domestic piperidine derivative synthesis, reducing import dependency for cough suppressant raw materials. API manufacturing concentrates in India, China, and Germany, with formulation finishing distributed across European hospital pharmacy consortiums. Piperidine derivative feedstock, citrate salt precursors, and gelatin capsule shells constitute critical input dependencies. Single-region intermediate concentration in Chinese chemical manufacturing creates chokepoint vulnerability for European and North American formulators. Distribution runs through hospital tender aggregators in France and Spain, stockist networks in tier-2 Indian cities, and maturing e-pharmacy platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API synthesis capacity bottlenecks in western Indian pharmaceutical clusters prop pricing power for qualified suppliers. Hospital procurement centralization and carbon-accounted sourcing mandates from the EU Green Deal constrain supply elasticity.
For Market Incumbents: To counter margin compression from Maharashtra-Gujarat manufacturing overcapacity, Mylan N.V. and Sun Pharmaceutical Industries should deepen backward integration into piperidine derivative production and secure dual-source API certifications for European hospital tenders. Isolator technology upgrades for aseptic syrup filling address EMA Annex 1 compliance costs while defending premium positioning. For New Entrants and Emerging Players: Launch via direct-to-patient pharmacy platforms in Indian homecare segments where regulatory frameworks for e-pharmacy are maturing and swallowing compliance drives syrup preference. Target sustained-release formulation development for tender-based hospital procurement differentiation, leveraging continuous flow chemistry pilot programs in Hyderabad and Visakhapatnam clusters to compress capital deployment timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in respiratory-focused portfolio specialists with demonstrated FDA pre-approval inspection clearance and real-time inventory visibility systems for hospital consortium frameworks. Long-term viability hinges on carbon-accounted supply chain alignment with EU Green Deal verification standards. Watch EMA pharmacovigilance reporting obligation harmonization across FDA and CDSCO jurisdictions as regulatory compliance cost inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Mylan N.V. secures cost advantages in generic cough suppressants through captive piperidine derivative supply. |
| Continuous Flow Chemistry Adoption | Hyderabad manufacturers compress antitussive intermediate synthesis timelines from multi-year builds to 12-18 month installations. |
| Isolator Technology Upgrade | German contract manufacturers reduce personnel intervention in aseptic filling to meet EMA Annex 1 sterile product requirements. |
| Direct-to-Patient Platform Launch | Indian e-pharmacy platforms capture homecare volume through same-city delivery guarantees and prescription upload compliance. |
| Sustained-Release Formulation Development | Extended-action tablet technologies differentiate commoditized portfolios in tender-based hospital procurement frameworks. |
Research Methodology
FDA filings, EMA manufacturing practice inspection records, and CDSCO quality benchmark notifications formed the secondary backbone of this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at tertiary care institutions in Maharashtra, Gujarat, France, and Spain provided demand-side validation. Customs data on piperidine derivative trade flows and pharmaceutical API import patterns supplemented supply-side triangulation. Bottom-up volume estimates from formulation production data and top-down market sizing from hospital pharmaceutical expenditure aggregates were reconciled across the analysis window.
Historical trendline analysis of antitussive API pricing and hospital tender award patterns informed the projection framework. Segmentation modeling incorporated dosage form, end-user channel, distribution mechanism, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of volume and value trajectories, adjusted for PLI scheme capacity addition timelines and EU Green Deal carbon accounting implementation phases. Forecast inputs included respiratory care protocol standardization rates and e-pharmacy regulatory maturation indicators.
Feedstock petrochemical price volatility, single-source intermediate concentration events, and pharmacovigilance reporting obligation fragmentation are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding CDSCO quality benchmark enforcement continuity and EMA Annex 1 compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Global Montelukast Sodium Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Carbapenem Market