
 Oxygen Indicator Labels Market | 2026-2036
Oxygen Indicator Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Indicator Labels Market Analytics
The EU Green Deal's packaging sustainability targets is pivoting pharmaceutical and food manufacturers toward smarter, waste-reducing verification systems. Mitsubishi Gas Chemical leverages its materials science heritage to dominate oxygen scavenging and indicator chemistry. 3M competes through adhesive and film technology leadership across healthcare packaging. Insignia Technologies specializes in colorimetric freshness indicators for protein-based food products.
Oxygen indicator labels are adhesive or substrate-mounted sensors that undergo reversible or irreversible color change when exposed to threshold oxygen concentrations, typically employing redox dyes such as methylene blue or palladium-catalyzed systems within polymer matrices. These devices enable non-instrumental verification of package integrity in modified atmosphere packaging, sterile medical devices, and anaerobic pharmaceutical environments. Self-adhesive labels occupy the largest volume position due to compatibility with existing packaging lines, while electronic indicators represent the fastest-growing technology segment as cold chain digitization accelerates. Food packaging anchors the application base, though medical devices and pharmaceuticals concentrate the highest margin pools where regulatory validation commands premium pricing.
FDA quality system regulations and EU MDR sterile barrier requirements shape product validation protocols and market access conditions for indicator label suppliers. ISO 11607 and ASTM F2097 standards define performance benchmarks that differentiate qualified suppliers from commodity producers. Stakeholders must monitor convergence between chemical indicator performance and connected packaging platforms as serialization mandates expand beyond pharmaceuticals into high-value food segments.
Market Dynamics
Pharmaceutical serialization mandates and cold chain digitization are compressing validation timelines while forcing indicator chemistry toward electronic integration. The tension between legacy colorimetric systems and connected packaging platforms is redrawing supplier capability requirements.
Growth Catalysts
- EU MDR sterile barrier requirements:Medical device manufacturers in Germany and Ireland now mandate oxygen verification for Class IIb and III implants, expanding qualified supplier rosters.
- Modified atmosphere packaging:Protein processors across Japan and the United States deploy irreversible indicators to reduce spoilage claims and extend retail shelf positioning.
- Palladium-catalyzed redox systems:These chemistries enable faster color transition at lower oxygen thresholds, satisfying anaerobic pharmaceutical specifications.
Market Restraints
- Palladium price volatility:Catalyst loading in premium indicators ties cost structures to precious metal commodity swings, compressing margin predictability.
- Adhesive polymer supply concentration:Acrylic and silicone pressure-sensitive formulations depend on German and Japanese chemical conglomerates, creating geographic chokepoints.
- Reversible indicator reliability gaps:Methylene blue systems suffer false-positive rates in high-humidity environments, limiting adoption in tropical logistics corridors.
Strategic Opportunities
- India pharmaceutical exports:CDSCO alignment with EU MDR and US FDA standards creates validation service demand for indicator suppliers establishing local technical support.
- Electronic indicator convergence:Integration of RFID-NFC platforms with chemical sensors enables real-time oxygen logging for high-value biologics.
- EU Green Deal packaging targets:Waste-reduction mandates favor single-use indicator labels over separate oxygen scavenger sachets in food applications.
Industry Challenges
- ISO 11607-1 validation timelines:Sterile barrier qualification protocols demand 12-18 month stability studies, delaying product commercialization.
- Legacy packaging line integration:Automated label applicators require sensor calibration rework, raising retrofit capex for mid-scale pharmaceutical contract manufacturers.
- Cross-contamination risk in multi-product facilities:Indicator dye migration between pharmaceutical and food production lines triggers regulatory scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Indicator Labels Market |
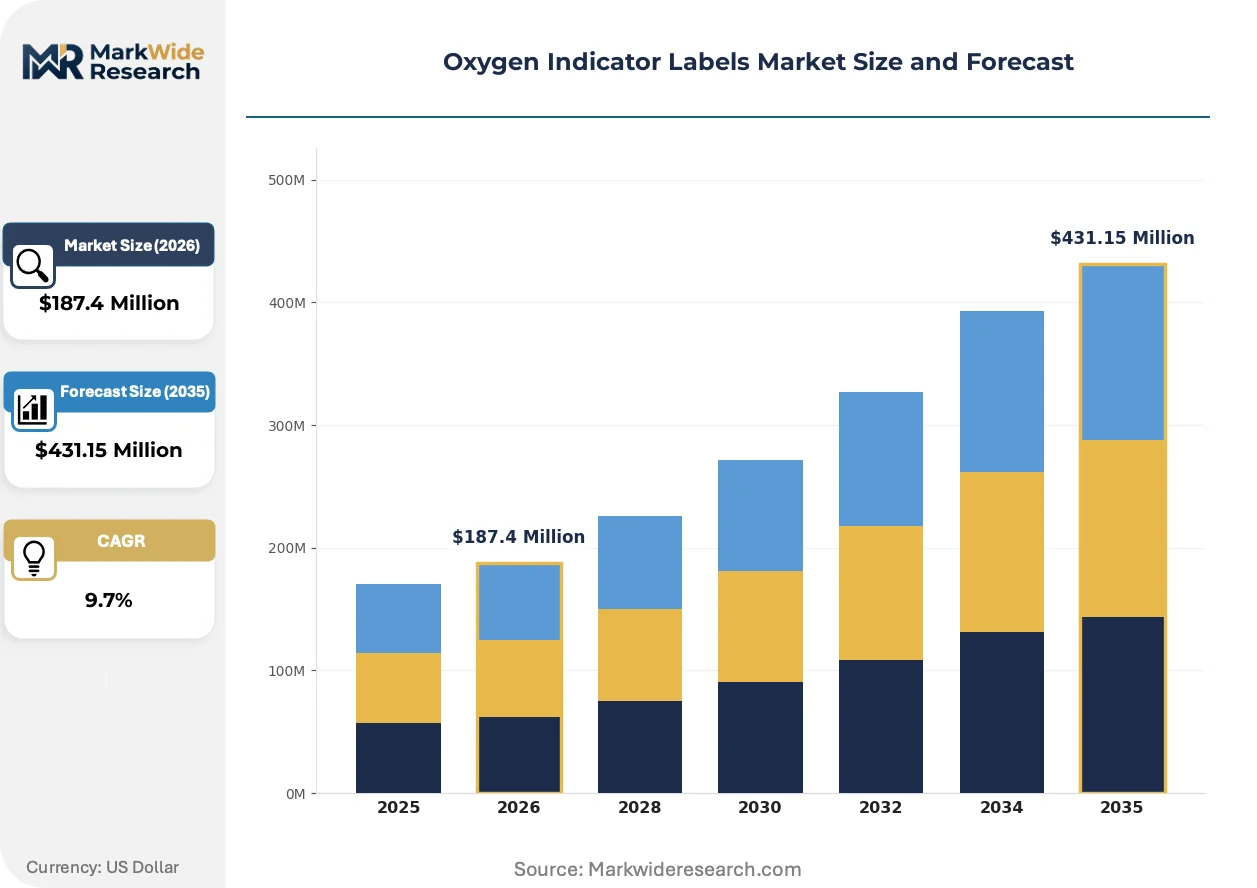
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-adhesive Labels, Heat-shrinkable Labels, Direct-printed Labels, Pressure-sensitive Labels Application: Food Packaging, Medical Devices, Pharmaceuticals, Industrial Applications End User: Food Manufacturers, Healthcare Providers, Chemical Industries, Logistics Companies Technology: Colorimetric Indicators, Electronic Indicators, Visual Indicators, Chemical Indicators |
| Companies Covered | 3M, Mitsubishi Gas Chemical, Temptime, Timestrip, OxySense, FreshPoint, Cryolog, Insignia Technologies, Paksense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Indicator Labels Market Evolving Landscape
Digital integration is absorbing traditional colorimetric functions while regulatory convergence compresses regional specification divergence. Chemistry suppliers face capability bets between electronic and chemical platform investments.
Printed electronics is absorbing oxygen sensing functions through thin-film transistor arrays deposited on flexible substrates. Pharmaceutical cold chain operators in Switzerland and the Netherlands pilot these platforms for continuous oxygen logging during transoceanic shipments. The technology is absorbing validation documentation burdens that previously required separate data loggers.
EU MDR Annex I technical documentation requirements now mandate sterile barrier integrity verification across all implantable device categories. German notified bodies enforce ISO 11607-2 audit protocols that disqualify indicator suppliers lacking Design Dossier support capabilities. Medical device contract manufacturers in Baden-Württemberg accelerate supplier consolidation toward full-service validation partners.
Biologics procurement teams now bundle indicator specifications into primary packaging tenders rather than sourcing separately. This pattern concentrates purchasing leverage with global pharmaceutical packaging integrators and marginalizes standalone indicator vendors. The shift is most visible in Massachusetts and North Carolina manufacturing clusters where top-five biologics producers centralize supply chain governance.
Oxygen Indicator Labels Market Segmentation
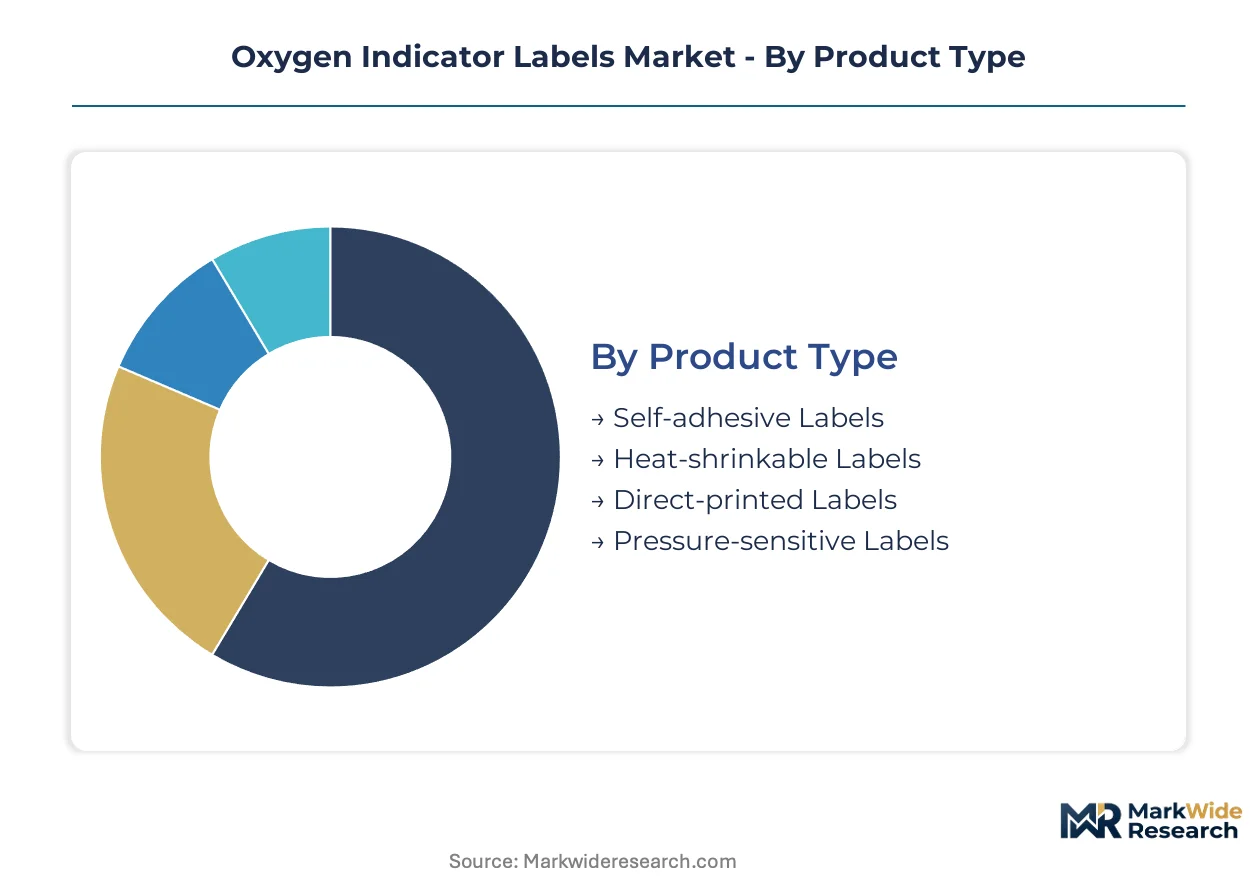
Oxygen indicator labels serve divergent buyer needs across packaging automation maturity, regulatory stringency, and value-at-risk thresholds. Segmentation reveals where chemical legacy systems retain dominance versus where electronic platforms capture premium positioning.
Product Type:
Buyers differentiate primarily by packaging line retrofit cost versus integration complexity.
- Self-adhesive Labels:Acrylic or silicone pressure-sensitive substrates enable manual or automated application onto flexible films and rigid trays. Food manufacturers in Germany and Japan favor these for compatibility with legacy thermoforming lines without capital retooling. These dominate volume positions across protein packaging and pharmaceutical blister formats.
- Heat-shrinkable Labels:PET-G or PVC sleeves conform to irregular container geometries during tunnel shrinking, embedding oxygen sensors within tamper-evident bands. Beverage and ready-meal processors deploy these where 360-degree coverage matters more than per-unit cost.
- Direct-printed Labels:Redox dyes integrate into primary packaging substrates during extrusion or coating, eliminating secondary label application. This appeals to high-volume pharmaceutical contract manufacturers seeking line simplification.
- Pressure-sensitive Labels:Engineered adhesive formulations bond to low-surface-energy plastics and glass vials, serving biologics cold chain requirements where delamination risks catastrophic sterility breach.
Self-adhesive labels lead volumes today; electronic indicator integration is gaining share fastest in pharmaceutical applications.
Application:
Margin concentration tracks regulatory validation burden and consequence-of-failure severity.
- Food Packaging:Modified atmosphere packaging for red meat, poultry, and ready-to-eat meals drives irreversible indicator consumption. Japanese retailers mandate oxygen verification for vacuum-packed sashimi and premium beef exports.
- Medical Devices:Class IIb and III implantable devices require sterile barrier integrity documentation under EU MDR Annex I. German notified bodies enforce ISO 11607-2 protocols that elevate qualified supplier requirements.
- Pharmaceuticals:Anaerobic drug formulations and biologics storage command premium pricing for palladium-catalyzed systems with sub-0.5% oxygen detection thresholds. Massachusetts and North Carolina manufacturing clusters concentrate demand.
- Industrial Applications:Electronics manufacturing and aerospace components use indicators for hermetic seal verification where nitrogen purging protects moisture-sensitive assemblies.
Food packaging anchors absolute volumes; pharmaceuticals capture the steepest margin expansion trajectory.
End User:
Procurement sophistication separates specification-driven healthcare buyers from cost-optimized commodity purchasers.
- Food Manufacturers:Protein processors and ready-meal assemblers prioritize spoilage claim reduction over sensor precision, driving methylene blue system volumes.
- Healthcare Providers:Hospital pharmacy and surgical kit sterilization services demand validated indicator documentation for liability protection.
- Chemical Industries:Specialty chemical and agrochemical producers monitor oxygen ingress during extended storage of oxidation-sensitive compounds.
- Logistics Companies:Third-party cold chain operators pilot RFID-integrated indicators for real-time oxygen logging during transoceanic biologics shipments.
Food manufacturers drive current procurement volumes; logistics companies are expanding adoption most aggressively through digitization mandates.
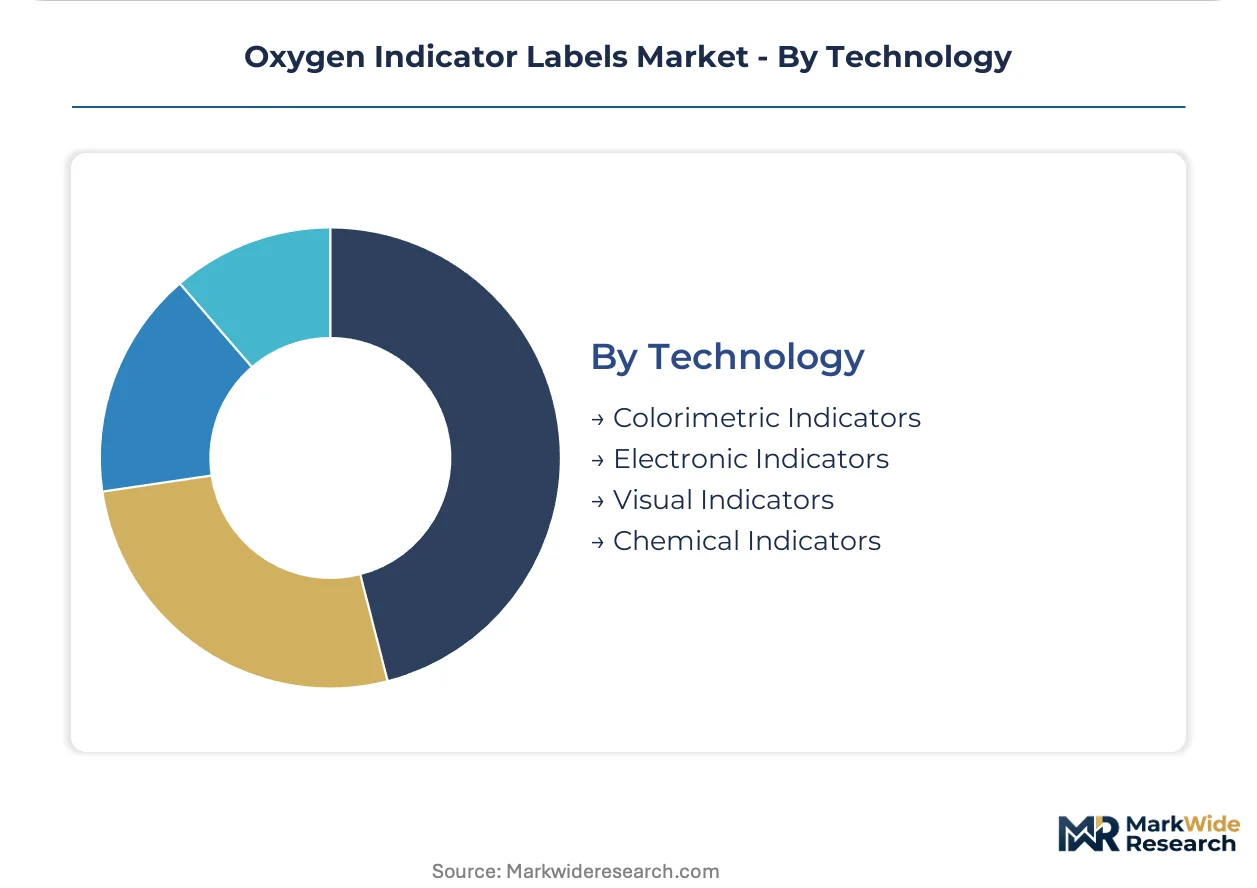
Technology:
Platform selection crystallizes around the trade-off between capital cost and data granularity.
- Colorimetric Indicators:Methylene blue and palladium-catalyzed redox dyes undergo irreversible or reversible color transitions at threshold oxygen concentrations. These remain the default for cost-sensitive food applications despite humidity sensitivity limitations in tropical corridors.
- Electronic Indicators:Thin-film transistor arrays and RFID-NFC platforms enable continuous oxygen logging with timestamped data transmission. Swiss and Dutch pharmaceutical cold chain operators pilot these for regulatory documentation automation.
- Visual Indicators:Simplified go/no-go color change systems serve consumer-facing freshness verification without quantitative readout requirements.
- Chemical Indicators:Broad category encompassing redox, pH-shift, and enzymatic reaction systems beyond oxygen-specific detection.
Colorimetric systems retain installed base dominance; electronic platforms are climbing the fastest as serialization mandates expand beyond pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive chemists and sterile barrier validation engineers concentrate in Germany, the United States, and Japan where pharmaceutical manufacturing clusters demand precision oxygen verification systems.
United States
FDA quality system regulations and biologics serialization mandates drive oxygen indicator procurement in Massachusetts and North Carolina manufacturing corridors. The FDA's sterile barrier integrity requirements for Class IIb and III devices elevate supplier qualification burdens. Boston-area contract manufacturers centralize purchasing leverage with packaging integrators who bundle indicator specifications into primary tender packages.
Germany
EU MDR Annex I technical documentation requirements and ISO 11607-2 audit protocols reshape sterile barrier verification demand in Baden-Württemberg medical device clusters. German notified bodies enforce design dossier capabilities that disqualify indicator suppliers lacking validation documentation support. Stuttgart-area contract manufacturers accelerate supplier consolidation toward full-service partners capable of 12-18 month stability studies.
Japan
Modified atmosphere packaging for premium protein exports and PMDA pharmaceutical quality standards anchor oxygen indicator consumption. METI packaging sustainability guidelines pivot food processors toward waste-reducing verification systems. Osaka-area protein processors deploy irreversible indicators for vacuum-packed sashimi and Wagyu beef destined for retail chains.
Switzerland
Swissmedic biologics regulations and cold chain digitization mandates pilot electronic oxygen logging platforms in Basel and Zurich pharmaceutical logistics corridors. Swiss cold chain operators test thin-film transistor arrays for continuous oxygen monitoring during transoceanic shipments. Geneva-area third-party logistics providers integrate RFID-NFC sensors with chemical indicators for real-time documentation automation.
India
CDSCO alignment with EU MDR and US FDA standards creates validation service demand as pharmaceutical exports expand. The country's national pharmaceutical regulator tightens sterile barrier requirements for export-oriented contract manufacturers. Hyderabad and Mumbai manufacturing clusters seek local technical support from indicator suppliers establishing regional validation capabilities.
Oxygen Indicator Labels Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the oxygen indicator landscape. Chemical conglomerates with captive materials science capabilities dominate palladium-catalyzed redox chemistry and adhesive polymer supply. Specialty indicator houses concentrate on colorimetric freshness verification for protein packaging. Three strategic archetypes define positioning: integrated chemical-materials suppliers, focused sensor technology developers, and packaging-integrated solution providers. Competitive moves center on backward integration into catalyst loading operations and geographic expansion of validation service networks.
Within the integrated chemical tier, Mitsubishi Gas Chemical anchors materials science heritage spanning oxygen scavenging and indicator chemistry. 3M occupies a position bridging adhesive technology leadership with healthcare packaging applications. Insignia Technologies exemplifies the specialized freshness indicator archetype concentrated on protein-based food verification systems.
| Leading Market Players |
|---|
| 3M |
| Mitsubishi Gas Chemical |
| Temptime |
| Timestrip |
| OxySense |
| FreshPoint |
| Cryolog |
| Insignia Technologies |
| Paksense |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's packaging sustainability targets gate qualified supply and premium-tier pricing access by mandating waste-reducing verification systems that only validated suppliers can deliver. Pharmaceutical and food manufacturers now face tiered procurement where ISO 11607-2 documentation capabilities separate premium pricing from commodity positioning.
Pricing Analysis
The bundled-versus-unbundled service split defines transaction structures across the oxygen indicator landscape. Premium tiers command project-based validation packages incorporating 12-18 month stability studies and design dossier support, while economy tiers operate on per-unit transactional models for standardized colorimetric labels. Price differentiation hinges on certification grade — EU MDR Annex I compliance versus basic food-grade verification — and geographic delivery cost from German or Japanese manufacturing clusters. Cost compression in the methylene blue segment is intensifying because humidity-sensitive reversible indicators face reliability challenges in tropical logistics corridors. Food manufacturers exhibit the highest price sensitivity, prioritizing spoilage claim reduction over sensor precision, whereas biologics procurement teams in Massachusetts and North Carolina demonstrate minimal elasticity for palladium-catalyzed systems with sub-0.5% oxygen detection thresholds.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for pharmaceutical contract manufacturers seeking to mitigate single-source vulnerability. Supply concentrates in Germany, the United States, and Japan where adhesive polymer formulations and palladium catalyst loading anchor production capabilities. Raw material dependencies draw from acrylic and silicone pressure-sensitive adhesive specialists, redox dye chemical producers, and precious metal catalyst suppliers. Palladium price volatility constitutes the dominant structural risk, compressing margin predictability for premium indicator tiers. Distribution runs through pharmaceutical packaging integrators who increasingly bundle indicator specifications into primary packaging tenders, marginalizing standalone vendors and concentrating purchasing leverage with global supply chain governance platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO alignment costs in India run substantially below EU MDR validation timelines, creating service export opportunities for established European suppliers.
For Market Incumbents: Acquire validation documentation capabilities to defend against packaging integrator bundling trends that marginalize standalone indicator vendors. Mitsubishi Gas Chemical and 3M should deepen backward integration into palladium catalyst loading operations to buffer precious metal commodity swings. Certification investment in ISO 11607-2 design dossier support separates defensible premium positioning from eroding commodity tiers.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical applications creates entry space for mid-tier specialists offering EU MDR-aligned validation without full-service bundling. India pharmaceutical exports represent the most penetrable geography where CDSCO alignment with FDA standards generates technical support demand. A go-to-market angle targeting Hyderabad and Mumbai contract manufacturers with localized stability study capabilities bypasses incumbent validation network advantages.
For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor technology developers because sterile barrier qualification protocols create customer switching costs that sustain acquired revenue bases. The five-to-ten year viability window favors platforms integrating electronic indicator convergence with legacy colorimetric systems. Acquisition target archetypes include RFID-NFC platform specialists and regional validation service providers. The signal to watch is biologics procurement team consolidation toward packaging integrators, which accelerates standalone vendor distress and roll-up opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Loading | Mitsubishi Gas Chemical secures palladium supply chains against commodity volatility in redox systems. |
| Electronic Indicator Platform Development | Thin-film transistor arrays enable Swiss cold chain operators to automate regulatory documentation burdens. |
| Regional Validation Service Expansion | CDSCO-aligned technical support in Hyderabad captures Indian pharmaceutical export growth. |
| Packaging Integrator Partnership | Bundled specifications with Boston-area contract manufacturers concentrate purchasing leverage. |
| EU MDR Design Dossier Investment | ISO 11607-2 documentation capabilities qualify suppliers for German notified body audits. |
Research Methodology
Coverage spans Germany, the United States, Japan, Switzerland, and India, with primary inputs from each market cluster. The analysis combines primary interviews with sterile barrier validation engineers, pharmaceutical packaging procurement leads, food manufacturer quality directors, and cold chain logistics operators with secondary validation from FDA quality system regulation filings, EU MDR technical documentation, ISO 11607 standard publications, and pharmaceutical export trade data. Bottom-up sizing of adhesive label volumes and top-down cross-check against palladium catalyst consumption patterns ensure triangulated accuracy.
Rate-of-change decomposition anchors the analytical framework across the projection horizon. Segmentation dimensions include product type, application, end user, and technology platform, with additional granularity on regional regulatory cluster alignment. CAGRs derive from installed base erosion modeling for colorimetric systems and adoption curve acceleration for electronic indicators. Industry-specific forecast inputs incorporate EU MDR Annex I implementation timelines and biologics serialization mandate expansion patterns.
Caveats apply where palladium price volatility, adhesive polymer supply disruptions, or reversible indicator reliability gaps in tropical corridors could materially shift the outlook. Forecasts reflect assumptions about regulatory convergence timelines and cold chain digitization adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Holographic Scratch-Off Labels Market
Labels
Global Thermal Transfer Label Market
Labels
Variable Data Printing Labels Market
Labels
Tags Market
Labels
Heat Shrink Sleeve Market
Labels
Stand Alone Label Applicator Market
Labels
Healthcare and Laboratory Labels Market
Labels
Wrap Around Labels Market
Labels
Polyester Labels Market
Labels
Repositionable Labels Market
Labels
Self-Laminating Tags Market
Labels
Waterproof and Weatherproof Label Market
Labels
Wash Off Labels Market
Labels
Shrink Sleeve Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Freezer Label Market