
 India Print Label Market | 2026-2036
India Print Label Market Size, Share, and Industry Trends Forecast 2026-2036
India Print Label Market Insights
BIS certification for label substrates is repositioning capital allocation across the value chain. Avery Dennison leverages its global adhesive technology portfolio to sustain premium positioning in pressure-sensitive roll stock. Uflex anchors domestic supply through integrated film extrusion and conversion facilities in Gujarat and Uttar Pradesh. Mudrika Labels competes on regional logistics density across western India pharmaceutical corridors.
India print labels are pressure-sensitive or sleeve-based substrates applied to primary and secondary packaging for identification, tracking, and brand communication, typically manufactured through flexographic or digital processes on paper, polypropylene, or PET facestocks with silicone release liners. Pressure-sensitive labels occupy the dominant volume share due to compatibility with high-speed applicators in beverage bottling lines, while RFID labels represent the fastest-growing technology segment as electronics and logistics operators adopt item-level tracking. Digital printing is displacing gravure for short-run cosmetic and pharma batches where variable data and regional language customization reduce plate costs and inventory risk.
CDSCO serialization mandates for pharmaceutical exports, FSSAI label disclosure rules for packaged foods, and BIS material standards for food-contact adhesives collectively tighten compliance thresholds for domestic converters. The PLI scheme for specialty chemicals indirectly supports domestic adhesive and coating capacity expansion. Stakeholders must monitor evolving BIS testing protocols and CDSCO track-and-trace deadlines to align capital deployment with compliance-driven demand inflections.
Market Dynamics
BIS certification mandates for label substrates are compressing converter margins while simultaneously consolidating procurement toward certified suppliers in Maharashtra and Gujarat pharmaceutical corridors.
Growth Catalysts
- CDSCO serialization mandates:Pharmaceutical exporters must deploy track-and-trace labels on secondary packaging, forcing label procurement upgrades across Mumbai and Ahmedabad production zones.
- Flexible packaging expansion:Beverage and dairy brands in western India are converting from direct-print to pressure-sensitive sleeve labels for SKU proliferation and regional language versioning.
- RFID integration:Electronics manufacturers and third-party logistics operators in Bangalore and Chennai corridors are adopting item-level RFID labels for warehouse automation and returns management.
Market Restraints
- Silicone release liner cost volatility:Petrochemical feedstock fluctuations pressure converter margins on pressure-sensitive roll stock, particularly for small-batch pharmaceutical orders.
- Adhesive supply concentration:Domestic acrylic adhesive capacity clusters in Gujarat and Maharashtra, creating single-source vulnerability for converters in southern states.
- Digital press throughput ceilings:Current inkjet web widths limit digital label economics to runs below fifty thousand units, constraining mid-volume pharmaceutical serialization contracts.
Strategic Opportunities
- North-eastern state penetration:Assam and Manipur packaged food processing is expanding without established label converter density, opening greenfield service contracts.
- PLI scheme tailwinds:Specialty chemicals incentives support domestic hot-melt adhesive and UV coating capacity, reducing import dependence for food-contact grades.
- Digital-press hybrid workflows:Converters combining flexographic base printing with inkjet variable data are capturing short-batch cosmetic and nutraceutical contracts in Hyderabad and Pune.
Industry Challenges
- Pre-press technician scarcity:Flexographic plate-making and color management expertise concentrates in Mumbai and Ahmedabad, constraining converter expansion in tier-two cities.
- BIS testing timeline compression:Migration to food-contact adhesive certification requires six-to-nine month validation cycles, delaying new product launches for domestic snack brands.
- Legacy ERP integration friction:Pharmaceutical serialization mandates require label-to-line data handshake, forcing mid-size converters to rebuild order management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Print Label Market |
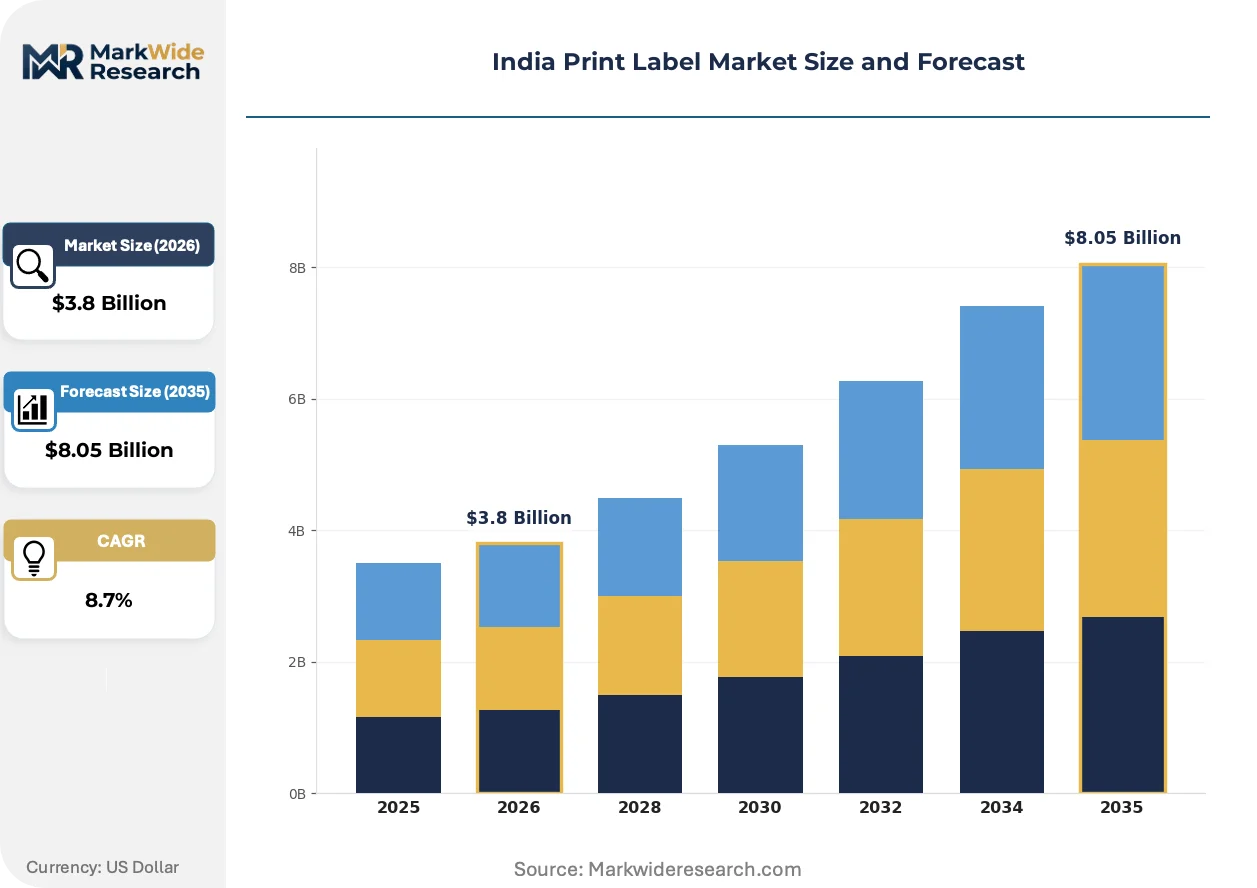
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Label, Shrink Sleeve, In-Mold Label, RFID Label Material: PVC, Polypropylene, Paper, PET Technology: Digital Printing, Flexographic Printing, Gravure Printing, Offset Printing End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics |
| Companies Covered | Avery Dennison, UPM Raflatac, CCL Industries, Skanem, JK Labels, Mudrika Labels, Uflex, LetraGraphix, Duralabel Graphics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Print Label Market Trends and Innovations
Convergence between regulatory serialization requirements and digital production economics is compressing traditional flexographic dominance in pharmaceutical and cosmetic label supply.
Single-pass inkjet web presses with integrated finishing modules are unifying printing, die-cutting, and variable data encoding into continuous workflows. Mumbai and Ahmedabad converters serving export pharmaceutical corridors are adopting these systems for CDSCO-compliant serialization batches. The technology is unifying what previously required three separate production stages, collapsing lead times from two weeks to forty-eight hours for regulatory-compliant orders.
FSSAI label disclosure amendments for packaged foods are mandating nutritional front-of-pack symbols and allergen callouts in regional languages. Domestic snack and dairy brands in Gujarat and Maharashtra are redesigning label artwork to accommodate expanded panel requirements. Secondary packaging lines in these states are retrofitting applicators to handle larger label formats without slowing bottling speeds.
Brand procurement teams are consolidating vendor relationships toward converters offering integrated design-to-dispatch services. Pharmaceutical and cosmetic manufacturers in western India are reducing approved supplier lists from twelve to four partners capable of managing regulatory artwork versioning. This concentration is most visible in Pune and Vadodara, where quality assurance teams prioritize converters with in-house BIS-certified laboratories over pure production capacity.
India Print Label Market Segmentation

Label converters in India configure production assets around substrate-technology pairings that match regional demand density. Segment selection determines capital deployment, adhesive sourcing strategy, and regulatory compliance architecture across Maharashtra, Gujarat, and southern manufacturing corridors.
Product Type:
Capital intensity varies sharply across substrate formats, with coating and lamination equipment representing the dominant fixed cost differential.
- Pressure-Sensitive Label:Silicone-coated release liners combined with acrylic or hot-melt adhesives enable high-speed dispensing on beverage bottling lines. Demand concentrates in Gujarat dairy and Mumbai pharmaceutical packaging corridors where FSSAI disclosure rules and CDSCO serialization mandates require frequent artwork revisions.
- RFID Label:Inlays embedding UHF or HF chips with printed antennas support item-level tracking for electronics manufacturers and third-party logistics operators. Bangalore and Chennai warehouse automation projects are absorbing capacity as labor costs climb and returns management complexity intensifies.
- Shrink Sleeve:PET-G or PVC films with printed graphics conform to container contours through heat application, serving craft beverage brands in Maharashtra seeking 360-degree decoration.
- In-Mold Label:Polypropylene labels fused during injection molding deliver scratch-resistant durability for personal care containers produced in Himachal Pradesh and Baddi manufacturing clusters.
Most installed capacity flows through Pressure-Sensitive Label. Expansion is steepest in RFID Label.
Material:
Raw material selection traces end-use performance requirements and BIS certification pathways rather than pure cost optimization.
- Polypropylene:Biaxially oriented films deliver moisture resistance and dimensional stability for refrigerated dairy labels across Gujarat cooperatives. BIS food-contact adhesive certification timelines currently constrain new product qualification cycles.
- Paper:Uncoated and coated wood-free stocks remain economical for short-batch pharmaceutical inserts and secondary carton labels, with procurement clustering around Mumbai and Ahmedabad converters serving export serialization contracts.
- PET:Polyester facestocks withstand chemical exposure and temperature extremes in industrial lubricant and agrochemical labeling applications.
- PVC:Rigid vinyl films support shrink sleeve applications where clarity and print gloss differentiate premium beverage positioning in urban Maharashtra markets.
Volume leadership sits with Polypropylene. PET is climbing fastest on chemical resistance specifications.
Technology:
Print technology segmentation reflects run-length economics and variable data requirements rather than image quality differentiation alone.
- Digital Printing:Single-pass inkjet and toner-based systems eliminate plate costs and enable lot-level serialization for CDSCO-compliant pharmaceutical exports. Mumbai and Pune converters serving cosmetic and nutraceutical brands are deploying hybrid flexo-digital workflows to capture short-batch regional language versioning.
- Flexographic Printing:Central impression cylinder presses with photopolymer plates dominate beverage and dairy label production where run lengths exceed fifty thousand units and color consistency across extended campaigns matters.
- Gravure Printing:Cylinder-based engraving delivers high-density solids for premium cosmetic labels, though plate costs and lead times are ceding share to digital alternatives in short-run segments.
- Offset Printing:Sheet-fed lithography persists in carton and leaflet applications adjacent to label production, particularly for pharmaceutical secondary packaging in Ahmedabad and Vadodara clusters.
Flexographic Printing retains the largest installed base. Digital Printing is expanding most quickly on pharmaceutical serialization demand.
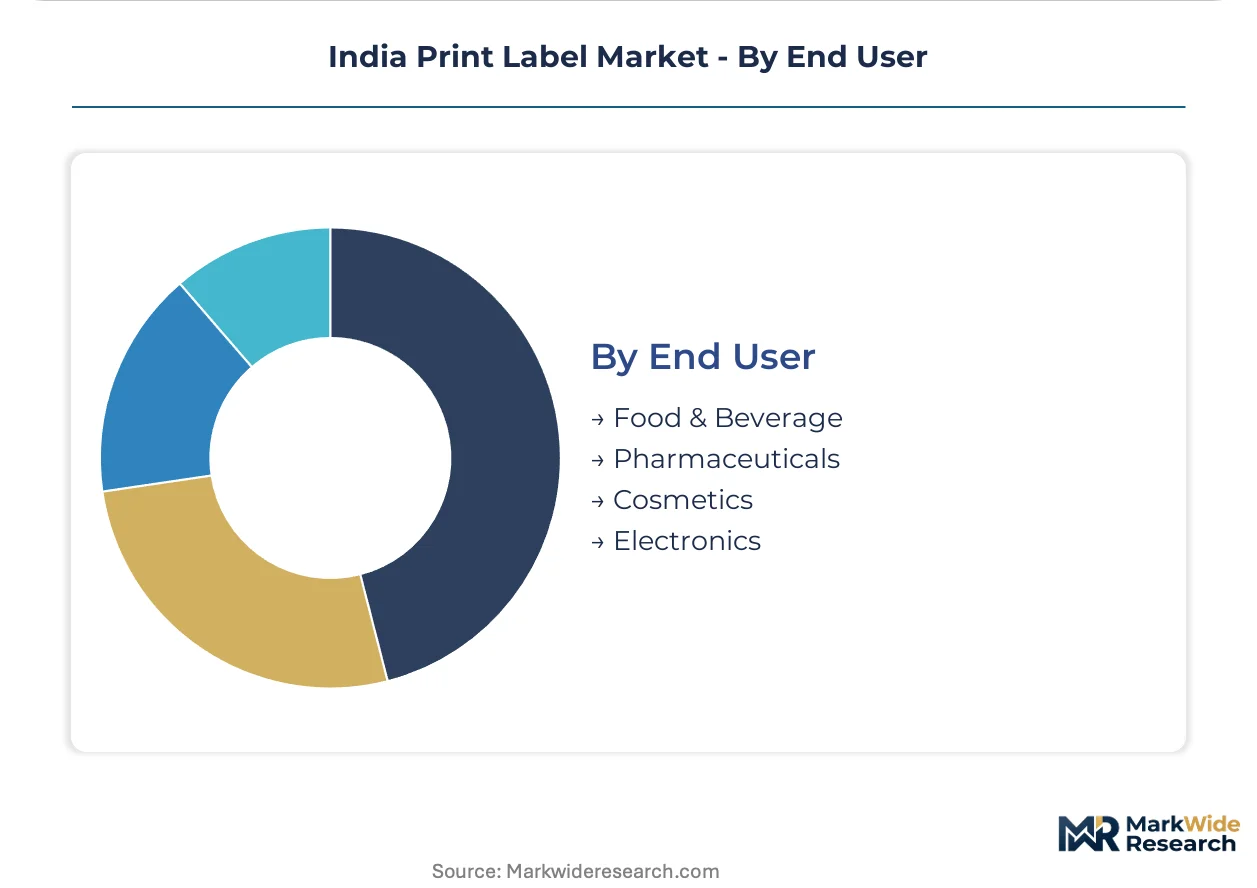
End User:
End-use segmentation reveals diverging compliance burdens and procurement consolidation patterns across western India manufacturing zones.
- Pharmaceuticals:CDSCO track-and-trace mandates for secondary packaging require serialized 2D codes and tamper-evident features. Export-oriented manufacturers in Mumbai and Ahmedabad are consolidating approved label suppliers toward converters with in-house BIS-certified laboratories.
- Food & Beverage:FSSAI front-of-pack labeling rules and allergen disclosure requirements in regional languages are expanding panel sizes and retrofitting applicator specifications across Gujarat dairy and Maharashtra snack processing lines.
- Cosmetics:SKU proliferation and seasonal promotional cycles favor digital production flexibility for regional language variants in Hyderabad and Pune personal care manufacturing corridors.
- Electronics:RFID integration for warehouse automation and anti-counterfeiting is penetrating Bangalore and Chennai assembly and logistics operations.
Food & Beverage commands the deepest label consumption. Pharmaceuticals is gaining share fastest on regulatory compliance upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pre-press technicians and color management specialists cluster disproportionately in Mumbai and Ahmedabad, anchoring converter capacity in western India while creating talent scarcity in tier-two cities.
Maharashtra
Pharmaceutical exporters in Mumbai and Pune drive pressure-sensitive label demand for CDSCO-compliant serialization batches. FSSAI disclosure rules for packaged foods are expanding panel sizes on dairy and snack labels. The Mumbai-Pune corridor hosts the densest concentration of flexographic plate-making expertise and digital hybrid workflows.
Gujarat
Dairy cooperatives and beverage bottlers in Ahmedabad and Vadodara procure polypropylene labels for refrigerated supply chains. BIS certification timelines for food-contact adhesives currently stretch six-to-nine months, delaying new product launches. The state anchors domestic acrylic adhesive capacity, creating single-source vulnerability for converters sourcing from outside the region.
Karnataka
Electronics manufacturers and third-party logistics operators in Bangalore absorb RFID label capacity for warehouse automation and returns management. CDSCO mandates indirectly influence label procurement as pharmaceutical packaging suppliers extend into southern markets. The Bangalore-Chennai corridor represents the fastest-growing RFID adoption zone in peninsular India.
Tamil Nadu
Chennai-based automotive and industrial lubricant producers specify PET facestocks for chemical-resistant labeling applications. The state's manufacturing base generates steady demand for durable labels in temperature-extreme environments. Converter presence remains thinner here than in western India, creating logistics cost premiums for just-in-time procurement.
Telangana
Cosmetic and nutraceutical brands in Hyderabad favor digital production flexibility for regional language versioning and seasonal promotional cycles. The city's personal care manufacturing corridor is consolidating approved supplier lists toward converters with integrated design-to-dispatch capabilities. Local converter density lags Maharashtra and Gujarat, opening service gaps for agile entrants.
India Print Label Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate, adhesive, and conversion layers of the value chain. The market exhibits tiered consolidation: global material science leaders occupy premium roll-stock positions, integrated domestic film producers anchor mid-market supply, and regional logistics specialists capture pharmaceutical corridor density. Three archetypes dominate: adhesive technology licensors, extrusion-integrated converters, and design-to-dispatch service providers. Competitive moves center on BIS laboratory certification acquisition and hybrid flexo-digital press deployment.
Among global material science players, Avery Dennison and UPM Raflatac represent the premium-tier adhesive and facestock archetype, leveraging technology portfolios to sustain positioning in pressure-sensitive roll stock. Uflex exemplifies the extrusion-integrated domestic model, with captive film production in Gujarat and Uttar Pradesh insulating against import volatility. Mudrika Labels occupies the regional logistics specialist position, competing on density across western India pharmaceutical corridors rather than material technology differentiation.
| Leading Market Players |
|---|
| Avery Dennison |
| UPM Raflatac |
| CCL Industries |
| Skanem |
| JK Labels |
| Mudrika Labels |
| Uflex |
| LetraGraphix |
| Duralabel Graphics |
| Others |
Pricing and Supply Chain Analysis
Flexographic plate-making specialists clustering in Mumbai and Ahmedabad command wage premiums that propagate through converter pricing tiers, stretching spreads between certified premium suppliers and uncertified regional competitors serving price-sensitive snack brands.
Pricing Analysis
Bundled design-to-dispatch services command premiums over unbundled production-only contracts. Three-tier pricing structure across BIS-certified premium, standard-compliant, and economy-grade converters reflects certification investment recovery timelines. Cost compression in economy-tier paper labels is intensifying because silicone liner petrochemical volatility squeezes small-batch pharmaceutical converters. Export pharmaceutical manufacturers show lowest price sensitivity due to CDSCO compliance non-negotiability, while domestic dairy cooperatives exhibit highest sensitivity to per-thousand-unit differentials.
Supply Chain Analysis
Freight cost differentials between western India adhesive clusters and southern converter markets disadvantage Karnataka and Tamil Nadu producers against Gujarat-based integrated suppliers. Raw material sourcing draws from domestic acrylic adhesive capacity in Gujarat, imported silicone release liners from South Korea and Japan, and biaxially oriented polypropylene film from domestic extrusion facilities. Single-source vulnerability concentrates in food-contact adhesive grades where BIS validation cycles create six-to-nine month qualification locks. Distribution runs through converter-direct relationships with FMCG procurement teams, bypassing distributor markups for volume pharmaceutical and dairy accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where CDSCO serialization mandates and FSSAI disclosure rules are concentrating procurement toward BIS-certified converters with in-house laboratory capabilities.
For Market Incumbents: To counter digital-native competitors capturing short-batch cosmetic contracts, incumbent converters should deepen captive adhesive coating capacity and secure BIS laboratory certification ahead of pending food-contact adhesive rule expansions. Hybrid flexo-digital press deployment captures mid-volume pharmaceutical serialization demand that pure-flexo economics cannot serve. For New Entrants and Emerging Players: CDSCO serialization mandates in India open a window for RFID-integrated label specialists to capture electronics logistics demand in Bangalore and Chennai corridors where incumbent converter density remains thin. Greenfield service contracts in Assam and Manipur packaged food processing offer white-space entry with lower certification backlog than western India markets. For Investors and Strategic Acquirers: Specialty chemicals conglomerates are the most active acquirer in this space, seeking downstream label conversion assets to complete adhesive-to-application value chain control. Long-term viability hinges on regulatory compliance infrastructure rather than pure production scale. The signal to watch is BIS testing protocol acceleration timelines, which would compress certification backlogs and revalue laboratory-equipped converters.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Laboratory Certification Acquisition | In-house testing capability collapses six-to-nine month validation cycles for food-contact adhesive launches. |
| Hybrid Flexo-Digital Press Deployment | Unified workflows capture CDSCO-compliant pharmaceutical serialization batches below fifty-thousand-unit digital ceilings. |
| Backward Integration into Adhesive Coating | Captive hot-melt and UV coating capacity insulates margin pressure from import-dependent supply. |
| North-Eastern State Service Expansion | Assam and Manipur packaged food processing growth lacks established converter density for just-in-time procurement. |
| RFID Inlay Integration Partnership | Electronics manufacturers in Bangalore and Chennai absorb item-level tracking labels for warehouse automation. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Karnataka, Tamil Nadu, and Telangana, with primary inputs from each. The analysis combines interviews with label converter operations directors, FMCG procurement managers, pharmaceutical packaging compliance officers, and specialty chemicals plant managers with secondary validation from CDSCO regulatory filings, FSSAI disclosure amendments, BIS certification registries, and customs trade data for silicone release liner imports. Bottom-up capacity estimates triangulate against top-down end-use demand modeling across the analysis window.
Rate-of-change decomposition separates volume growth from mix-shift effects across substrate type, print technology, and end-use industry dimensions. Modeled segmentation spans pressure-sensitive, RFID, shrink sleeve, and in-mold product categories crossed with pharmaceutical, food and beverage, cosmetics, and electronics end-user verticals. CAGRs derive from regression-adjusted historical trajectories and regulatory deadline inflection assumptions. Forecast inputs incorporate PLI scheme disbursement timelines for specialty chemicals capacity and CDSCO track-and-trace implementation phases.
Revisions become necessary when BIS testing protocol timelines compress, CDSCO serialization deadlines shift, or petrochemical feedstock volatility disrupts silicone release liner supply economics. Forecasts reflect documented assumptions about regulatory implementation fidelity and capital deployment response speeds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Syringe Labels Market
Labels
Laser Printable Wristbands Market
Labels
Die Cut Labels Market
Labels
Global Thermal Transfer Label Market
Labels
In-Mold Labeling (IML) Market
Labels
Pressure Sensitive Labels Market
Labels
Printable Tags Market
Labels
Holographic Labels Market
Labels
Waterproof and Weatherproof Label Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Multi-Part Labels Market
Labels
Domed Labels Market
Labels
Direct Thermal Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Global QR Code Labels Market
Labels
GHS Labels Market