
 Foldable Display Market | 2026-2036
Foldable Display Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Display Market Intelligence
Equipment leasing and project finance for OLED deposition tools is reshaping competitive entry in foldable display manufacturing. Samsung Display leverages captive semiconductor energy laboratory partnerships to sustain organic material supply chains. BOE Technology Group anchors massive Gen-6 flexible OLED capacity in Hefei and competes on price-performance for Chinese smartphone brands. TCL China Star Optoelectronics Technology specializes in inkjet-printed OLED architectures that differentiate its cost structure against vapor-deposition rivals.
A foldable display integrates flexible substrate films, thin-film encapsulation barriers, and bendable electrode layers to enable repeated mechanical deformation exceeding hundreds of thousands of cycles while preserving pixel uniformity. These assemblies serve consumer electronics brands seeking differentiated form factors without sacrificing screen area. Flexible AMOLED dominates current shipment value due to established supply chains and proven reliability in smartphones, while rollable OLED represents the fastest-expanding technology dimension as automotive manufacturers prototype reconfigurable dashboard surfaces. Single-fold configurations occupy the mature volume position, whereas dual-fold and multi-fold architectures concentrate margin pools at premium price tiers.
REACH restrictions on hazardous substances in electronics and the EU Green Deal's circular economy requirements shape material selection and end-of-life recovery obligations for European-bound panels. China's GB standards and MIIT directives govern local display quality certifications and energy efficiency thresholds that BOE and TCL must satisfy for domestic market access. South Korea's MFDS and METI frameworks in Japan influence biocompatibility and electromagnetic emissions testing for wearable applications. Stakeholders must monitor how evolving substrate material regulations and deposition equipment export controls alter sourcing flexibility and capital deployment timelines.
Market Dynamics
Ultra-thin glass substrate manufacturing concentration among Korean and Chinese panel suppliers is compressing margin pools for downstream device integrators while accelerating form factor experimentation across consumer electronics brands.
Growth Catalysts
- Flexible OLED Deposition Equipment:Leasing structures for Gen-6 vapor-phase deposition tools lower capital barriers for new entrants in panel fabrication.
- EU Green Deal Circular Economy Requirements:Mandates for end-of-life material recovery drive substrate recyclability innovation and closed-loop supply partnerships.
- Automotive Dashboard Prototyping:Reconfigurable surface demand from vehicle OEMs expands addressable application space beyond handheld devices.
Market Restraints
- Organic Material Supply Concentration:Captive semiconductor energy laboratory partnerships in South Korea limit independent sourcing options for rival panel makers.
- Encapsulation Barrier Yield Rates:Thin-film multi-layer deposition defects constrain production economics at current manufacturing scales.
- Mechanical Fatigue Testing Durations:Hundred-thousand-cycle bend reliability protocols extend product qualification timelines for new substrate formulations.
Strategic Opportunities
- India Smartphone Assembly Incentives:PLI scheme subsidies for local device manufacturing create pull-through demand for imported flexible panel modules.
- Inkjet-Printed OLED Convergence:Solution-processed organic semiconductor deposition merges with flexible substrate handling to disrupt vapor-deposition cost structures.
- Healthcare Wearable Biocompatibility:MFDS and METI testing frameworks for skin-contact applications open premium pricing tiers for medical-grade foldable sensors.
Industry Challenges
- Multi-Fold Hinge Mechanism Integration:Dual-fold and tri-fold architectures demand precision torque engineering that exceeds current mechanical design talent availability.
- Cross-Border Deposition Equipment Export Controls:Licensing delays for advanced vacuum chamber systems disrupt capacity expansion timelines for non-captive fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Display Market |
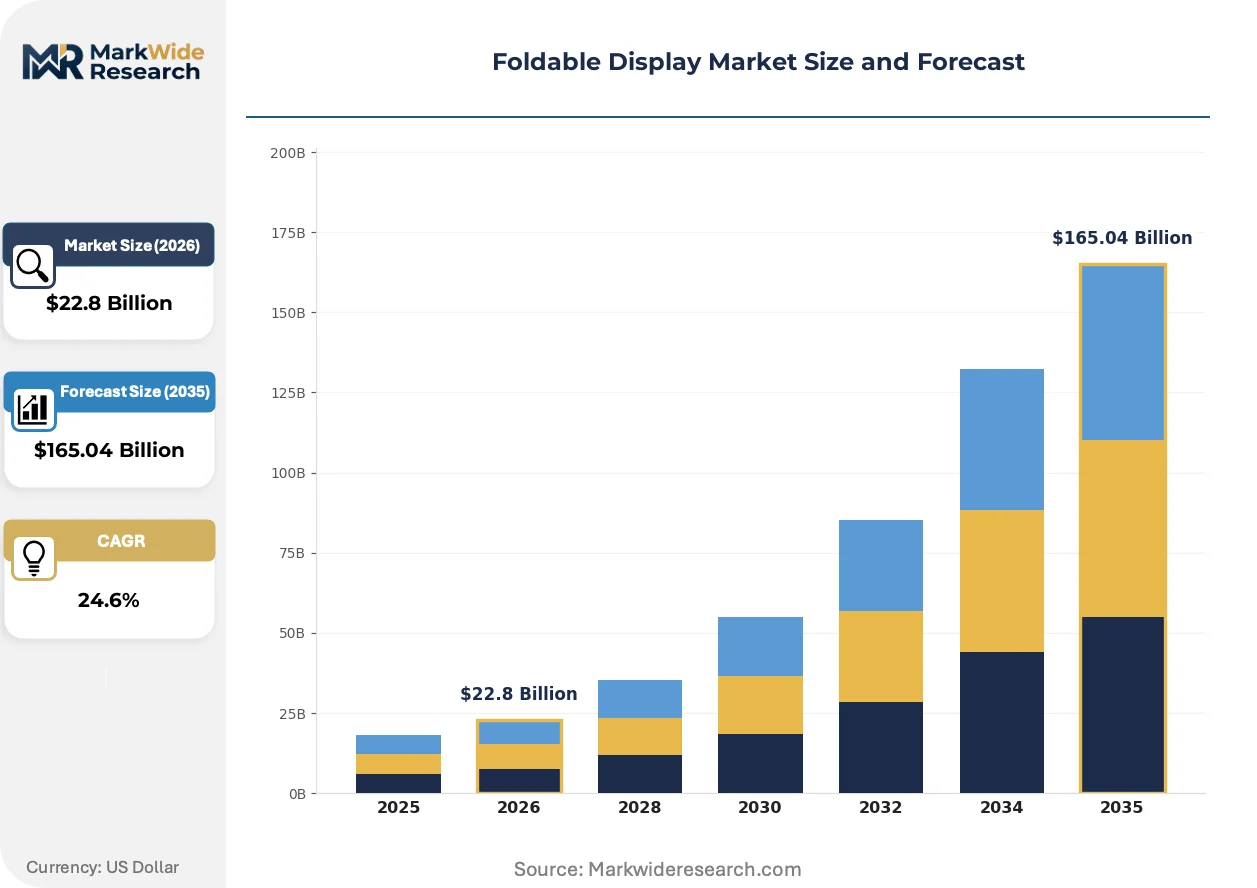
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $165.04 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible OLED, Flexible LCD, Flexible AMOLED, Flexible E-Ink, Rollable OLED Technology: Single Fold, Dual Fold, Multi Fold, Slide & Fold, Sweep Fold Application: Smartphones, Tablets, Wearables, Automotive Displays, Gaming Consoles End User: Consumer Electronics Brands, Telecommunication Companies, Automotive Manufacturers, Gaming Device Producers |
| Companies Covered | Samsung Display, BOE Technology Group, LG Display, Royole Corporation, Visionox Technology, TCL China Star Optoelectronics Technology, AUO Corporation, Innolux Corporation, Semiconductor Energy Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Display Market Strategic Shifts & Innovations
Active matrix organic light-emitting diode architectures are undergoing substrate-level transformation as manufacturers pursue mechanical durability without sacrificing pixel density or power efficiency.
Quantum dot color conversion layers integrated with flexible blue OLED emitters are digitizing display color gamut performance while reducing power consumption. Automotive interior designers at premium German and Japanese OEMs are specifying these architectures for curved instrument clusters. The technology is digitizing how vehicle human-machine interfaces render navigation and entertainment content across non-planar surfaces.
REACH restrictions on hazardous substances in electronics are tightening permissible thresholds for heavy metals in thin-film transistor backplanes. Panel fabricators serving European-bound shipments must reformulate indium-gallium-zinc-oxide sputtering targets. Display module assemblers in Vietnam and Mexico are establishing segregated production lines to isolate EU-compliant material flows from other regional variants.
Chinese smartphone brands are consolidating panel procurement around domestic flexible OLED suppliers rather than splitting volumes across Korean and Chinese sources. This concentration is compressing supplier negotiation leverage for second-tier device makers. The shift is most pronounced in mid-tier handset segments where bill-of-materials cost sensitivity dominates sourcing decisions.
Foldable Display Market Segmentation
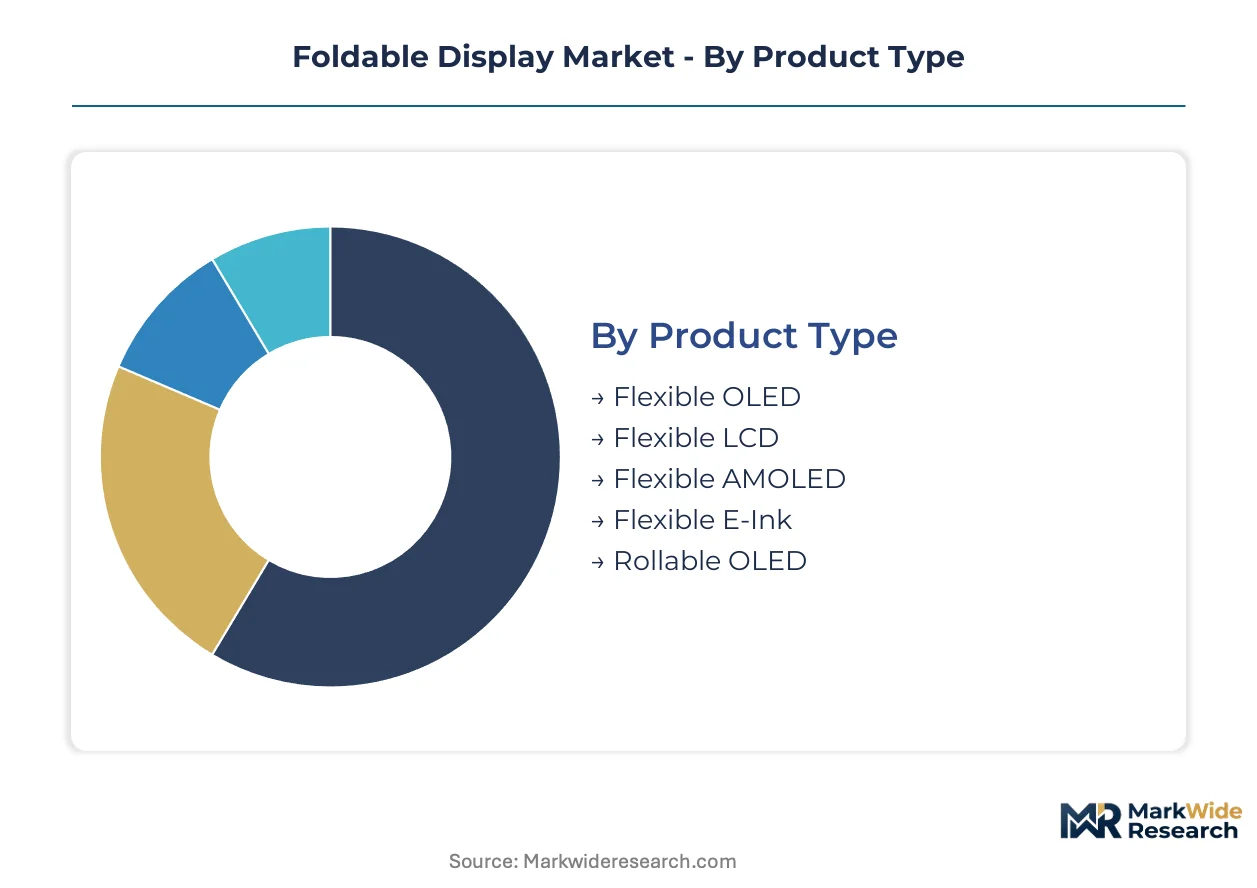
Segmentation in foldable displays reveals how technical specifications, mechanical architectures, and end-use requirements fragment procurement patterns across device manufacturers. Each dimension carries distinct margin structures and qualification barriers that reshape supplier competitive positioning.
Product Type:
Mature vapor-deposition technologies anchor current volume, while emerging solution-processed formats are compressing cost curves for price-sensitive applications.
- Flexible OLED:Thin-film organic emissive layers deposited on polyimide substrates enable sub-millimeter bend radii for smartphone form factors. Korean and Chinese panel fabs concentrate procurement for premium handset launches where mechanical reliability exceeds hundred-thousand-cycle thresholds.
- Flexible AMOLED:Active matrix addressing with thin-film transistor backplanes delivers pixel-level brightness control for high-resolution wearable displays. Samsung Display and BOE Technology Group supply Korean and Chinese smartwatch brands seeking always-on functionality with minimal power draw.
- Flexible LCD:Liquid crystal cells laminated to flexible glass substrates serve cost-optimized tablet applications where color gamut requirements trail OLED performance.
- Flexible E-Ink:Electrophoretic particle displays on plastic substrates address e-reader and low-power signage segments with sunlight readability.
- Rollable OLED:Continuous deposition on polymer films enables cylindrical storage for automotive and television prototypes. German and Japanese OEMs specify these architectures for reconfigurable dashboard surfaces where screen area must expand without permanent footprint expansion.
Flexible AMOLED retains volume leadership; Rollable OLED holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium multi-fold architectures from standard single-fold volumes, with mid-tier dual-fold configurations capturing mainstream adoption.
- Single Fold:One hinge axis with 180-degree closure enables book-style smartphone formats. Chinese consumer electronics brands dominate procurement for mass-market handsets where bill-of-materials sensitivity constrains mechanical complexity.
- Dual Fold:Two independent hinge axes create tri-panel configurations with expanded screen real estate. Samsung Electronics and Huawei source these modules for flagship devices targeting productivity-oriented users.
- Multi Fold:Three or more hinge axes enable tablet-to-phone transformation with Z-fold or accordion architectures. Prototype volumes concentrate among Korean and Chinese device makers testing extreme form factor differentiation.
- Slide & Fold:Combination sliding mechanism with fold axis allows variable aspect ratios without visible crease lines.
- Sweep Fold:Curved hinge geometry distributes bending stress across larger radius to reduce fatigue concentration.
Single Fold dominates shipment value; Multi Fold is climbing the fastest toward commercialization.
Application:
Volume concentration in handheld devices contrasts with emerging automotive and gaming segments where specification requirements diverge sharply from mobile norms.
- Smartphones:Clamshell and book-style foldables with ultra-thin glass cover layers account for the majority of flexible panel procurement. Korean and Chinese brands specify these modules for annual flagship refresh cycles.
- Tablets:Larger diagonal formats with strengthened hinge mechanisms target creative professionals and enterprise field workers. Apple and Microsoft evaluate these panels for next-generation portable computing devices.
- Wearables:Small-form circular and rectangular displays with biocompatibility certifications serve smartwatch and health-monitoring bands. Japanese and Korean medical device regulations govern skin-contact material selection.
- Automotive Displays:Curved and reconfigurable dashboard surfaces require extended temperature operating ranges and vibration resistance. German premium OEMs prototype these for electric vehicle interiors.
- Gaming Consoles:Handheld units with integrated controllers demand low-latency response times and high refresh rates for competitive gameplay.
Smartphones retain volume leadership; Automotive Displays hold the steepest expansion curve.
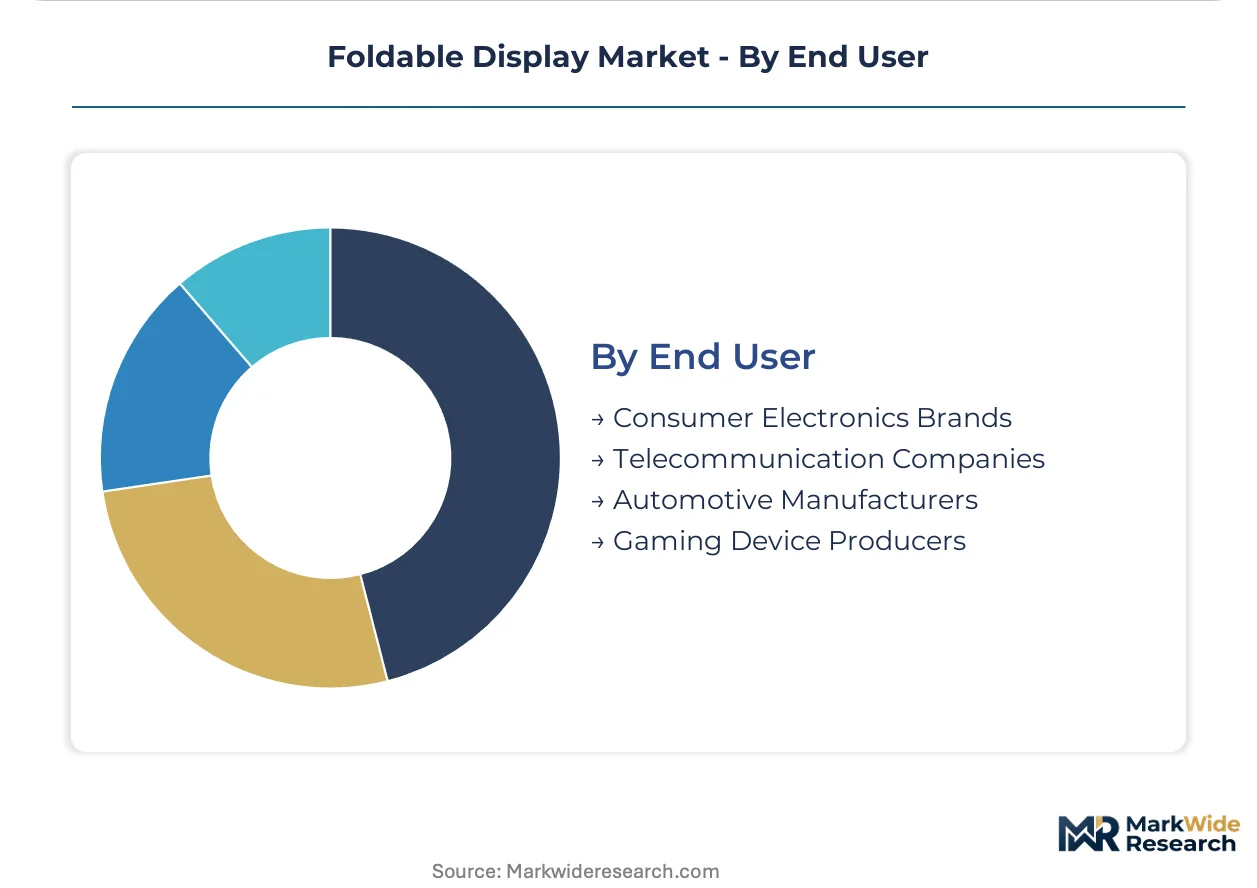
End User:
Customer type segmentation reveals how procurement authority concentrates among integrated device manufacturers versus specialized component suppliers serving fragmented downstream markets.
- Consumer Electronics Brands:Vertically integrated smartphone and tablet manufacturers source flexible panels through multi-year supply agreements with captive fabs. Samsung Electronics and Xiaomi negotiate directly with Samsung Display and BOE for exclusive capacity allocations.
- Automotive Manufacturers:Tier-1 display integrators serve German and Japanese OEMs with customized modules for vehicle-specific dashboard geometries. Continental and Bosch intermediate between panel suppliers and final assembly lines.
- Telecommunication Companies:Carrier-branded device programs in India and Southeast Asia specify mid-tier flexible panels for subsidized handset distribution.
- Gaming Device Producers:Niche portable console manufacturers source specialized high-refresh panels with minimal input lag for competitive gaming segments.
Consumer Electronics Brands retain volume leadership; Automotive Manufacturers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panel fabrication capacity concentrates in East Asian export hubs while device assembly gravitates toward import-dependent manufacturing zones seeking localization incentives.
China
Domestic smartphone brands consolidate procurement around Shenzhen and Chengdu panel clusters. MIIT directives on display quality certifications and GB standards for energy efficiency govern local market access. Hefei anchors massive Gen-6 flexible OLED capacity where BOE Technology Group competes on price-performance metrics.
South Korea
Samsung Display sustains captive organic material supply chains through semiconductor energy laboratory partnerships. MFDS frameworks influence biocompatibility testing protocols for wearable applications. Gyeonggi-do manufacturing complexes concentrate ultra-thin glass substrate capabilities serving global handset brands.
United States
Apple and Microsoft evaluate larger-format foldable panels for portable computing device refreshes. FCC electromagnetic emissions standards constrain module integration timelines. California-based design studios prototype automotive dashboard specifications for German premium OEMs.
Japan
Automotive interior designers at premium OEMs specify quantum dot color conversion layers for curved instrument clusters. METI frameworks govern electromagnetic testing thresholds for vehicle-integrated displays. Nagoya-area Tier-1 suppliers intermediate between Korean panel makers and final vehicle assembly.
India
PLI scheme subsidies for local smartphone assembly create pull-through demand for imported flexible panel modules. TRAI regulations on device certification shape import documentation requirements. Tamil Nadu and Karnataka manufacturing corridors concentrate handset final assembly operations.
Foldable Display Market Key Industry Players
On the supply side, the industry is consolidating around Korean and Chinese panel fabricators with captive deposition equipment access. Samsung Display and BOE Technology Group anchor opposing poles of this structure. Three archetypes dominate: vertically integrated display divisions of conglomerates, independent panel specialists with government-backed capacity expansion, and materials-science laboratories with organic semiconductor IP. Competitive moves concentrate on multi-year supply agreements with consumer electronics brands and strategic leasing structures for Gen-6 vapor-phase deposition tools.
Among Korean fabricators, Samsung Display and LG Display occupy positions within the conglomerate-integrated tier, leveraging captive semiconductor energy laboratory partnerships for organic material continuity. BOE Technology Group represents the state-supported capacity expansion archetype with massive Hefei installations. TCL China Star Optoelectronics Technology exemplifies the solution-processed differentiation vector, specializing in inkjet-printed OLED architectures that challenge vapor-deposition economics.
| Leading Market Players |
|---|
| Samsung Display |
| BOE Technology Group |
| LG Display |
| Royole Corporation |
| Visionox Technology |
| TCL China Star Optoelectronics Technology |
| AUO Corporation |
| Innolux Corporation |
| Semiconductor Energy Laboratory |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Korean ultra-thin glass substrate suppliers determines both the widening spread between premium multi-fold and economy single-fold pricing tiers and the geographic clustering of panel fabrication capacity in Gyeonggi-do and Hefei manufacturing zones.
Pricing Analysis
Consumer electronics brands anchor a contract-based long-term offtake pricing structure where multi-year supply agreements with Samsung Display and BOE Technology Group secure volume allocations. Price differentiation separates medical-grade wearable panels with MFDS biocompatibility certification from standard smartphone modules and automotive dashboard prototypes with extended temperature ratings. Cost compression in mid-tier single-fold configurations is intensifying because Chinese smartphone brands consolidate procurement around domestic suppliers. Mid-tier handset manufacturers exhibit the highest price sensitivity, while German premium automotive OEMs show the least due to specification-driven procurement.
Supply Chain Analysis
BOE Technology Group and TCL China Star Optoelectronics Technology hold captive Gen-6 flexible OLED deposition capacity in China, while Samsung Display and LG Display anchor Korean fabrication clusters. The supply chain draws from indium-gallium-zinc-oxide sputtering targets, polyimide substrate films, and organic emissive materials concentrated in South Korea and China. Single-source vulnerability on vapor-phase deposition equipment from Japanese and Korean toolmakers disrupts capacity expansion timelines for non-captive fabricators. Distribution runs through vertically integrated display divisions of conglomerates directly to device OEMs, bypassing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Chinese smartphone brands as procurement consolidation around BOE and domestic suppliers fragments negotiation leverage for second-tier device makers seeking flexible panel allocations.
For Market Incumbents: Entrench organic material supply continuity through captive semiconductor energy laboratory partnerships that rival Samsung Display's captive sourcing model. Add Gen-6 flexible OLED capacity in Hefei or Chengdu clusters to defend against price-performance competition from BOE. Monitor inkjet-printed OLED solution processing as a substitute technology threatening vapor-deposition economics. For New Entrants and Emerging Players: India's PLI scheme subsidies for local smartphone assembly represent the most penetrable geographic entry point for imported flexible panel modules targeting carrier-branded device programs. Target automotive dashboard prototyping for German and Japanese OEMs as a specification-differentiated segment with premium pricing tolerance. Pursue healthcare wearable biocompatibility certification under MFDS and METI frameworks as a go-to-market angle commanding medical-grade margins. For Investors and Strategic Acquirers: REACH restrictions and EU Green Deal circular economy requirements reshape the acquisition landscape toward panel fabricators with closed-loop substrate recovery capabilities and segregated EU-compliant production lines. Frame long-term viability around solution-processed OLED architectures that disrupt incumbent vapor-deposition cost structures across the next decade. Target materials-science laboratories with organic semiconductor IP as acquisition archetypes. Watch inkjet-printed OLED yield rate improvements at TCL China Star as the inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Gen-6 Flexible OLED Capacity Expansion | BOE's Hefei installations capture Chinese smartphone brand procurement consolidation. |
| Ultra-Thin Glass Substrate Partnership | Samsung Display's Gyeonggi-do capabilities secure mechanical reliability for hundred-thousand-cycle bend thresholds. |
| Inkjet-Printed OLED R&D Investment | TCL China Star's solution processing challenges vapor-deposition equipment leasing economics. |
| Automotive Dashboard Prototyping Agreement | German OEM specifications for rollable OLED expand addressable market beyond handheld devices. |
| Healthcare Wearable Biocompatibility Certification | MFDS and METI compliance opens premium pricing tiers for skin-contact medical sensors. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with panel fabrication executives, OLED deposition equipment specialists, smartphone procurement directors, automotive Tier-1 display integrators, and regulatory affairs leads; and secondary validation through MIIT directive filings, GB standards documentation, REACH substance restriction updates, SEC 10-K disclosures from listed display manufacturers, and customs trade data on flexible panel module flows. Bottom-up triangulation across supplier capacity announcements and top-down demand modeling from device OEM production schedules anchored volume and value estimates.
Forecast inputs considered flexible AMOLED and rollable OLED technology trajectories, single-fold versus multi-fold mechanical architecture adoption curves, smartphone versus automotive versus wearable application penetration patterns, and consumer electronics brand versus automotive manufacturer end-user procurement behaviors across the projection horizon. CAGRs were derived from segmented growth rate blending weighted by current shipment value concentration. Industry-specific inputs included Gen-6 vapor-phase deposition tool installation timelines and inkjet-printed OLED yield improvement curves.
Practitioners should monitor organic material supply concentration in Korean semiconductor energy laboratory partnerships, encapsulation barrier yield rate breakthroughs, and cross-border deposition equipment export control licensing delays for early signals of forecast revision. Quarterly review of MIIT display quality certification updates, EU Green Deal circular economy implementation timelines, and PLI scheme subsidy disbursement rates in India is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Center Stack Display Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Projector Screen Market
Display Technologies
E-Paper Display Market
Display Technologies
Touch Screen Film Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Mono LCD Displays Market
Display Technologies
3D Display Market
Display Technologies
3D Display Module Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Global Magic Wall Interactive Surface Market