
 Marine Selective Catalytic Reduction Systems Market | 2026-2036
Marine Selective Catalytic Reduction Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Selective Catalytic Reduction Systems Market Analysis
Tier III NOx compliance standards are redrawing procurement priorities across marine engine rooms. Wärtsilä Corporation leverages its integrated engine-SCR packages to dominate newbuild contracts in European yards. MAN Energy Solutions anchors its position through backward integration into catalyst substrate manufacturing. Yara Marine Technologies specializes in compact urea dosing systems tailored for retrofit installations on existing vessels.
Marine Selective Catalytic Reduction Systems inject aqueous urea into diesel exhaust streams, where thermal decomposition produces ammonia that reacts with nitrogen oxides over vanadium or zeolite catalyst substrates at temperatures between 300°C and 450°C, converting harmful emissions into nitrogen and water vapor to satisfy International Maritime Organization emission limits. Urea-Based SCR systems capture the largest installed base due to safer onboard handling compared with anhydrous ammonia alternatives, while Combined Systems integrating diesel oxidation catalysts are expanding fastest as shipowners seek single-unit compliance solutions. Retrofit installations command premium margins as yard downtime constraints and space limitations force engineering customization.
The International Maritime Organization Tier III framework, enforced by flag state administrations including Lloyd's Register and DNV classification societies, mandates NOx reduction in Emission Control Areas covering the North Sea, Baltic Sea, and North American coastlines. The European Union F-Gas Regulation and REACH chemical restrictions further constrain catalyst material sourcing and urea supply chain certification. Stakeholders must monitor pending IMO reviews of black carbon regulations and emerging ammonia-fuel engine compatibility requirements that could obsolete current SCR configurations.
Market Dynamics
IMO Tier III enforcement is compressing installation timelines and forcing shipyards to pre-integrate SCR units during hull construction rather than treating emissions hardware as an afterthought.
Growth Catalysts
- ECA Zone Expansion:The North American Emission Control Area and Baltic Sea designation force vessel operators to install compliant systems before entering regulated waters.
- Vanadium-Titanium Formulations:New catalyst substrates operate effectively at 280°C, extending SCR applicability to low-load marine engine operations previously outside the temperature window.
- South Korean Shipyard Cluster:Hyundai Heavy Industries and Samsung Heavy Industries anchor concentrated newbuild demand, creating localized procurement scale.
Market Restraints
- Urea Supply Concentration:Yara International and a handful of producers control maritime-grade aqueous urea (AUS 40) supply, exposing buyers to input cost volatility.
- Zeolite Catalyst Sourcing:Copper-zeolite substrate production concentrates in German and Japanese specialty chemical facilities, creating import dependency for non-European yards.
- Ammonia Fuel Substitution:Ammonia-fuel engine development threatens to obsolete urea-based SCR systems if ammonia combustion achieves commercial scale before 2040.
Strategic Opportunities
- Retrofit Installation Services:Existing vessel fleets in Greece and Singapore require compact urea dosing systems that fit constrained engine room footprints.
- EU F-Gas Regulatory Tailwind:The European Union F-Gas Regulation restricts high-global-warming-potential refrigerants, indirectly favoring marine SCR over alternative NOx reduction technologies that rely on controlled substances.
- Diesel Oxidation Catalyst Convergence:Combined DOC-SCR units reduce footprint and installation complexity, appealing to cruise operators seeking single-vendor compliance solutions.
Industry Challenges
- Marine Exhaust Systems Integration:Retrofit projects require custom piping and thermal management to connect SCR units to legacy two-stroke engine exhaust trains.
- Classification Society Certification Lag:Lloyd's Register and DNV approval timelines for novel catalyst formulations extend 18-24 months, delaying product commercialization.
- Urea Quality Assurance:Shipboard storage conditions degrade aqueous urea; ISO 18611 compliance testing adds operational overhead for fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Selective Catalytic Reduction Systems Market |
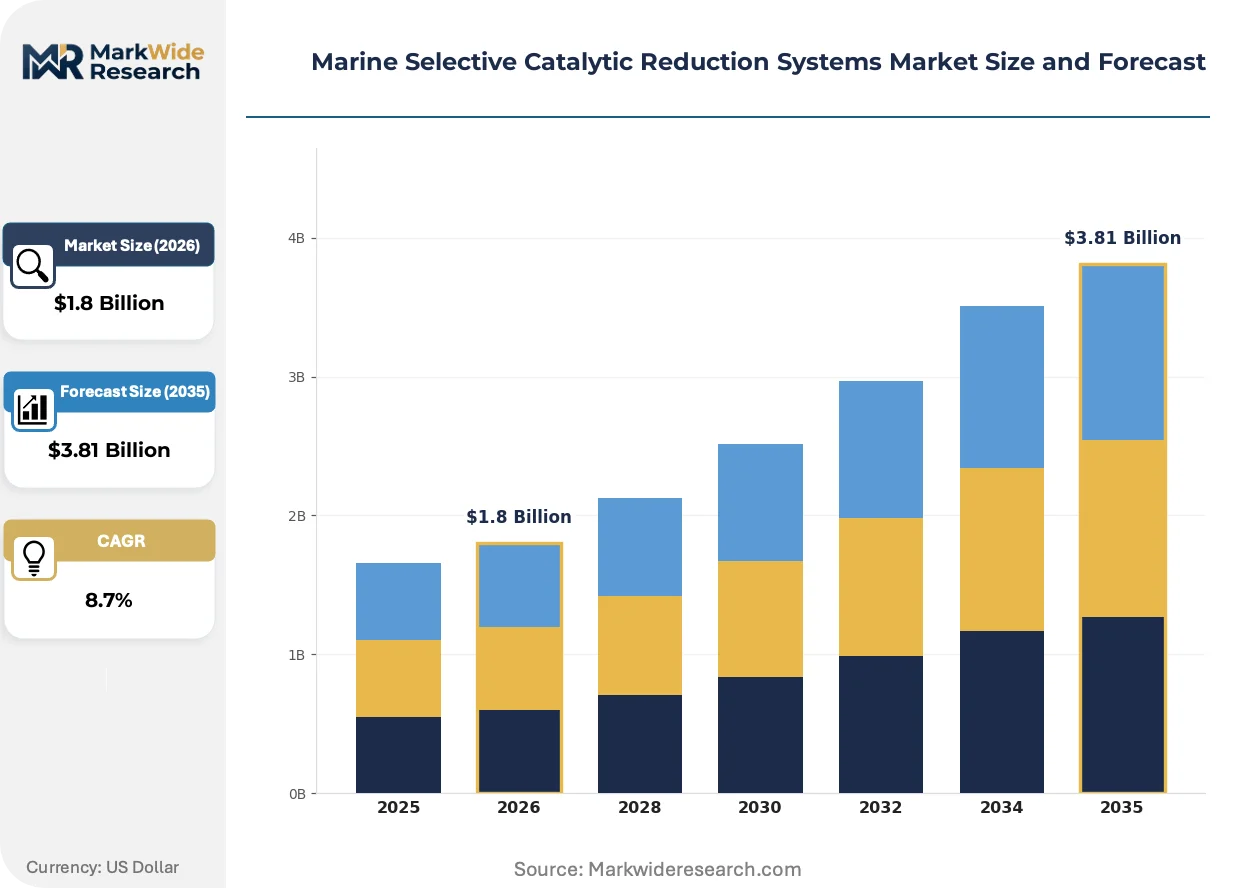
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea-Based SCR, Ammonia SCR, Diesel Oxidation Catalyst, Combined Systems Installation Type: Onshore, Offshore, Integrated, Retrofit End User: Commercial Shipping, Fishing Vessels, Passenger Ferries, Naval Vessels Technology: Active SCR, Passive SCR, Hybrid Systems, Advanced Monitoring |
| Companies Covered | Wärtsilä Corporation, MAN Energy Solutions, Yara Marine Technologies, Hitachi Zosen Corporation, Mitsubishi Heavy Industries, Johnson Matthey, BASF, Nett Technologies, Tenneco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Selective Catalytic Reduction Systems Market Emerging Trajectories
Marine SCR technology is pivoting from standalone hardware sales toward integrated compliance packages that bundle catalyst monitoring, urea logistics, and regulatory documentation.
Zeolite-based catalyst formulations are decomposing the historical dominance of vanadium-titanium substrates in marine applications. Cruise operators are adopting copper-zeolite systems for their broader temperature operating range. This shift is decomposing the traditional supplier-customer relationship as engine manufacturers bring catalyst production in-house.
REACH chemical restrictions and the EU F-Gas Regulation are tightening material sourcing requirements for catalyst substrates. Manufacturers must now document supply chain provenance for rare earth elements and ceramic substrates. European shipyards face the steepest compliance burden, with German and Dutch facilities restructuring procurement to meet ECHA documentation standards.
Shipowners are unbundling after-sales service contracts from initial equipment purchases. Independent service providers now handle urea logistics, catalyst replacement, and emissions monitoring for mid-size tanker fleets. This pattern is most pronounced in Singapore, where port proximity enables just-in-time urea delivery and third-party technical staffing.
Marine Selective Catalytic Reduction Systems Market Segmentation
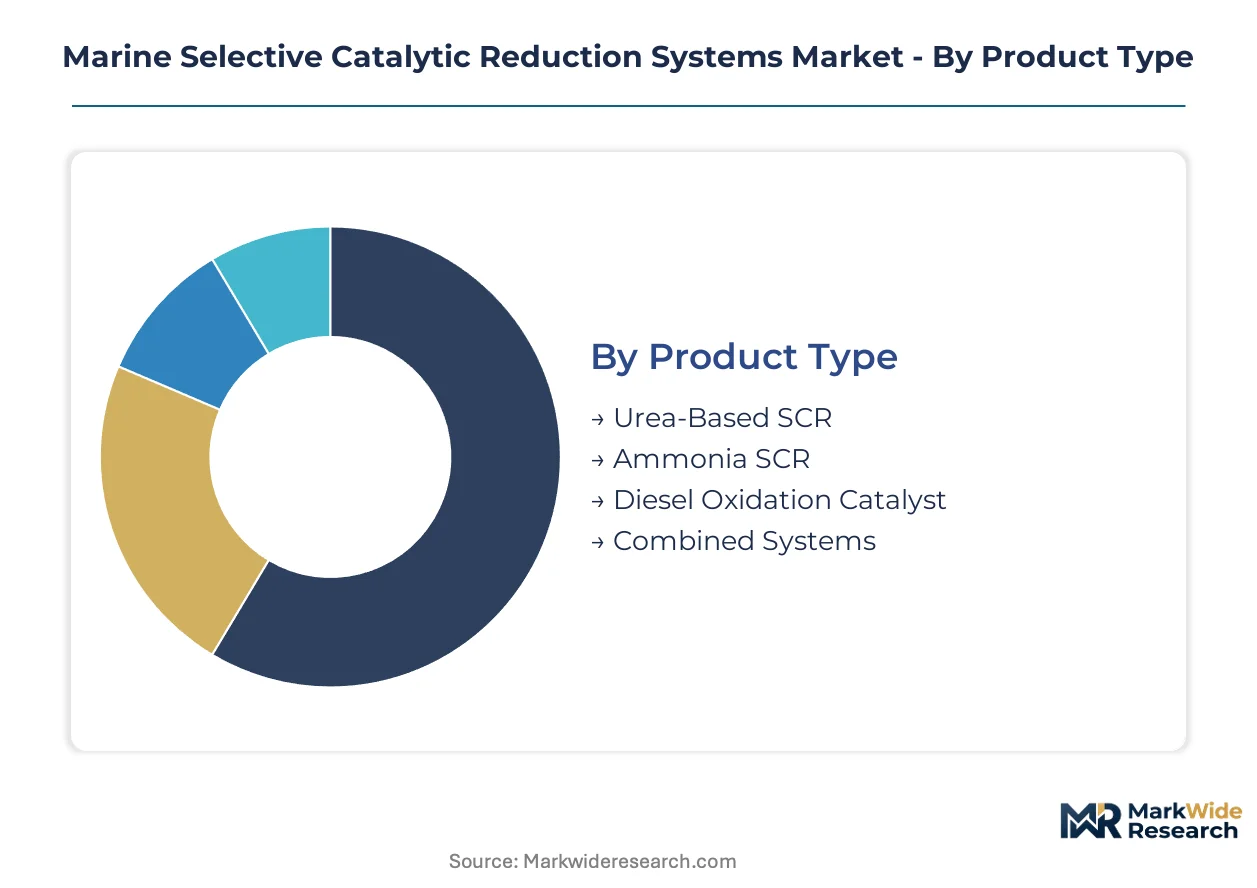
IMO Tier III compliance deadlines force distinct procurement patterns across vessel types and installation scenarios. Each segment carries unique certification requirements and supply chain constraints that shape vendor selection and pricing.
Product Type:
REACH chemical restrictions and EU F-Gas Regulation enforcement differentiate material eligibility across formulations, with vanadium and zeolite substrates facing distinct documentation burdens.
- Urea-Based SCR:Aqueous urea injection systems decompose thermally to release ammonia at 300-450°C exhaust temperatures. Commercial shipping fleets in South Korea specify these units for safer onboard handling versus anhydrous alternatives, though Yara International's supply concentration creates input cost exposure.
- Combined Systems:Integrated diesel oxidation catalyst-SCR units compress footprint and installation complexity into single-vendor packages. Cruise operators favor these for newbuild contracts where yard space constraints and Lloyd's Register certification timelines favor consolidated procurement.
- Ammonia SCR:Direct anhydrous ammonia injection achieves higher conversion efficiency at lower catalyst volumes. Limited adoption reflects stringent IMDG Code storage requirements and crew safety training mandates.
- Diesel Oxidation Catalyst:Standalone DOC units address hydrocarbon and carbon monoxide emissions without NOx reduction. Primarily specified for Tier II legacy vessels in non-ECA waters where full SCR investment is uneconomical.
Urea-Based SCR handles the majority of throughput; Combined Systems is the fastest mover on share.
Installation Type:
Cost tier stratification separates pre-integrated newbuild solutions from premium-priced retrofit engineering.
- Retrofit:Custom piping and thermal management adaptations for legacy two-stroke engine exhaust trains command 40-60% installation premiums. Greek and Singaporean tanker fleets drive demand where yard downtime constraints force rapid turnaround engineering.
- Integrated:Hull-construction-phase SCR integration at Hyundai Heavy Industries and Samsung Heavy Industries achieves lowest total installed cost. South Korean shipyard clustering enables just-in-time catalyst delivery and reduced classification society recertification.
- Onshore:Land-based marine engine test facilities and port power installations utilize stationary SCR configurations. Port authorities in Rotterdam and Los Angeles specify these for shore power alternative compliance.
- Offshore:Platform supply vessels and drilling rig auxiliary power units require explosion-proof dosing systems. DNV certification for Zone 2 hazardous area operation extends approval timelines.
Integrated captures the largest installation volume; Retrofit climbs the fastest on margin contribution.
End User:
Application-specific duty cycles determine catalyst degradation rates and urea consumption profiles.
- Commercial Shipping:Container and bulk carrier fleets face the most stringent ECA zone transit requirements. MAN Energy Solutions and Wärtsilä Corporation anchor engine-SCR package contracts for these operators.
- Passenger Ferries:High-frequency port calls and variable load profiles favor copper-zeolite catalysts with broader temperature windows. EU Green Deal funding accelerates fleet conversion in Baltic Sea routes.
- Fishing Vessels:Smaller engine displacements and intermittent operation patterns challenge SCR temperature maintenance. Compact urea dosing systems from Yara Marine Technologies address constrained engine room footprints.
- Naval Vessels:Military specifications prioritize shock resistance and electromagnetic compatibility over conversion efficiency. National security procurement restricts vendor pools to domestic or allied-country suppliers.
Commercial Shipping accounts for the dominant share; Passenger Ferries gains share fastest on regulatory subsidy alignment.
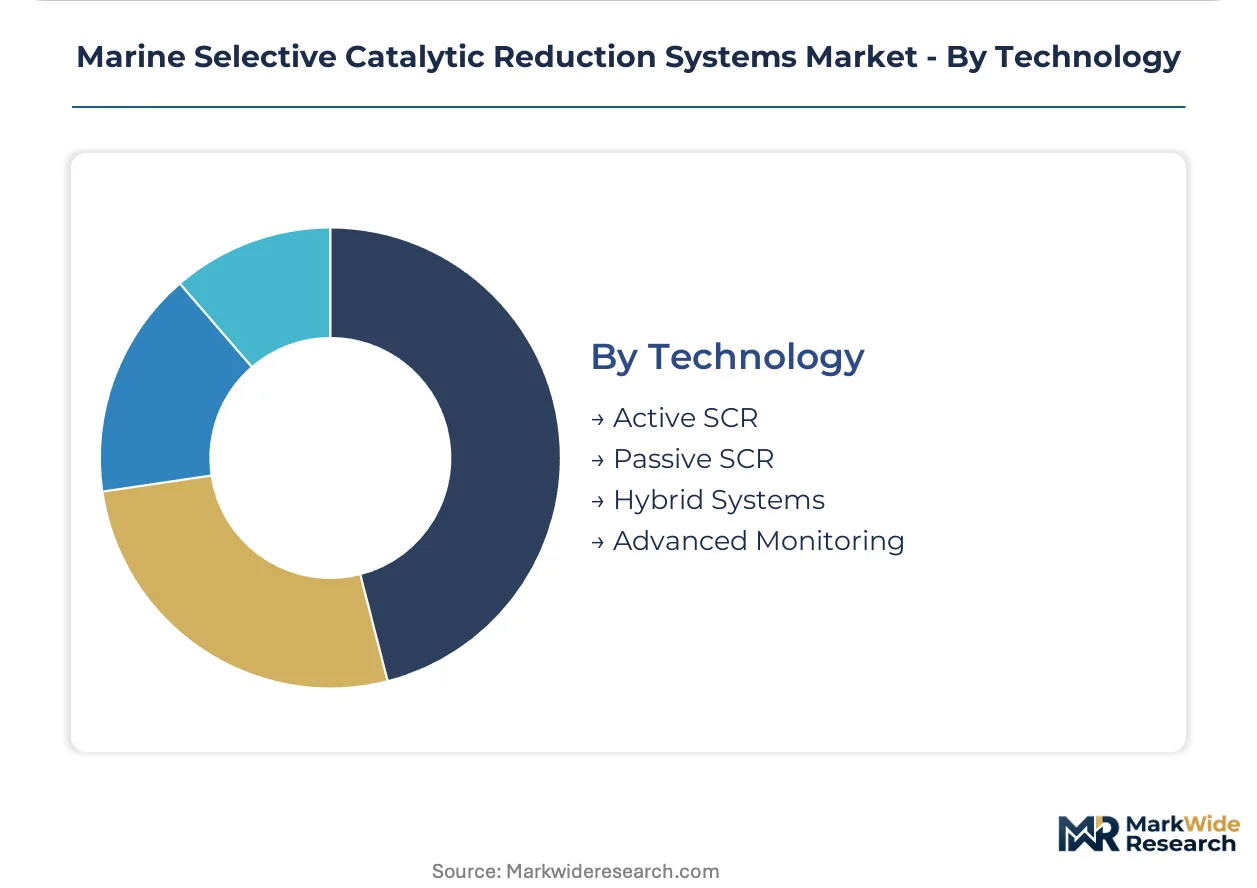
Technology:
Maturity curves separate proven active injection systems from emerging monitoring capabilities.
- Active SCR:Computer-controlled urea dosing with continuous NOx sensor feedback maintains optimal ammonia slip ratios. Standard specification for IMO Tier III certification in North American ECA waters.
- Advanced Monitoring:Predictive catalyst degradation algorithms and cloud-connected emissions documentation reduce unplanned maintenance. Singapore-based independent service providers bundle these capabilities with urea logistics.
- Passive SCR:Fixed-geometry catalyst beds without active dosing control suit steady-state operation. Limited to auxiliary engines and gensets with predictable load profiles.
- Hybrid Systems:Combined active-passive configurations switch modes based on engine load. Complexity increases failure points; adoption concentrates in research vessel applications.
Active SCR dominates current installations; Advanced Monitoring shows steepest expansion trajectory on unbundled service contract growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine SCR manufacturing clusters in South Korea, Germany, and Japan control catalyst substrate supply and engine-SCR integration capabilities. Yard capacity and regulatory enforcement intensity determine regional procurement patterns.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor concentrated newbuild demand for urea-based SCR units. The Korean Register of Shipping enforces IMO Tier III certification timelines that compress installation schedules. Ulsan and Geoje shipyard clusters achieve just-in-time catalyst delivery through localized supplier networks.
Germany
MAN Energy Solutions backward integration into catalyst manufacturing secures substrate supply for two-stroke engine packages. REACH chemical restrictions and ECHA documentation standards constrain rare earth element sourcing. Hamburg and Bremen port authorities specify combined DOC-SCR units for shore power alternative compliance.
Japan
Copper-zeolite substrate production concentrates in specialty chemical facilities serving domestic shipyards. METI industrial policy supports marine emissions technology development through targeted R&D funding. Nagoya and Kobe industrial corridors host catalyst formulation and engine testing infrastructure.
United States
EPA enforcement of North American Emission Control Area rules forces retrofit installations on vessels calling at Los Angeles and Long Beach. Lloyd's Register and DNV maintain regional certification offices to expedite novel catalyst approvals. Pacific Northwest and Gulf Coast repair yards specialize in compact urea dosing system integration.
China
State-owned shipyard consolidation under CSSC and CSIC creates procurement scale for domestic SCR suppliers. MEE enforcement of domestic emission control areas expands addressable market beyond international-flagged vessels. Shanghai and Dalian maritime clusters develop indigenous catalyst formulations to reduce import dependency.
Marine Selective Catalytic Reduction Systems Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Engine manufacturers with captive catalyst production dominate newbuild contracts through integrated package pricing. Independent emissions specialists capture retrofit margins where engineering customization commands premiums. Strategic moves concentrate on backward integration into substrate manufacturing and geographic expansion through port-proximate service networks.
Among European integrated system providers, Wärtsilä Corporation and MAN Energy Solutions exemplify the engine-catalyst convergence archetype. Yara Marine Technologies occupies a specialist position in compact dosing systems for constrained installation footprints. These three companies represent distinct competitive vectors: full integration, component specialization, and logistics-enabled service models.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| MAN Energy Solutions |
| Yara Marine Technologies |
| Hitachi Zosen Corporation |
| Mitsubishi Heavy Industries |
| Johnson Matthey |
| BASF |
| Nett Technologies |
| Tenneco |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between South Korean shipyards and catalyst substrate suppliers lock in both supply access and price visibility, compressing procurement uncertainty for newbuild contracts while exposing retrofit buyers to spot market volatility for vanadium-titanium formulations.
Pricing Analysis
IMO Tier III dictates the pricing tier structure across the marine SCR landscape. Three-tier pricing separates Lloyd's Register-certified premium packages from standard DNV-approved configurations and economy-grade legacy Tier II retrofits. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese indigenous catalyst formulations are gaining technical acceptance. Container fleet operators demonstrate highest price sensitivity, while cruise operators prioritize single-vendor compliance over unit economics.
Supply Chain Analysis
German specialty chemical facilities anchor copper-zeolite substrate production, creating import dependency for non-European yards. The marine SCR supply chain draws from South Korea for hull-integrated system assembly, Germany for catalyst substrate manufacturing, and Japan for zeolite raw material processing. Rare earth element sourcing from Chinese processors and ceramic substrate supply from Japanese producers concentrate input risk. Distribution runs through port-proximate service networks in Singapore and Rotterdam, with just-in-time urea logistics replacing centralized warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine SCR demand is accelerating on a regulatory inflection as IMO Tier III enforcement expands beyond North American and Baltic Sea ECAs into Mediterranean and East Asian waters, compressing installation timelines and forcing premature fleet upgrade cycles.
For Market Incumbents: Shield market position by deepening backward integration into catalyst substrate manufacturing to offset zeolite sourcing concentration risk from German and Japanese suppliers. Prioritize certification pre-approval investments with Lloyd's Register and DNV to compress 18-24 month approval timelines for novel vanadium-titanium formulations, denying fast-follower oxygen to emerging competitors. For New Entrants and Emerging Players: Korean Register of Shipping fast-track certification for low-temperature catalyst variants opens immediate white-space access. Target retrofit installation services for Greek and Singaporean tanker fleets where constrained engine room footprints and yard downtime premiums reward engineering specialization over manufacturing scale. Lead with compact urea dosing system integration as the go-to-market wedge against integrated engine-SCR packages. For Investors and Strategic Acquirers: Independent emissions monitoring and urea logistics providers represent the most defensible acquisition archetype as shipowners unbundle after-sales service from initial equipment purchases. Long-term viability hinges on ammonia-fuel engine compatibility roadmaps; obsolescence risk escalates if ammonia combustion achieves commercial scale before catalyst formulations adapt. Watch for IMO black carbon regulation reviews as the signal for next-generation compliance hardware demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Manufacturing | MAN Energy Solutions' substrate production secures supply continuity against German-Japanese zeolite concentration. |
| Compact Retrofit System Development | Yara Marine Technologies' dosing systems address Greek and Singaporean tanker fleet engine room constraints. |
| Port-Proximate Service Network Expansion | Singapore-based independent providers bundle urea logistics with predictive catalyst monitoring capabilities. |
| Combined DOC-SCR Unit Convergence | Cruise operators favor single-vendor packages that compress Lloyd's Register certification timelines. |
| Low-Temperature Catalyst Formulation R&D | Vanadium-titanium substrates operating at 280°C extend applicability to low-load marine engine operations. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with shipyard procurement directors, marine engineering consultants, classification society surveyors, and fleet technical managers; and secondary validation against Lloyd's Register certification databases, DNV approval registries, Korean Register of Shipping filings, and IMO Marine Environment Protection Committee documentation. Bottom-up vessel installation tallies triangulated against top-down catalyst substrate production estimates from German and Japanese specialty chemical facilities.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, installation scenario, end-user vessel category, and catalyst formulation technology. CAGRs were derived from regression analysis of historical installation rates projected against IMO regulatory deadline clustering. Key inputs included shipyard capacity utilization at Hyundai Heavy Industries and Samsung Heavy Industries, ECA zone expansion schedules, and ammonia-fuel engine development milestones.
Decision-makers should treat outputs as directional under sustained IMO Tier III enforcement and current catalyst technology trajectories; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ammonia-fuel engine commercialization timelines and black carbon regulatory reviews evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Zeolite Molecular Sieve Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
North America Zeolite Market
Catalysts
North America Refining Catalysts Market
Catalysts
South America Refining Catalysts Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Secondary Reforming Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Organic Catalyst Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Hydrodesulfurization Catalyst Market
Catalysts
Aluminum-Nickel Catalyst Market
Catalysts
Heterogeneous Catalyst Market