

Copper Bismuth Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Bismuth Catalyst Market Insights
Multi-source procurement is pivoting toward qualified regional suppliers as chemical manufacturers seek supply security for bismuth feedstock. BASF leverages its integrated precursor network to sustain captive catalyst production across European sites. Shepherd Chemical anchors North American supply through controlled bismuth oxide refining. Umicore competes on specialty formulations for fine chemicals producers requiring low-leach specifications.
Copper bismuth catalysts comprise bimetallic active phases, typically Cu-Bi ratios between 1:0.1 and 1:0.5 by weight, deposited on alumina or silica supports via impregnation or co-precipitation routes, functioning primarily to activate oxygen for selective oxidation and epoxidation reactions. Supported catalysts dominate volume shipments due to established regeneration protocols in fixed-bed reactors, while nano catalysts command premium pricing from research laboratories pursuing atom-efficient pathways. Heterogeneous catalysis leads application scale, though electrocatalysis is gaining traction in environmental remediation installations where electrode stability determines operational economics.
REACH in Europe and EPA toxicity thresholds in the United States restrict residual heavy-metal content in process streams, directly elevating bismuth's appeal as a lower-toxicity alternative to lead or mercury analogues. China's MEE enforces discharge limits that push petrochemical processors toward compliant catalytic systems. Stakeholders must monitor evolving precursor export controls and certification timelines across these jurisdictions to align capacity commitments with accessible demand pools.
Market Dynamics
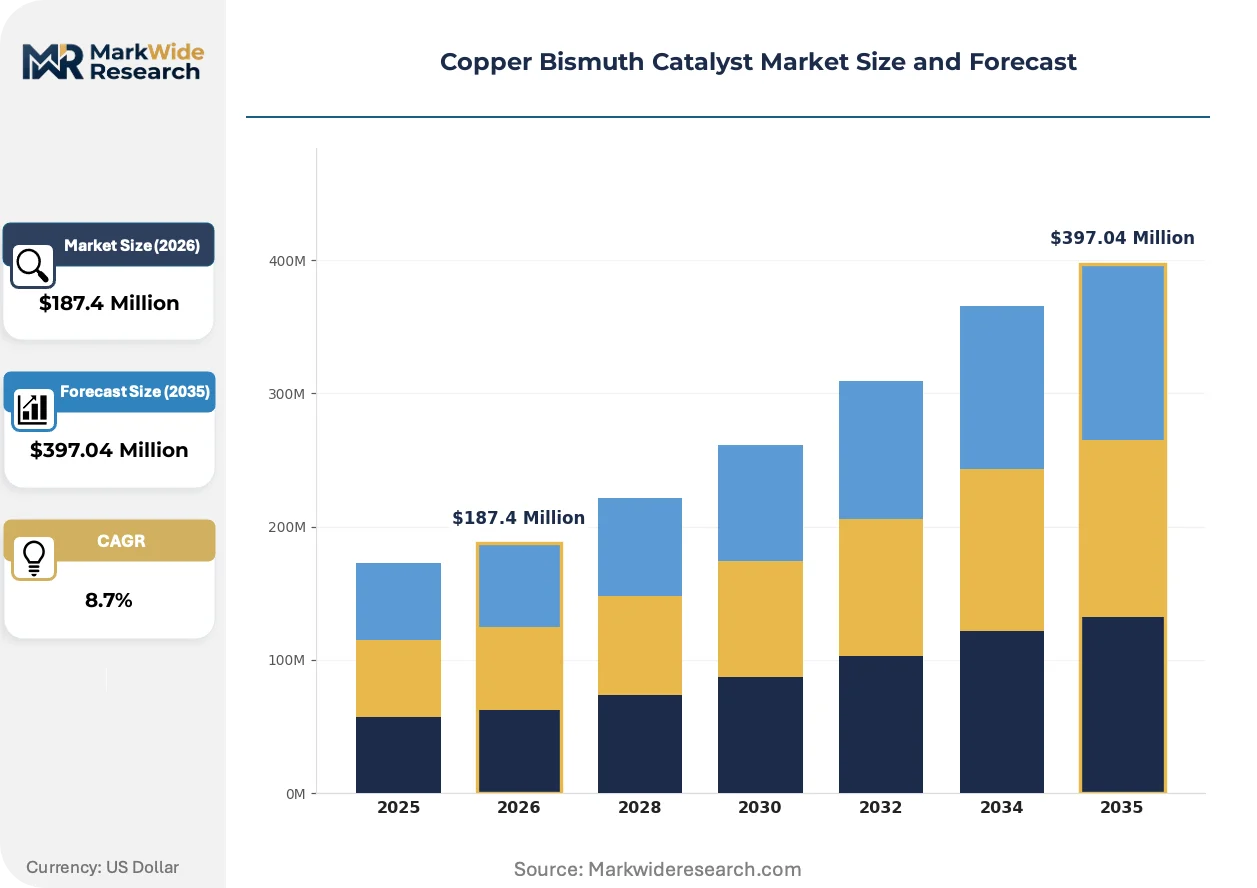
The copper bismuth catalyst market pivots on regulatory displacement of toxic heavy metals, with REACH compliance and China's dual carbon goals forcing petrochemical processors to requalify their catalytic stacks. This structural pressure concentrates procurement authority among specialty chemical producers with verified bismuth precursor supply chains.
Growth Catalysts
- REACH toxicity thresholds:European chemical manufacturers face mandatory reduction of lead and mercury residuals in process streams, elevating bismuth-based systems as compliant drop-in replacements for selective oxidation units.
- China's MEE discharge mandates:Petrochemical processors in the Yangtze River Delta must meet stringent wastewater standards that legacy heavy-metal catalysts cannot satisfy, accelerating substitution timelines.
- Fixed-bed reactor regeneration protocols:Established alumina-supported catalyst regeneration infrastructure lowers switching costs for refineries adopting bimetallic Cu-Bi formulations without capital equipment overhaul.
Market Restraints
- Bismuth price volatility:Concentrated extraction from lead-zinc smelting byproduct streams ties catalyst feedstock costs to base metal mining economics, compressing margin predictability for formulators.
- Precursor supply concentration:Refined bismuth oxide capacity clusters in Chinese smelting corridors, exposing non-Asian catalyst producers to export control disruptions and tariff exposure.
- Performance ceiling in high-temperature epoxidation:Cu-Bi active phases exhibit thermal deactivation above threshold temperatures, restricting deployment in certain steam-cracker derivative processes where alternative catalysts maintain stability.
Strategic Opportunities
- Electrocatalysis environmental remediation:Wastewater treatment installations in industrial zones seek electrode-stable bimetallic catalysts for electrochemical pollutant degradation, opening unit-dose pricing models.
- India's PLI scheme for specialty chemicals:Domestic production incentives for advanced materials create localized formulation opportunities for catalyst suppliers establishing technical service presence.
- Nano-catalyst research commercialization:Atom-efficient synthesis pathways developed in academic laboratories transition to pilot-scale contract manufacturing, commanding premium pricing from pharmaceutical intermediate producers.
Industry Challenges
- Bimetallic impregnation expertise scarcity:Precise Cu-Bi ratio control during co-precipitation requires experienced catalytic chemists, with talent competition intensifying among European specialty chemical employers.
- REACH certification timeline compression:New bismuth-based formulations face extended substance registration periods, delaying market entry for innovators against incumbent qualified suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Bismuth Catalyst Market Trends and Innovations
Process intensification and atom-efficiency mandates are compressing catalyst development cycles, with formulators integrating computational screening into experimental workflows. This convergence accelerates qualification timelines for novel bimetallic systems.
Computational catalyst design is unifying density functional theory predictions with high-throughput experimentation. Specialty chemical producers in Germany and Japan deploy these hybrid workflows to optimize Cu-Bi surface architectures for specific oxidation selectivity. The approach is unifying previously siloed R&D functions, collapsing the traditional 18-24 month formulation cycle into compressed 8-12 month qualification periods for targeted petrochemical applications.
REACH authorization timelines for substituted heavy-metal catalysts are tightening residual toxicity thresholds in European process streams. Chemical manufacturers face mandatory requalification of catalytic systems by specified deadlines, elevating documentation burdens for incumbent suppliers. Fine chemicals producers in the Rhine-Ruhr corridor accelerate bismuth-based pilot programs to secure regulatory continuity ahead of enforcement windows.
Long-term offtake contracting is displacing spot procurement for bismuth precursor supply. Petrochemical processors in East Asian manufacturing clusters negotiate multi-year feedstock agreements directly with refined oxide producers, bypassing traditional distributor networks. This pattern concentrates procurement leverage among integrated chemical majors with balance sheet capacity to commit volume guarantees.
Copper Bismuth Catalyst Market Segmentation
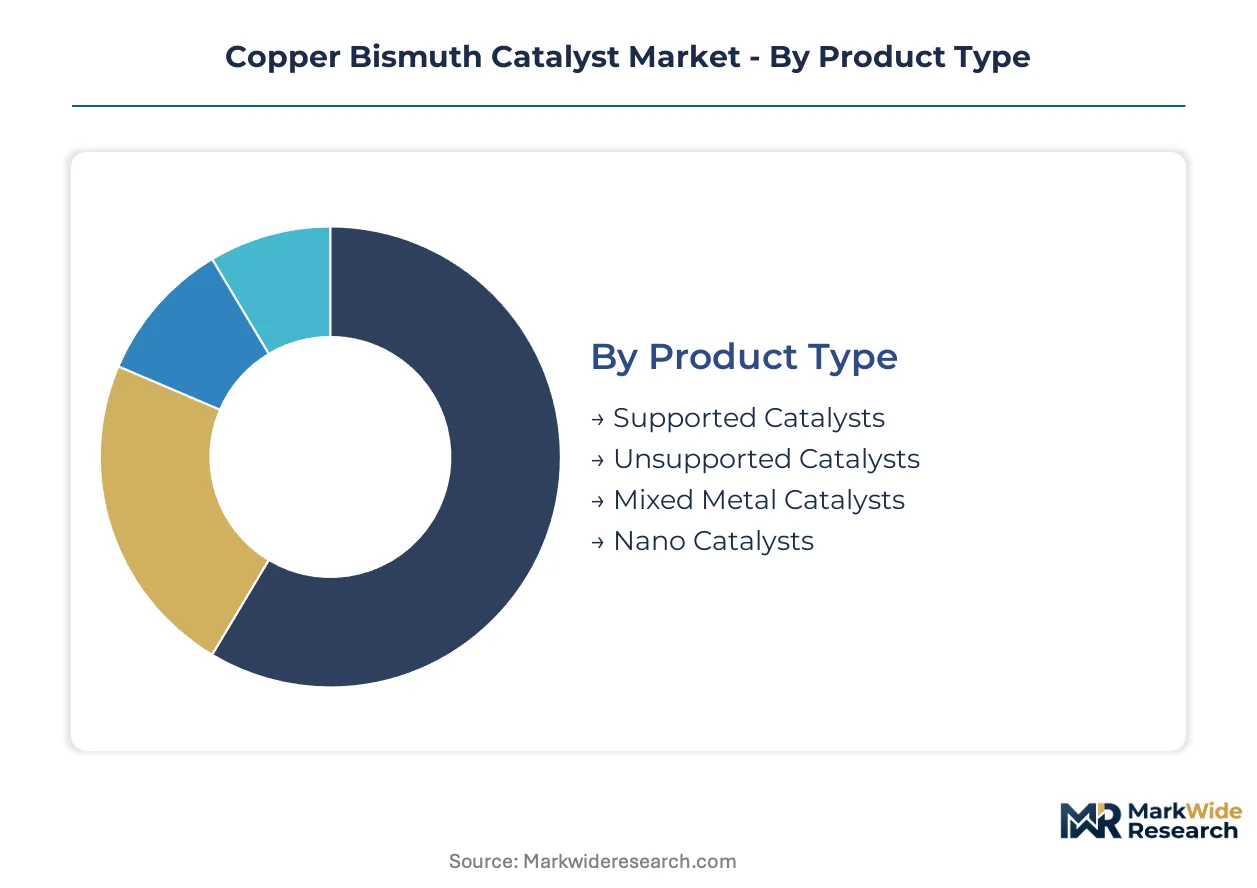
Copper bismuth catalyst procurement patterns diverge sharply across product architectures and catalytic technologies. Refinery operators prioritize regeneration-compatible formats while specialty chemical producers seek atom-efficient nano formulations for high-value synthesis.
Product Type:
Replacement cycles for fixed-bed reactor systems favor catalyst formats with established regeneration protocols, driving upgrade decisions toward proven support architectures.
- Supported Catalysts:Bimetallic Cu-Bi phases deposited on alumina or silica carriers via impregnation routes, typically with Cu-Bi weight ratios between 1:0.1 and 1:0.5. Petrochemical processors in the Yangtze River Delta favor these for oxidative dehydrogenation units where thermal cycling demands robust support adhesion.
- Nano Catalysts:Atomically dispersed active phases below 10nm particle size, synthesized through controlled co-precipitation or microemulsion techniques. Research laboratories in Osaka and pharmaceutical intermediate producers command premium unit pricing for electrocatalytic and selective oxidation applications requiring maximum surface-area-to-volume ratios.
- Unsupported Catalysts:Bulk bimetallic oxides without carrier matrices, offering higher metal loading for specific gas-phase reactions.
- Mixed Metal Catalysts:Cu-Bi systems alloyed with tertiary metals such as cobalt or manganese to modulate redox properties for specialized epoxidation pathways.
Supported catalysts sit at the top of the volume ranking, with nano catalysts climbing the fastest.
Technology:
Cost tier separation between mature heterogeneous installations and emerging electrocatalytic systems shapes R&D allocation across formulator portfolios.
- Heterogeneous Catalysis:Solid-phase catalysts operating in fixed-bed or fluidized-bed reactor configurations, dominating current commercial deployment. BASF and Umicore leverage decades of impregnation expertise to serve European petrochemical clients under REACH-mandated requalification timelines.
- Electrocatalysis:Electrode-immobilized bimetallic systems for electrochemical pollutant degradation and environmental remediation. Wastewater treatment facilities in Germany's Rhine-Ruhr industrial corridor pilot these for MEE-aligned discharge compliance, with unit-dose pricing models emerging.
- Homogeneous Catalysis:Molecularly dispersed catalysts in liquid phase, limited to batch specialty chemical synthesis with recovery challenges.
- Photocatalysis:Light-activated systems combining Cu-Bi with semiconductor supports for solar-driven oxidation processes, currently confined to academic and pilot-scale investigation.
Heterogeneous catalysis commands the installed base, while electrocatalysis gains share fastest.
Application:
Application-driven procurement concentrates in manufacturing clusters where regulatory pressure intersects with process scale.
- Petrochemical Processing:Selective oxidation and epoxidation reactions in steam cracker derivative production, particularly propylene oxide and acrylic acid synthesis. Chinese processors under MEE discharge mandates accelerate substitution of legacy lead-based systems.
- Fine Chemicals Production:High-purity intermediate synthesis for pharmaceuticals and agrochemicals, where low-leach specifications and batch traceability command formulation premiums. Specialty producers in Germany's chemical triangle prioritize REACH-compliant bismuth systems ahead of authorization deadlines.
- Organic Synthesis:General oxidation and coupling reactions across commodity chemical manufacturing.
- Environmental Remediation:Catalytic degradation of industrial pollutants in wastewater and off-gas treatment.
Petrochemical processing leads volume deployment, with fine chemicals production expanding most quickly.
End User Industry:
Customer-type segmentation reveals a bifurcation between volume-contracting integrated majors and specification-driven niche purchasers.
- Chemical Manufacturers:Integrated petrochemical majors operating continuous-process facilities with multi-year catalyst offtake agreements. East Asian clusters around Shanghai negotiate directly with refined bismuth oxide producers, bypassing distributor networks.
- Specialty Chemical Producers:Batch-oriented manufacturers of pharmaceutical and agrochemical intermediates, requiring documented low-toxicity certification and technical service support. Rhine-Ruhr and Osaka-based formulators drive qualification of novel Cu-Bi surface architectures.
- Research Laboratories:Academic and contract research organizations developing next-generation catalytic systems.
- Catalyst Suppliers:Merchant formulators and distributors serving fragmented regional chemical processors.
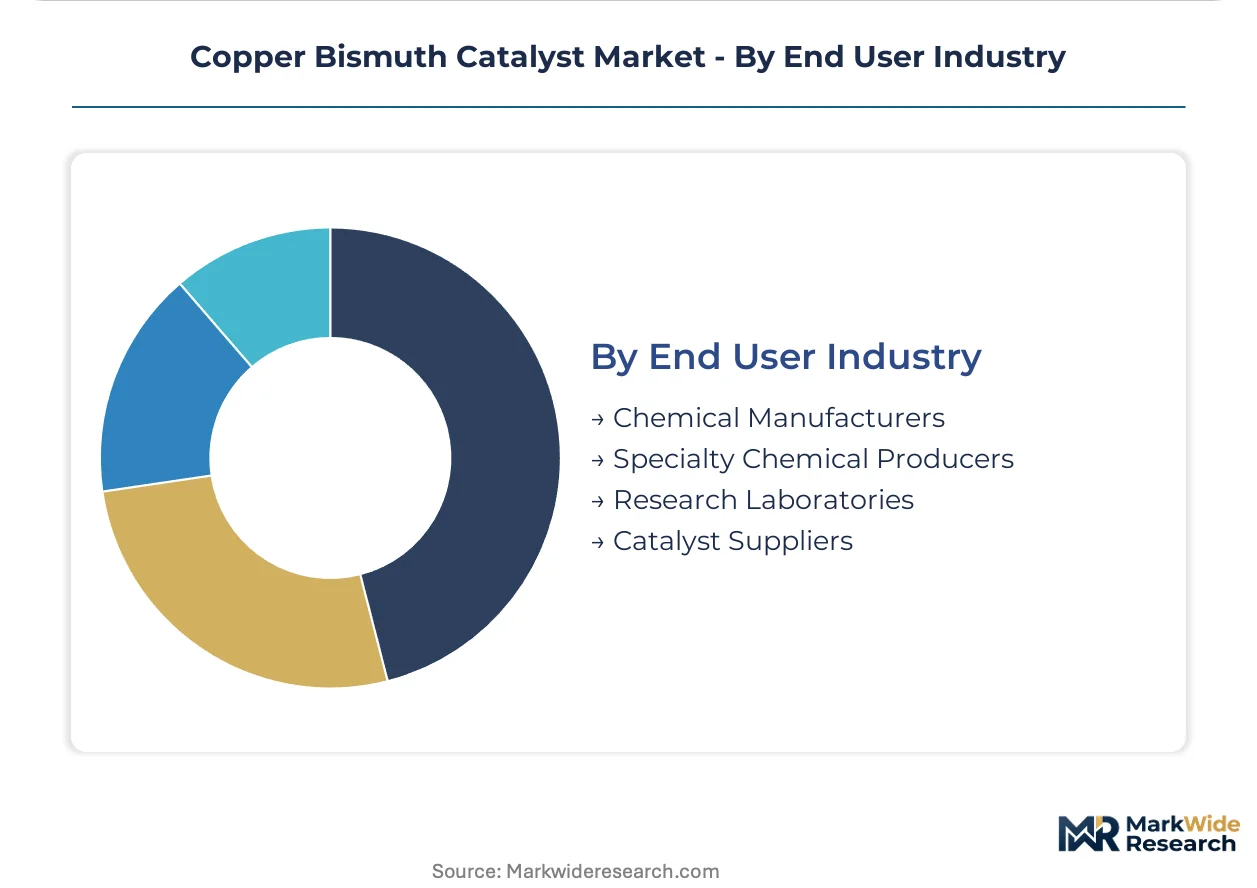
Chemical manufacturers anchor procurement volume, with specialty chemical producers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing copper bismuth catalyst production toward jurisdictions where REACH-equivalent compliance costs remain lower, while established chemical clusters absorb premium-tier formulation work.
China
MEE discharge mandates in the Yangtze River Delta are forcing petrochemical processors to abandon legacy lead-based systems. The country's dual carbon goals accelerate substitution timelines for heavy-metal catalysts in steam cracker derivative production. Manufacturing clusters around Shanghai negotiate multi-year bismuth oxide offtake agreements directly with refined oxide producers.
Germany
Specialty chemical producers in the Rhine-Ruhr corridor face compressed REACH authorization timelines for substituted heavy-metal catalysts. ECHA toxicity thresholds elevate documentation burdens for incumbent suppliers. Fine chemicals manufacturers in North Rhine-Westphalia accelerate bismuth-based pilot programs to secure regulatory continuity ahead of enforcement windows.
United States
EPA toxicity thresholds restrict residual heavy-metal content in process streams, elevating bismuth's appeal as a lower-toxicity alternative. Shepherd Chemical anchors North American supply through controlled bismuth oxide refining. Petrochemical processors on the Gulf Coast leverage established fixed-bed reactor regeneration infrastructure to lower switching costs.
Japan
Research laboratories in Osaka command premium pricing for nano catalysts requiring maximum surface-area-to-volume ratios. METI standards for chemical manufacturing push pharmaceutical intermediate producers toward atom-efficient synthesis pathways. The Kansai manufacturing belt concentrates pilot-scale contract manufacturing for academic commercialization.
India
The PLI scheme for specialty chemicals creates localized formulation opportunities for catalyst suppliers establishing technical service presence. Domestic production incentives for advanced materials attract merchant formulators seeking to bypass Chinese precursor supply concentration. Gujarat and Maharashtra chemical corridors emerge as qualification sites for novel bimetallic surface architectures.
Copper Bismuth Catalyst Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrocatalytic and nano-catalyst niches where premium pricing sustains smaller-scale operations. The market structures around three archetypes: integrated chemical majors with captive precursor networks, specialized catalyst formulators with impregnation expertise, and refined metal suppliers backward-integrating into oxide production. Dominant competitive moves include long-term offtake contracting for feedstock security and computational screening investments to compress formulation cycles.
Among European-integrated majors, BASF and Lanxess exemplify the captive-production archetype through established precursor networks. Shepherd Chemical occupies a position as a North American anchor for controlled oxide refining. Umicore sits within the specialty-formulation tier, representing the low-leach specification segment for fine chemicals producers. These three patterns illustrate how geographic origin and company structure shape competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| BASF |
| Shepherd Chemical |
| Lanxess |
| Solvay |
| Arkema |
| Eastman Chemical Company |
| 5N Plus |
| Umicore |
| JX Nippon Mining & Metals |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange bismuth price indices cascade through catalyst supply chains, compressing margin buffers for formulators when lead-zinc smelting economics tighten. REACH compliance premiums and Chinese export licensing delays stratify procurement costs across buyer archetypes, with specialty chemical producers absorbing tiered certification markups that commodity processors avoid.
Pricing Analysis
Input-cost pass-through from refined bismuth oxide spot markets governs catalyst pricing, with formulators adjusting quotations quarterly to smelter corridor output rates. Price differentiation rests on REACH pre-registration status and low-leach certification grade, separating specialty chemical producers from commodity petrochemical buyers. Pricing pressure stems from concentrated precursor supply in Chinese refining clusters, squeezing margin predictability for European formulators lacking captive oxide capacity. Specialty chemical producers in Germany's Rhine-Ruhr corridor exhibit lowest price sensitivity due to regulatory deadline pressure, while Gulf Coast petrochemical processors negotiate hardest on volume contract terms.
Supply Chain Analysis
Bismuth feedstock supply rests on Chinese lead-zinc smelting byproduct recovery, with secondary refining corridors in Belgium and Mexico providing regional buffer capacity. Catalyst production draws from refined bismuth oxide, alumina and silica support matrices, and tertiary metal dopants for specialized formulations. Single-source vulnerability concentrates in Yangtze River Delta oxide refiners, exposing non-Asian formulators to export permit disruptions and tariff repositioning. Distribution runs through direct long-term offtake agreements between integrated chemical majors and refined metal producers, bypassing traditional merchant distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India's PLI scheme for specialty chemicals, where domestic production incentives undercut REACH compliance costs burdening European formulators by approximately one-third.
For Market Incumbents: Extend captive precursor networks into Indian and Southeast Asian refining corridors to offset Chinese supply concentration risk. Lock in multi-year bismuth oxide offtake agreements ahead of MEE enforcement windows tightening in the Yangtze River Delta. Invest in computational catalyst screening capabilities to compress formulation cycles against emerging nano-catalyst specialists.
For New Entrants and Emerging Players: Regional distributors serving fragmented chemical processors in India's Gujarat corridor represent the most penetrable channel partner type for market entry. Target electrocatalysis environmental remediation installations in Germany's industrial zones, where electrode stability specifications command premium unit-dose pricing absent entrenched supplier relationships. Pursue pilot-scale contract manufacturing partnerships with Osaka-based research laboratories to commercialize atom-efficient synthesis pathways.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialty catalyst formulators possessing impregnation expertise and REACH pre-registered product portfolios. Long-term viability favors acquisition targets with demonstrated bimetallic ratio control capabilities and established technical service presence in at least two regulatory jurisdictions. Watch MEE discharge mandate enforcement intensity in Chinese petrochemical clusters as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Shepherd Chemical's captive oxide capacity insulates North American formulators from Chinese export volatility. |
| Long-term Supply Agreement | East Asian manufacturing clusters around Shanghai negotiate direct multi-year bismuth oxide offtake contracts. |
| Green Manufacturing Transition | REACH toxicity thresholds elevate bismuth-based systems as compliant replacements for lead and mercury catalysts. |
| Joint Venture | Indian PLI scheme incentives attract foreign catalyst suppliers establishing localized formulation partnerships. |
| Capacity Expansion | Rhine-Ruhr specialty chemical producers accelerate pilot-scale capacity to meet compressed ECHA authorization timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with catalyst procurement managers, plant engineers at petrochemical facilities, technical R&D directors at specialty chemical producers, and distribution channel partners in East Asian manufacturing clusters. Secondary validation drew from customs and trade flow databases, Cefic and ACC chemical industry reports, SEC 10-K filings of listed chemical majors, and ECHA substance registration timelines. Bottom-up catalyst shipment tracking and top-down petrochemical capacity modeling were triangulated against regional regulatory implementation schedules.
Segment-weighting approaches distributed value estimates across supported versus nano catalyst architectures, heterogeneous versus electrocatalytic technology deployments, and petrochemical processing versus fine chemicals production applications. CAGRs were derived from regression analysis of historical precursor price elasticity and projected regulatory substitution timelines, incorporating bismuth oxide supply forecasts from lead-zinc smelting output models and REACH authorization deadline phasing across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese environmental policy enforcement intensity and bismuth export licensing protocol changes. Forecasts reflect documented assumptions regarding MEE discharge mandate implementation rates and ECHA toxicity threshold revision schedules. A small set of named triggers warrants ongoing watch: precursor export permit disruptions, computational catalyst design breakthroughs, and electrocatalysis pilot-to-commercial scale transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.