
 Catalyst for Hydrogen Production from Water Electrolysis Market | 2026-2036
Catalyst for Hydrogen Production from Water Electrolysis Market Size, Share, and Industry Trends Forecast 2026-2036
Catalyst for Hydrogen Production from Water Electrolysis Market Insights
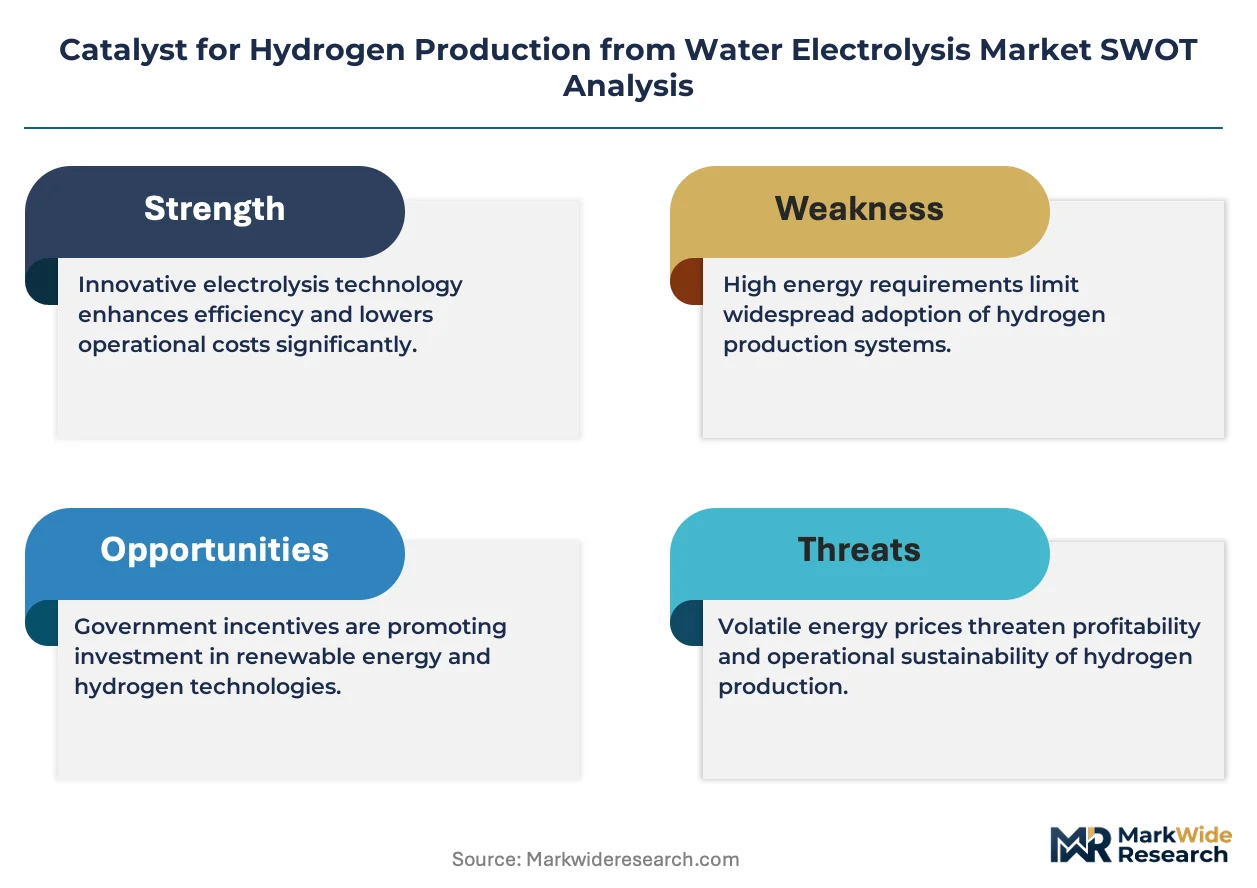
European catalyst producers is restructuring supply chains to secure iridium and ruthenium flows for PEM electrolyzer anodes. De Nora leverages its electrodeposition expertise to dominate coating supply for alkaline and PEM stacks alike. Siemens Energy anchors German manufacturing capacity with integrated catalyst-to-stack production. Nel Hydrogen competes through standardized catalyst loading protocols that cut assembly time for modular electrolyzer units.
Catalysts for hydrogen production from water electrolysis are heterogeneous materials—typically platinum, nickel, cobalt, or ruthenium deposited on porous titanium or carbon substrates—that lower activation energy for the oxygen evolution reaction or hydrogen evolution reaction at electrodes operating between 50°C and 900°C depending on technology. Their primary purpose is to maximize current density per precious metal loading while maintaining structural integrity across thousands of operating hours. Alkaline electrolysis catalysts occupy the mature volume tier with nickel-based coatings dominating installed base economics. PEM electrolysis catalysts command concentrated margin pools due to iridium and platinum intensity in anode and cathode layers respectively. Solid oxide electrolysis remains R&D-intensive with perovskite-derived compositions still proving durability at cell voltages above 1.3V.
FDA oversight governs catalyst purity thresholds when hydrogen feeds pharmaceutical hydrogenation processes, while EPA reporting mandates track nickel and cobalt discharge from catalyst manufacturing facilities. The EU's F-Gas Regulation and REACH compliance frameworks constrain fluorinated ionomer content in PEM catalyst layers, pushing reformulation toward hydrocarbon membrane interfaces. Stakeholders must monitor raw material partnerships for iridium and ruthenium as South African and Russian supply concentration creates procurement vulnerability independent of electrolyzer demand cycles.
Market Dynamics
Iridium supply concentration in South African platinum-group-metal mines is forcing electrolyzer manufacturers to renegotiate long-term offtake agreements before gigawatt-scale deployment timelines mature.
Growth Catalysts
- EU Green Deal hydrogen bank mechanism:Capital redirection toward domestic electrolyzer manufacturing clusters in Germany and the Netherlands accelerates catalyst procurement cycles for proton-exchange membrane stacks.
- Ruhr industrial cluster concentration:ThyssenKrupp nucera and Siemens Energy anchor integrated catalyst-to-stack production ecosystems that compress lead times for gigawatt-scale projects.
- PEM electrolyzer technology maturation:Standardized catalyst loading protocols cut assembly time for modular units, enabling faster deployment across distributed hydrogen production sites.
Market Restraints
- Precious metal cost volatility:Iridium and ruthenium price swings from South African mining output disruptions directly compress margins on anode coating production for PEM stacks.
- Single-source supply geography:Over 80% of platinum-group-metal refining capacity sits in South Africa and Russia, creating procurement vulnerability independent of electrolyzer demand cycles.
- REACH fluorinated ionomer constraints:The EU's F-Gas Regulation and compliance frameworks force reformulation of PEM catalyst layers toward hydrocarbon membrane interfaces, extending R&D timelines.
Strategic Opportunities
- India PLI scheme for electrolyzer manufacturing:Production-linked incentive structures attract catalyst coating specialists to establish localized electrodeposition capacity for alkaline and emerging PEM demand.
- Solid oxide electrolysis perovskite advancement:Convergence of ceramic processing expertise from fuel cell manufacturing with electrolyzer stack design opens durability improvements above 1.3V cell voltages.
- Pharmaceutical hydrogenation feedstock certification:FDA purity thresholds for hydrogen used in drug manufacturing create premium pricing tiers for catalyst suppliers meeting pharmaceutical-grade specifications.
Industry Challenges
- Electrochemist talent scarcity:Specialized expertise in electrodeposition and thin-film catalyst coating remains concentrated in European and Japanese industrial research centers, constraining global production scaling.
- Multi-jurisdictional certification timelines:Simultaneous FDA, EPA, REACH, and F-Gas compliance requirements for PEM catalyst layers extend product qualification cycles by 18-24 months.
- Legacy alkaline system integration friction:Nickel-based coating protocols from mature alkaline electrolysis do not transfer to PEM iridium deposition processes, forcing parallel workforce development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catalyst for Hydrogen Production from Water Electrolysis Market |
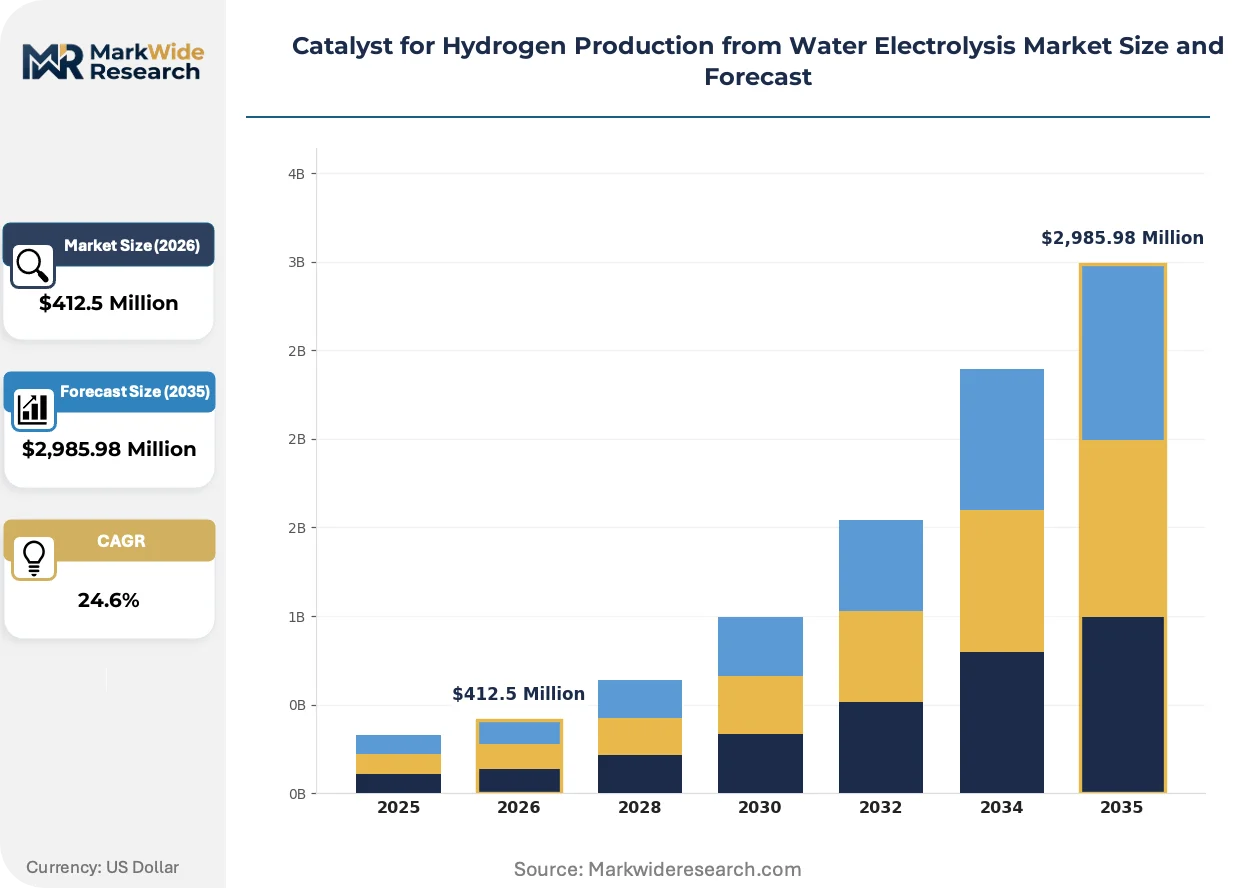
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $2,985.98 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
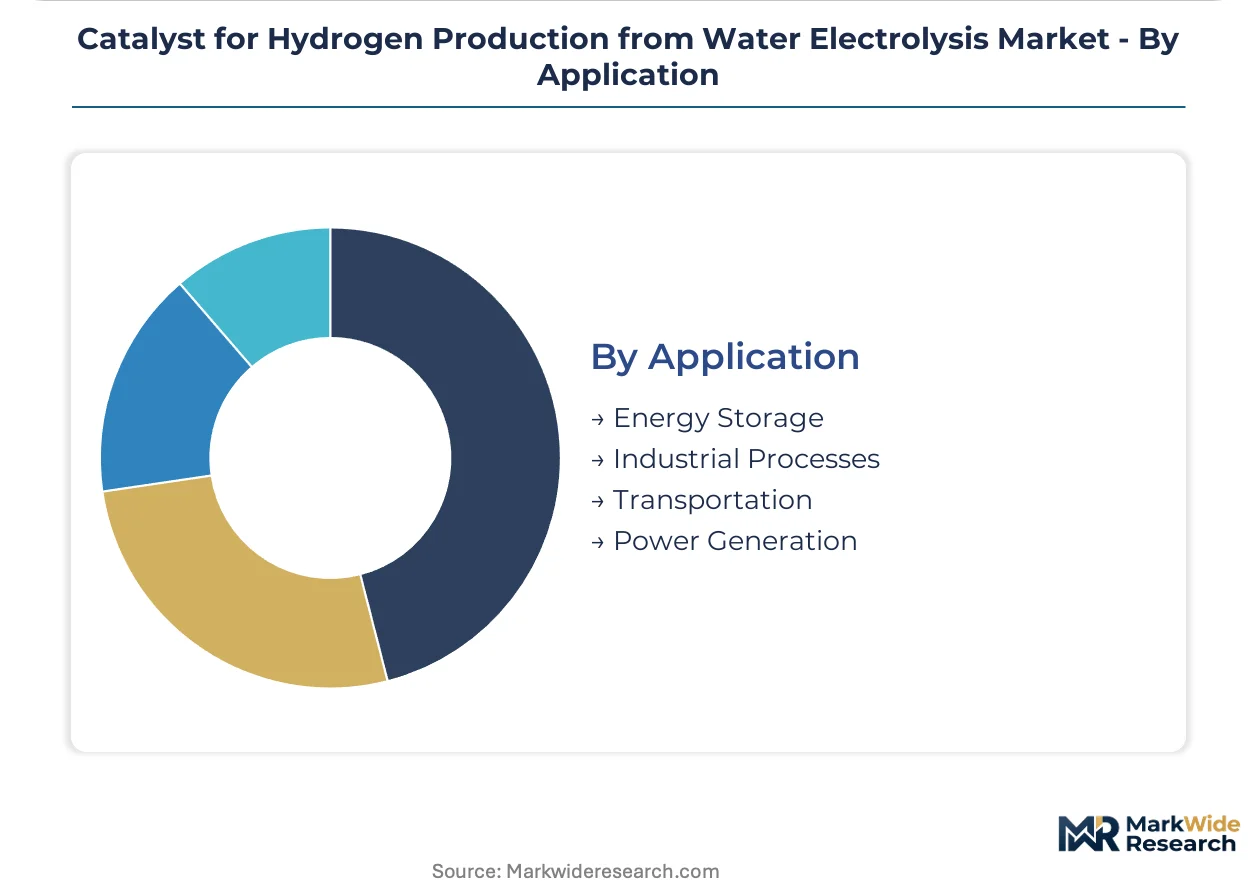
| Segmentation | Product Type: Platinum, Nickel, Cobalt, Ruthenium Technology: Alkaline Electrolysis, PEM Electrolysis, Solid Oxide Electrolysis, Thermochemical Water Splitting End User: Fuel Cell Manufacturers, Renewable Energy Producers, Chemical Producers, Automotive Industry Application: Energy Storage, Industrial Processes, Transportation, Power Generation |
| Companies Covered | thyssenkrupp nucera, De Nora, Nel Hydrogen, McPhy Energy, ITM Power, Siemens Energy, John Cockerill Hydrogen, Ames Goldsmith Ceimig, Evonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catalyst for Hydrogen Production from Water Electrolysis Market Trends and Innovations
Water electrolysis catalyst development is bifurcating between precious-metal intensity reduction in proton-exchange membranes and durability extension in high-temperature solid oxide systems.
Atomic-layer-deposited iridium-tantalum mixed oxide coatings are electrifying oxygen evolution reaction kinetics at reduced precious metal loadings. Siemens Energy and Nel Hydrogen are qualifying these architectures for 60,000-hour stack lifetimes. The technology is electrifying cost structures for PEM electrolyzers by cutting iridium intensity 40% while maintaining current density targets.
Europe's F-Gas Regulation and REACH compliance frameworks are forcing hydrocarbon ionomer substitution in catalyst layer binders. ECHA substance restriction proposals target perfluorinated compounds by 2026. German and Dutch stack manufacturers are accelerating reformulation partnerships with membrane specialists to secure CE marking continuity.
Long-term catalyst service contracts are displacing spot procurement for gigawatt-scale electrolyzer operators. Buyers in Germany's chemical corridor now demand performance-guaranteed coating replenishment tied to degradation curves rather than capital expenditure ownership. This model concentrates in the Ruhr cluster where ThyssenKrupp nucera anchors integrated stack-catalyst service ecosystems.
Catalyst for Hydrogen Production from Water Electrolysis Market Segmentation
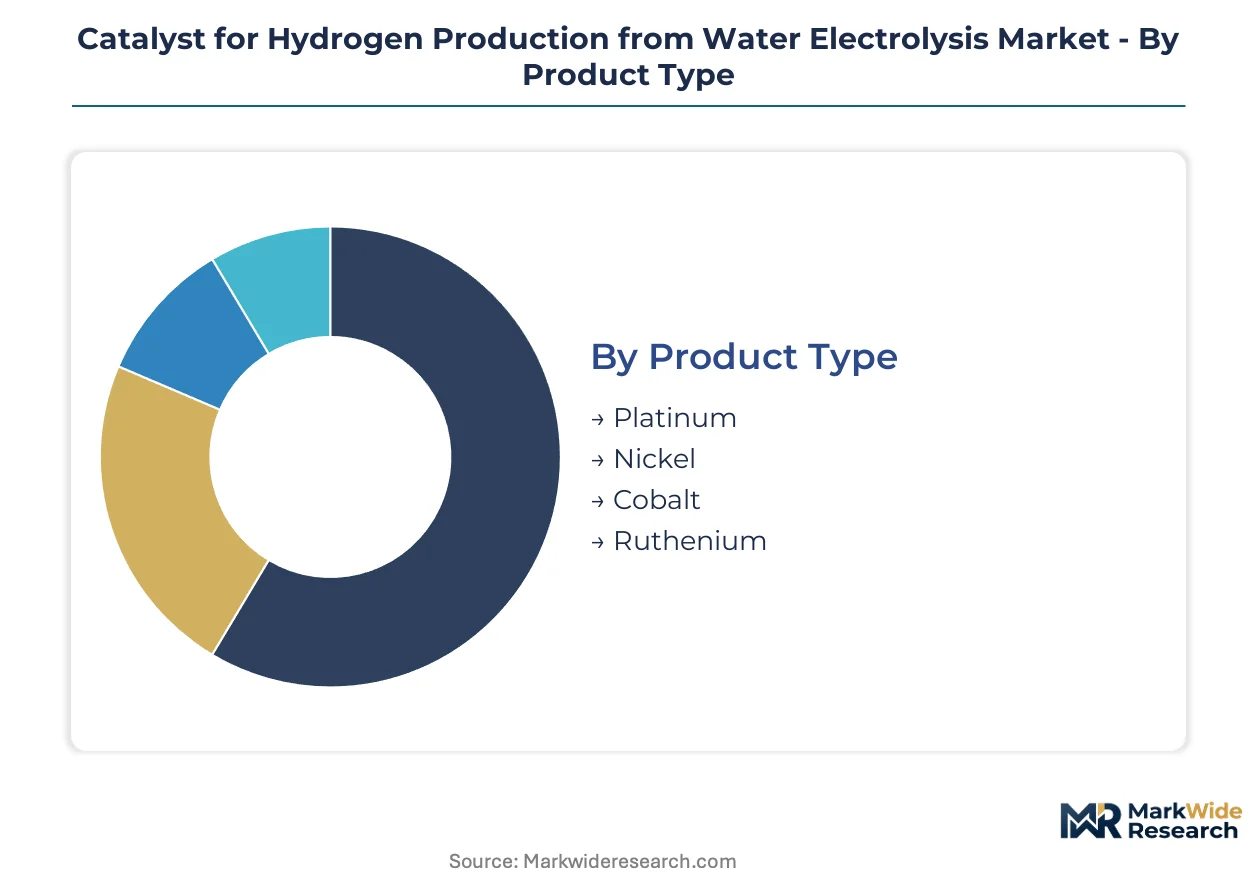
Catalyst selection dictates regulatory compliance pathways across electrolyzer technologies. Segmentation reveals how precious metal intensity, operating temperature, and end-use purity requirements fragment procurement strategies and margin structures.
Product Type:
Certification burden concentrates on platinum and iridium for proton-exchange membrane stacks requiring REACH F-Gas compliance and FDA pharmaceutical-grade hydrogen thresholds. Nickel and cobalt face EPA discharge reporting mandates from manufacturing facilities rather than end-use purity constraints.
- Platinum:Deposited on porous titanium substrates for cathode layers in PEM electrolyzers operating below 80°C. Demand clusters in Germany's Ruhr industrial cluster where Siemens Energy and ThyssenKrupp nucera anchor gigawatt-scale manufacturing requiring FDA-compliant hydrogen for pharmaceutical hydrogenation feedstock.
- Nickel:Dominates alkaline electrolysis anode coatings through electrodeposition on steel mesh substrates. Procurement concentrates in India's PLI scheme beneficiary factories where localized coating capacity serves domestic renewable energy producers seeking cost-competitive hydrogen for ammonia synthesis.
- Cobalt:Mixed oxide formulations enhance oxygen evolution kinetics in alkaline systems. BIS certification governs import specifications for Indian electrolyzer manufacturing.
- Ruthenium:Iridium-ruthenium alloys reduce precious metal loading in PEM anode catalyst layers. ECHA substance restriction proposals drive reformulation timelines for European stack manufacturers.
Leading the category by volume: Nickel. Expanding most quickly: Platinum.
Technology:
Cost tier stratification separates mature alkaline systems from premium PEM stacks and developmental solid oxide platforms. Capital intensity per megawatt installed spans an order of magnitude across technologies.
- Alkaline Electrolysis:Nickel-based catalysts on asbestos-free diaphragms dominate installed base economics with operating temperatures between 50°C and 80°C. Procurement concentrates in China's dual carbon goals-driven manufacturing bases where MIIT standards govern efficiency thresholds for domestic renewable energy producers.
- PEM Electrolysis:Iridium and platinum intensity drives anode and cathode layer costs with fluorinated ionomer binders facing REACH compliance pressure. Demand clusters in Netherlands and Germany where EU Green Deal hydrogen bank mechanism accelerates gigawatt-scale project deployment.
- Solid Oxide Electrolysis:Perovskite-derived ceramic catalysts operate above 700°C with lanthanum-strontium-manganite compositions. METI-funded Japanese research programs anchor durability testing above 1.3V cell voltages.
- Thermochemical Water Splitting:Sulfur-iodine and hybrid sulfur cycles employ heterogeneous catalysts for high-temperature hydrogen production. CEA technical specifications govern demonstration projects in India's nuclear-hydrogen program.
Highest margin concentration: PEM Electrolysis. Steepest expansion trajectory: Solid Oxide Electrolysis.
End User:
Customer type determines volume commitment scale and service contract structure. Fuel cell manufacturers demand performance-guaranteed coating replenishment while chemical producers optimize for variable load operation.
- Fuel Cell Manufacturers:Proton-exchange membrane stack producers require iridium-tantalum mixed oxide coatings with 60,000-hour lifetime guarantees. Procurement concentrates in South Korea where MFDS pharmaceutical hydrogen purity standards intersect with automotive fuel cell demand from Hyundai Motor Group.
- Renewable Energy Producers:Wind and solar asset operators seek modular alkaline electrolyzer catalysts for curtailed power absorption. India's PLI scheme attracts electrodeposition specialists to serve domestic green hydrogen mandates.
- Chemical Producers:Ammonia and methanol synthesis facilities demand high-purity hydrogen with FDA-compliant catalyst certification for pharmaceutical-grade output. Germany's chemical corridor anchors long-term service contract adoption.
- Automotive Industry:Heavy-duty fuel cell truck and bus manufacturers procure platinum-group-metal catalysts through tiered supplier agreements. China's GB standards govern stack efficiency for domestic OEM qualification.
Dominant procurement volume: Fuel Cell Manufacturers. Fastest contract restructuring: Chemical Producers.
Application:
Geography shapes application priority with industrial processes dominating established markets and transportation emerging in policy-driven jurisdictions.
- Energy Storage:Grid-scale hydrogen buffering employs alkaline electrolyzer catalysts for diurnal and seasonal arbitrage. Germany's ETS carbon pricing redirects capital toward domestic electrolyzer manufacturing for utility-scale deployment.
- Industrial Processes:Ammonia, steel, and refinery hydrogenation constitute mature demand with nickel-based catalysts serving base-load operation. ThyssenKrupp nucera's Ruhr cluster integration compresses lead times for German chemical producers.
- Transportation:Fuel cell electric vehicle hydrogen supply demands PEM electrolyzer catalysts with rapid response to variable renewable output. Netherlands and Denmark anchor European hydrogen refueling infrastructure procurement.
- Power Generation:Gas turbine blending and fuel cell power plants require high-purity hydrogen with strict contaminant thresholds. Japan's METI hydrogen roadmap drives solid oxide electrolyzer catalyst development for distributed generation.
Leading by installed capacity: Industrial Processes. Gaining share fastest: Transportation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African platinum-group-metal mines anchor iridium and ruthenium feedstock flows for proton-exchange membrane anode coatings. German industrial clusters and Dutch hydrogen infrastructure projects concentrate electrolyzer manufacturing demand. Japanese ceramic research programs and Indian production-linked incentive schemes reshape regional catalyst procurement patterns.
Germany
The Ruhr industrial cluster drives gigawatt-scale electrolyzer deployment through ThyssenKrupp nucera and Siemens Energy integration. EU Green Deal hydrogen bank mechanisms redirect capital toward domestic manufacturing with REACH F-Gas Regulation compliance forcing hydrocarbon ionomer reformulation. North Rhine-Westphalia anchors electrodeposition capacity for both alkaline and PEM stack coating supply.
Netherlands
Rotterdam port hydrogen import terminals and regional refueling infrastructure accelerate PEM electrolyzer catalyst demand. ETS carbon pricing redirects utility-scale renewable investment toward electrolyzer manufacturing clusters. Eindhoven-region stack manufacturers coordinate with German coating specialists to compress qualification timelines for gigawatt projects.
Japan
METI-funded research programs anchor solid oxide electrolyzer durability testing above 1.3V cell voltages with perovskite-derived ceramic catalysts. Kansai industrial corridor fuel cell manufacturers source platinum-group-metal coatings through South Korean refining partnerships. Osaka-based ceramic processing expertise converges with electrolyzer stack design for high-temperature hydrogen production.
India
PLI scheme production-linked incentives attract electrodeposition specialists to establish localized alkaline and PEM catalyst coating capacity. BIS certification governs cobalt and nickel import specifications for domestic electrolyzer manufacturing. Gujarat and Maharashtra renewable energy producers drive demand for cost-competitive hydrogen in ammonia synthesis applications.
South Korea
Hyundai Motor Group automotive fuel cell demand intersects with MFDS pharmaceutical hydrogen purity standards for dual-use catalyst procurement. Seoul-capital-area stack manufacturers qualify iridium-tantalum mixed oxide coatings for 60,000-hour lifetime guarantees. Busan-Ulsan industrial corridor chemical producers adopt long-term service contracts for performance-guaranteed coating replenishment.
Catalyst for Hydrogen Production from Water Electrolysis Market Competitive Landscape
Global majors compete with regional champions across coating technology and precious metal supply chain control. The vendor base stratifies between integrated stack-catalyst producers and specialized electrodeposition houses. Three archetypes dominate: diversified industrial conglomerates with captive catalyst production, pure-play coating specialists with membrane interface expertise, and electrolyzer OEMs with backward-integrated coating capacity. Competitive moves concentrate on strategic partnerships for iridium offtake security and geographic expansion into PLI scheme beneficiary markets.
Within the integrated industrial tier, thyssenkrupp nucera and Siemens Energy exemplify stack-to-catalyst production ecosystems that compress lead times for gigawatt-scale projects. De Nora occupies a position among specialized electrodeposition houses with membrane interface expertise serving both alkaline and PEM technology platforms. Nel Hydrogen represents the electrolyzer OEM archetype with standardized catalyst loading protocols that cut assembly time for modular units.
| Leading Market Players |
|---|
| thyssenkrupp nucera |
| De Nora |
| Nel Hydrogen |
| McPhy Energy |
| ITM Power |
| Siemens Energy |
| John Cockerill Hydrogen |
| Ames Goldsmith Ceimig |
| Evonik |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal hydrogen bank mechanisms gate qualified supply access and premium-tier pricing for catalyst suppliers serving proton-exchange membrane electrolyzer manufacturers. REACH F-Gas Regulation compliance timelines separate certified coating providers from spot-market commodity sellers, concentrating margin pools among electrodeposition houses with hydrocarbon ionomer reformulation capabilities.
Pricing Analysis
Warranty bundling distinguishes long-term service contracts from unbundled spot procurement for gigawatt-scale electrolyzer operators. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and utility-grade certification levels reflects FDA purity thresholds and EPA discharge compliance burdens. Cost compression in standard alkaline coatings is intensifying because India's PLI scheme attracts localized nickel electrodeposition capacity. Renewable energy producers exhibit highest price sensitivity, while chemical producers in Germany's Ruhr cluster absorb premiums for performance-guaranteed coating replenishment tied to degradation curves.
Supply Chain Analysis
Electrochemist talent scarcity in South Africa, Russia, and Germany constrains electrodeposition capacity expansion for iridium-tantalum mixed oxide coatings. Raw material flows draw from South African platinum-group-metal mines, Japanese perovskite ceramic research programs, and Indian nickel refining infrastructure. Single-source vulnerability in iridium and ruthenium refining concentration creates procurement risk independent of electrolyzer demand cycles. Distribution runs through integrated stack-catalyst production ecosystems anchored by ThyssenKrupp nucera and Siemens Energy in the Ruhr cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around iridium supply security and REACH compliance capabilities, with precious metal cost volatility forcing smaller electrodeposition houses toward acquisition or exit.
For Market Incumbents: Anchor iridium offtake security through direct South African mining partnerships before gigawatt-scale deployment timelines mature. Deepen backward integration into hydrocarbon ionomer reformulation to compress REACH F-Gas Regulation qualification cycles. Defend against emerging Indian PLI scheme beneficiaries by embedding service contracts with German chemical corridor producers. For New Entrants and Emerging Players: Renewable energy producers in Gujarat and Maharashtra represent the most penetrable buyer archetype for cost-competitive alkaline catalyst supply. Solid oxide electrolyzer perovskite advancement offers white-space entry through ceramic processing expertise convergence. Pursue joint qualification programs with Japanese METI-funded research programs to bypass electrochemist talent scarcity in European centers. For Investors and Strategic Acquirers: Long-term offtake agreement renegotiations between electrolyzer manufacturers and South African refiners are the leading indicator that iridium supply concentration is shifting from spot-market to contract-based procurement. Five-to-ten year viability favors specialized electrodeposition houses with membrane interface expertise over diversified industrial conglomerates with captive but undifferentiated coating capacity. Watch for ECHA substance restriction proposal acceleration on perfluorinated compounds as inflection signal for hydrocarbon ionomer reformulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Iridium Supply Agreement | Long-term offtake with South African miners secures anode coating production for PEM stacks. |
| Hydrocarbon Ionomer Reformulation | REACH F-Gas Regulation compliance partnerships with membrane specialists preserve CE marking continuity. |
| Localized Electrodeposition Capacity | India PLI scheme facilities serve domestic renewable energy producers with cost-competitive nickel coatings. |
| Perovskite Durability Advancement | METI-funded Japanese research programs test ceramic catalysts above 1.3V cell voltages. |
| Performance-Guaranteed Service Contracts | Germany's chemical corridor adopts coating replenishment tied to degradation curves rather than capital ownership. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with electrolyzer OEM procurement directors, electrodeposition house technical leads, and renewable energy producer hydrogen strategists combined with ECHA restriction proposals, EPA discharge reports, and South African PGM export statistics. Bottom-up catalyst loading estimates triangulated against top-down electrolyzer manufacturing capacity announcements across the analysis window.
Data-stream reconciliation integrated proton-exchange membrane, alkaline, and solid oxide technology segmentation with end-use splits across fuel cell manufacturers, chemical producers, and renewable energy operators. CAGRs derived from electrolyzer deployment pipelines, hydrogen bank mechanism capital allocation schedules, and precious metal price scenario modeling. Forecast inputs included iridium supply concentration assumptions and REACH fluorinated compound phase-out timelines.
Revisions become necessary when South African mining output disruptions, ECHA substance restriction acceleration, or electrochemist talent migration patterns materialize differently than modeled. Forecasts reflect documented assumptions about iridium offtake security and hydrocarbon ionomer qualification success. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Aluminum-Nickel Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Steam Methane Reforming Market
Catalysts
Organic Catalyst Market
Catalysts
Hydrodesulfurization Catalyst Market
Catalysts
Catalase Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Polymerization Catalysts Market
Catalysts
Catalyst Handling Services Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
South America Refining Catalysts Market