
 Global Healthcare Equipment Leasing Market | 2026-2036
Global Healthcare Equipment Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Equipment Leasing Market Foresight
Ambulatory surgical centers is reorganizing demand patterns across the Global Healthcare Equipment Leasing Market, pulling volume away from traditional hospital procurement. Siemens Healthineers leverages its imaging systems portfolio to dominate lease origination in European diagnostic networks. GE Healthcare anchors North American market presence through captive finance arms embedded within equipment sales workflows. McKesson Corporation competes on distribution density, bundling leased surgical tools with consumable supply contracts.
Healthcare equipment leasing constitutes a contractual financing mechanism where medical device users obtain operational rights without full capital ownership, typically structured through fixed-term payments with residual value allocation. Lease contracts specify equipment condition standards, maintenance obligations, and return protocols calibrated to FDA device classification tiers. Diagnostic machines and imaging systems command the largest share of lease origination value due to unit costs exceeding two million dollars for MRI and CT modalities. Operating leases attract short-cycle technology categories where obsolescence risk concentrates with lessors, while finance leases dominate surgical tools and patient monitoring devices where depreciation schedules align with clinical utility timelines.
FDA premarket notification requirements and EPA medical waste handling standards shape lessor refurbishment protocols and secondary market remarketing eligibility. The EU Medical Device Regulation and CE marking conformity assessment extend compliance burdens to cross-border lease portfolios held by DLL and Getinge AB. Stakeholders must monitor how SAMR device re-registration rules in China and Japan's PMDA quality management standards alter residual valuation models for leased equipment redeployed across Asia-Pacific clinical networks.
Market Dynamics
Capital constraints across ambulatory surgical centers are accelerating lease structures over traditional equipment procurement, compressing ownership cycles and expanding lessor balance sheets.
Growth Catalysts
- EU Medical Device Regulation:CE marking conformity assessment for refurbished diagnostic equipment creates compliant secondary markets, enabling lessors to extend asset utility across European clinical networks.
- Japan's aging hospital infrastructure:Replacement demand for MRI and CT modalities concentrates lease origination as facilities defer capital outlays.
- Outcome-based reimbursement:Bundled payment models in United States healthcare systems align lease payment structures with patient throughput metrics.
Market Restraints
- Residual value volatility:Rapid obsolescence in imaging technology compresses lessor recovery rates on returned equipment.
- China SAMR device re-registration:Cross-border redeployment of leased assets faces extended approval timelines and documentation burdens.
- Specialized maintenance labor:OEM-trained technician scarcity limits independent lessor servicing capabilities for complex diagnostic systems.
Strategic Opportunities
- India's diagnostic network expansion:Tier-2 and Tier-3 city hospital construction creates underpenetrated demand for mid-range imaging lease structures.
- Artificial intelligence integration:Convergence of AI-enabled diagnostic software with leased hardware platforms enables premium pricing on analytics-enhanced contracts.
- Japan PMDA quality management standards:Compliance certification for refurbished equipment opens remarketing pathways across Asia-Pacific clinical networks.
Industry Challenges
- Biomedical engineering talent pipeline:Equipment lifecycle management and refurbishment expertise shortages constrain lessor operational scaling.
- Legacy system integration:Newer leased diagnostic platforms require costly interoperability upgrades with existing hospital IT infrastructure.
- FDA premarket notification pathways:Refurbished device 510(k) submission timelines delay fleet redeployment and compress lessor utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Equipment Leasing Market |
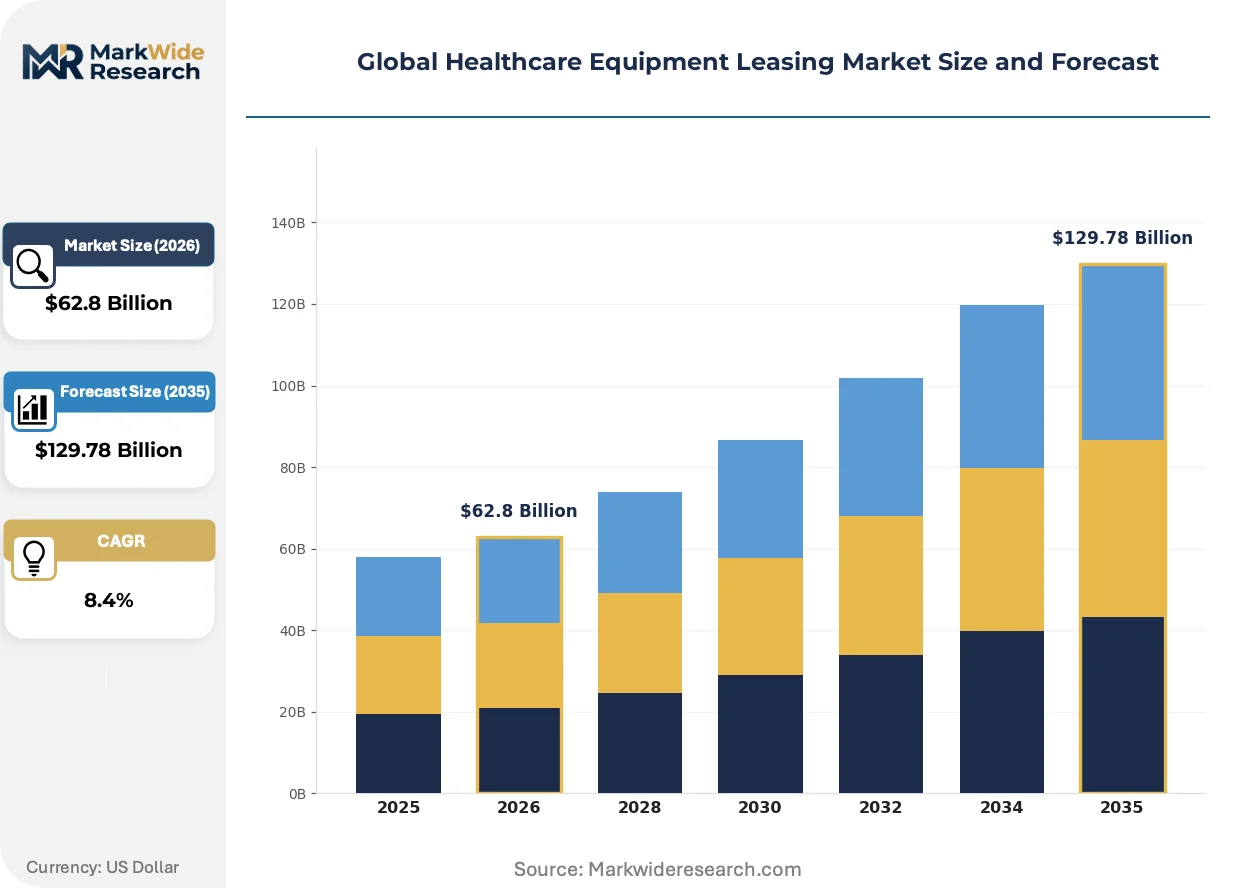
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $129.78 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Diagnostic Machines, Surgical Tools, Patient Monitoring Devices, Imaging Systems, Laboratory Instruments Leasing Model: Operating Lease, Finance Lease, Rental, Hire Purchase, Sale and Leaseback End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Facilities Application Area: Cardiology, Oncology, Orthopedics, Neurology, Radiology |
| Companies Covered | Agiliti Inc., McKesson Corporation, GE Healthcare, Med One Group, Stryker Corporation, Siemens Healthineers, Getinge AB, DLL, Koninklijke Philips NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Equipment Leasing Market Shifts & Advancements
Digital lease origination platforms and predictive asset management tools are compressing transaction timelines while reshaping how lessors price residual risk across equipment categories.
Subscription-based equipment access models are displacing traditional fixed-term leases in diagnostic imaging segments. Ambulatory surgical centers in Germany and the United States are adopting per-scan pricing structures tied to actual utilization. This shift transfers technology obsolescence risk entirely to lessors while compressing customer switching costs.
Japan's PMDA has tightened quality management system requirements for refurbished medical devices entering secondary lease markets. Manufacturers must now demonstrate equivalence to original performance specifications through extended clinical validation. European diagnostic networks face parallel compliance burdens under EU MDR Article 14, forcing lessors to expand in-house refurbishment capabilities or exit cross-border portfolios.
Hospital procurement departments are consolidating vendor relationships around integrated equipment-service-consumable bundles. United States health systems increasingly require lessors to assume maintenance, calibration, and disposable supply obligations within single contractual frameworks. This unbundling of traditional OEM service arms compresses margins for pure-play equipment financiers while favoring vertically integrated lessors with captive technical service networks.
Global Healthcare Equipment Leasing Market Segmentation
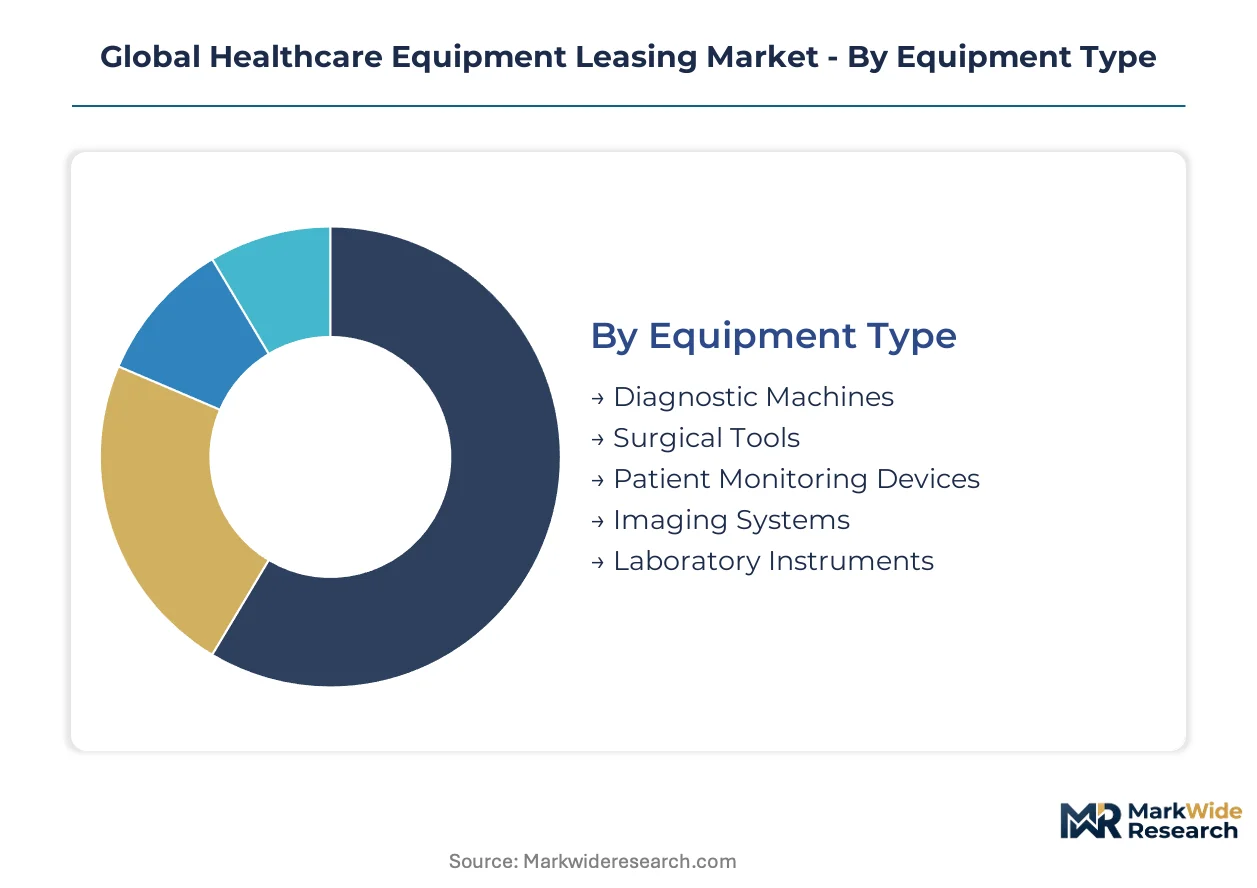
Equipment leasing structures vary sharply across clinical settings and capital intensity levels. Substitution threats from subscription models and pay-per-use arrangements are fragmenting traditional lease categories. Lessors must calibrate residual risk and contract terms to each segment's obsolescence velocity and regulatory exposure.
Equipment Type:
Substitution pressure concentrates in imaging categories where AI-enabled software upgrades extend hardware utility and compress replacement cycles.
- Imaging Systems:MRI and CT modalities dominate lease origination value due to unit costs exceeding two million dollars. United States hospital systems defer capital outlays through structured finance leases tied to CMS reimbursement timelines.
- Diagnostic Machines:Refurbishment protocols under FDA 510(k) pathways enable secondary market redeployment. European diagnostic networks leverage CE marking conformity assessment to extend asset utility across cross-border lease portfolios.
- Surgical Tools:Capital constraints across ambulatory surgical centers accelerate lease adoption for robotic and laparoscopic systems.
- Patient Monitoring Devices:Short technology cycles favor operating lease structures where lessors retain obsolescence risk.
- Laboratory Instruments:Pathology automation and molecular diagnostics drive demand in United States reference laboratory networks.
Imaging Systems retains volume leadership; Diagnostic Machines holds the steepest expansion curve.
Leasing Model:
Cost tier stratification separates premium full-service contracts from stripped-down capital-only arrangements.
- Operating Lease:Lessors retain ownership and depreciation risk while lessees obtain usage rights without balance sheet recognition. Short-cycle technology categories in German diagnostic networks favor this structure for rapid upgrade flexibility.
- Finance Lease:Lessees assume economic ownership with purchase options at term end. Surgical tools and patient monitoring devices align with depreciation schedules matching clinical utility timelines in Japanese hospital procurement.
- Rental:Short-term access without residual value obligations serves surge capacity and temporary facility needs.
- Hire Purchase:Installment structures transfer ownership progressively, common in India's tier-2 hospital construction financing.
- Sale and Leaseback:Liquidity extraction from owned equipment balancesheets dominates United States health system consolidation strategies.
Finance Lease commands the largest transaction value; Operating Lease gains share fastest among ambulatory providers.
End User:
Customer type fragmentation reflects divergent capital access and procurement sophistication across clinical settings.
- Hospitals:Integrated equipment-service-consumable bundles consolidate vendor relationships around single contractual frameworks. United States health systems increasingly require lessors to assume maintenance and calibration obligations.
- Ambulatory Surgical Centers:Capital constraints tighten as reimbursement compression limits traditional equipment procurement. Per-scan pricing structures tied to actual utilization transfer technology obsolescence risk entirely to lessors.
- Diagnostic Centers:Mid-range imaging demand concentrates in India's tier-2 and tier-3 city network expansion.
- Specialty Clinics:Focused service lines require targeted equipment configurations with shorter lease terms.
- Rehabilitation Facilities:Physical therapy and mobility equipment leasing accelerates with aging population demand in Japan.
Hospitals anchor transaction volume; Ambulatory Surgical Centers exhibits the most rapid structural shift toward lease structures.
Application Area:
Margin dispersion across clinical applications tracks reimbursement rate differentials and equipment utilization intensity.
- Radiology:Imaging-intensive workflows generate highest equipment utilization rates and lease payment coverage ratios. Bundled payment models in United States healthcare systems align lease structures with patient throughput metrics.
- Cardiology:Cath lab and electrophysiology systems require specialized maintenance labor with OEM-trained technician scarcity limiting independent lessor servicing capabilities.
- Oncology:Linear accelerator and PET-CT leasing faces extended FDA premarket notification timelines for refurbished device redeployment.
- Orthopedics:Robotic surgical systems and navigation platforms concentrate lease demand in German and United States ambulatory settings.
- Neurology:Specialized diagnostic and interventional equipment serves concentrated academic medical center demand.
Radiology sustains the deepest lease penetration; Cardiology shows the most aggressive expansion in structured finance origination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports refurbished diagnostic equipment to Eastern European clinical networks through CE-marked lease portfolios. Japanese lessors redeploy returned MRI systems across Southeast Asian markets under PMDA-certified refurbishment protocols.
United States
Hospital consolidation drives sale-leaseback transactions as health systems extract liquidity from owned equipment. FDA 510(k) premarket notification requirements govern refurbished device redeployment timelines. Texas Medical Center in Houston anchors diagnostic imaging lease origination for ambulatory surgical center networks.
Germany
Ambulatory surgical centers adopt per-scan pricing structures for CT and MRI modalities. EU Medical Device Regulation Article 14 mandates conformity assessment for refurbished equipment secondary markets. Bavarian diagnostic networks leverage cross-border lease portfolios into Austria and Switzerland.
Japan
Aging hospital infrastructure accelerates replacement demand for high-field MRI systems. PMDA quality management standards extend clinical validation requirements for refurbished device remarketing. Kansai region academic medical centers concentrate lease origination for PET-CT and linear accelerator systems.
India
Tier-2 and Tier-3 city hospital construction generates underpenetrated demand for mid-range imaging equipment. CDSCO device registration rules complicate cross-border redeployment of leased assets from Singapore and Dubai. Maharashtra state diagnostic networks in Mumbai and Pune lead structured finance adoption.
China
Domestic diagnostic network expansion drives demand for leasing structures preserving capital flexibility. SAMR device re-registration requirements impose extended approval timelines on imported refurbished equipment. Yangtze River Delta hospital clusters in Shanghai and Suzhou concentrate premium imaging lease origination.
Global Healthcare Equipment Leasing Market Competitive Landscape
Player mix skews toward diversified healthcare conglomerates with captive finance capabilities. Siemens Healthineers and GE Healthcare anchor European and North American lease origination through embedded sales workflows. Three archetypes dominate: OEM-captive financiers, independent equipment lessors, and distribution-integrated bundlers. Competitive moves concentrate on vertical integration into technical service networks and geographic expansion through cross-border refurbishment certification.
Among OEM-captive financiers, Siemens Healthineers and GE Healthcare exemplify the integrated equipment-service model, embedding lease origination within diagnostic system sales channels. McKesson Corporation occupies a distinct position as a distribution-integrated bundler, leveraging consumable supply density to anchor surgical equipment lease structures. Independent lessors including DLL and Getinge AB sit within the cross-border portfolio tier, managing regulatory compliance burdens across EU MDR and Japan PMDA jurisdictions.
| Leading Market Players |
|---|
| Agiliti Inc. |
| McKesson Corporation |
| GE Healthcare |
| Med One Group |
| Stryker Corporation |
| Siemens Healthineers |
| Getinge AB |
| DLL |
| Koninklijke Philips NV |
| Others |
Supply & Pricing Matrix
High-field MRI manufacturing scale economies in Germany and Japan concentrate production among three OEMs, compressing unit cost floors while elevating refurbishment value recovery across secondary lease markets. This concentration amplifies pricing power for lessors holding certified pre-owned inventory, yet simultaneously exposes margin structures to OEM-controlled spare parts and software licensing terms.
Pricing Analysis
Next-generation AI-enabled imaging platforms command 40-60% lease rate premiums over prior-generation hardware lacking embedded analytics capabilities. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) certification tier and bundled maintenance scope. Pricing pressure stems from ambulatory surgical centers demanding per-scan utilization models that transfer obsolescence risk entirely to lessors. Independent diagnostic centers exhibit highest price sensitivity due to capital constraints and reimbursement compression, while academic medical centers prioritize uptime guarantees over rate minimization.
Supply Chain Analysis
Extended lead times for superconducting magnet components and gradient coil assemblies constrain fleet refresh velocity across North American and European lessor portfolios. Manufacturing concentrates in Germany, Japan, and the United States for high-field diagnostic systems, with refurbishment operations increasingly localized to comply with EU MDR and PMDA quality management standards. Supply chain risk hinges on single-source dependency for helium-3 isotope supplies essential to MRI magnet cooling systems. Distribution runs through OEM-captive finance arms and independent lessor networks serving hospital procurement committees and ambulatory surgical center administrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based equipment access models are disrupting traditional fixed-term lease structures, with FDA premarket notification pathway streamlining for refurbished devices serving as the critical regulatory enabler accelerating this transition.
For Market Incumbents: Compound defensive moats by embedding predictive maintenance software into lease contracts, creating switching costs that neutralize independent lessor price competition. Expand in-house refurbishment certification to EU MDR and Japan PMDA standards, capturing secondary market remarketing margins previously ceded to third-party servicers. Prioritize backward integration into technical labor training pipelines to address OEM-trained technician scarcity constraining independent competitors.
For New Entrants and Emerging Players: FDA 510(k) abbreviated review pathways for refurbished diagnostic equipment enable rapid market entry without full new-device development costs. Target India's tier-2 and tier-3 city diagnostic networks where CDSCO registration complexity has suppressed incumbent penetration. Deploy asset-light partnership models with established refurbishment facilities rather than capital-intensive manufacturing footprints.
For Investors and Strategic Acquirers: Independent lessors with cross-border EU MDR and Japan PMDA certification capabilities represent prime acquisition targets as regulatory barriers consolidate secondary market access. Long-term viability centers on software-enabled service revenue streams decoupled from hardware depreciation cycles. Monitor FDA premarket notification backlog clearance rates as the inflection signal for refurbished equipment velocity acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 14 compliance unlocks cross-border lease portfolio expansion across German and Austrian diagnostic networks. |
| Hospital System Partnership | Integrated equipment-service-consumable bundles consolidate vendor relationships and compress pure-play financier margins. |
| Software Companion Development | AI-enabled diagnostic analytics embedded in leased hardware platforms enable premium per-scan pricing structures. |
| Reimbursement Strategy | CMS bundled payment alignment with lease payment schedules reduces ambulatory surgical center default risk. |
| FD Submission | Streamlined 510(k) pathways for refurbished devices accelerate fleet redeployment and improve lessor utilization rates. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR conformity assessment records, and hospital procurement contract registries preceded structured interviews with biomedical engineering directors, GPO contracts managers, ambulatory surgical center administrators, and OEM lease origination executives. Secondary validation drew from CMS reimbursement datasets, PMDA quality management system filings, and CDSCO device registration archives. Bottom-up lease transaction modeling triangulated against top-down healthcare capital expenditure forecasts across the analysis window.
Variance decomposition across equipment type, leasing model, end user category, and application area segments informed volume and value projections throughout the forecast period. CAGRs were derived from regression analysis against historical replacement cycle data and reimbursement rate trajectories. Industry-specific inputs incorporated FDA premarket notification clearance timelines, EU MDR transition implementation pace, and ambulatory surgical center construction permitting velocity.
Underlying assumptions cover stable reimbursement frameworks and helium supply chain continuity, with deviation risk concentrated in SAMR device re-registration delays and rapid imaging technology obsolescence compressing residual valuations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
Factoring Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market