
 US Auto Loan Market | 2026-2036
US Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
US Auto Loan Market Insights
Auto finance underwriting talent is rotating away from traditional bank branches toward captive lender digital platforms and fintech servicing centers. Toyota Financial Services leverages its dealer floorplan relationships to sustain captive market presence. Ally Financial competes through direct-to-consumer refinancing channels that bypass dealership markups. Santander Consumer Finance specializes in near-prime and subprime structures that incumbent banks often avoid.
US auto loans are secured credit instruments collateralized by vehicle titles, with loan-to-value ratios typically ranging from 80% to 120% depending on borrower credit tier and vehicle condition. Their primary commercial purpose is to convert durable goods purchases into amortizing payment streams that match asset depreciation curves. New car loan originations still occupy the largest share of outstanding balances, though used car financing is accelerating faster as vehicle prices normalize and certified pre-owned programs expand. Subprime and near-prime segments concentrate the highest yield spreads but also carry elevated loss severity when collateral depreciation outpaces principal reduction.
The Consumer Financial Protection Bureau monitors auto lending for disparate impact under fair lending statutes, while the Federal Reserve's interest rate posture directly resets cost of funds across the sector. State usury ceilings and titling regulations fragment compliance obligations across jurisdictions. Stakeholders must weigh the trade-off between automated underwriting speed and manual review depth as regulatory scrutiny intensifies on dealer markup participation and add-on product disclosures.
Market Dynamics
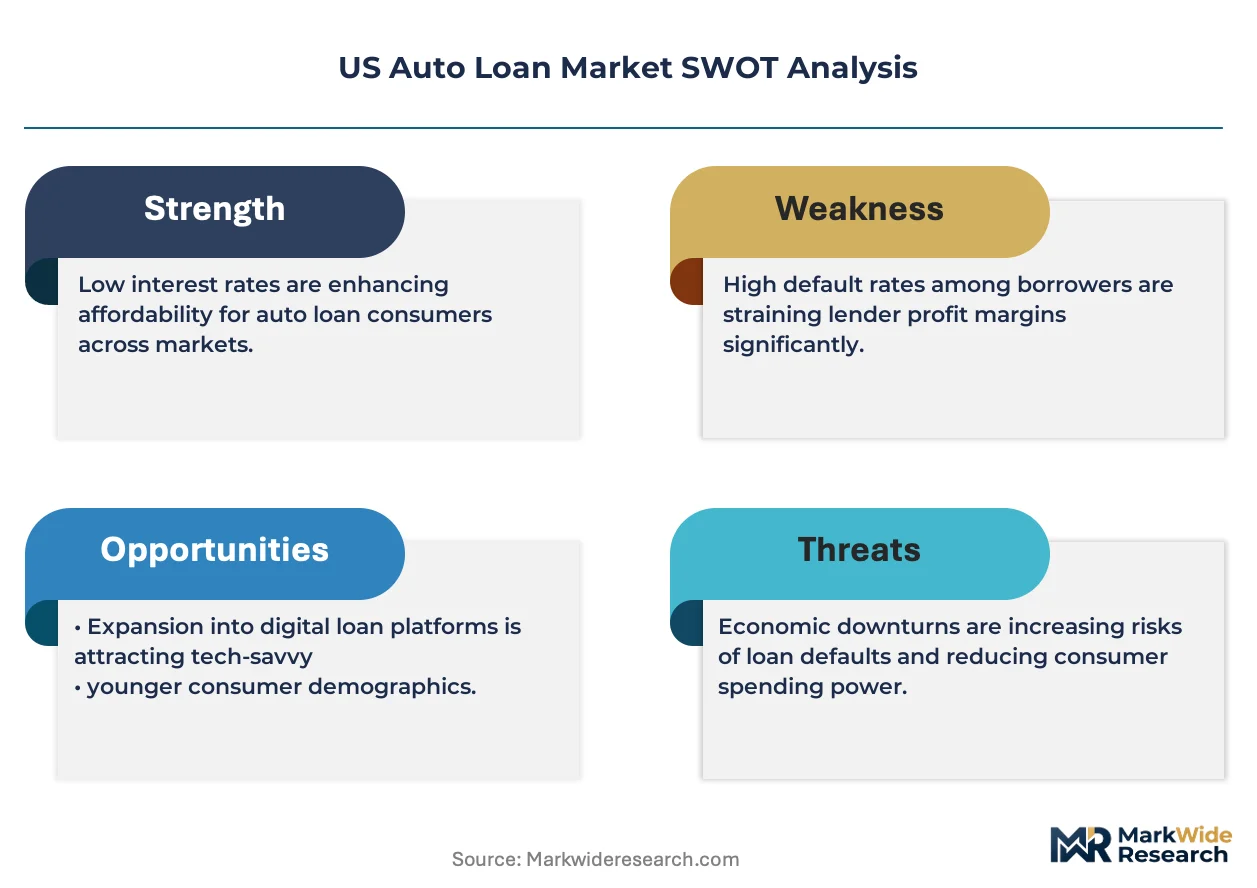
The Consumer Financial Protection Bureau's supervisory authority over dealer markup practices is compressing origination margins and forcing lenders toward direct-to-consumer digital channels.
Growth Catalysts
- Credit Union Expansion:Member-owned institutions are deepening penetration in used vehicle financing, particularly among first-time borrowers previously underserved by traditional bank branches.
- Certified Pre-Owned Programs:Manufacturer-backed CPO inventory is normalizing residual value forecasting, reducing collateral depreciation risk and expanding near-prime lending capacity.
- Texas and Florida Registration Volume:These states anchor national vehicle sales density, with dealership clustering creating concentrated origination opportunities for regional and national lenders alike.
Market Restraints
- Interest Rate Transmission Lag:The Federal Reserve's rate posture resets cost of funds faster than loan portfolios can reprice, squeezing net interest margins across the sector.
- Collateral Depreciation Velocity:Used vehicle price normalization is outpacing principal amortization schedules, elevating loss severity in subprime segments where loan-to-value ratios often exceed 100%.
- State Usury Fragmentation:Jurisdictional variation in rate ceilings and titling regulations fragments compliance infrastructure, raising operational overhead for multi-state originators.
Strategic Opportunities
- California EV Financing:The state's zero-emission vehicle mandates and purchase incentives are creating dedicated lending products for battery-electric and hydrogen fuel-cell collateral.
- Embedded Insurance Integration:Fintech servicing platforms are converging auto loans with usage-based insurance products, capturing incremental fee revenue per origination.
- Refinancing Channel Bypass:Direct-to-consumer platforms are disintermediating dealership markup participation, capturing rate-sensitive borrowers from captive lender portfolios.
Industry Challenges
- Underwriting Talent Migration:Experienced credit analysts are rotating from bank branches toward captive digital platforms and fintech servicing centers, creating capability scarcity at traditional institutions.
- Automated-Manual Review Tension:Regulatory scrutiny on dealer markup participation and add-on product disclosures is forcing lenders to rebuild manual review depth without sacrificing digital origination speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Auto Loan Market |
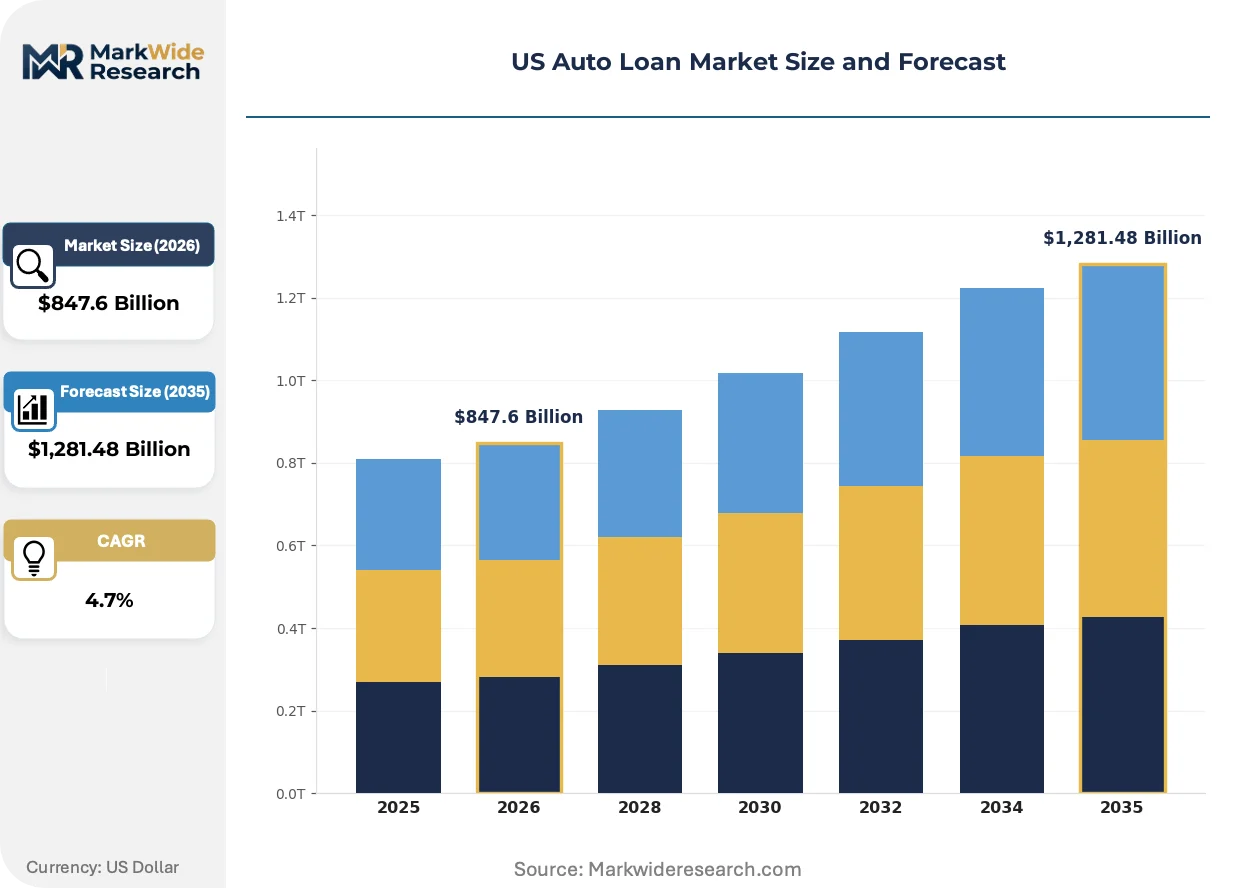
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,281.48 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: New Cars, Used Cars, Refinancing, Leases Customer Type: First-Time Buyers, Repeat Buyers, Business Purchases, Leasing Firms Term Length: 36 Months, 48 Months, 60 Months, 72 Months Credit Score Range: Prime, Subprime, Near-Prime, Super Prime |
| Companies Covered | Toyota Financial Services, General Motors Financial Company, Ford Motor Credit Company, American Honda Finance Corp, Chase Auto, Capital One Auto Finance, Ally Financial, Santander Consumer Finance, Bank of America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Auto Loan Market Trends and Innovations
Digital origination infrastructure is displacing paper-based dealer submission workflows, while regulatory technology investments are reshaping compliance cost structures across the lending stack.
Artificial intelligence-driven income verification is displacing manual paystub review and bank statement analysis in subprime underwriting. Near-prime specialists are adopting these tools fastest, compressing approval timelines from days to hours. This automation is displacing traditional credit bureau dependency and enabling thin-file borrower segmentation previously deemed unprofitable.
The Consumer Financial Protection Bureau's disparate impact enforcement under the Equal Credit Opportunity Act is mandating algorithmic audit trails for automated underwriting decisions. Lenders must now document adverse action reasoning with granularity previously reserved for manual review. Subprime originators with dealer markup participation programs face the steepest compliance reconstruction, with several restructuring compensation structures entirely.
Subscription and flexible ownership models are fragmenting traditional 72-month amortization demand. Fleet management platforms and vehicle-as-a-service providers are capturing urban households previously committed to purchase financing. This behavioral pivot is most visible in California and Texas metropolitan corridors, where parking scarcity and mobility optionality reduce ownership attachment.
US Auto Loan Market Segmentation
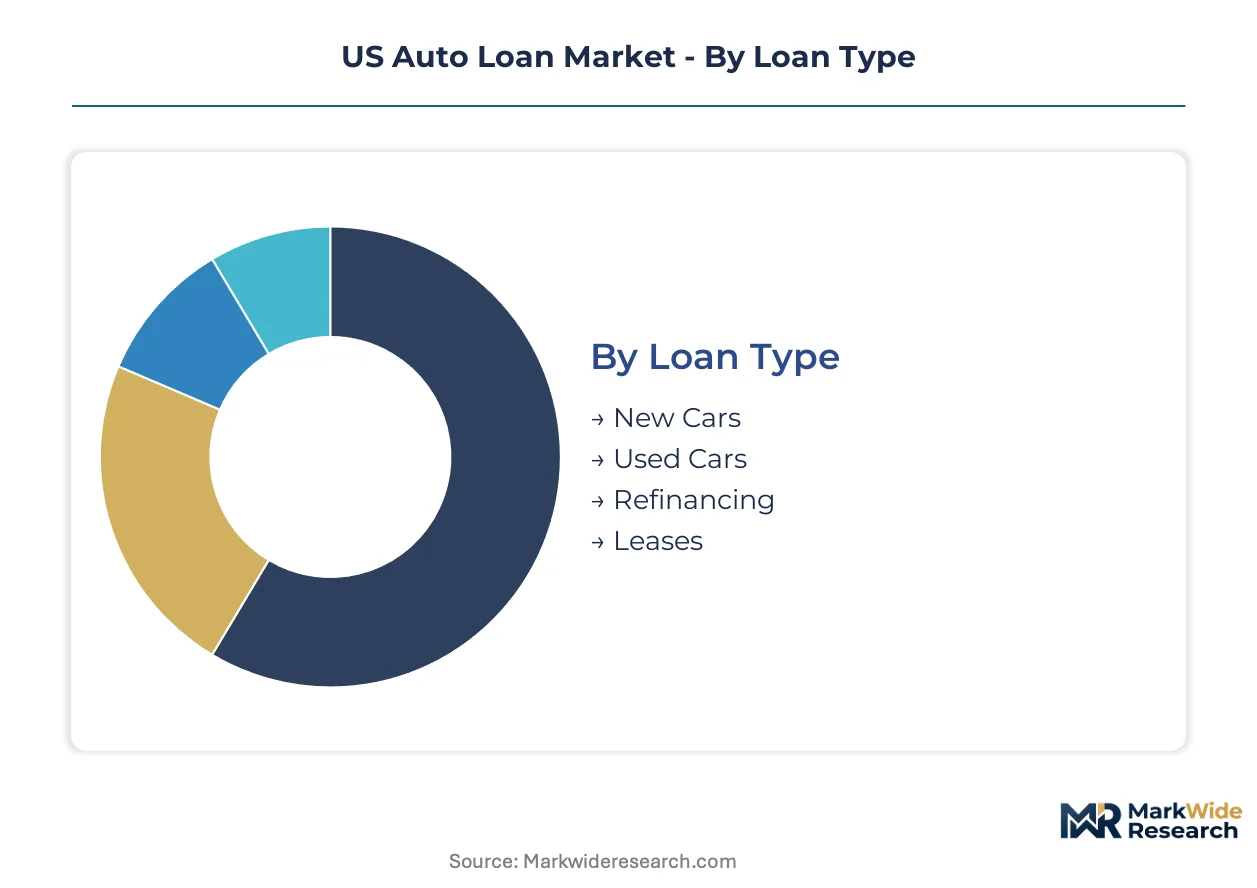
Auto loan segmentation reveals how collateral type, borrower profile, and risk tier reshape origination economics. Lenders configure product structures around depreciation curves and credit bureau stratification.
Loan Type:
New car financing concentrates in captive lender portfolios tied to manufacturer sales incentives, while used vehicle demand spreads across credit unions and independent finance companies.
- New Cars:Factory-backed incentive programs subsidize below-market rates through dealer reserve structures. Texas and California franchise dealerships generate the heaviest origination volume for captive lenders.
- Used Cars:Certified pre-owned inventory commands tighter loan-to-value ratios than independent dealer lots. Credit unions in Florida and Texas are capturing first-time buyer segments previously served by buy-here-pay-here operators.
- Refinancing:Direct-to-consumer platforms bypass dealership markup participation entirely.
- Leases:Residual value guarantees shift depreciation risk to manufacturer captive finance arms.
New car originations hold the largest share; momentum sits with used car financing as vehicle price normalization accelerates.
Customer Type:
First-time buyer penetration determines long-term customer lifetime value for lenders building multi-product relationships.
- First-Time Buyers:Thin credit files require alternative data integration for underwriting approval. Subprime specialists deploy AI-driven income verification to compress decision timelines from days to hours.
- Repeat Buyers:Established payment history enables streamlined refinancing and loyalty rate programs. Captive lenders leverage existing servicing relationships to defend portfolio retention against fintech competitors.
- Business Purchases:Fleet management platforms and commercial vehicle-as-a-service providers are fragmenting traditional amortization demand.
- Leasing Firms:Residual value forecasting expertise separates specialist lessors from balance-sheet lenders.
Repeat buyers generate the largest outstanding balance base; first-time buyers are expanding most quickly as credit union membership deepens.
Term Length:
Amortization schedule selection directly correlates with monthly payment affordability and total interest cost exposure.
- 36 Months:Aggressive principal reduction minimizes negative equity risk but elevates monthly payment burden. Prime and super-prime borrowers in coastal metropolitan markets select this structure to minimize total interest cost.
- 48 Months:Balanced payment-to-equity accumulation suits near-prime credit tiers with stable employment verification.
- 60 Months:Standard manufacturer incentive structures anchor promotional APR offers around this term.
- 72 Months:Extended amortization stretches affordability for subprime segments where loan-to-value ratios often exceed collateral value.
Sixty-month terms hold the largest share; seventy-two-month structures are gaining share fastest as payment sensitivity intensifies.
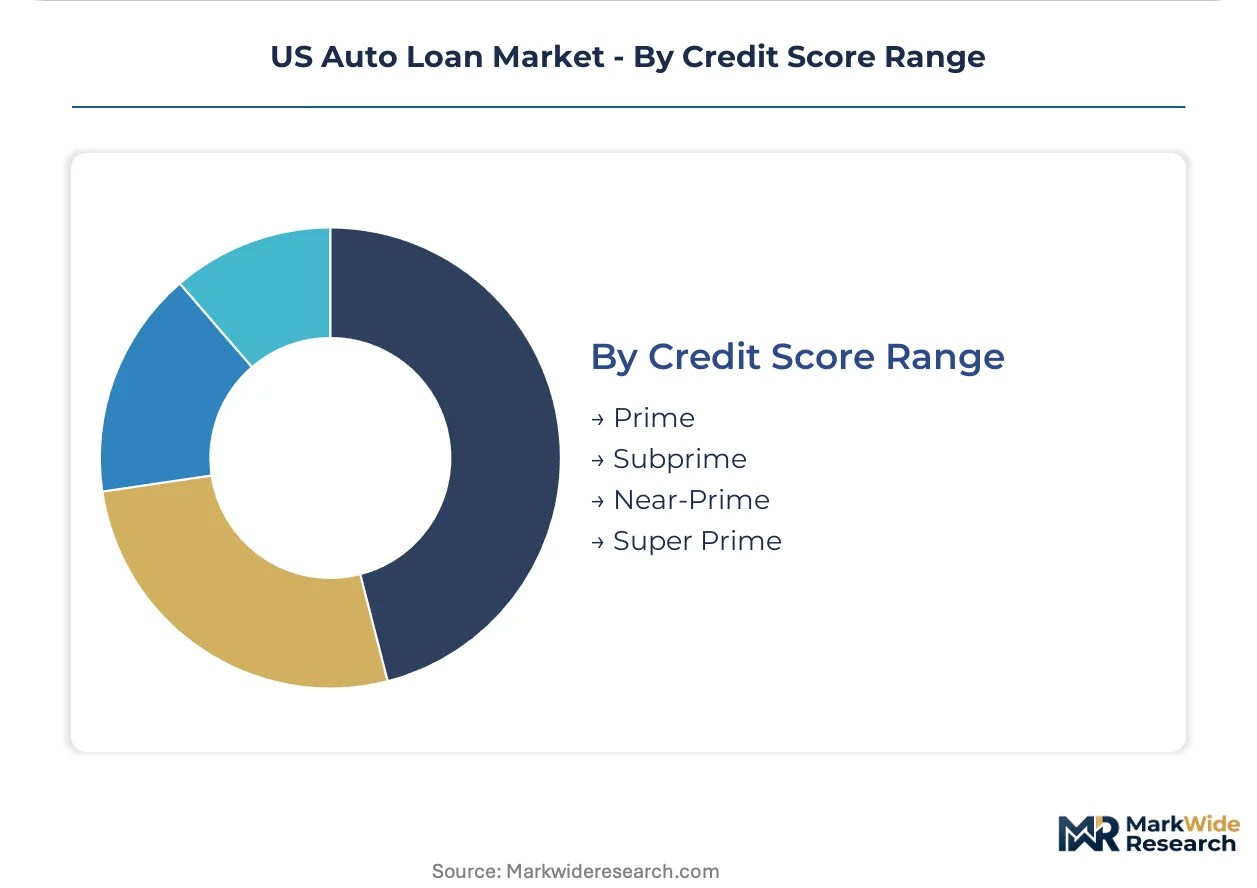
Credit Score Range:
Risk-based pricing stratification determines yield spread and loss severity exposure across the lending stack.
- Prime:FICO scores above 660 qualify for manufacturer-subsidized promotional rates and minimal dealer reserve participation. Regional banks and credit unions compete aggressively on rate in this segment.
- Super Prime:Top-tier borrowers access direct-to-consumer refinancing channels that bypass dealership markup entirely. Fintech platforms target this segment with automated approval workflows and same-day funding.
- Near-Prime:Scores between 620 and 659 require enhanced income verification and stricter loan-to-value limits.
- Subprime:Below-620 scores concentrate in specialty finance companies with dealer markup participation and add-on product attachment.
Prime credit tiers hold the largest share; near-prime segments are climbing the fastest as alternative data expands addressable borrower pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Consumer Financial Protection Bureau anchors federal oversight of auto lending practices nationwide, with state-level variations in usury ceilings and titling regulations creating compliance fragmentation across jurisdictions.
Texas
Vehicle registration volumes and dealership density in Dallas-Fort Worth and Houston generate concentrated origination opportunities for regional and national lenders. The state's Motor Vehicle Division maintains streamlined electronic lien and title systems that accelerate collateral perfection timelines. San Antonio and Austin metropolitan corridors anchor captive lender floorplan relationships tied to franchise dealership networks.
California
Zero-emission vehicle mandates and purchase incentives in Los Angeles and San Francisco Bay Area metros are creating dedicated lending products for battery-electric collateral. The California Department of Financial Protection and Innovation supplements federal CFPB oversight with state-specific disclosure requirements. Southern California's certified pre-owned inventory concentration supports tighter loan-to-value ratio structures for near-prime segments.
Florida
First-time buyer penetration among credit union members in Miami and Tampa markets is displacing traditional buy-here-pay-here operators. The Florida Office of Financial Regulation enforces rate ceiling compliance across multi-state originators operating in the state. Orlando's tourism-driven vehicle fleet turnover sustains used car financing velocity for independent finance companies.
Michigan
Detroit's manufacturer captive finance headquarters anchor promotional APR programs tied to factory incentive structures. The Michigan Department of Insurance and Financial Services coordinates with federal regulators on dealer markup participation examinations. Grand Rapids and Ann Arbor submarkets concentrate prime borrower refinancing activity through direct-to-consumer digital channels.
Ohio
Columbus and Cleveland credit union networks are expanding used vehicle financing membership penetration previously served by bank branches. The Ohio Department of Commerce Division of Financial Institutions monitors compliance with state-specific add-on product disclosure statutes. Cincinnati's dealership clustering supports regional lender participation in floorplan and retail origination programs.
US Auto Loan Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive finance arms of major automakers commanding promotional rate subsidies through dealer reserve structures. Regional banks and credit unions compete on rate in prime segments, while independent finance companies concentrate near-prime and subprime yield spreads. Strategic archetypes include manufacturer-captive lenders, direct-to-consumer refinancing platforms, and specialty subprime servicers. Competitive moves center on digital origination infrastructure deployment and compliance technology investments responding to regulatory scrutiny.
Among manufacturer-captive lenders, Toyota Financial Services and Ford Motor Credit Company exemplify integrated origination and servicing models tied to franchise dealership networks. Ally Financial occupies a position bridging captive and independent finance archetypes through direct-to-consumer refinancing channels. Santander Consumer Finance anchors the specialty subprime tier with structures targeting borrower segments incumbent banks often avoid.
| Leading Market Players |
|---|
| Toyota Financial Services |
| General Motors Financial Company |
| Ford Motor Credit Company |
| American Honda Finance Corp |
| Chase Auto |
| Capital One Auto Finance |
| Ally Financial |
| Santander Consumer Finance |
| Bank of America |
| Others |
Pricing and Supply Chain Analysis
CFPB supervisory authority over dealer markup practices gates both lender qualification and rate differentiation simultaneously, compressing origination margins for multi-state originators while favoring direct-to-consumer platforms with cleaner compliance architectures.
Pricing Analysis
Contract-based long-term offtake structures dominate captive lender portfolios tied to manufacturer incentive programs, while spot-rate refinancing channels serve rate-sensitive prime borrowers. Price differentiation hinges on credit tier stratification and geographic delivery cost variation across state usury jurisdictions. Cost compression in subprime segments is intensifying because collateral depreciation outpaces principal reduction. First-time buyers exhibit highest price sensitivity; super-prime borrowers accessing direct channels show lowest.
Supply Chain Analysis
Floorplan financing concentration in Texas and California dealership clusters creates origination chokepoints where captive lenders anchor promotional rate subsidies. Raw material dependencies include vehicle inventory procurement, residual value forecasting data, and credit bureau scoring infrastructure. Single-source vulnerability sits with dealer markup participation programs facing regulatory restriction. Distribution runs through franchise dealership networks, direct-to-consumer digital platforms, and credit union branch infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital origination infrastructure and AI-driven underwriting are disrupting traditional auto finance, with CFPB algorithmic audit requirements accelerating compliance technology investment as the critical inflection.
For Market Incumbents: Shield prime borrower portfolios from fintech refinancing poaching by embedding loyalty rate programs within existing servicing relationships. Deepen vertical integration into direct-to-consumer digital channels to bypass dealer markup regulatory exposure. Channel control through captive floorplan relationships remains the critical defensive lever against Ally Financial and emerging platforms.
For New Entrants and Emerging Players: Lead with AI-driven income verification tools targeting thin-file first-time buyer segments previously deemed unprofitable by incumbent banks. California EV financing products and Texas used vehicle credit union corridors represent the most penetrable white-space. A go-to-market angle anchored in embedded insurance integration captures incremental fee revenue per origination.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across direct-to-consumer digital platforms as cloud infrastructure displaces branch networks. Long-term viability over the projection horizon favors platforms with algorithmic audit trail capabilities and clean dealer compensation structures. Acquisition targets should profile as near-prime specialists with automated underwriting depth. The signal to watch is CFPB enforcement action frequency on disparate impact claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Origination Platform Deployment | Ally Financial's direct-to-consumer refinancing demonstrates margin capture without dealer markup participation. |
| AI-Driven Underwriting Investment | Santander Consumer Finance compresses subprime approval timelines from days to hours using alternative data integration. |
| Embedded Insurance Integration | Fintech servicing platforms converge auto loans with usage-based products for incremental fee revenue. |
| Credit Union Membership Expansion | Florida and Texas first-time buyer penetration displaces buy-here-pay-here operators through tighter loan-to-value structures. |
| Algorithmic Audit Trail Compliance | CFPB Equal Credit Opportunity Act enforcement mandates documentation granularity previously reserved for manual review. |
Research Methodology
Initial hypotheses were tested against primary input from auto finance underwriting directors, dealership operations managers, credit union lending officers, and regulatory compliance leads and refined through secondary validation against SEC 10-K filings, CFPB supervisory guidance, state regulatory bulletins, and vehicle registration databases. Bottom-up origination volume modeling and top-down macroeconomic triangulation anchored the analytical framework.
Variance-decomposition across the projection horizon isolates interest rate transmission, collateral depreciation velocity, and regulatory enforcement intensity as primary forecast drivers. Segmentation dimensions modeled include loan type, credit score tier, term length, customer profile, and regional origination cluster. CAGRs derive from compounding annual growth assumptions applied to baseline outstanding balance positions, with Federal Reserve posture and used vehicle price indices serving as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained CFPB enforcement intensity or abrupt interest rate regime shifts would require recalibration. Forecasts reflect documented assumptions about dealer markup participation restructuring and digital channel migration pace. Practitioners should keep alternative scenarios live as regulatory scrutiny and fintech platform consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Refinancing Market
Loans and Leasing
E-Scooter Financing Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market