
 Brazil Home Equity Lending Market | 2026-2036
Brazil Home Equity Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Home Equity Lending Market Outlook
Securitization of mortgage-backed receivables is reshaping how Brazilian lenders fund their balance sheets. Banco Bradesco leverages its captive deposit base to originate home equity products at scale across the Southeast. Creditas specializes in digital-first collateral appraisal, shortening time-to-disbursement against residential property. Itaú Unibanco anchors its position through branch-based advisory for high-net-worth clients seeking structured equity releases.
Home equity lending denotes credit extended against the appraised value of residential real estate minus outstanding mortgage obligations, with loan-to-value ratios typically capped by central bank prudential limits to contain systemic risk. The instrument serves primarily as a lower-cost funding alternative to unsecured consumer credit, channeling property wealth into consumption, investment, or liability management. Fixed-rate loans currently dominate origination volumes among product types, reflecting borrower preference for payment predictability amid Selic rate volatility. Online platforms represent the fastest-expanding lending model, though traditional banking retains the dominant share of total credit disbursed and the deepest integration with property registry systems.
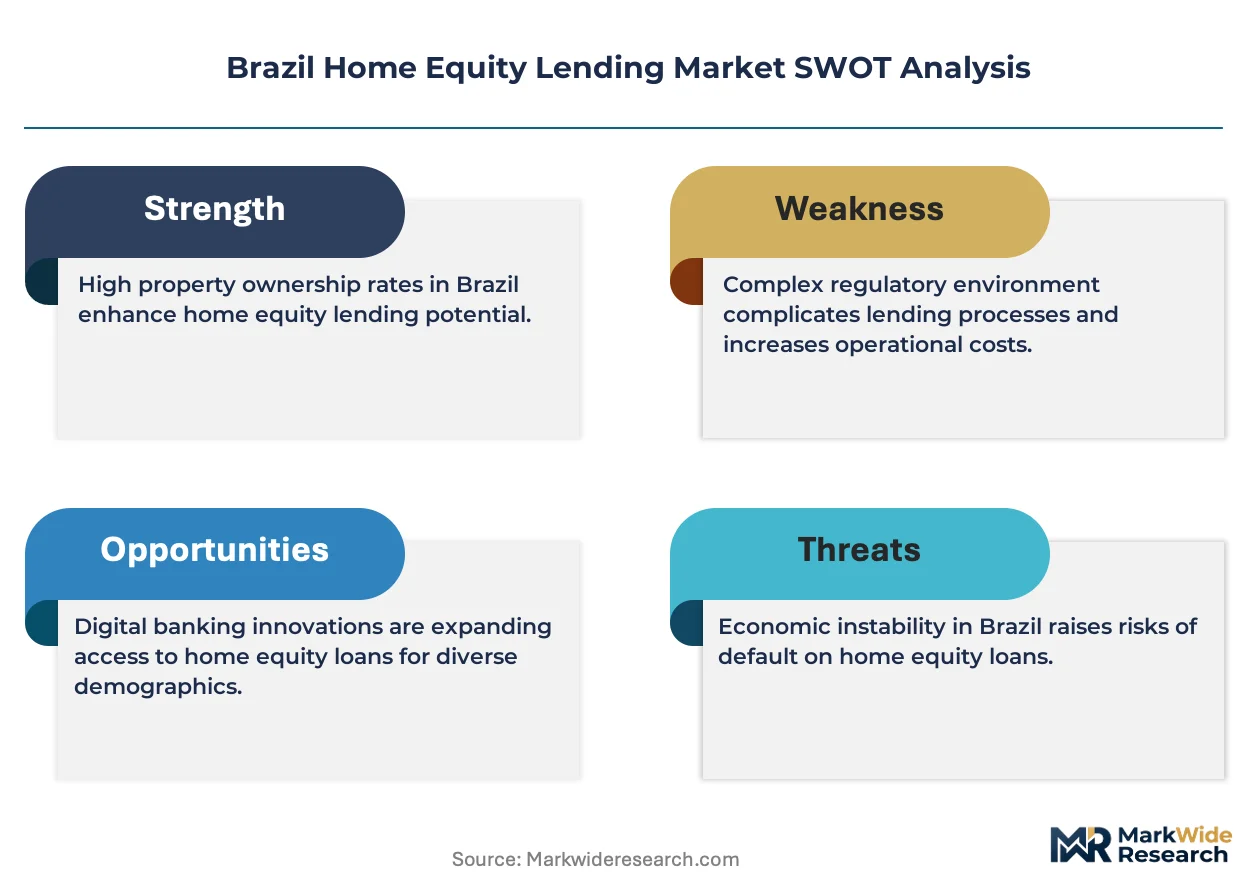
Banco Central do Brasil governs loan-to-value thresholds and capital reserve requirements for mortgage credit, while ANVISA-aligned consumer protection standards mandate transparent disclosure of total effective cost to borrowers. The country's national securities regulator oversees securitization structures that fund originators, linking capital market access to portfolio performance. Stakeholders must monitor how open banking data sharing and instant payment infrastructure alter credit scoring precision and collateral monitoring costs.
Market Dynamics
Open banking integration is compressing underwriting timelines from weeks to days, forcing traditional lenders to rebuild their collateral appraisal workflows around real-time property data feeds and instant payment rails.
Growth Catalysts
- Pix instant payment infrastructure:Real-time settlement capabilities reduce disbursement friction for home equity borrowers, accelerating capital deployment into renovation and debt consolidation use cases.
- São Paulo property valuation premiums:Concentrated wealth effects in Brazil's largest state generate refinancing velocity that outperforms national benchmarks, pulling originators toward Southeast branch networks.
- ANVISA-aligned disclosure mandates:Standardized total effective cost presentations reduce borrower search costs and compress price dispersion across competing lenders.
Market Restraints
- Selic rate volatility:Central bank monetary policy swings compress net interest margins for fixed-rate originators and complicate hedging strategies.
- Property registry fragmentation:Municipal cartório systems across Brazil's 5,570 municipalities create title verification delays and collateral perfection risks.
- Unsecured credit substitution:Payroll-deductible consignado loans compete for the same household liability management demand with faster approval workflows.
Strategic Opportunities
- Northeast urban corridors:Recife and Salvador metropolitan areas show rising property valuations with limited incumbent lender penetration.
- Securitization channel deepening:FIDC structures open institutional capital access for non-bank originators seeking balance sheet relief.
- API-driven appraisal convergence:Integration of satellite imagery with registry databases collapses collateral verification costs for digital-first platforms.
Industry Challenges
- Data science talent scarcity:Open banking scoring model development requires specialized quantitative risk professionals in short supply domestically.
- Legacy core banking integration:Incumbent institutions face middleware complexity connecting instant payment rails to decades-old loan servicing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Home Equity Lending Market |
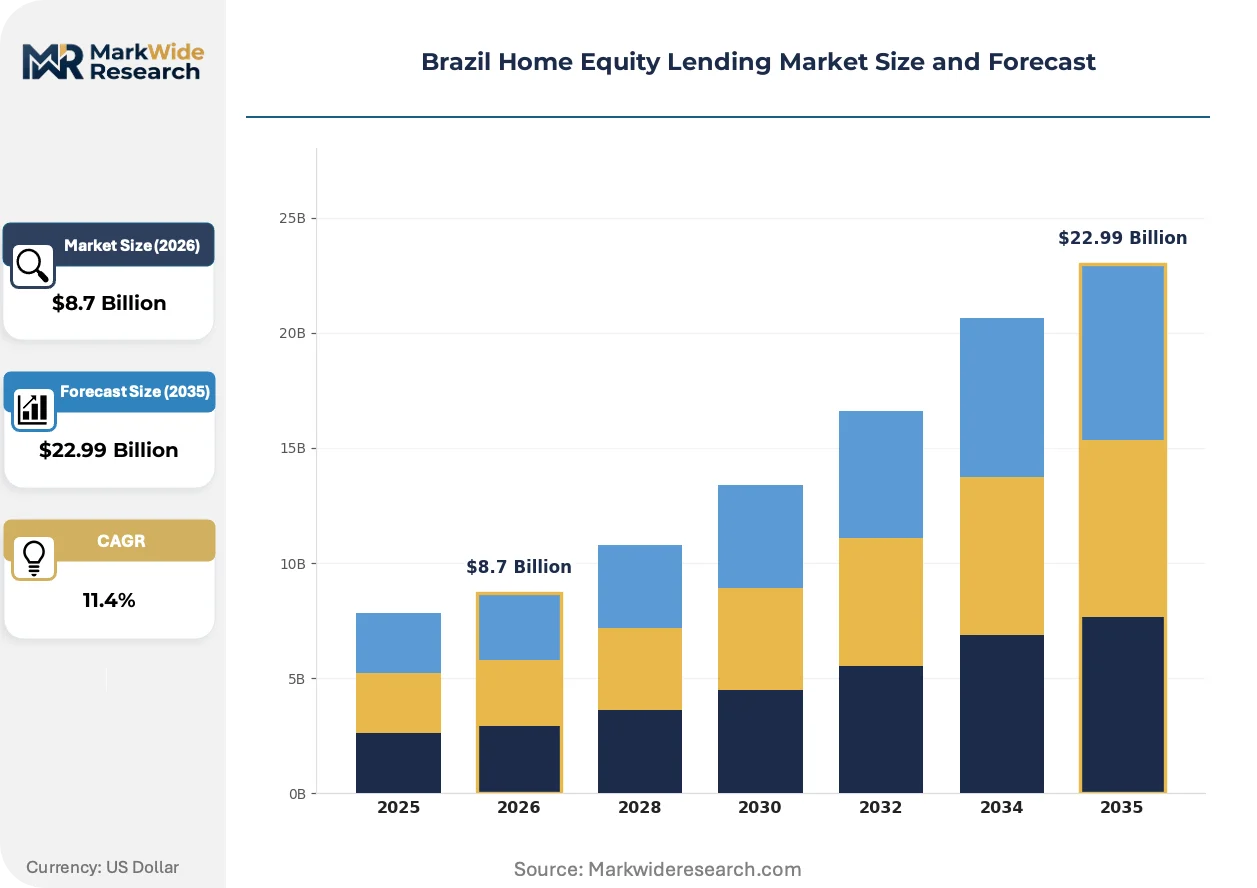
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Rate Loans, Adjustable-Rate Loans, Home Equity Lines of Credit, Second Mortgages Client Type: Individual Homeowners, Investors, Real Estate Developers, Financial Institutions Purpose: Debt Consolidation, Home Improvements, Education Funding, Business Investment Lending Model: Direct Lending, Peer-to-Peer, Online Platforms, Traditional Banking |
| Companies Covered | Banco Bradesco, NuBank, Caixa Econômica Federal, FinanZero, Creditas, Banco do Brasil, Banco Santander Brasil, Nomad, Itaú Unibanco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Home Equity Lending Market Strategic Shifts
Digital collateral verification and automated income assessment are compressing traditional branch-based origination models, while regulatory pressure on transparency accelerates standardization of pricing disclosure across distribution channels.
Automated valuation models fed by municipal tax records and satellite imagery are collapsing the cost structure of residential appraisal. Digital lenders deploy these tools to underwrite home equity lines within 48 hours, a timeline that brick-and-mortar competitors struggle to match without workflow overhaul. The compression of appraisal expenses is enabling smaller-ticket originations that were previously uneconomical to process.
Banco Central do Brasil's open banking framework mandates standardized data sharing across financial institutions, creating interoperability obligations that reshape credit scoring architectures. Lenders now ingest transaction histories, payroll data, and tax filings through regulated APIs, reducing reliance on self-reported income. The regulatory push most acutely affects mid-tier banks that lack captive data ecosystems and must build external data integration capabilities.
Borrower preference is migrating toward self-service digital origination with transparent rate comparison tools, displacing branch-based advisory relationships for standardized home equity products. Online aggregators and fintech platforms capture this demand rotation, while traditional institutions reconfigure their physical networks toward complex structured equity releases for high-net-worth segments. São Paulo and Rio de Janeiro metropolitan areas exhibit the fastest channel shift velocity, reflecting higher smartphone penetration and digital literacy baselines.
Brazil Home Equity Lending Market Segmentation
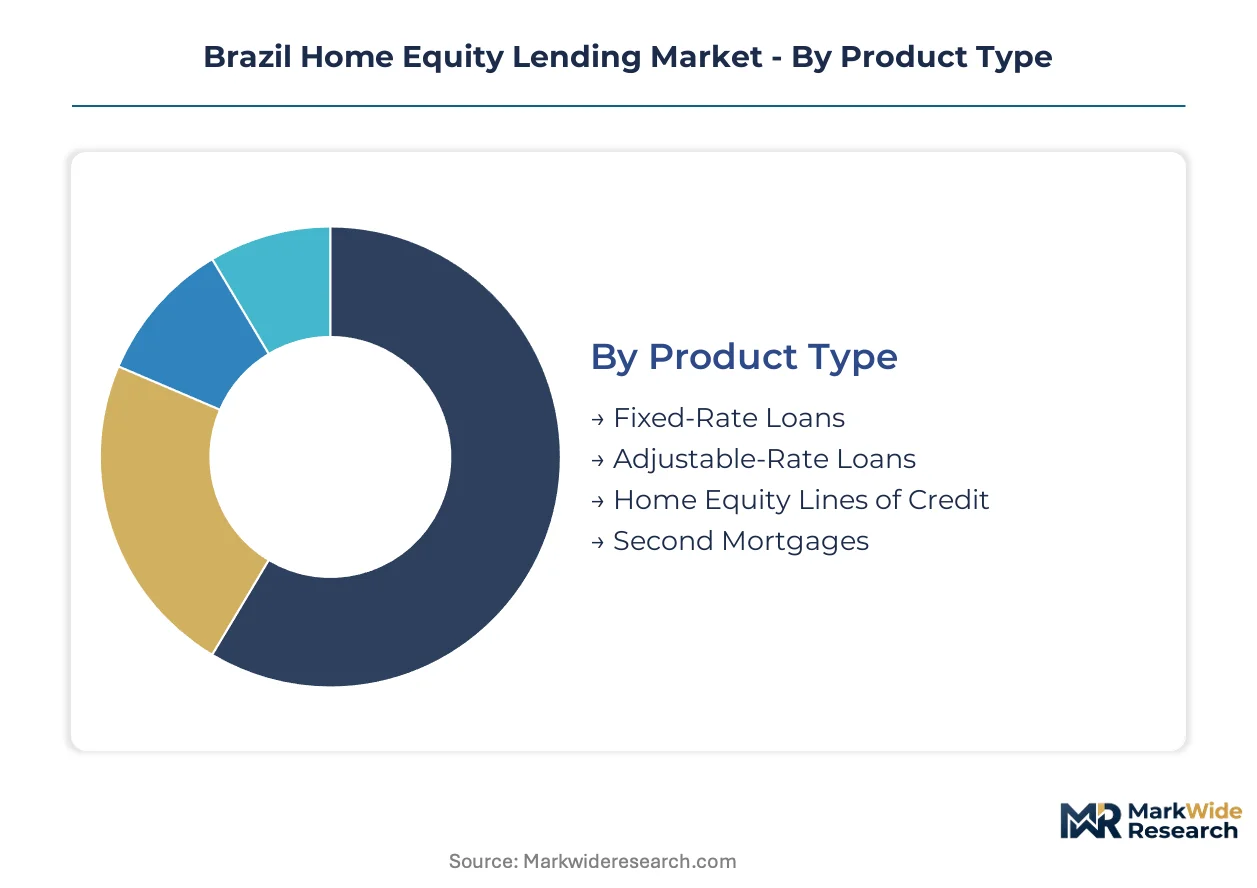
Segmentation reveals how collateralized property credit fragments across borrower profiles and origination channels. Each dimension carries distinct risk-return characteristics and regulatory treatment under Banco Central do Brasil prudential limits.
Product Type:
Cycle times vary sharply: fixed-rate products lock pricing for extended durations while revolving facilities turn over continuously as borrowers draw and repay.
- Fixed-Rate Loans:Interest rates remain constant throughout the loan term, shielding borrowers from Selic volatility. Demand concentrates among São Paulo state homeowners seeking payment predictability for renovation projects amid monetary policy swings.
- Home Equity Lines of Credit:Revolving facilities allow repeated drawdowns against appraised property value without reapplication. Digital lenders in Southeast metropolitan areas deploy automated valuation models to compress approval timelines for these flexible structures.
- Adjustable-Rate Loans:Pricing floats with benchmark indices, transferring rate risk to borrowers.
- Second Mortgages:Subordinate liens behind existing mortgage obligations carry elevated collateral perfection complexity.
Fixed-Rate Loans dominate installed base. Home Equity Lines of Credit is where expansion concentrates.
Client Type:
Cost tiers separate retail originations from institutional relationships, with wholesale pricing available to balance-sheet-heavy counterparties.
- Individual Homeowners:Retail borrowers accessing property wealth for consumption smoothing or liability management. Applications cluster in Rio de Janeiro and São Paulo metropolitan corridors where property valuations support meaningful equity extraction.
- Real Estate Developers:Professional counterparties deploying residential equity as construction financing bridge capital. ANVISA-aligned disclosure mandates apply differently to commercial entities with in-house legal capacity.
- Investors:Portfolio holders seeking leverage against rental property portfolios.
- Financial Institutions:Banks and insurers optimizing capital structure through collateralized funding.
Individual Homeowners anchor volume throughput. Real Estate Developers is where margin expansion concentrates.
Purpose:
Application-driven origination patterns show debt consolidation moving fastest while business investment carries elongated due diligence cycles.
- Debt Consolidation:Borrowers replacing high-cost unsecured obligations with lower-rate property-secured credit. Pix instant payment infrastructure accelerates disbursement velocity for this use case across Southeast branch networks.
- Home Improvements:Renovation financing captures property value appreciation directly. Municipal permit data integration through open banking APIs streamlines collateral verification for construction-phase drawdowns.
- Education Funding:Tuition payment schedules align with longer amortization profiles.
- Business Investment:Entrepreneurial equity extraction for working capital or equipment acquisition.
Debt Consolidation dominates application volume. Home Improvements is where digital origination investment concentrates.
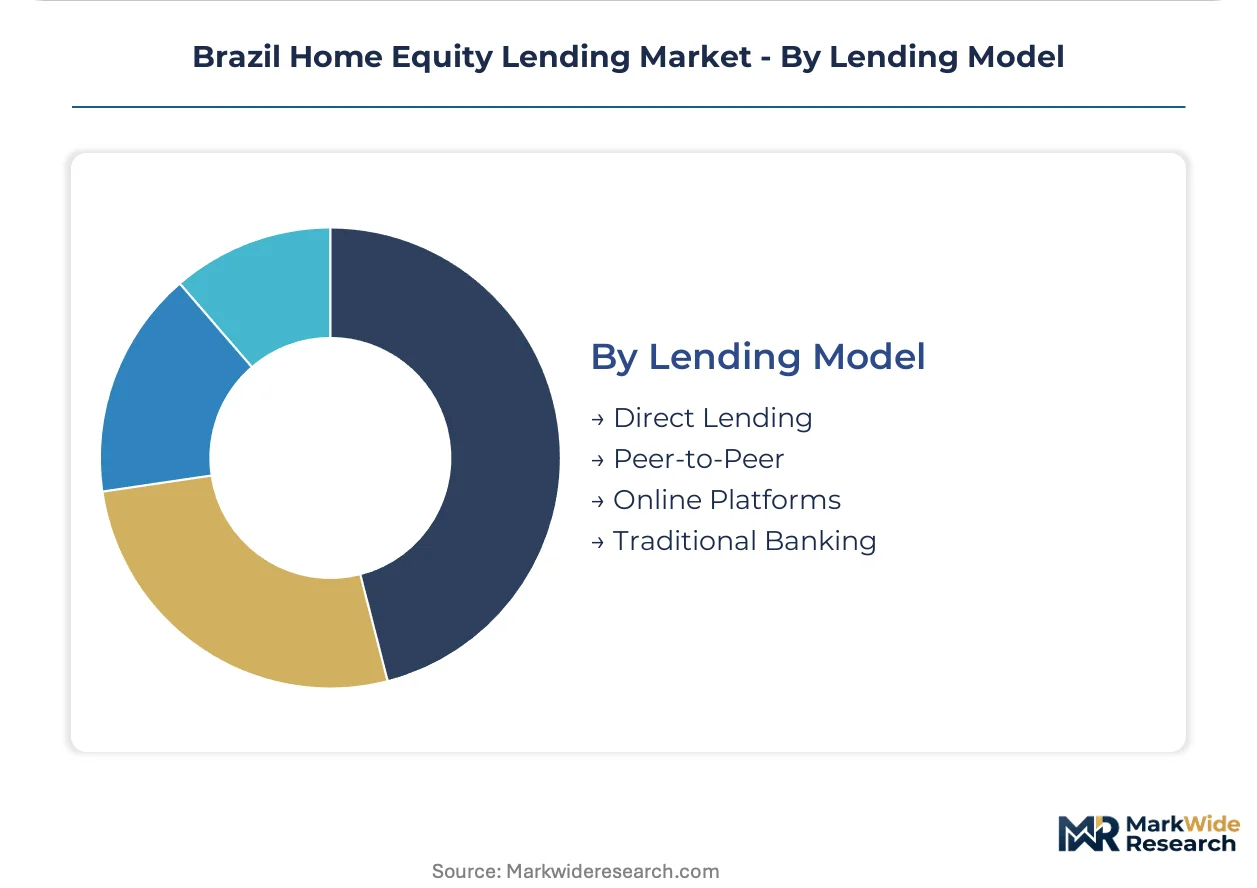
Lending Model:
Volume distribution favors established deposit-taking institutions while customer acquisition costs are climbing fastest at digital entry points.
- Traditional Banking:Branch-based origination leveraging captive deposit bases and deep cartório relationships. Itaú Unibanco and Banco Bradesco anchor this channel with integrated property registry access across Southeast states.
- Online Platforms:Digital-first workflows collapsing appraisal and underwriting timelines through satellite imagery and API-driven income verification. Creditas exemplifies this model with 48-hour disbursement benchmarks.
- Direct Lending:Non-bank originators funding through securitization rather than deposits.
- Peer-to-Peer:Marketplace structures matching retail investors with property-secured borrowers.
Traditional Banking dominates credit outstanding. Online Platforms is where capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo homeowners deploy equity extraction primarily for debt consolidation and renovation, while Rio de Janeiro borrowers concentrate liquidity releases on entrepreneurial investment. Northeast corridors exhibit faster digital adoption velocity than national benchmarks despite lower average ticket sizes.
São Paulo
Metropolitan São Paulo generates refinancing velocity exceeding national averages through concentrated property valuation premiums. Banco Central do Brasil prudential limits on loan-to-value ratios bind most tightly here given elevated collateral values. The ABC Paulista industrial corridor anchors branch network density for traditional deposit-taking institutions.
Rio de Janeiro
Rio de Janeiro state borrowers channel equity releases toward small business working capital at higher rates than renovation financing. ANVISA-aligned disclosure mandates standardize total effective cost presentations across cartório jurisdictions. The Baixada Fluminense sub-region exhibits rising digital platform penetration for mid-ticket originations.
Minas Gerais
Belo Horizonte metropolitan homeowners favor fixed-rate structures amid Selic volatility exposure in this mining-dependent economy. Open banking API integration accelerates income verification for public sector employees concentrated in the state capital. The Triângulo Mineiro corridor shows emerging demand for agribusiness-linked equity products.
Rio Grande do Sul
Southern Brazil exhibits higher branch banking loyalty than Southeast metros, slowing digital platform migration. Pix instant payment infrastructure reduces disbursement friction for debt consolidation use cases across Porto Alegre metropolitan networks. Serra Gaúcha manufacturing clusters generate self-employed borrower segments with complex income documentation requirements.
Bahia
Salvador metropolitan property valuations rise faster than Northeast regional averages, attracting non-bank originator expansion. Municipal cartório digitization lags Southeast standards, extending collateral perfection timelines. The Recife-Salvador coastal corridor concentrates fintech customer acquisition investment for first-time equity borrowers.
Brazil Home Equity Lending Market Competitive Environment
Capability concentration sits with deposit-rich incumbents possessing deep cartório relationships; scale advantage sits with digital platforms with compressed underwriting timelines. The market structures around three archetypes: traditional branch networks with captive funding, digital-first originators with API-driven appraisal, and marketplace aggregators matching borrowers to multiple capital sources. Competitive moves concentrate on securitization channel deepening and instant payment rail integration.
Among established banking networks, Banco Bradesco and Itaú Unibanco anchor the incumbent tier with integrated property registry access across Southeast states. Creditas occupies a position exemplifying the digital-native archetype, collapsing appraisal and disbursement timelines through automated valuation models. NuBank represents the platform-scale entrant leveraging existing customer bases for cross-sell origination.
| Leading Market Players |
|---|
| Banco Bradesco |
| NuBank |
| Caixa Econômica Federal |
| FinanZero |
| Creditas |
| Banco do Brasil |
| Banco Santander Brasil |
| Nomad |
| Itaú Unibanco |
| Others |
Value Chain & Pricing Dynamics
Selic rate volatility functions as the dominant risk vector shaping both pricing tier compression and supply chain configuration across Brazilian home equity lending. Central bank monetary policy swings force originators to widen spreads between fixed-rate and adjustable-rate products while simultaneously driving consolidation of funding sources toward deposit-rich incumbents with captive liquidity buffers.
Pricing Analysis
Long-term fixed-rate contracts dominate origination volumes, with borrowers locking payment predictability amid benchmark rate uncertainty. Price differentiation rests on loan-to-value ratios and borrower credit tier, with ANVISA-aligned disclosure mandates compressing opacity premiums previously captured by branch-based advisors. Pricing pressure intensifies in the revolving credit segment as digital platforms undercut traditional appraisal cost structures. Individual homeowners in São Paulo state exhibit lowest price sensitivity given property valuation premiums, while Northeast corridor borrowers drive hardest bargain hunting.
Supply Chain Analysis
Upstream funding draws from three concentrated sources: captive retail deposit bases at Itaú Unibanco and Banco Bradesco, securitization channels through FIDC structures tapping institutional capital, and fintech balance sheets backed by venture equity. Raw material dependencies include real-time property registry data from municipal cartórios, satellite imagery feeds for automated valuation models, and open banking API infrastructure for income verification. Single-source vulnerability concentrates in cartório digitization lags across Brazil's 5,570 municipalities. Distribution runs through hybrid architectures combining instant payment rails with legacy loan servicing platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in digital origination workflows as borrower preference rotates toward self-service channels, creating niche entry points for specialized platforms outside incumbent branch networks.
For Market Incumbents: Entrench branch network advantages through deeper cartório digitization partnerships and API-driven collateral verification integration. Threat substitution from Creditas-style 48-hour disbursement benchmarks demands workflow compression investments. Priority lever sits in instant payment rail integration with legacy core banking systems to match fintech settlement velocity. For New Entrants and Emerging Players: Establish a beachhead in Salvador and Recife metropolitan corridors where property valuations rise faster than incumbent penetration. Northeast urban corridors offer limited competition from deposit-rich banks. Go-to-market angle centers on municipal permit data integration for construction-phase home improvement drawdowns. For Investors and Strategic Acquirers: API-driven appraisal specialists with satellite imagery capabilities and open banking scoring architectures represent the target acquisition archetype. Long-term viability hinges on regulatory alignment with Banco Central do Brasil prudential frameworks. Signal to watch: FIDC securitization volume inflection indicating institutional capital appetite for non-bank originator paper.| Strategic Initiative | Industry Significance |
|---|---|
| Instant Payment Rail Integration | Pix infrastructure adoption reduces disbursement friction against unsecured credit alternatives. |
| Automated Valuation Model Deployment | Satellite imagery compression of appraisal timelines enables smaller-ticket originations previously uneconomical. |
| Cartório Digitization Partnership | Municipal registry modernization collapses collateral perfection delays in high-velocity markets. |
| FIDC Securitization Channel Deepening | Institutional capital access provides balance sheet relief for digital-first originators scaling operations. |
| Open Banking API Integration | Real-time income verification through regulated data sharing reduces reliance on self-reported borrower disclosures. |
Study Parameters
Initial hypotheses were tested against primary input from chief lending officers at deposit-taking institutions, digital platform risk executives, municipal cartório administrators, and securitization structurers, then refined against secondary validation from Banco Central do Brasil regulatory filings, ANVISA disclosure standard documentation, FIDC issuance prospectuses, and property registry transaction records. Bottom-up origination volume triangulation with top-down credit outstanding estimates anchored market sizing.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled encompass product type, client archetype, application purpose, and lending channel. CAGRs derived from regression analysis against Selic rate trajectories, property valuation indices, and digital adoption curves. Industry-specific forecast inputs included open banking API penetration rates and cartório digitization milestones.
Stress conditions across benchmark rate volatility bands, collateral perfection timeline extensions, and unsecured credit substitution thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory continuity and payment infrastructure stability. Material shifts in Banco Central do Brasil prudential limits or Pix operational reliability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
China Home Loan Market