
 US Mortgage/Loan Brokers Market | 2026-2036
US Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
US Mortgage/Loan Brokers Market Insights
The Nationwide Multistate Licensing System certification cycle is unwinding broker participation, filtering out undercapitalized operators. United Wholesale Mortgage leverages its wholesale-only model to sustain volume through correspondent partnerships. Rocket Mortgage dominates direct-to-consumer digital origination, while CrossCountry Mortgage anchors its position through distributed retail branch networks.
Mortgage and loan brokers function as intermediaries connecting borrowers with capital sources, earning origination fees and yield spread premiums while managing documentation, underwriting coordination, and closing logistics. Purchase loans command the largest service type share as housing turnover recovers, while online platforms within the technology segment attract the fastest growth by compressing application-to-close timelines. Fixed-rate mortgages maintain structural dominance in the loan type category as borrowers seek payment certainty against rate volatility.
The Consumer Financial Protection Bureau enforces disclosure standards through TILA-RESPA integrated disclosures, while state banking regulators overlay licensing requirements that vary by jurisdiction. FHA and VA program guidelines administered through HUD and the Department of Veterans Affairs shape product availability for government-backed segments. Stakeholders must monitor how GSE policy revisions and Basel III endgame capital rules reshape correspondent channel economics and broker compensation structures.
Market Dynamics
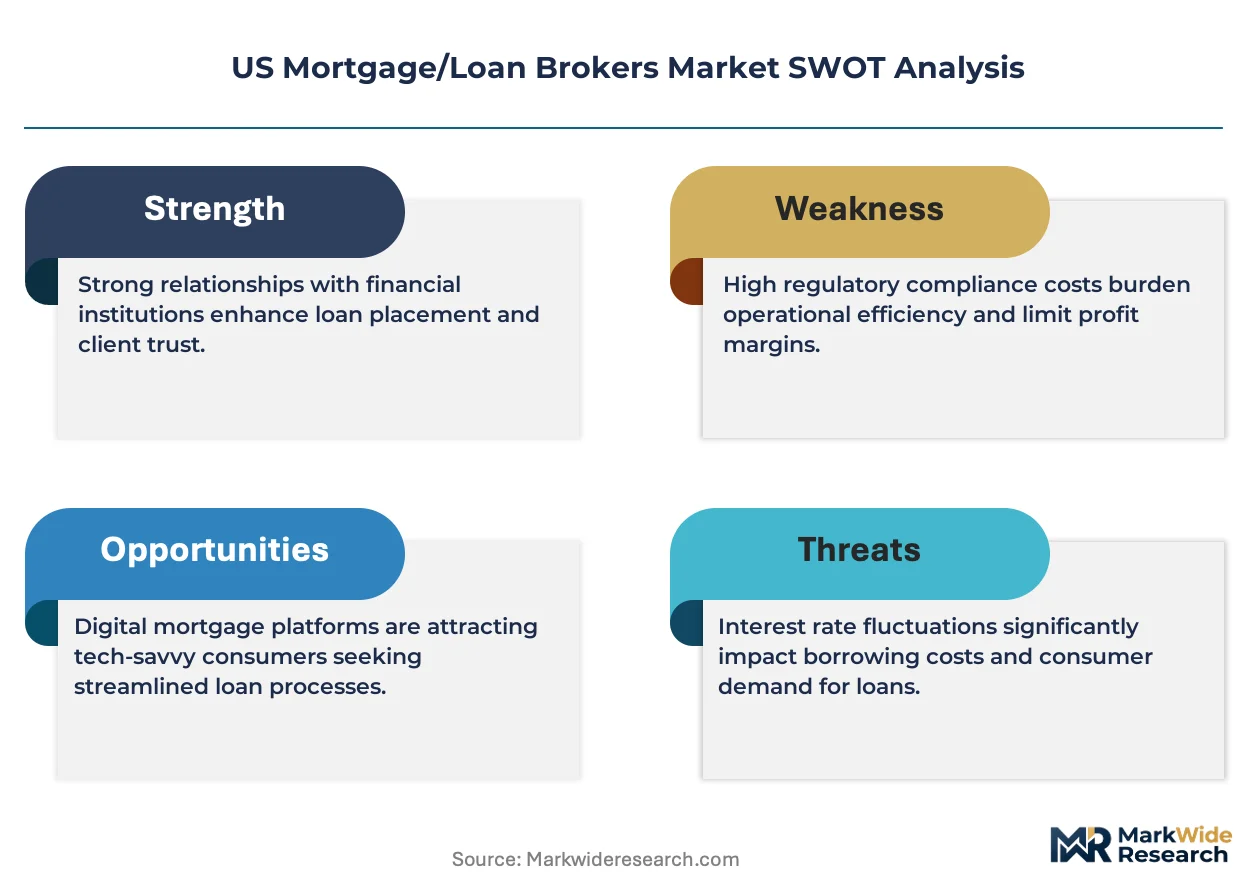
The Nationwide Multistate Licensing System recertification cycle is compressing broker participation, forcing capital-light operators to exit while concentrating volume among scaled wholesalers and retail networks with compliance infrastructure.
Growth Catalysts
- Sun Belt Migration:Population inflows into Texas, Florida, and Arizona are elevating purchase loan origination volumes, with brokers capturing referral networks from relocating buyers seeking local market expertise.
- FHA Program Expansion:HUD guideline modifications for first-time buyer down-payment assistance are expanding broker-accessible product menus, particularly for credit-impaired borrowers locked out of conventional channels.
- API-First Origination Stacks:Automated income verification and asset aggregation tools are collapsing application-to-close timelines, allowing brokers to compete with direct lenders on speed while retaining advisory relationships.
Market Restraints
- NMLS Compliance Burden:The Secure and Fair Enforcement for Mortgage Licensing Act mandates state-by-state licensing renewals with continuing education requirements, creating fixed cost barriers for small operators.
- Yield Spread Compression:GSE pricing adjustments and correspondent channel margin compression are squeezing broker compensation pools, particularly for conforming loan products where rate transparency has commoditized shopping.
- Capital Markets Volatility:MBS spread widening and warehouse line capacity constraints at regional banks are interrupting broker liquidity, forcing reliance on a shrinking pool of national warehouse lenders.
Strategic Opportunities
- Non-QM Product Development:Bank statement loans and DSCR products for self-employed borrowers represent underserved segments where broker expertise in documentation packaging commands premium pricing.
- HELOC Origination Integration:Rising homeowner equity positions are creating cross-sell opportunities, with brokers embedding home equity access into purchase and refinance workflows.
- State-Level First-Time Buyer Incentives:Down-payment assistance programs in California, New York, and Illinois are generating broker referral volume from housing finance agencies seeking origination partners.
Industry Challenges
- Loan Officer Recruitment and Retention:NMLS-licensed originators command premium compensation packages, with turnover accelerating as retail lenders and fintech platforms poach experienced producers with equity incentives.
- TILA-RESPA Disclosure Precision:The Consumer Financial Protection Bureau's enforcement of integrated disclosure timing and accuracy is elevating E&O exposure, requiring technology investments to prevent cure cost erosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mortgage/Loan Brokers Market |
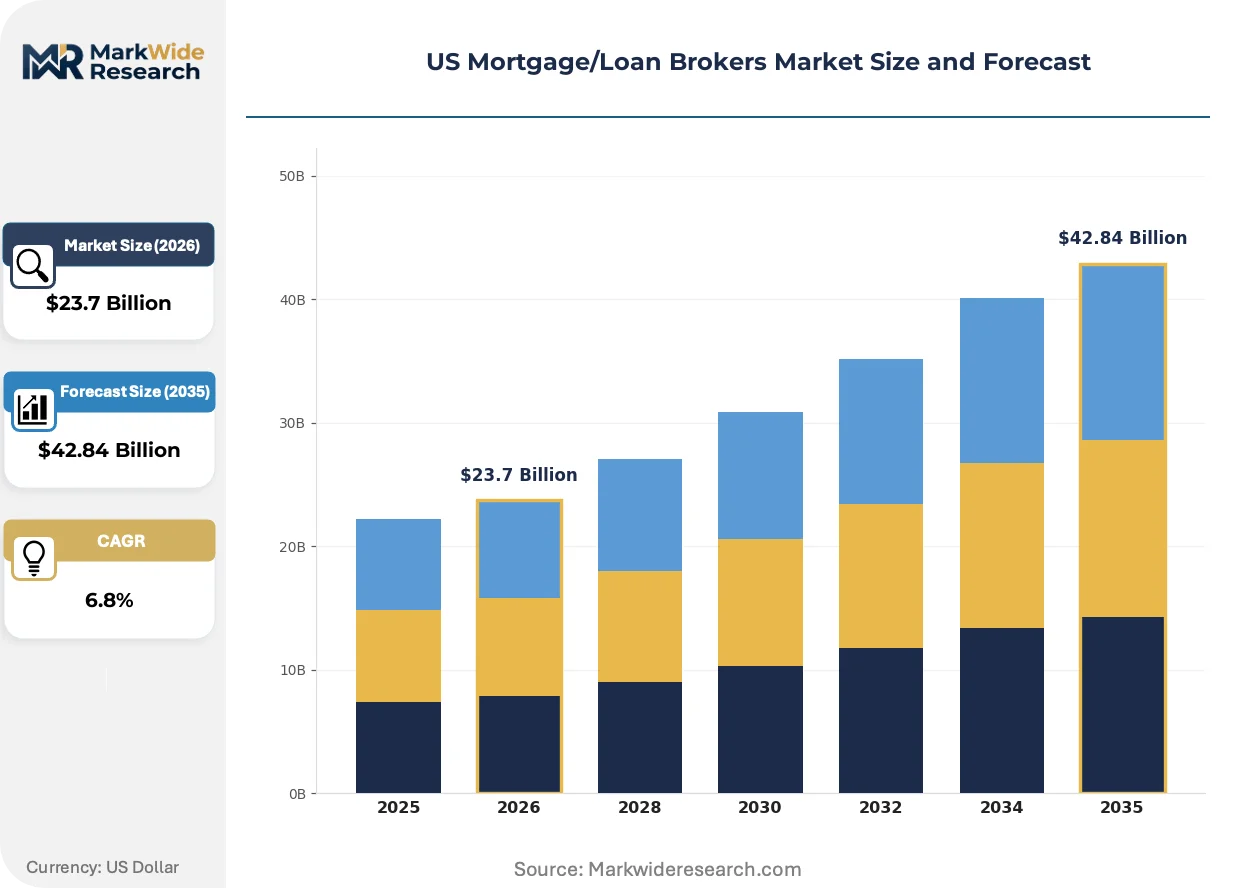
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Purchase Loans, Refinance Loans, Home Equity Lines, FHA Loans Client Type: First-Time Buyers, Investors, Refinancers, Upgraders Loan Type: Fixed-Rate Mortgages, Adjustable-Rate Mortgages, Interest-Only Loans, VA Loans Technology: Online Platforms, Mobile Applications, Mortgage Calculators, CRM Software |
| Companies Covered | United Wholesale Mortgage, Rocket Mortgage, CrossCountry Mortgage, Fairway Independent Mortgage Corporation, Guaranteed Rate, Guild Mortgage Company, LoanDepot, Caliber Home Loans, Lendingtree, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mortgage/Loan Brokers Market Trends and Innovations
Digital origination infrastructure is fragmenting competitive positioning, separating technology-enabled brokers from documentation-dependent operators while regulatory disclosure automation and borrower self-service expectations reshape workflow economics.
Point-of-sale platforms with embedded pricing engines are bifurcating the broker channel. Top-20 wholesale lenders are mandating API connectivity for rate sheet access, locking out smaller brokers lacking IT investment capacity. This technology compression is consolidating correspondent relationships around scaled originators with direct LOS integration.
The Consumer Financial Protection Bureau's TILA-RESPA integrated disclosure rule revisions are tightening compliance automation requirements. Brokers must now synchronize loan estimate and closing disclosure generation with title and escrow providers through standardized data exchanges. Purchase transactions in high-cost coastal markets face the steepest adaptation curves as disclosure tolerance thresholds narrow.
Self-directed borrower research is displacing traditional referral-dependent acquisition models. First-time buyers in metropolitan Texas and Florida markets are initiating rate comparisons through aggregator platforms before selecting brokers, compressing the consultative sales cycle. Brokers responding with transparent pricing tools and educational content are capturing this pre-qualified demand upstream of application submission.
US Mortgage/Loan Brokers Market Segmentation
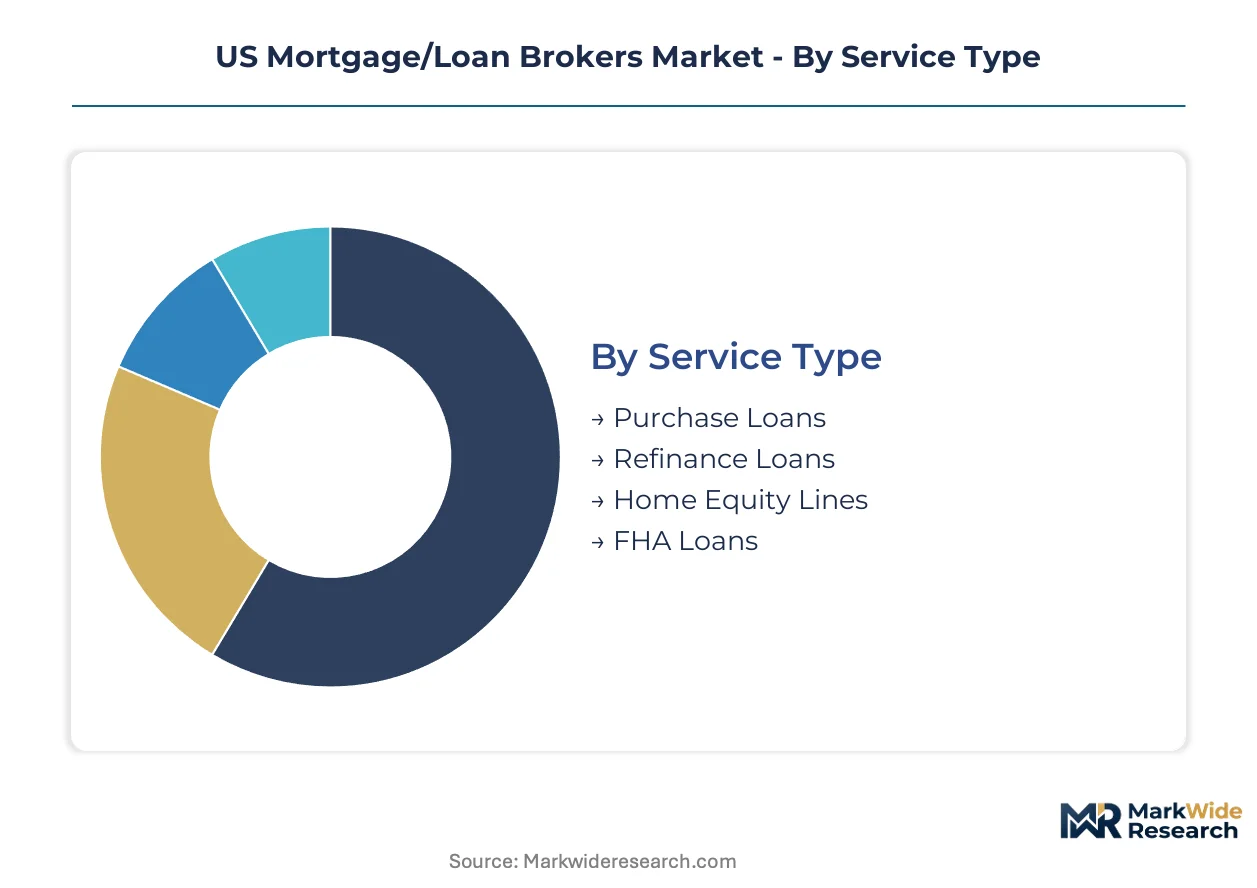
US mortgage brokers serve distinct borrower cohorts with specialized product menus and origination workflows. Service specialization and technology deployment determine which intermediaries capture volume in purchase-heavy versus refinance-driven cycles.
Service Type:
Refinance products face acute substitution pressure from direct-to-consumer digital lenders, while purchase loans retain broker dependency due to complex coordination requirements.
- Purchase Loans:These originations finance primary residence acquisitions and require extensive documentation coordination between buyers, sellers, title agents, and underwriters. Sun Belt markets in Texas and Florida concentrate purchase volume as interstate migration elevates housing turnover.
- Refinance Loans:Rate-term refinances and cash-out transactions replace existing mortgage obligations. Rate volatility has compressed refinancing windows, forcing brokers to accelerate application processing to capture narrow opportunity periods.
- Home Equity Lines:HELOCs provide revolving credit secured by residential property. Rising homeowner equity positions in appreciating markets are expanding cross-sell potential alongside first-lien originations.
- FHA Loans:Government-insured products serve credit-impaired borrowers and first-time buyers with reduced down-payment requirements. HUD guideline modifications continue expanding accessible product menus for this segment.
Purchase loans retain volume leadership; online platform integration is gaining share fastest among service delivery models.
Client Type:
Cost-tier differentiation separates transaction-heavy investors from advisory-dependent first-time buyers seeking education-intensive support.
- First-Time Buyers:This cohort requires extensive guidance through documentation, down-payment assistance programs, and credit optimization. State housing finance agencies in California and New York generate substantial referral volume to participating brokers.
- Investors:Residential property investors pursue DSCR and bank-statement products for non-owner-occupied acquisitions. Documentation complexity commands premium broker pricing for non-QM packaging expertise.
- Refinancers:Existing homeowners seek rate reduction or equity extraction. Rate sensitivity drives rapid platform switching, compressing loyalty and origination margins.
- Upgraders:Move-up buyers bridge financing between existing home sales and new purchases. Contingency management and concurrent transaction coordination sustain broker advisory value.
First-time buyers dominate absolute transaction counts; investors deliver the steepest margin expansion curve.
Loan Type:
Maturity-stage variation separates commoditized fixed-rate products from specialized adjustable and government-backed alternatives.
- Fixed-Rate Mortgages:These instruments lock borrowing costs for 15-30 year terms. Payment certainty demand against Federal Reserve policy uncertainty sustains structural dominance in broker product mixes.
- Adjustable-Rate Mortgages:ARMs carry rate-reset provisions after initial fixed periods. Short-term rate expectations influence borrower uptake, with 5/1 and 7/1 hybrid structures attracting cost-sensitive applicants.
- Interest-Only Loans:These products defer principal amortization during initial terms. Jumbo markets and high-net-worth borrowers in coastal metropolitan areas sustain limited demand for cash-flow optimization.
- VA Loans:Department of Veterans Affairs guarantees eliminate down-payment requirements for eligible service members. Military concentration states including Texas and Virginia concentrate origination activity.
Fixed-rate products anchor volume; non-QM alternatives are expanding most quickly among self-employed borrower segments.
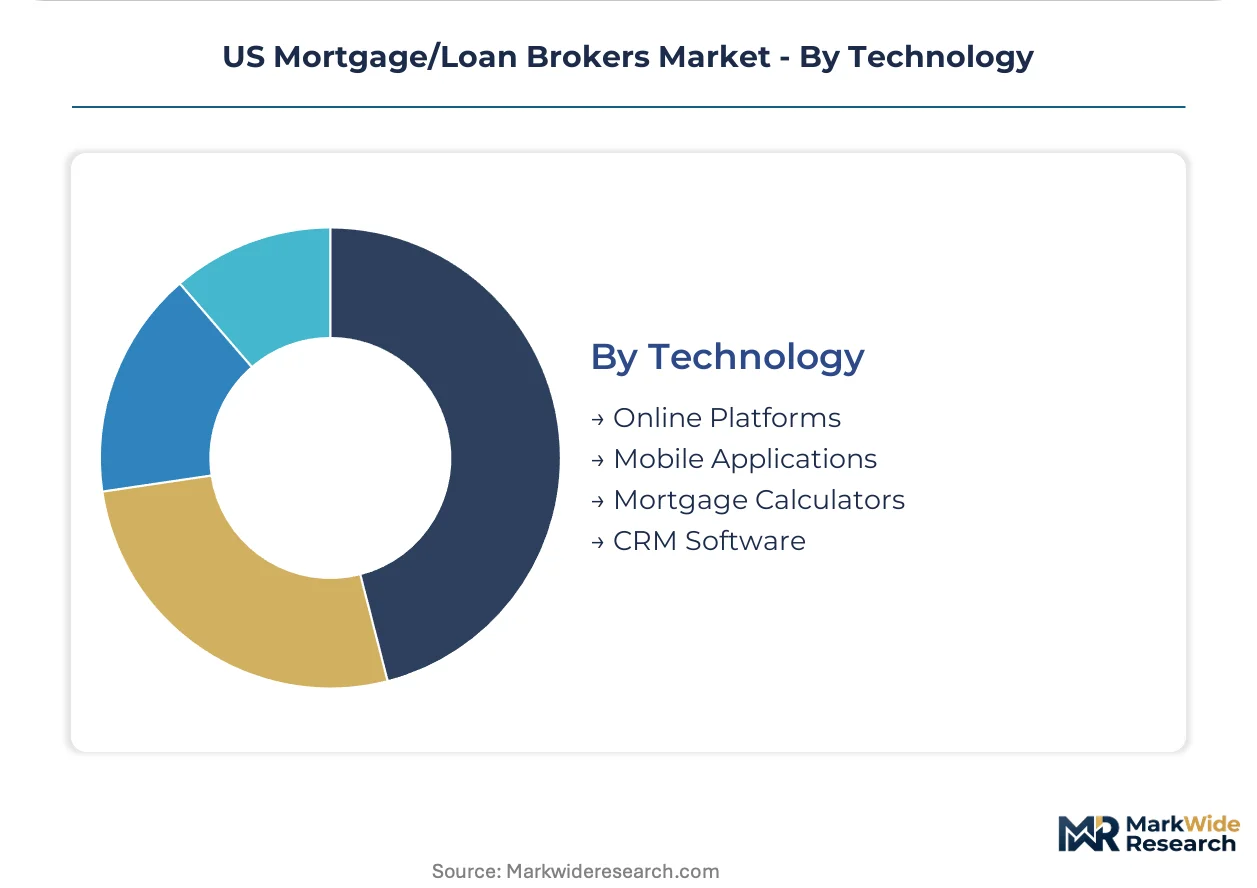
Technology:
Supply concentration among top-20 wholesale lenders is forcing API connectivity mandates that filter out technology-deficient brokers.
- Online Platforms:Web-based origination portals enable borrower self-service with embedded pricing engines. Aggregator platforms in Texas and Florida metropolitan markets are capturing upstream rate comparison traffic.
- Mobile Applications:Smartphone-native interfaces support document upload and status tracking. First-time buyer demographics drive adoption pressure for mobile-first engagement.
- Mortgage Calculators:Affordability and payment estimation tools support pre-qualification workflows. Transparency requirements are elevating calculator accuracy standards.
- CRM Software:Pipeline management systems coordinate lead nurturing and referral partner relationships. Compliance automation integration is becoming mandatory for TILA-RESPA disclosure synchronization.
Online platforms lead transaction volume; mobile applications show the steepest adoption trajectory among originator technology investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyers and relocating professionals concentrate demand in Sun Belt corridors, where housing affordability differentials and remote work mobility sustain broker-referral network expansion.
Texas
Houston and Dallas-Fort Worth metro areas absorb interstate migration flows from California and New York, elevating purchase loan origination volumes. The Texas Department of Savings and Mortgage Lending enforces state-level broker licensing overlays beyond NMLS requirements. Austin's technology sector employment growth is generating high-income borrower segments seeking jumbo product expertise.
Florida
Tampa and Orlando markets experience retiree and remote worker inflows, sustaining non-QM and bank-statement loan demand for self-employed transplants. The Florida Office of Financial Regulation administers mortgage broker licensing with continuing education mandates. Miami-Dade County's international buyer concentration supports specialized foreign-national lending programs through correspondent channels.
California
Bay Area and Los Angeles metros retain high-dollar origination activity despite net outmigration, with brokers specializing in jumbo and super-jumbo products. CalHFA down-payment assistance programs channel first-time buyer volume through approved broker networks. Sacramento's inland affordability advantage is capturing spillover demand from coastal price compression.
Arizona
Phoenix and Tucson markets lead national housing turnover rates, with brokers capturing referral relationships from inbound buyers seeking local market navigation. The Arizona Department of Financial Institutions coordinates NMLS reciprocity for multistate operators. Scottsdale's luxury corridor sustains private banking partnerships for high-net-worth mortgage placement.
Illinois
Chicago's diversified employment base stabilizes origination volumes through economic cycles, with brokers cross-selling HELOC products alongside purchase financing. The Illinois Department of Financial and Professional Regulation enforces distinct branch licensing requirements for mortgage operations. Downstate markets including Springfield and Peoria retain community bank referral dependencies for FHA and USDA rural lending.
US Mortgage/Loan Brokers Market Competitive Landscape
Player mix skews toward wholesale specialists and retail branch networks, with technology-enabled direct lenders compressing margins on rate-sensitive refinance products. Three archetypes dominate: wholesale-only aggregators, distributed retail originators, and direct-to-consumer digital platforms. Competitive moves concentrate on API integration mandates and correspondent relationship consolidation.
Among wholesale-focused operators, United Wholesale Mortgage and CrossCountry Mortgage exemplify scale-driven correspondent channel dominance, while Rocket Mortgage anchors the direct-to-consumer digital tier. These three entities represent divergent strategic postures on technology investment, retail presence, and capital markets access.
| Leading Market Players |
|---|
| United Wholesale Mortgage |
| Rocket Mortgage |
| CrossCountry Mortgage |
| Fairway Independent Mortgage Corporation |
| Guaranteed Rate |
| Guild Mortgage Company |
| LoanDepot |
| Caliber Home Loans |
| Lendingtree |
| Others |
Pricing and Supply Chain Analysis
API-first origination stacks replacing legacy LOS integrations are redrawing correspondent lender geography toward scaled national wholesalers while compressing rate sheet margins for technology-deficient brokers. This substitution simultaneously elevates pricing power for warehouse lenders with direct system connectivity and erodes yield spread retention among documentation-dependent intermediaries.
Pricing Analysis
Cost-plus contracts indexed to primary-secondary mortgage spreads dominate wholesale channel economics, with broker compensation fluctuating alongside MBS price movements. Price differentiation hinges on loan officer NMLS certification tier and correspondent relationship depth, with premium pricing attaching to non-QM packaging expertise. Pricing pressure stems from GSE pricing transparency tools commoditizing conforming loan shopping. First-time buyers exhibit highest price sensitivity, while self-employed investors seeking DSCR products demonstrate lowest elasticity.
Supply Chain Analysis
Inventory compression in warehouse lending capacity has collapsed broker liquidity lead times from regional banks, forcing reliance on national warehouse lenders concentrated in New York, California, and Texas. Capital sourcing draws from correspondent relationships, agency securities pipelines, and private-label MBS conduits. Single-source vulnerability concentrates around top-20 wholesale lenders mandating API connectivity. Distribution runs through correspondent channels, wholesale broker networks, and direct retail origination arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US mortgage broker market constitutes a high-growth disruption as NMLS recertification cycles filter capital-light operators while API-first origination infrastructure rewrites competitive economics. The Secure and Fair Enforcement for Mortgage Licensing Act enforcement represents the decisive regulatory inflection compressing participation thresholds.
For Market Incumbents: Fortify correspondent channel control through exclusive LOS integration investments that lock out technology-deficient competitors. Deepen vertical integration into title and escrow services to capture ancillary revenue streams as yield spreads compress. Prioritize NMLS compliance automation to prevent E&O exposure from TILA-RESPA disclosure timing violations. For New Entrants and Emerging Players: NMLS fast-track licensing programs in Sun Belt states offer expedited market entry pathways for capitalized operators. White-space concentration sits in non-QM product development for self-employed borrowers underserved by conventional channels. California and Texas down-payment assistance program partnerships provide referral network anchoring with housing finance agencies. For Investors and Strategic Acquirers: Capital is best deployed toward technology-enabled wholesale aggregators with direct API connectivity to top-20 correspondent lenders. Long-term viability centers on scalable compliance infrastructure capable of absorbing NMLS regulatory evolution. Watch for GSE pricing adjustment announcements as volume inflection signals reshaping broker compensation pools.| Strategic Initiative | Industry Significance |
|---|---|
| API-First LOS Integration | Mandatory connectivity to United Wholesale Mortgage and Rocket Mortgage rate engines locks in correspondent volume access. |
| Non-QM Product Development | Bank statement and DSCR loans for self-employed borrowers command premium pricing in underserved credit segments. |
| HELOC Cross-Sell Integration | Embedding home equity access into purchase workflows captures rising homeowner equity positions in appreciating Sun Belt markets. |
| NMLS Compliance Automation | TILA-RESPA disclosure synchronization with title providers prevents cure cost erosion from CFPB enforcement actions. |
| State Housing Agency Partnerships | CalHFA and Texas Department of Housing referral networks channel first-time buyer volume through approved broker networks. |
Research Methodology
Initial hypotheses were tested against primary input from mortgage broker principals, wholesale lender correspondent managers, NMLS compliance officers, and title agency executives and refined through secondary validation against HUD guideline publications, CFPB enforcement action databases, NMLS licensing statistics, and MBA origination volume surveys. Bottom-up broker count modeling triangulated against top-down origination dollar flow analysis.
Variance decomposition across service type, client segment, loan structure, and technology deployment dimensions anchored the analytical framework. CAGRs were derived through regression-based trending of historical origination volumes against macroeconomic drivers. Forecast inputs incorporated Federal Reserve policy trajectory assumptions and Sun Belt migration pattern persistence.
Underlying assumptions cover sustained NMLS regulatory enforcement intensity and correspondent channel consolidation continuity, with deviation risk concentrated in warehouse lending capacity disruptions and GSE pricing model revisions. Revision becomes warranted when MBS spread volatility crosses historical thresholds or NMLS recertification cycles accelerate unexpectedly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Refinancing Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
Car Finance Market
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market