
 Australia Education Student Loans Market | 2026-2036
Australia Education Student Loans Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Education Student Loans Market Insights
HELP indexation is broadening the cost-of-entry calculus for prospective students weighing lifetime debt against expected graduate earnings. Commonwealth Bank leverages its branch network and digital platform integration to sustain dominant retail positioning in private student lending. Westpac anchors its education finance offering through bundled products tied to graduate banking relationships, while ANZ Bank competes on rate transparency and refinancing flexibility for post-graduation consolidation.
Australia education student loans constitute credit instruments extended to enrolled students for financing tuition fees, living expenses, textbooks, and course materials, typically structured with income-contingent repayment mechanisms tied to borrower earnings thresholds. Federal Loans dominate outstanding portfolio volume through the Higher Education Loan Program administered by Services Australia, while Private Loans represent the fastest-expanding segment as domestic banks develop specialized education credit products with accelerated digital origination. Borrower Demographics reveal Graduate borrowers command larger per-capita disbursements and extended repayment terms, concentrating margin pools in professional-degree financing.
The Department of Education sets policy parameters governing HELP eligibility and indexation methodology, while the Australian Prudential Regulation Authority supervises capital adequacy for bank-originated private student credit. TGA does not regulate this market; instead, ASIC administers responsible lending obligations under the National Consumer Credit Protection Act, shaping product disclosure standards and borrower assessment protocols. Stakeholders must monitor indexation rate methodology reviews and potential income threshold adjustments that would reshape repayment timelines and portfolio risk profiles.
Market Dynamics
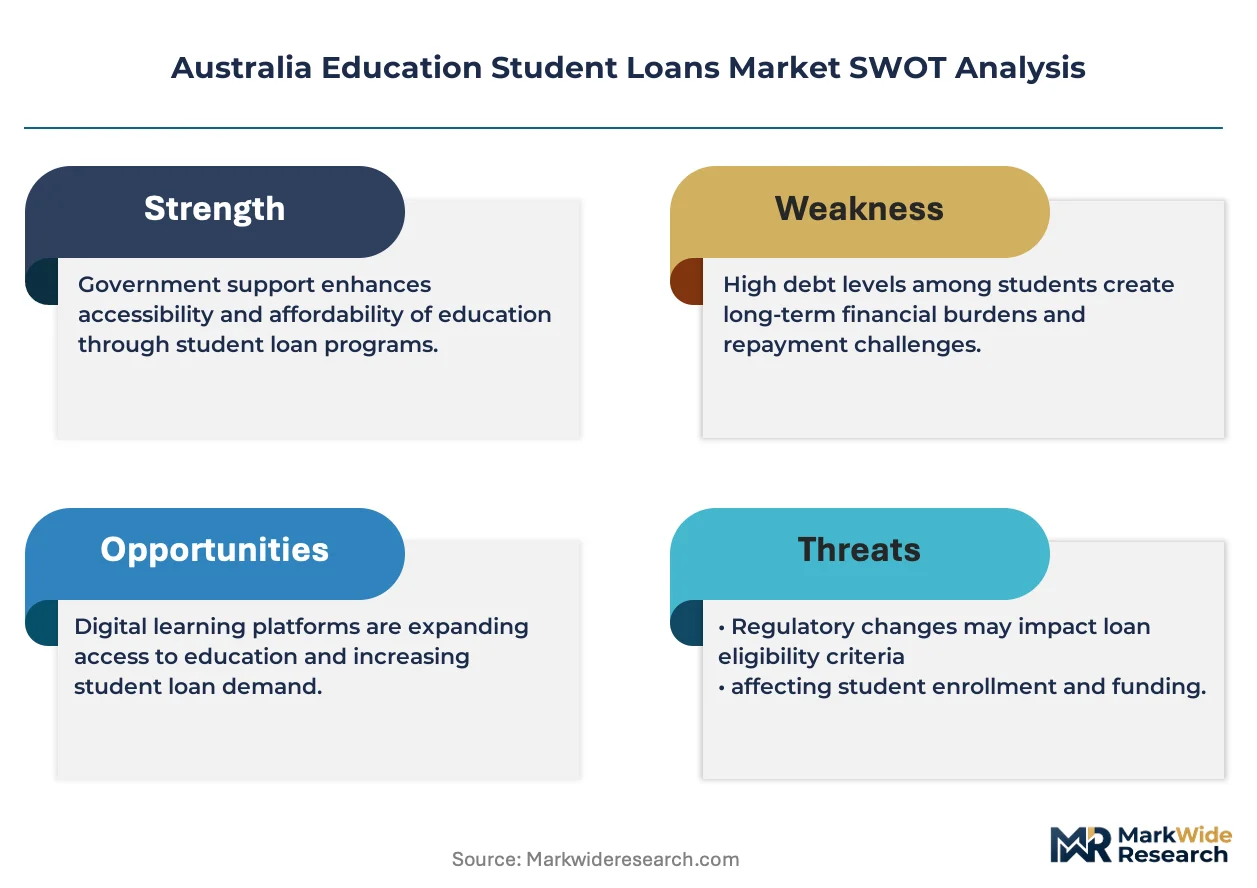
HELP indexation methodology revisions are restructuring borrower repayment calculus across income brackets, compressing enrollment timelines for price-sensitive demographics while expanding private refinancing alternatives.
Growth Catalysts
- Professional upskilling mandates:Employers in healthcare and engineering sectors now require postgraduate credentials for senior roles, pulling mid-career professionals into coursework programs with full-fee financing needs.
- Services Australia administrative digitization:Automated income verification and repayment threshold adjustments reduce application friction, accelerating loan origination velocity for first-year undergraduates.
- Metropolitan cost-of-living inflation:Sydney and Melbourne rental markets push students toward larger living-expense supplements, expanding average disbursement sizes in New South Wales and Victoria.
Market Restraints
- Indexation rate volatility:CPI-linked adjustments to outstanding HELP balances create uncertainty in lifetime repayment projections, deterring risk-averse borrowers from extended professional-degree programs.
- Private credit concentration:Four major banks dominate non-government student lending, limiting rate competition and product differentiation for specialized borrower segments.
- Income threshold rigidity:Fixed repayment thresholds fail to adjust for regional wage disparities, creating disproportionate burden on graduates in lower-income states.
Strategic Opportunities
- Refinancing product development:Post-graduation consolidation loans with rate transparency features capture borrowers transitioning from HELP to private amortization structures.
- Regional university partnerships:Queensland and South Australia campuses show enrollment growth with underdeveloped private lending penetration relative to borrower demand.
- Skills Priority List alignment:Commonwealth-designated shortage occupations trigger enhanced subsidy eligibility, creating targeted marketing entry points for allied health and engineering finance products.
Industry Challenges
- Responsible lending assessment complexity:ASIC's National Consumer Credit Protection Act requirements demand income projection modeling for students without established earnings histories, extending origination timelines.
- Legacy system integration:Bank-originated private loans must interface with Services Australia repayment infrastructure, creating technical debt in servicing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Education Student Loans Market |
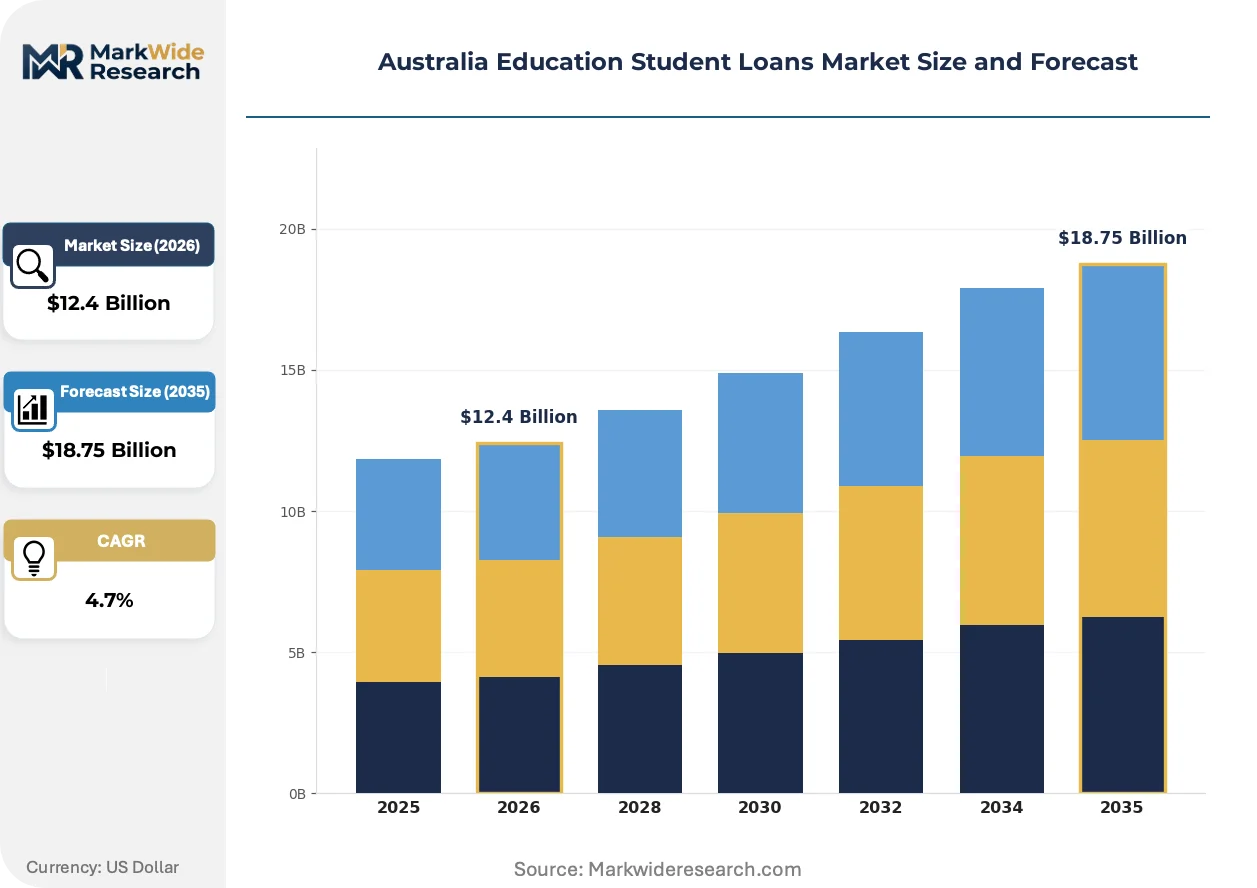
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Federal Loans, Private Loans, Consolidation Loans, Alternative Financing Repayment Plan: Income-Driven, Fixed, Graduated, Extended Borrower Demographics: Undergraduates, Graduates, International Students, Part-Time Students Loan Purpose: Tuition Fees, Living Expenses, Textbooks, Course Materials |
| Companies Covered | Department of Education, Study Assist, Services Australia, Commonwealth Bank, Westpac, ANZ Bank, NAB, Macquarie Bank, Suncorp Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Education Student Loans Market Trends and Innovations
Digital origination platforms are compressing application-to-disbursement cycles while regulatory indexation debates reshape product architecture across federal and private lending channels.
Application programming interfaces between bank mobile platforms and university enrollment systems are unifying identity verification, course confirmation, and funds disbursement into single-session workflows. Domestic banks with established graduate banking relationships deploy these integrations most aggressively. This unification is collapsing origination costs and shifting competitive advantage toward deposit-rich institutions with existing customer data infrastructure.
The Australian Government's scheduled HELP indexation methodology review is forcing portfolio repricing assumptions across income-contingent loan products. Services Australia and private lenders alike must model alternative CPI linkage formulas and threshold adjustment mechanisms. Professional-degree borrowers with extended repayment horizons face the greatest exposure to parameter changes, driving demand for fixed-rate private refinancing alternatives.
Course-level employment outcome disclosure requirements are altering program selection patterns among first-generation university entrants. Prospective students in Western Australia and Tasmania increasingly prioritize vocational education and training pathways with explicit job placement metrics over traditional undergraduate degrees. This geographic concentration of preference shift is pressuring regional university finance offices to expand sub-bachelor certificate program lending arrangements.
Australia Education Student Loans Market Segmentation
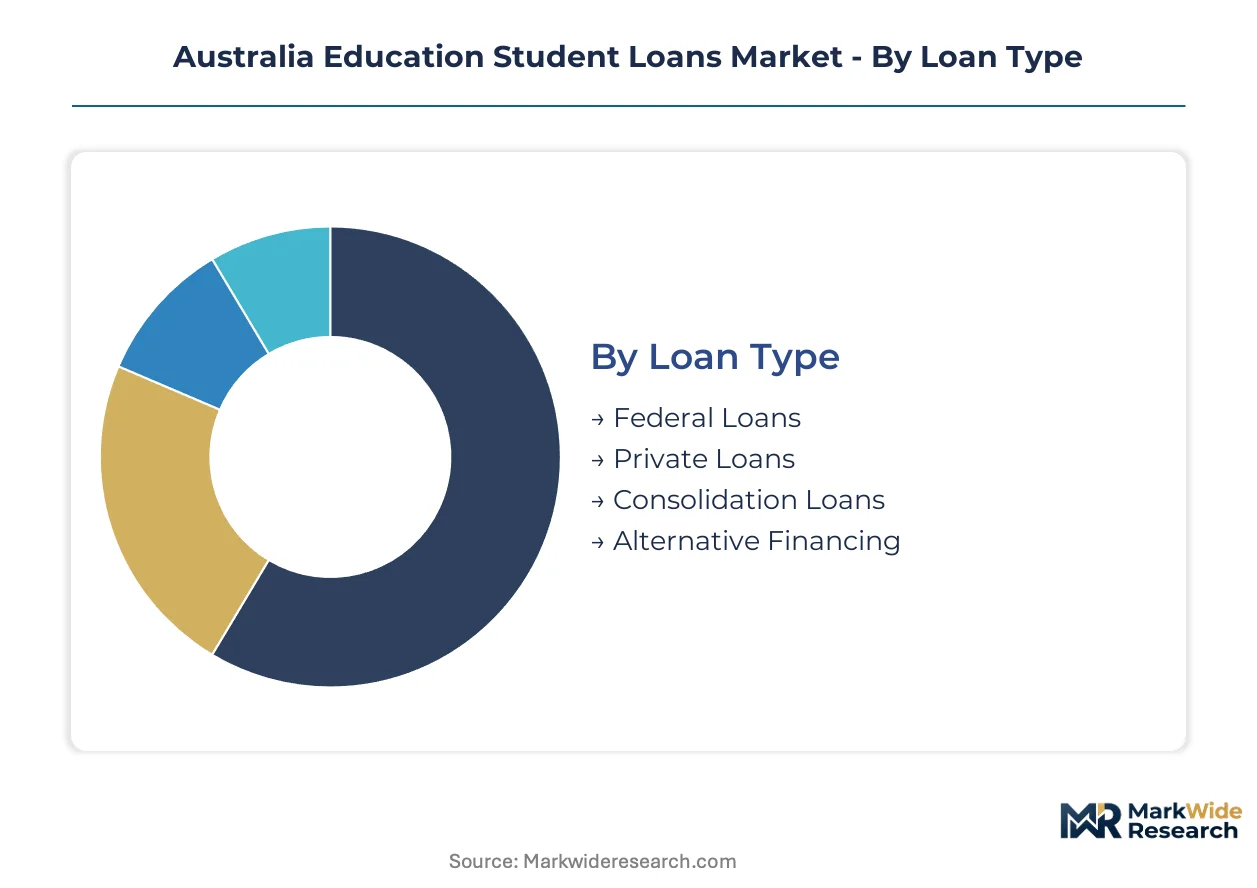
Segmentation in Australian education student loans reveals how repayment mechanics and borrower profiles reshape product architecture. Lenders calibrate origination protocols around income-contingent structures versus fixed amortization, while demographic targeting determines geographic deployment and channel strategy.
Loan Type:
Technology integration distinguishes origination velocity and servicing infrastructure across government and private channels.
- Federal Loans:Higher Education Loan Program instruments administered through Services Australia carry CPI-linked indexation and income-contingent repayment thresholds. Demand concentrates in New South Wales and Victoria where university enrollment density drives application volume, though indexation rate volatility compresses enrollment timelines for price-sensitive cohorts.
- Private Loans:Bank-originated credit products feature accelerated digital origination through mobile platform integration with university enrollment systems. Commonwealth Bank and Westpac dominate this segment through branch network coverage and graduate banking relationship bundling, capturing borrowers seeking fixed-rate alternatives to HELP indexation exposure.
- Consolidation Loans:Post-graduation refinancing instruments merge multiple obligations into single amortization structures with rate transparency features.
- Alternative Financing:Income-share agreements and employer-sponsored tuition programs operate outside traditional credit frameworks with variable repayment terms tied to employment outcomes.
Mature deployment sits with Federal Loans. Newer deployment is concentrated in Private Loans.
Repayment Plan:
Cost tier differentiation separates borrowers by income stability and career stage rather than loan size alone.
- Income-Driven:HELP-linked structures adjust repayment obligations against annual earnings with threshold-triggered deferment periods. Services Australia infrastructure supports automated income verification, reducing administrative friction for graduates entering volatile employment markets.
- Fixed:Standard amortization schedules with predictable monthly obligations appeal to mid-career professionals in stable employment sectors.
- Graduated:Payment structures begin below full amortization levels and escalate on predetermined schedules.
- Extended:Term elongation reduces immediate payment burden while increasing lifetime interest accumulation.
Volume concentration favors Income-Driven structures. Margin expansion is steepest in Fixed repayment products.
Borrower Demographics:
Application patterns cluster around life stage and enrollment intensity, with distinct origination protocols for each cohort.
- Undergraduates:First-degree seekers accessing HELP for tuition and living expense supplements dominate application flow through Services Australia digital portals.
- Graduates:Postgraduate coursework participants command larger per-capita disbursements and extended repayment terms, concentrating margin pools in professional-degree financing for healthcare and engineering credentials.
- International Students:Full-fee paying cohorts require private credit or pre-paid arrangements without HELP eligibility, driving demand for bank-originated products with foreign income verification protocols.
- Part-Time Students:Employment-constrained learners exhibit irregular enrollment patterns and extended program timelines.
Customer acquisition costs are lowest for Undergraduates. Lifetime value concentration sits with Graduates.
Loan Purpose:
Geographic cost variation drives disbursement size dispersion across metropolitan and regional markets.
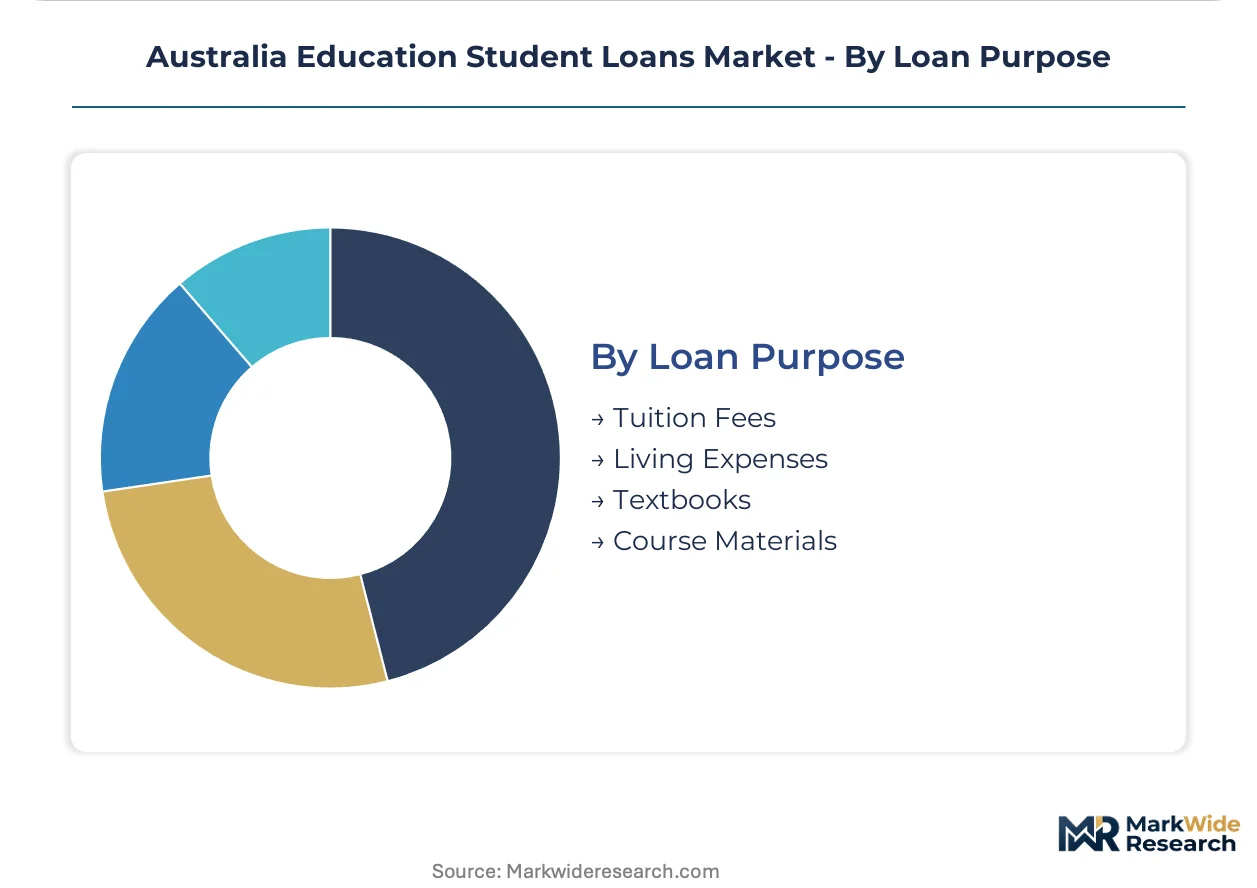
- Tuition Fees:University-determined charges constitute the core loan purpose with standardized disbursement schedules aligned to academic calendars.
- Living Expenses:Rental market inflation in Sydney and Melbourne pushes supplemental borrowing volumes, expanding average disbursement sizes in high-cost metropolitan corridors.
- Textbooks:Course-specific material requirements generate smaller, frequent disbursement events.
- Course Materials:Specialized equipment and software purchases for professional programs carry higher per-unit costs than standard textbooks.
Regulatory scrutiny is tightest for Living Expenses. Disbursement velocity is fastest for Tuition Fees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University precincts in New South Wales and Victoria operate as Australia's primary education finance clusters, where metropolitan living costs and enrollment density concentrate both federal HELP disbursements and private lending origination.
New South Wales
Sydney's rental market inflation drives supplemental living-expense borrowing volumes beyond tuition financing alone. The Department of Education's HELP eligibility parameters govern access for students at Group of Eight universities concentrated in the metropolitan corridor. Macquarie Park and Parramatta satellite campuses are expanding postgraduate coursework enrollment, pulling mid-career professionals into professional-degree financing.
Victoria
Melbourne's inner-city university precincts generate Australia's highest per-capita student loan disbursements through combined tuition and accommodation costs. Services Australia administers income-contingent repayment infrastructure for RMIT and University of Melbourne cohorts. The western suburbs corridor is seeing enrollment growth in vocational education and training pathways with distinct sub-bachelor lending arrangements.
Queensland
Brisbane and Gold Coast campuses show enrollment expansion with comparatively underdeveloped private lending penetration relative to borrower demand. The Australian Prudential Regulation Authority supervises capital adequacy for regional bank branches extending education credit products. Southeast Queensland's university network is developing specialized healthcare and engineering finance products aligned with Commonwealth Skills Priority List designations.
Western Australia
Perth-based students increasingly prioritize vocational education and training pathways with explicit job placement metrics over traditional undergraduate degrees. ASIC's National Consumer Credit Protection Act shapes responsible lending assessment protocols for bank-originated products in the state. The Fiona Stanley precinct and resources sector corridor are driving professional upskilling mandates for postgraduate credential financing.
South Australia
Adelaide's metropolitan university enrollment is expanding with limited private lending infrastructure relative to eastern states. The Department of Education's indexation methodology adjustments directly affect repayment burden calculations for local graduates. The Tonsley innovation district and emerging defense industry precinct are creating targeted demand for engineering and technology credential financing.
Australia Education Student Loans Market Competitive Landscape
Major bank lenders anchor one tier; federal administrative agencies hold the infrastructure layer. The market presents a bifurcated structure with Services Australia dominating outstanding portfolio volume through HELP administration, while four major banks concentrate private origination. Strategic archetypes include deposit-rich institutions leveraging graduate banking relationships, rate-transparent competitors pursuing refinancing capture, and administrative specialists optimizing income-verification automation. Competitive moves center on digital platform integration with university enrollment systems and post-graduation consolidation product development.
Within the major bank tier, Commonwealth Bank, Westpac, and ANZ Bank occupy distinct positioning vectors. Commonwealth Bank exemplifies the branch-network-dominant archetype with digital platform integration sustaining retail positioning. Westpac represents the relationship-bundling approach, anchoring education finance within broader graduate banking propositions. ANZ Bank sits within the rate-transparency segment, competing on refinancing flexibility for post-graduation consolidation. These three institutions collectively shape private lending architecture while operating under ASIC's responsible lending framework and APRA's capital adequacy requirements.
| Leading Market Players |
|---|
| Department of Education |
| Study Assist |
| Services Australia |
| Commonwealth Bank |
| Westpac |
| ANZ Bank |
| NAB |
| Macquarie Bank |
| Suncorp Bank |
| Others |
Pricing and Supply Chain Analysis
API-enabled origination platforms are collapsing application processing costs while concentrating competitive advantage among deposit-rich institutions with established customer data infrastructure, simultaneously reshaping cost economics and supply concentration across federal and private lending channels.
Pricing Analysis
Expedited disbursement timelines command premium rate positioning, while standard processing windows attract rate-sensitive borrowers through modest discounts. Three-tier pricing structure across premium, standard, and economy levels segments borrowers by income stability and enrollment urgency. Pricing pressure stems from Services Australia indexation methodology uncertainty compressing demand for extended professional-degree programs. First-year undergraduates accessing HELP through digital portals exhibit highest price sensitivity, whereas mid-career professionals financing postgraduate credentials show lowest sensitivity due to employer subsidy offsets.
Supply Chain Analysis
Regional distribution centers in Sydney and Melbourne anchor hub-and-spoke disbursement patterns, with satellite branches in Brisbane and Perth extending coverage into underpenetrated markets. Capital provisioning draws from domestic deposit bases in New South Wales and Victoria, with supplementary wholesale funding sourced from institutional money markets. Single-source vulnerability concentrates in Services Australia repayment infrastructure, where legacy system dependencies create servicing bottlenecks for bank-originated private loans. Distribution runs through university financial aid offices, mobile banking platforms, and direct-to-borrower digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating toward vertical-integration races as major banks pursue upstream control over graduate banking relationships and downstream capture of refinancing origination.
For Market Incumbents: Deepen integration with university enrollment systems to lock in first-year customer acquisition before HELP eligibility determination. Expand fixed-rate refinancing product development to capture borrowers fleeing CPI-linked indexation exposure. Services Australia threshold adjustments represent the primary regulatory threat requiring portfolio repricing capability. Backward integration into graduate banking relationships sustains lifetime value capture across product lifecycles. For New Entrants and Emerging Players: Regional university partnerships in Queensland and South Australia present underserved buyer archetypes with enrollment growth and limited private lending penetration. Sub-bachelor certificate program financing in Western Australia vocational pathways offers secondary white-space entry. Skills Priority List alignment creates targeted marketing entry points for allied health and engineering finance products with enhanced subsidy eligibility. For Investors and Strategic Acquirers: Exit pathways concentrate in deposit-rich institutions with scalable digital origination infrastructure and established graduate banking franchises. Long-term viability hinges on regulatory indexation methodology stability and income threshold adjustment predictability. Acquisition targets should demonstrate Services Australia system integration capability and regional university partnership density. The signal to monitor is HELP indexation rate volatility triggering demand surges for fixed-rate private alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| University Enrollment System Integration | API unification with Services Australia infrastructure collapses origination friction for first-year undergraduates. |
| Fixed-Rate Refinancing Product Launch | Post-graduation consolidation captures borrowers seeking shelter from CPI-linked HELP indexation exposure. |
| Regional Campus Partnership Expansion | Queensland and South Australia enrollment growth outpaces private lending infrastructure deployment. |
| Skills Priority List Alignment | Commonwealth-designated shortage occupations trigger enhanced subsidy eligibility for targeted credential financing. |
| Graduate Banking Relationship Bundling | Deposit-rich institutions leverage existing customer data to sustain cross-sell velocity across product lifecycles. |
Research Methodology
Independent corroboration across primary interviews with university financial aid directors, bank education lending product managers, regulatory policy specialists, and postgraduate enrollment officers underwrites the qualitative findings. Secondary validation draws from Department of Education policy circulars, APRA prudential standards, ASIC regulatory guidance, and Services Australia administrative reports. Bottom-up loan origination modeling triangulates against top-down market sizing from aggregate HELP disbursement data and private bank portfolio disclosures.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the projection horizon. Segmentation dimensions modeled include loan type, repayment plan structure, borrower life stage, and geographic enrollment cluster. CAGRs derive from enrollment trend extrapolation, indexation methodology assumptions, and private lending penetration rate analysis. Forecast inputs incorporate metropolitan cost-of-living inflation trajectories and professional upskilling mandate propagation across employer sectors.
Revisions become necessary when HELP indexation methodology reviews materialize, income threshold adjustments alter repayment burden calculations, or regulatory responsible lending obligations expand assessment complexity. Forecasts reflect documented assumptions regarding Services Australia administrative capacity and major bank digital platform investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Software Market