
 Car Leasing Market | 2026-2036
Car Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Car Leasing Market Intelligence
The capital-intensity divergence between captive finance arms and independent lessors is collapsing as balance-sheet requirements for residual-value risk compress margins. Enterprise Holdings Inc. leverages its integrated fleet management infrastructure to sustain utilization rates across airport and neighborhood locations. LeasePlan Corporation NV anchors its position through multi-country fleet administration capabilities. General Motors Financial Company, Inc. competes by tying lease terms directly to vehicle production cycles and residual forecasting.
Car leasing constitutes a contractual arrangement where a lessee obtains vehicle use rights for a defined term through fixed monthly payments, with residual value typically borne by the lessor and mileage limits enforced through per-kilometer penalties. The primary commercial purpose centers on converting capital-intensive vehicle ownership into predictable operating expenses while transferring depreciation risk to the financing entity. Closed-end leases dominate individual consumer channels because they cap residual exposure for lessees, while open-end structures prevail among fleet operators who accept variable resale outcomes in exchange for customized terms. Online platforms represent the fastest-expanding sales channel as digital origination reduces friction in credit decisioning and contract execution.
The Consumer Financial Protection Bureau in the United States enforces Truth in Lending Act disclosures that shape lease advertising and payment presentations, while the EU's GDPR constrains telematics data collection used for usage-based pricing. The SEC monitors residual-value securitization practices that fund lessor balance sheets. Stakeholders must monitor evolving emissions compliance timelines and residual-value model accuracy as electrification disrupts historical depreciation curves.
Market Dynamics
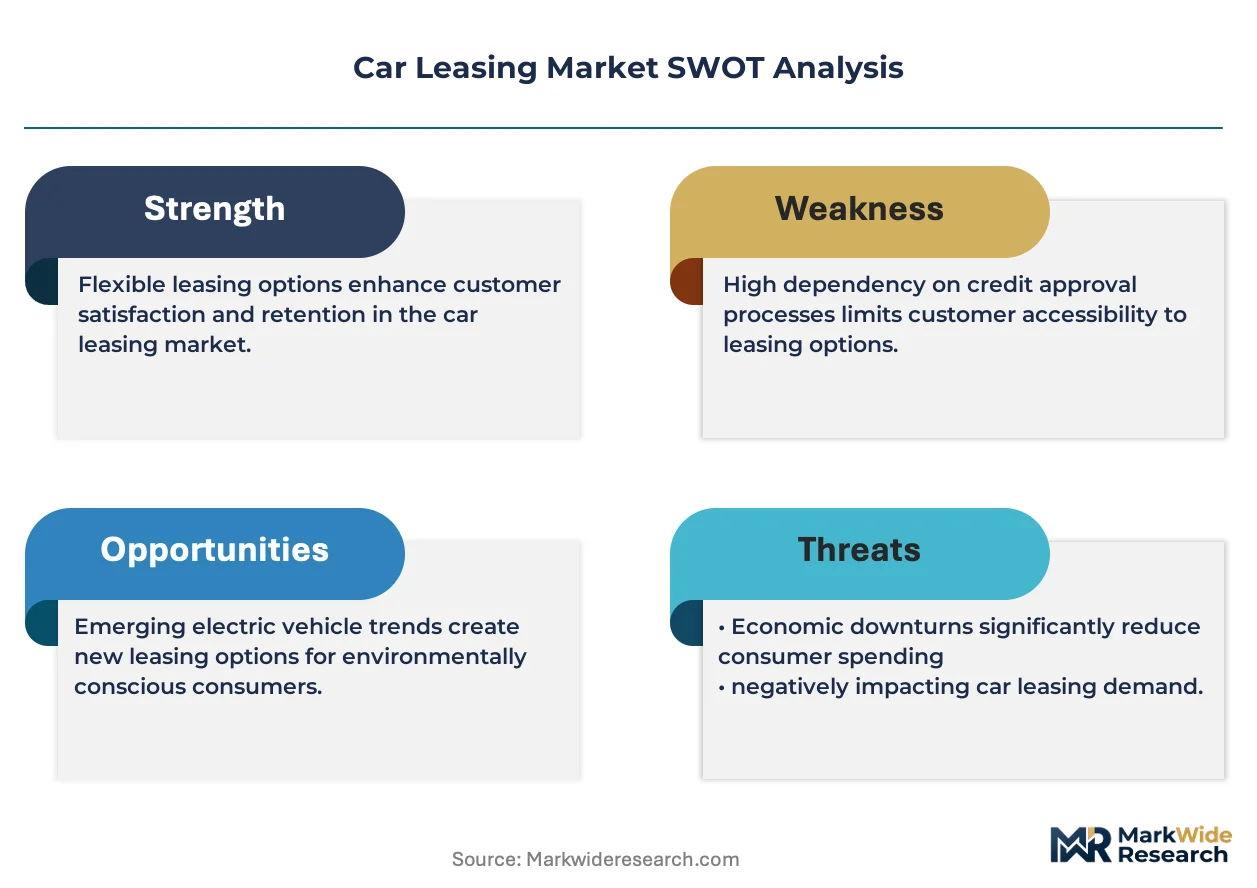
The transition toward electric powertrains is compressing residual-value forecasting accuracy as battery degradation curves replace engine-wear depreciation models, forcing lessors to rebuild pricing frameworks around uncertain secondary-market demand for used EVs.
Growth Catalysts
- EU F-Gas Regulation:Fleet operators in Germany, France, and the Netherlands are accelerating vehicle replacement cycles to comply with refrigerant-phaseout timelines, expanding short-term lease volumes for compliant models.
- Telematics integration:Real-time mileage and driver-behavior monitoring enables usage-based pricing structures that expand addressable demand among low-mileage urban households previously excluded by fixed-mileage contracts.
- Captive finance arms:OEM-owned lessors in Japan and South Korea leverage production-schedule alignment to offer subvented lease rates that absorb residual risk during new-model launches.
Market Restraints
- Lithium-ion battery cost volatility:Raw-material price swings for nickel and cobalt compress EV lease margin predictability, forcing lessors to embed wider residual-value cushions.
- Semiconductor supply concentration:Taiwan and South Korea manufacturing dominance creates delivery-timeline uncertainty that delays fleet-delivery commitments and extends lease origination cycles.
- Closed-end lease rigidity:Fixed-term structures struggle to accommodate remote-work-induced mileage reductions, pushing some lessees toward subscription alternatives.
Strategic Opportunities
- India fleet modernization:Corporate leasing penetration remains below Western levels, creating white space as GST input-credit rules improve and organized used-car channels mature.
- Battery-as-a-service decoupling:Separating battery costs from vehicle leases reduces residual-value exposure while enabling lower monthly payments for price-sensitive segments.
- Used-lease certification programs:Standardized battery-health reporting and OEM-backed warranties can unlock secondary-market liquidity for off-lease EVs.
Industry Challenges
- Data-science talent scarcity:Residual-value modeling now requires machine-learning expertise combined with automotive engineering knowledge, a hybrid skill set in short supply across lessor analytics teams.
- Legacy IT integration:Mainframe-based contract-management systems at established lessors resist API connectivity with digital origination platforms, slowing real-time credit decisioning.
- Cross-border titling complexity:Fleet operators managing multi-country portfolios face fragmented registration-transfer rules that extend vehicle redeployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Leasing Market |
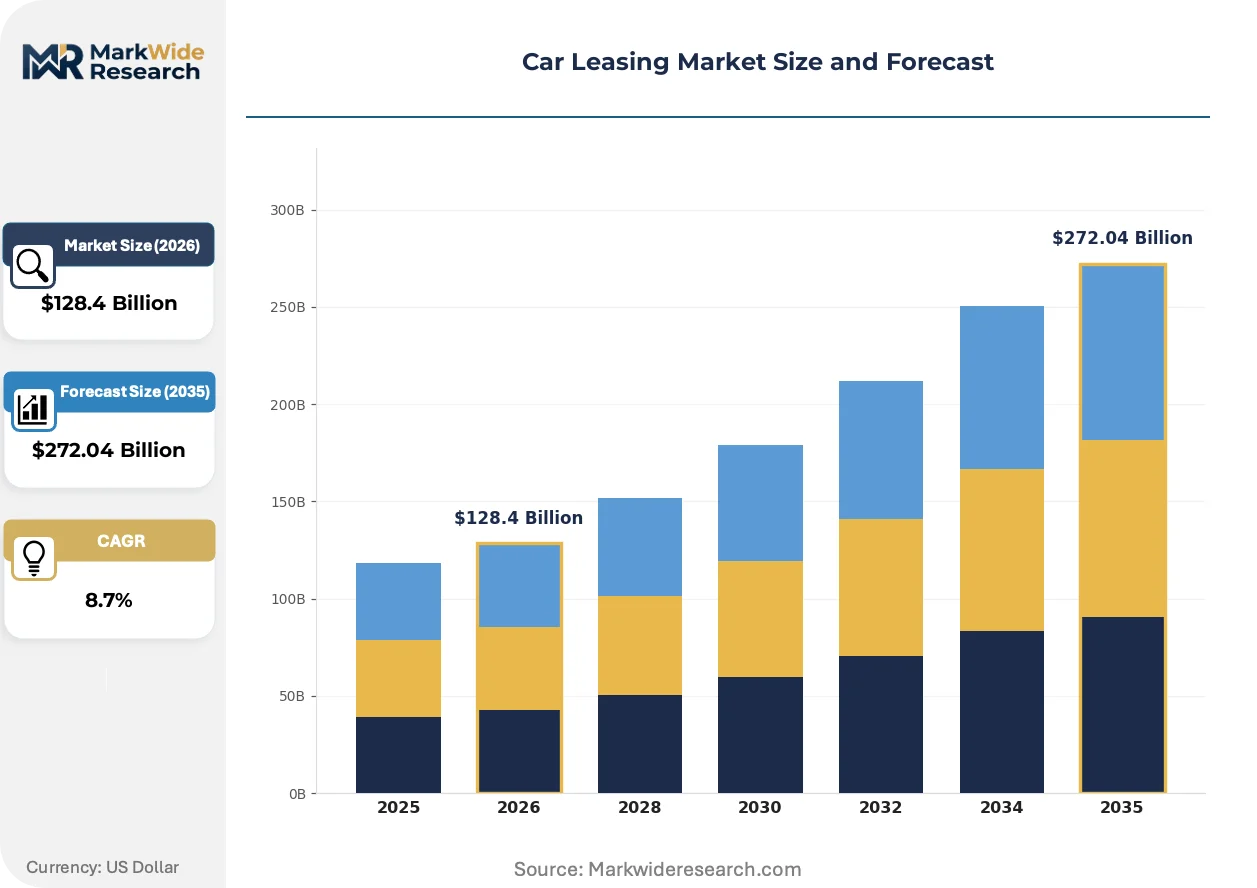
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $272.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lease Type: Open-End, Closed-End, Single-Payment, Subvented Lease Vehicle Category: Sedan, SUV, Coupé, Convertible, Hatchback Customer Segment: Individual Consumers, Small Business Owners, Fleet Operators, Government Entities Sales Channel: Direct Dealer, Broker Services, Online Platforms, Corporate Leasing Programs |
| Companies Covered | Enterprise Holdings Inc., Hertz Global Holdings Inc., General Motors Financial Company, Inc., Daimler Mobility AG, LeasePlan Corporation NV, Ford Motor Credit Co Llc, Avis Budget Group Inc., Turo Inc., Ally Financial Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Leasing Market Strategic Shifts & Innovations
Digital origination platforms and embedded telematics are restructuring how lessors assess risk, price contracts, and manage vehicle lifecycles, compressing the gap between consumer expectations and legacy operational workflows.
Battery-electric vehicle leasing is bifurcating the market into technology-forward lessors with dedicated EV residual-modeling capabilities and traditional players dependent on internal-combustion depreciation curves. Early-adopter fleets in Nordic countries and California are migrating to EV-first lease structures, while mainstream lessors hesitate until secondary-market data accumulates. This divergence is compressing market share for generalist lessors unable to fund specialized EV analytics teams.
The EPA's tightening emissions standards and the EU's CO2 fleet-average mandates are accelerating lease-term compression as corporate fleets cycle vehicles faster to maintain compliance. Manufacturers with captive finance arms are responding by embedding regulatory-compliance guarantees into lease contracts, transferring emissions-risk exposure from lessees to lessors. This shift most acutely affects full-size SUV and light-truck segments where electrification timelines lag passenger-car categories.
Fleet procurement patterns are fragmenting as remote-work policies reduce centralized commuting demand and shift vehicle utilization toward pooled, hour-by-hour access models. Large employers in technology and professional-services verticals are unbundling traditional assigned-vehicle benefits in favor of mobility allowances redeemable across lease, subscription, and shared-fleet channels. This behavioral pivot is most visible in metropolitan corridors of Germany, the United Kingdom, and the northeastern United States where public-transit alternatives reduce sole-vehicle dependency.
Car Leasing Market Segmentation
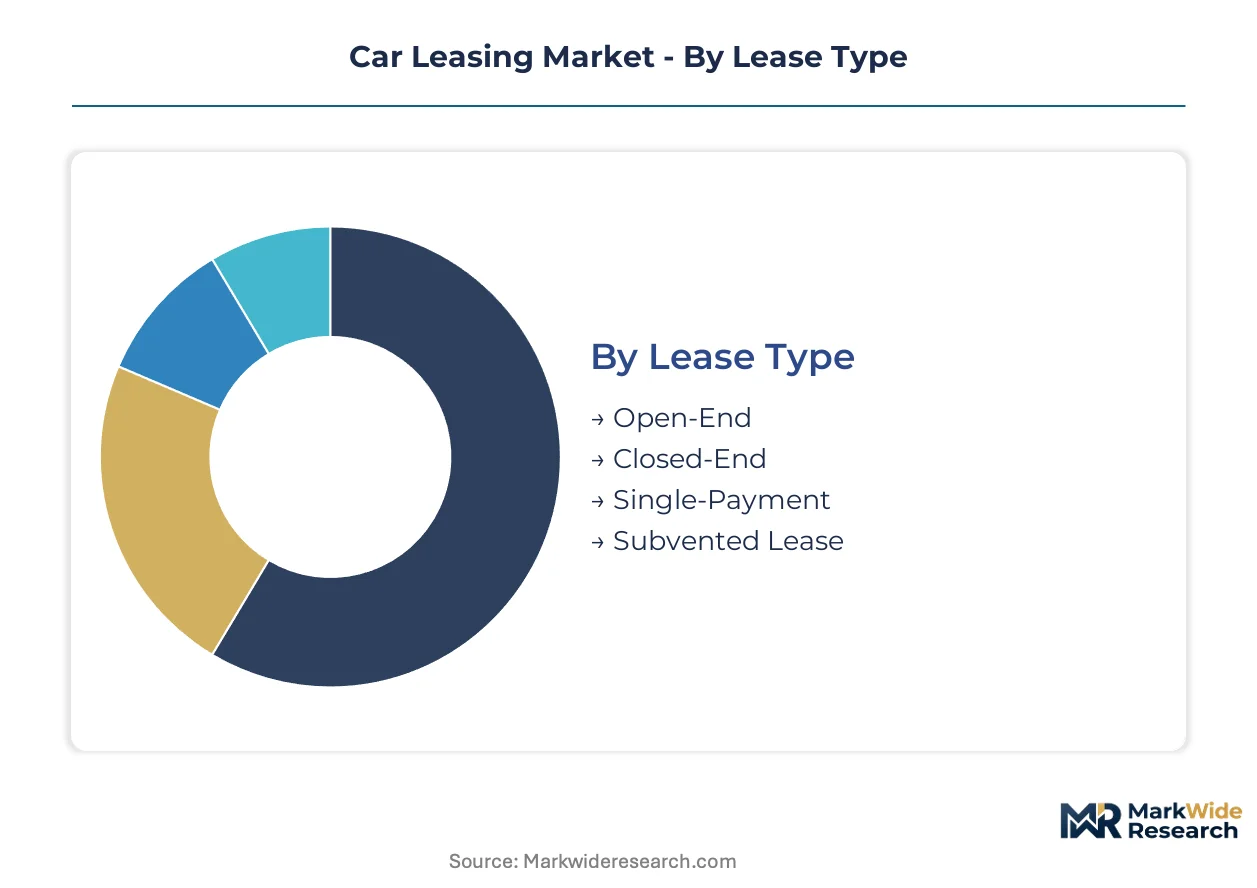
Car leasing segmentation reveals divergent risk-transfer mechanisms across customer types, with closed-end structures dominating individual channels while fleet operators absorb residual exposure through open-end contracts. Channel fragmentation between digital platforms and captive dealer networks reshapes origination economics and customer acquisition costs.
Lease Type:
Geographic concentration varies sharply by lease structure, with closed-end penetration deepest in Germany and the United States where consumer protection frameworks cap lessee liability, while open-end structures concentrate in Japan and South Korea's corporate fleet corridors.
- Closed-End:Fixed-term contracts transfer all residual-value risk to lessors, with mileage penalties enforcing contract discipline. Demand concentrates among individual consumers in Germany and California where household budgets favor predictable monthly obligations over ownership uncertainty.
- Open-End:Lessees bear variable resale outcomes, typically with depreciation reserves adjusted post-term. Fleet operators in Japan and the Netherlands dominate uptake, accepting price volatility in exchange for customized term flexibility and early-termination rights.
- Single-Payment:Upfront lump-sum arrangements eliminate monthly servicing costs for cash-rich lessees seeking simplified accounting.
- Subvented Lease:OEM-subsidized rates absorb residual risk during new-model launches, concentrated in South Korea and Japan where captive finance arms align with production cycles.
Closed-end commands the established base. The steepest expansion runs through subvented structures as manufacturers deploy lease subsidies to accelerate EV adoption.
Vehicle Category:
Cost-tier stratification separates premium-body configurations from utility-focused segments, with margin profiles diverging based on residual forecasting complexity and secondary-market liquidity depth.
- SUV:Elevated ride height and flexible cargo capacity define the segment, with demand concentrating in Texas and the American Southeast where fuel-price sensitivity historically lagged coastal markets. Electrification timelines lag passenger cars, compressing lease terms for compliance.
- Sedan:Three-box configurations with dedicated trunk compartments retain fleet share in Germany and Japan where executive transport conventions persist. Corporate leasing penetration remains highest here due to standardized residual models.
- Coupé:Two-door fixed-roof bodies target enthusiast segments with shorter average lease terms reflecting faster style obsolescence.
- Convertible:Retractable-roof designs concentrate in Mediterranean climates and coastal California, with highly seasonal demand patterns.
- Hatchback:Two-box bodies with integrated cargo access dominate European urban cores where parking constraints favor compact footprints.
Sedan retains the volume base. The steepest expansion trajectory belongs to SUV electrification variants as battery platforms enable compliance without utility sacrifice.
Customer Segment:
Procurement sophistication separates segments, with fleet operators deploying telematics-integrated tendering while individual consumers respond to digital origination friction reduction.
- Fleet Operators:Multi-vehicle portfolios managed through centralized procurement leverage scale for customized terms and maintenance bundling. Demand concentrates in Germany's corporate corridor and the Netherlands where mobility-budget experimentation advances fastest.
- Individual Consumers:Personal-use lessees prioritize monthly payment predictability and warranty coverage over ownership equity accumulation. Urban households in London and New York exhibit highest subscription-to-lease migration rates.
- Small Business Owners:Owner-operator structures blend personal and commercial use, creating tax-optimization complexity across jurisdictions.
- Government Entities:Public-sector procurement favors domestic OEMs through mandated fleet-localization rules in France and South Korea.
Fleet operators command the established base. The steepest expansion runs through individual consumers as digital platforms reduce origination friction for first-time lessees.
Sales Channel:
Channel maturity stratifies between legacy dealer networks with captive finance integration and insurgent digital platforms unburdened by physical infrastructure depreciation.
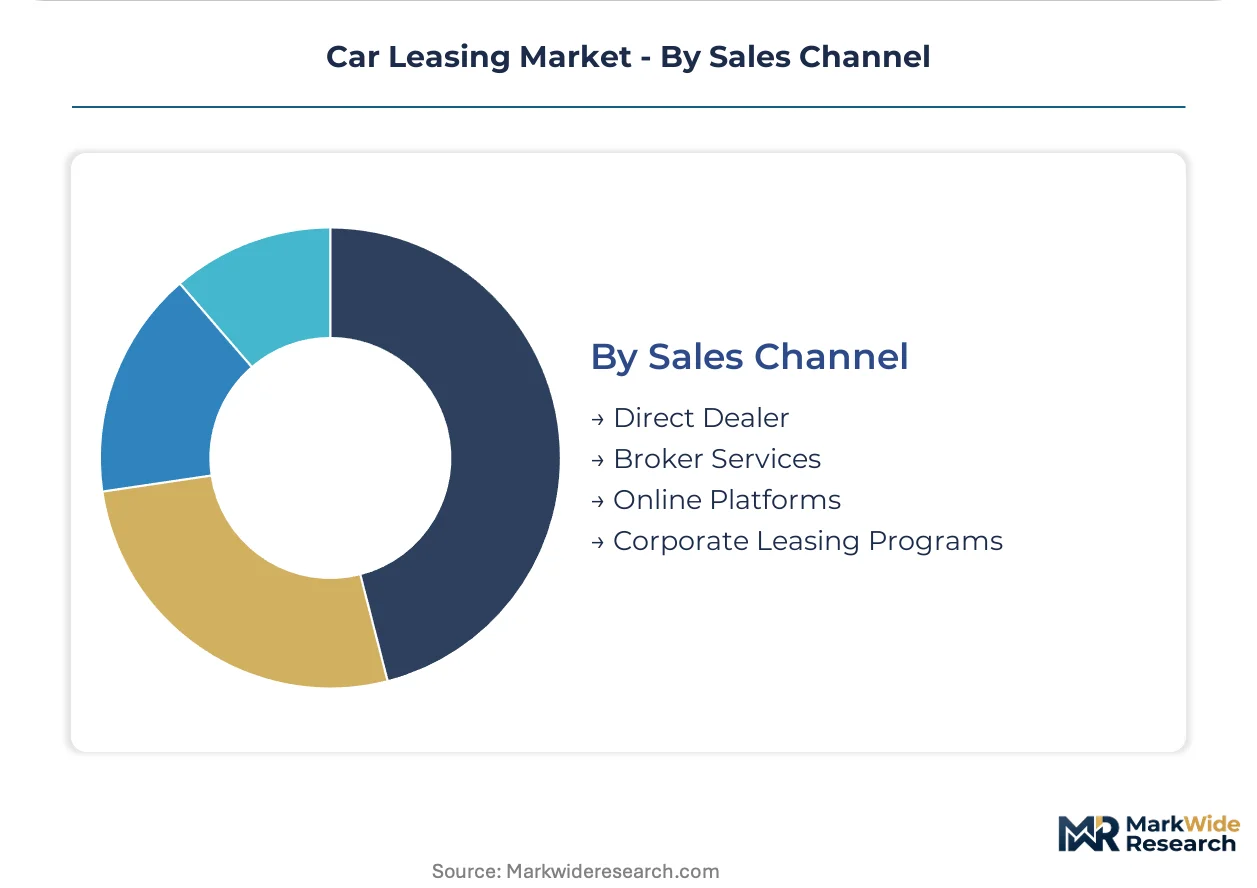
- Online Platforms:Digital origination compresses credit-decision timelines from days to minutes through API-integrated scoring. Demand concentrates among tech-sector employees in Seattle and Bangalore where remote-purchase conventions established earliest.
- Direct Dealer:Captive-finance-aligned showrooms offer subvented rates tied to manufacturer inventory priorities. Germany's dense OEM-owned network sustains highest penetration globally.
- Broker Services:Independent intermediaries aggregate lessor quotes for price-sensitive segments, with regulatory scrutiny intensifying under the Consumer Financial Protection Bureau's disclosure enforcement.
- Corporate Leasing Programs:Employer-embedded enrollment channels leverage payroll deduction and bulk-negotiated terms, concentrated in Japan's keiretsu-affiliated enterprises.
Direct dealer commands the established base. The steepest expansion runs through online platforms as telematics-enabled remote underwriting matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in automotive finance services while the United States and Japan balance substantial domestic leasing volumes with cross-border fleet management exports. Import dependence concentrates in lithium-ion battery supply chains feeding electric lease fleets across all major markets.
Germany
Corporate fleet demand drives volume through the Rhine-Ruhr and Stuttgart corridors where OEM captive finance arms cluster. The EU F-Gas Regulation accelerates replacement cycles for commercial vehicles with refrigerant compliance deadlines. Munich anchors multi-country fleet administration operations serving pan-European lessees.
United States
Airport and neighborhood rental fleet operators sustain utilization-based leasing models across Texas and California metropolitan zones. The EPA's tightening emissions standards compress lease terms for light-truck segments awaiting electrification timelines. Detroit retains captive finance headquarters tied to manufacturer production cycles.
Japan
Keiretsu-affiliated enterprises deploy corporate leasing programs with payroll-deducted payments concentrated in Tokyo and Osaka. METI guidelines shape residual-value disclosure standards for consumer protection. Nagoya's automotive engineering cluster supports telematics integration for usage-based pricing.
South Korea
Captive finance arms align subvented lease rates with domestic manufacturer launch schedules in the Seoul Capital Area. The MFDS regulates embedded telematics data collection for driver-behavior monitoring. Busan-Ulsan hosts fleet redeployment infrastructure for secondary-market vehicle flows.
India
GST input-credit improvements expand corporate leasing penetration among Maharashtra and Karnataka technology employers. The RBI monitors non-banking financial company lessor capital adequacy for residual-value exposure. Delhi-NCR experiments with mobility-budget structures replacing assigned-vehicle benefits.
Car Leasing Market Key Industry Players
Concentration sits with captive finance arms and integrated fleet operators who control residual-value risk through vertical infrastructure. The market structures around three tiers: manufacturer-owned lessors with production-cycle alignment, independent fleet specialists with multi-country administration capabilities, and digital-native platforms unburdened by physical asset depreciation. Strategic moves center on telematics-enabled pricing diversification and battery-health certification programs for secondary-market liquidity.
Within the captive finance tier, General Motors Financial Company, Inc. and Daimler Mobility AG exemplify manufacturer-tied structures that absorb residual exposure during new-model launches. Enterprise Holdings Inc. anchors the integrated fleet operator archetype through combined airport and neighborhood utilization management. LeasePlan Corporation NV occupies a position among multi-country specialists with centralized procurement and cross-border titling expertise.
| Leading Market Players |
|---|
| Enterprise Holdings Inc. |
| Hertz Global Holdings Inc. |
| General Motors Financial Company, Inc. |
| Daimler Mobility AG |
| LeasePlan Corporation NV |
| Ford Motor Credit Co Llc |
| Avis Budget Group Inc. |
| Turo Inc. |
| Ally Financial Inc. |
| Others |
Cost & Logistics Intelligence
Closed-end lease contracts lock in predictable monthly obligations for lessees while transferring residual-value exposure to lessors, embedding semiconductor procurement timelines and battery cost volatility directly into rate-setting frameworks across Germany, Japan, and the United States.
Pricing Analysis
Corporate fleet operators anchor lease pricing through multi-year master service agreements that negotiate volume-scaled rates against telematics-enabled usage data. Three-tier pricing structure across premium, standard, and economy levels separates full-service maintenance bundles from bare-metal rentals. Cost compression in EV lease tiers is intensifying because lithium-ion raw-material swings force wider residual-value cushions. Small business owners exhibit highest price sensitivity due to cash-flow constraints, while government entities leverage mandated localization rules for rate advantages.
Supply Chain Analysis
Taiwan Strait semiconductor transit underwrites just-in-time vehicle electronics delivery for lessor fleet configurations across North American and European markets. Manufacturing concentrates in Germany, Japan, and South Korea for precision powertrain components, while China, Indonesia, and Australia feed critical mineral streams for battery cell production. Raw-material dependencies center on nickel, cobalt, and lithium carbonate shipments. Single-source vulnerability from TSMC fabrication dominance creates delivery-timeline uncertainty. Distribution runs through captive dealer networks aligned with OEM finance arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription mobility services pose direct substitution threats to traditional closed-end leasing structures, forcing incumbents to defend contract origination volumes against flexible, short-term alternatives.
For Market Incumbents: Compound residual-value modeling capabilities through machine-learning talent acquisition and battery-health certification investments. Strengthen captive finance integration with OEM production cycles to absorb EV launch-phase depreciation risk. Defend against digital-native platform entrants by embedding telematics-enabled usage-based pricing that matches subscription flexibility without surrendering contract discipline. For New Entrants and Emerging Players: Lead with battery-as-a-service decoupling in India and Southeast Asian markets where GST input-credit rules are improving and organized used-car channels remain underdeveloped. Target corporate fleet operators migrating from assigned-vehicle benefits toward mobility-budget structures. Deploy API-first origination platforms that compress credit-decision timelines below incumbent mainframe-limited workflows. For Investors and Strategic Acquirers: Telecommunications-integrated fleet analytics specialists with proven EV residual-modeling track records command premium positioning as electrification disrupts historical depreciation curves. Long-term viability hinges on secondary-market liquidity creation for off-lease battery-electric vehicles. Monitor battery-health standardization adoption rates across Germany and California as inflection indicators for used-lease market depth.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time driver-behavior data enables usage-based pricing expansion into low-mileage urban households. |
| Battery Supply Agreement | Long-term cell procurement contracts stabilize EV lease margin predictability against raw-material volatility. |
| Residual-Value Securitization | ABS structures tap institutional capital pools to fund lessor balance-sheet expansion. |
| Charging Infrastructure Partnership | Workplace and residential charging access bundles reduce lessee range anxiety and early-termination rates. |
| Geographic Manufacturing Footprint | Regional assembly proximity to fleet demand centers compresses delivery timelines and titling complexity. |
Research Approach
The analysis maps closed-end consumer leasing, open-end fleet administration, and subscription mobility services, each validated through fleet procurement directors, captive finance risk officers, telematics platform engineers, and used-car remarketing specialists. Primary fieldwork combined with secondary validation draws from SEC residual-value securitization filings, EU F-Gas regulatory timelines, vehicle production databases, and IHS Markit registration data. Bottom-up lease origination volume estimates triangulate against top-down automotive finance market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include lease structure type, vehicle propulsion architecture, customer procurement sophistication tier, and regional regulatory cluster. CAGRs were derived from regression analysis of historical fleet turnover rates and electrification compliance timelines. Forecast inputs incorporate battery degradation curve assumptions and telematics penetration trajectories.
Forecasts assume regulatory continuity in EPA emissions standards and EU F-Gas phaseout schedules; material policy shifts would require re-modeling lease-term compression assumptions. Practitioners should keep alternative scenarios live as semiconductor supply concentration and lithium-ion cost volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Russia Auto Loan Market