
 Europe Mortgage Lending Market | 2026-2036
Europe Mortgage Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mortgage Lending Market Insights
Digital underwriting automation is narrowing the cost gap between direct banks and mortgage brokers across Europe. Deutsche Bank leverages its integrated retail platform to control origination workflows from application to securitization. ING Group anchors its competitive position through proprietary algorithmic risk scoring that compresses decision timelines. HSBC Holdings competes by extending cross-border lending capabilities that serve mobile professional segments in London, Paris, and Frankfurt.
Europe mortgage lending encompasses secured credit instruments collateralized by residential or commercial real estate, typically structured with loan-to-value ratios between 60% and 90% and amortization horizons spanning 15 to 30 years, functioning to channel household savings and institutional capital into property ownership and housing stock maintenance. Fixed-rate mortgages dominate origination volumes in Germany and France where borrowers prioritize payment certainty over rate flexibility, while interest-only mortgages retain structural importance in the Netherlands where tax treatment of debt servicing sustains demand among higher-income homeowners. Online lenders represent the fastest-growing distribution channel as regulatory sandboxes in multiple jurisdictions lower barriers to digital-first entry.
The European Banking Authority and national regulators including Germany's BaFin and France's ACPR enforce capital adequacy and consumer protection standards that shape product design, disclosure requirements, and stress-testing protocols for mortgage portfolios. The EU Green Deal and national building codes are creating segmented eligibility criteria that tie loan pricing to energy performance certificates. Stakeholders must monitor how the EU AI Act and forthcoming algorithmic accountability rules reshape automated underwriting and fair-lending compliance obligations.
Market Dynamics
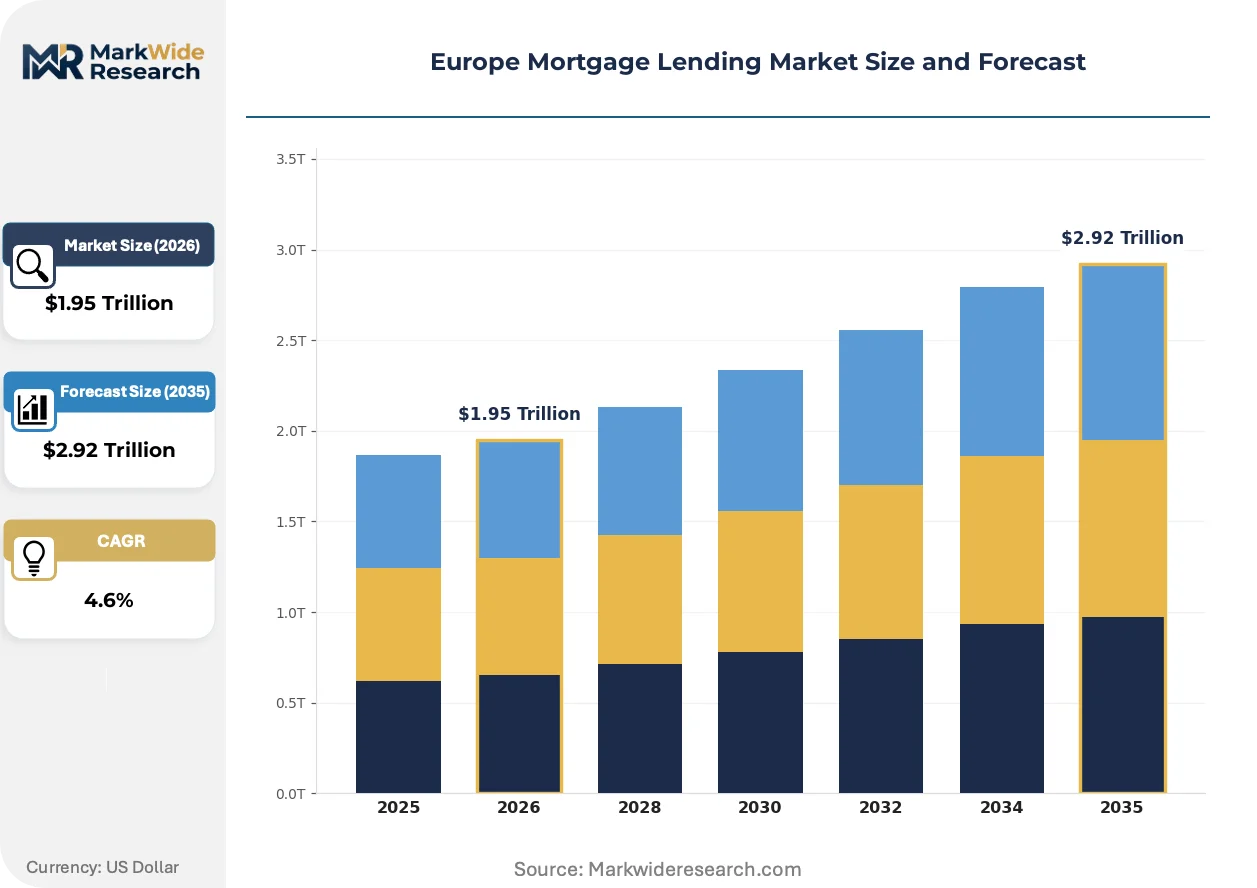
Digital underwriting automation is compressing origination costs and compressing the competitive window between incumbent banks and fintech challengers across European mortgage markets. The EU Green Deal's energy-efficiency mandates are restructuring loan eligibility criteria and pricing frameworks, redirecting capital flows toward renovation-linked products.
Growth Catalysts
- EU Green Deal building renovation mandates:National energy-performance certificates now gate access to preferential loan rates, stimulating demand for green mortgage products tied to retrofit financing.
- Algorithmic risk-scoring platforms:Automated credit decision engines are collapsing approval timelines from weeks to hours, expanding lender capacity to serve first-time buyer segments.
- Germany's urban housing shortage:Chronic undersupply in Berlin, Munich, and Frankfurt sustains origination volumes and refinancing activity despite rate volatility.
Market Restraints
- Interest rate volatility:ECB policy uncertainty is widening bid-ask spreads on fixed-rate products and compressing net interest margins for originators.
- Collateral valuation concentration:Automated valuation models rely on limited transactional data in secondary cities, creating systemic risk in stress scenarios.
- Regulatory fragmentation:Divergent national implementation of EBA capital requirements creates compliance complexity for cross-border lenders operating in multiple jurisdictions.
Strategic Opportunities
- Netherlands interest-only refinancing wave:Maturing tax-advantaged loans create a captive audience for product switching and cross-selling of energy-efficiency upgrades.
- Embedded finance distribution:Property technology platforms and real estate marketplaces are emerging as origination channels, bypassing traditional broker networks.
- EU AI Act compliance services:Algorithmic accountability rules create advisory and audit revenue streams for firms navigating automated underwriting transparency requirements.
Industry Challenges
- Legacy core system integration:Incumbent banks face technical debt when connecting cloud-native underwriting tools to decades-old loan servicing infrastructure.
- ESG data verification:Energy-performance certificate fraud and inconsistent building audit standards undermine the integrity of green mortgage pricing differentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mortgage Lending Market |
| Market Size in 2026 | $1.95 Trillion |
| Market Size in 2035 | $2.92 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Rate Mortgages, Adjustable-Rate Mortgages, Interest-Only Mortgages, FHA Loans End User: First-Time Buyers, Refinancers, Investors, Homeowners Distribution Channel: Direct Banks, Mortgage Brokers, Online Lenders, Credit Unions Loan Amount: Low-Value Loans, Mid-Value Loans, High-Value Loans, Jumbo Loans |
| Companies Covered | Interhyp AG, London & Country Mortgages, Mortgage Advice Bureau, Dr. Klein, Connells Group, BNP Paribas SA, Deutsche Bank, HSBC Holdings, ING Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mortgage Lending Market Trends and Innovations
Open banking data sharing is dissolving information asymmetries between lenders and borrowers, enabling real-time income verification and dynamic risk repricing. This infrastructure shift is reconfiguring competitive advantage toward data aggregation capabilities and away from branch density.
Automated property valuation models is hybridizing satellite imagery, municipal permit databases, and transactional comparables to generate collateral assessments without physical inspection. Dutch and German lenders are deploying these tools for refinance originations where speed outweighs precision requirements. The technology is hybridizing cost structures and compressing the role of traditional surveyors in standardized property segments.
The EU AI Act's algorithmic transparency requirements are mandating explainability standards for automated credit decisions that affect consumer outcomes. Lenders must now document feature importance and bias testing protocols for machine learning underwriting models. French and German regulators are conducting the first wave of compliance examinations, forcing institutions to retrofit existing decision engines with interpretability layers.
First-time buyers are aggregating through digital mortgage marketplaces that commoditize rate comparison and streamline documentation submission. Broker platforms in France and Spain are capturing an expanding share of origination volume by bundling notary services and insurance products. This channel migration is most pronounced among urban professionals aged 25-35 seeking financing for compact apartments in Paris, Barcelona, and Milan.
Europe Mortgage Lending Market Segmentation
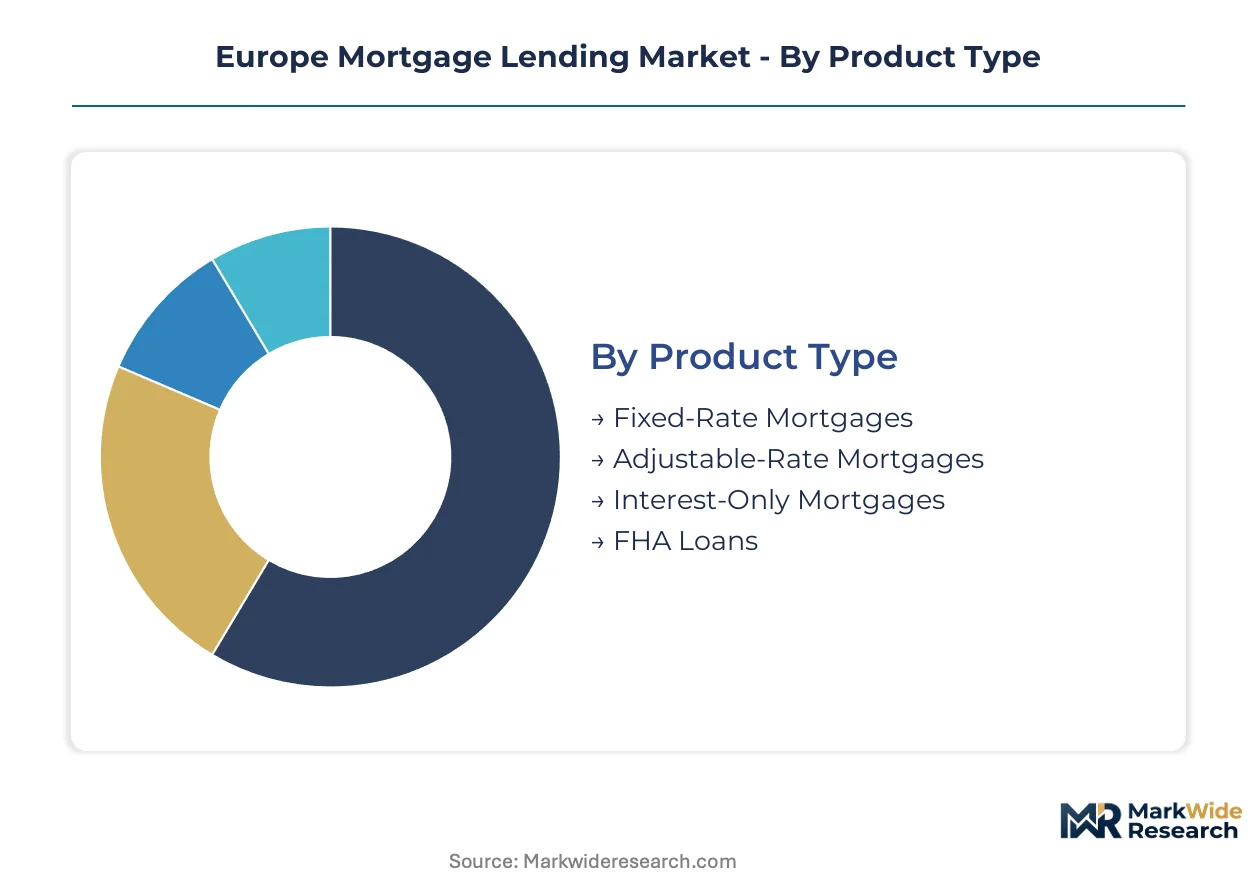
Mortgage product design varies sharply across borrower profiles and distribution economics in Europe. Lenders calibrate pricing, risk weighting, and servicing infrastructure to the distinct origination cadence and retention characteristics of each segment.
Product Type:
Fixed-rate products lock in spreads for decades while adjustable structures reprice within months, creating divergent balance sheet velocity across originator portfolios.
- Fixed-Rate Mortgages:Long-duration contracts with locked nominal rates dominate German and French origination volumes where borrowers prioritize payment certainty over rate flexibility. Deutsche Bank and BNP Paribas anchor their retail deposit strategies around these sticky liabilities.
- Adjustable-Rate Mortgages:Floating-rate instruments tied to Euribor or national reference rates concentrate in Spain and Portugal where central bank policy transmission is immediate and household rate sensitivity is lower.
- Interest-Only Mortgages:Dutch tax treatment sustains structural demand among higher-income homeowners in Amsterdam and Rotterdam seeking maximum leverage efficiency.
- FHA Loans:Government-backed instruments with explicit credit guarantees support first-time buyer access in markets with thin private mortgage insurance depth.
Fixed-Rate Mortgages anchors the volume base while Interest-Only Mortgages gains share at the steepest rate.
End User:
Borrower lifecycle position determines origination cost, cross-sell potential, and default probability in lender underwriting models.
- First-Time Buyers:Entry-level borrowers with limited credit histories and elevated loan-to-value ratios drive automated underwriting investment at ING Group and HSBC Holdings. Berlin, Munich, and Frankfurt housing shortages sustain origination pipelines.
- Refinancers:Seasoned borrowers with established payment trackbooks and accumulated home equity generate the lowest acquisition costs and highest lifetime value metrics for direct banks.
- Investors:Non-owner-occupied financing faces stricter capital requirements under EBA guidelines and higher interest rate spreads in France and Germany.
- Homeowners:Existing property holders seeking renovation-linked green mortgages respond to EU Green Deal energy-efficiency pricing incentives.
Refinancers contributes the largest profit pool while First-Time Buyers expands most quickly.
Distribution Channel:
Channel economics range from branch-heavy fixed cost structures to variable-cost digital platforms with divergent scale efficiencies.
- Direct Banks:Integrated deposit-lending institutions like Deutsche Bank control full origination-to-securitization workflows and capture maximum margin per loan.
- Mortgage Brokers:Independent intermediaries dominate French and Spanish markets by bundling notary services and insurance products for urban professionals.
- Online Lenders:Digital-first entrants leverage regulatory sandboxes and open banking data to collapse approval timelines from weeks to hours.
- Credit Unions:Member-owned cooperatives concentrate in Netherlands and Ireland with relationship-based underwriting and limited geographic reach.
Direct Banks holds the revenue concentration while Online Lenders climbs the fastest.
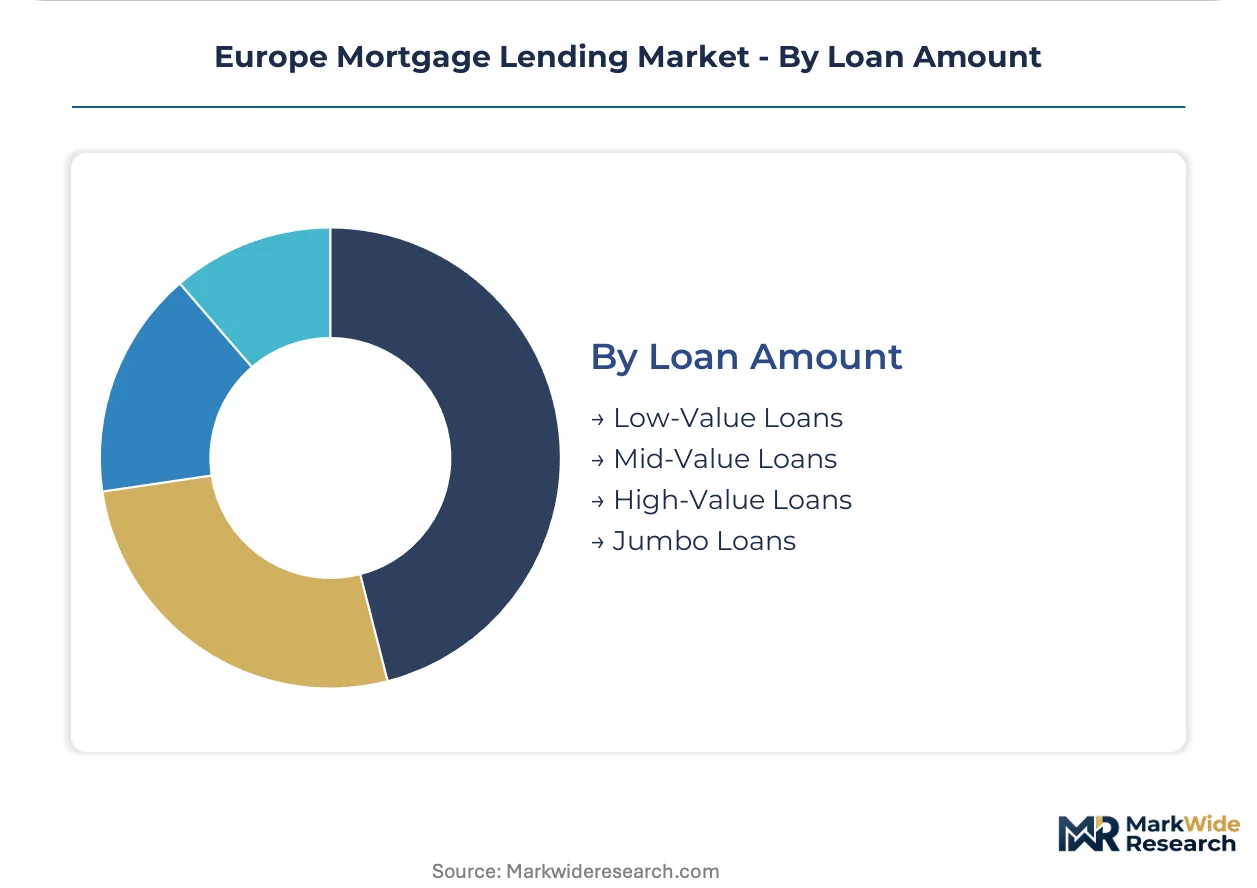
Loan Amount:
Ticket size stratifies origination economics, collateral valuation protocols, and secondary market liquidity access for European lenders.
- Low-Value Loans:Sub-€100,000 originations serve peripheral urban markets and secondary cities with automated valuation model dependency and higher per-unit processing costs.
- Mid-Value Loans:€100,000-€400,000 segments align with median property values in Paris, Barcelona, and Milan condominium markets.
- High-Value Loans:Premium financing for central district properties triggers manual underwriting and bespoke pricing at private banking divisions.
- Jumbo Loans:Super-conforming exposures exceeding national guarantee limits concentrate in London, Geneva, and Luxembourg cross-border professional segments.
Mid-Value Loans anchors origination volume while Jumbo Loans delivers the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mortgage lenders export refinancing expertise to Dutch and French markets seeking automated underwriting platforms. Cross-border capital flows from Frankfurt and Amsterdam now finance housing stock renovation across the Low Countries and Northern France.
Germany
Berlin, Munich, and Frankfurt sustain origination volumes through chronic urban housing shortages and first-time buyer pipeline expansion. BaFin enforces EBA capital adequacy standards that shape stress-testing protocols for mortgage portfolios. The Rhine-Ruhr corridor anchors automated valuation model deployment for mid-value loan segments.
France
Paris and Lyon condominium markets drive mid-value loan demand among urban professionals aged 25-35. ACPR disclosure requirements and consumer protection standards govern product design for green mortgage eligibility. The Île-de-France region concentrates broker platform activity bundling notary services with rate comparison tools.
Netherlands
Amsterdam and Rotterdam sustain structural demand for interest-only mortgages through tax-advantaged debt treatment among higher-income homeowners. National energy-performance certificates now gate preferential loan rates under EU Green Deal implementation. The Randstad cluster channels refinancing waves toward energy-efficiency upgrade cross-selling.
United Kingdom
London anchors cross-border lending capabilities serving mobile professional segments from Paris and Frankfurt. Open banking infrastructure enables real-time income verification collapsing approval timelines for digital-first entrants. The Southeast corridor concentrates jumbo loan origination for premium central district properties.
Spain
Barcelona and Madrid drive adjustable-rate mortgage demand where ECB policy transmission reaches households with lower rate sensitivity. National regulators align EBA guidelines with local consumer protection frameworks for automated underwriting transparency. Mediterranean coastal cities attract investor financing facing stricter capital requirements under non-owner-occupied guidelines.
Europe Mortgage Lending Market Competitive Landscape
Channel-controlling players compete with product-specialist players across origination-to-securitization workflows and broker-intermediated distribution. The market structure tiers between integrated deposit-lending institutions with captive funding bases and digital-first entrants leveraging regulatory sandboxes. Two strategic archetypes dominate: full-stack retail banks controlling margin capture end-to-end, and algorithmic specialists compressing decision timelines through automated risk scoring. Competitive moves center on embedded finance partnerships with property technology platforms and retrofit advisory services bundling energy audits with loan origination.
Within the integrated banking tier, Deutsche Bank and BNP Paribas occupy positions anchoring retail deposit strategies around fixed-rate product stickiness. ING Group exemplifies the algorithmic specialist archetype through proprietary risk-scoring platforms. Among broker-intermediated channels, Interhyp AG and Dr. Klein represent the independent advisory model bundling notary and insurance services for first-time buyer segments.
| Leading Market Players |
|---|
| Interhyp AG |
| London & Country Mortgages |
| Mortgage Advice Bureau |
| Dr. Klein |
| Connells Group |
| BNP Paribas SA |
| Deutsche Bank |
| HSBC Holdings |
| ING Group |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's container cost dynamics amplify pricing power for deposit-rich lenders in Frankfurt and Amsterdam while squeezing margin capture for broker-dependent originators in secondary French and Spanish markets. Supply concentration in core banking hubs feeds downstream price differentiation between algorithmic direct lenders and branch-heavy intermediaries.
Pricing Analysis
Technology-generation pricing gaps separate cloud-native underwriting platforms from legacy core system incumbents and emerging AI-act-compliant next-generation engines. Three-tier pricing structure across premium algorithmic scoring, standard automated decisioning, and economy manual underwriting segments dominates origination economics. Price differentiation rests on speed-to-decision and ESG data verification depth as primary drivers. Cost compression in the economy tier intensifies because open banking infrastructure erodes information-rent capture for traditional brokers. First-time buyers exhibit highest price sensitivity while jumbo loan segments in London and Geneva show least elasticity.
Supply Chain Analysis
Upstream feedstock of capital concentrates in Germany, France, and the Netherlands where retail deposit bases and covered bond markets anchor funding pipelines. Wholesale funding draws from ECB liquidity facilities, institutional investor pools, and securitization conduits. Single-source vulnerability runs through ECB policy transmission as the dominant marginal cost setter. Distribution runs through direct banking platforms, broker networks, and embedded finance partnerships with property technology marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
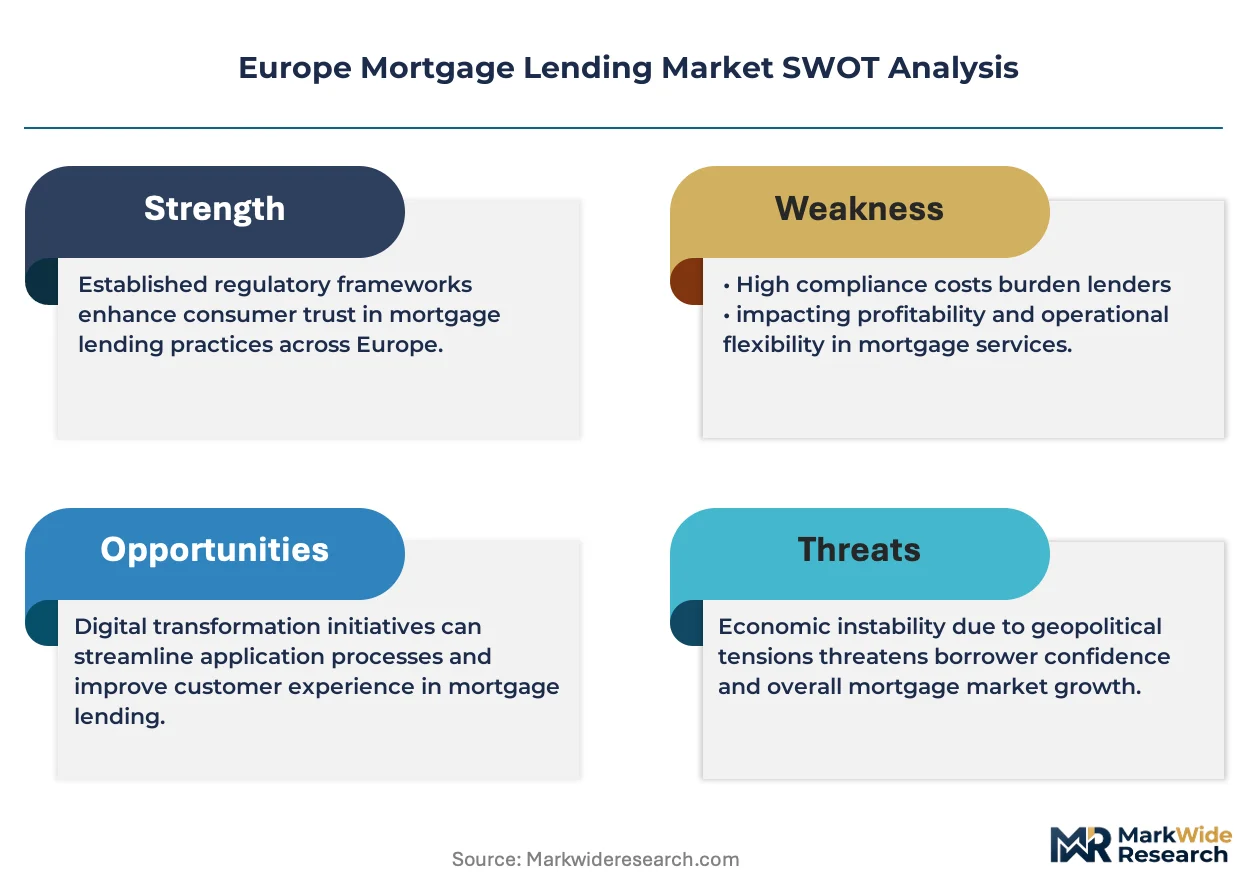
The Europe mortgage lending market constitutes a high-growth disruption as algorithmic underwriting and EU Green Deal energy-efficiency mandates restructure origination economics and product eligibility simultaneously.
For Market Incumbents: Harden core deposit franchises against fintech rate transparency by integrating renovation advisory services that capture EU Green Deal retrofit flows. Fortify automated valuation model governance to preempt EBA scrutiny on collateral concentration risk in secondary cities.
For New Entrants and Emerging Players: Build out embedded finance distribution through property technology platforms serving first-time buyer segments in Berlin, Munich, and Frankfurt where housing shortages sustain origination velocity. Target the Netherlands interest-only refinancing wave with energy-efficiency upgrade bundling as the most penetrable white-space.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier banks with stagnant legacy core systems and concentrated geographic footprints in underpenetrated Spanish and Portuguese adjustable-rate markets. Monitor ECB policy trajectory and EU AI Act enforcement intensity as the critical inflection signal for algorithmic underwriting valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Underwriting Platform Deployment | Compresses decision timelines from weeks to hours for first-time buyer segments. |
| Green Mortgage Product Expansion | Captures EU Green Deal capital flows tied to energy-performance certificate eligibility. |
| Embedded Finance Partnership | Bypasses traditional broker networks through property technology marketplace integration. |
| Automated Valuation Model Investment | Reduces collateral assessment costs for refinance originations in standardized segments. |
| Cross-Border Lending Capability Buildout | Serves mobile professional demand across London, Paris, and Frankfurt corridors. |
Research Methodology
Operator-level perspectives from mortgage origination heads, risk management officers, digital transformation leads, and broker network directors anchored the qualitative base. Secondary validation drew from EBA stress-test disclosures, national regulator bulletins, ECB statistical releases, and covered bond issuance documentation. Bottom-up loan-level modeling triangulated against top-down macroeconomic scenario analysis.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, upside, and downside paths reflecting ECB policy trajectory and housing supply elasticity variations. Segmentation dimensions encompassed product type, end-user lifecycle position, distribution channel economics, and loan amount tiers. CAGRs derived from originator capacity expansion curves and refinancing wave timing. Industry-specific inputs included energy-performance certificate adoption rates and open banking penetration by national market.
Practitioners should monitor ECB deposit facility rate shifts and EU AI Act enforcement precedence for early signals of forecast revision. Cross-checking against ECB mortgage lending statistics and national land registry transaction volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
India Student Loan Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Japan Auto Loan Market