
 Europe Syndicated Loans Market | 2026-2036
Europe Syndicated Loans Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Syndicated Loans Market Insights
Project finance structures with long-dated tenors and limited-recourse features is tilting competitive advantage toward arrangers with deep institutional distribution networks. BNP Paribas leverages its pan-European balance sheet to anchor lead-left positions on cross-border infrastructure facilities. Barclays competes through specialized energy transition desks in London and Frankfurt. Blackstone Credit sustains deployment velocity via direct lending platforms that complement traditional bank syndications.
A syndicated loan is a debt facility underwritten by a group of lenders and structured into multiple tranches with varying seniority, maturity profiles, and pricing grids; documentation typically incorporates financial covenants, collateral packages, and intercreditor agreements governing payment waterfall priority. Its primary purpose is to aggregate sufficient capital for large-scale corporate or project expenditures while distributing credit exposure across institutional portfolios. Corporate loans dominate arranger fee pools due to repeat issuance frequency and relationship pricing power, while project financing tranches command wider margins reflecting construction-phase risk and bespoke due diligence requirements. Floating-rate structures linked to EURIBOR resets occupy the majority of new issuance volume as borrowers seek to transfer interest rate risk to lender syndicates.
The European Banking Authority's supervisory standards on large exposures constrain single-bank hold positions and mechanically expand syndicate participation requirements. EBA guidelines on leveraged transactions and the EU Securitisation Regulation reshape documentation standards for institutional investor eligibility. ECB monetary policy transmission affects pricing benchmarks across the eurozone and periphery markets with divergent timing. Stakeholders must monitor how Basel III endgame implementation alters risk-weighted asset calculations for committed but undrawn revolving facilities.
Market Dynamics
The EU Green Deal is restructuring lender consortium composition by mandating ESG-linked pricing mechanisms across multi-tranche facilities. This regulatory pressure is forcing arrangers to embed sustainability performance targets into margin ratchets and documentation frameworks.
Growth Catalysts
- Offshore wind deployment:German and Dutch utility-scale renewable projects require long-tenor, limited-recourse structures that aggregate institutional capital through syndicated channels. Grid interconnection investments in the North Sea basin are accelerating facility origination.
- EU Taxonomy alignment:The sustainable finance disclosure regulation creates eligibility criteria that direct bank consortium formation toward transition finance mandates. Borrowers meeting technical screening criteria access preferential pricing grids.
- ECB monetary transmission:Divergent rate cycles across eurozone core and periphery markets are compressing pricing benchmarks in France and widening spreads in southern jurisdictions, generating cross-border arbitrage opportunities for multi-currency structures.
Market Restraints
- Basel III RWA compression:Risk-weighted asset calculations for committed revolving facilities are tightening bank balance sheet capacity. Undrawn commitment charges face upward pressure as capital requirements escalate.
- Single-name exposure limits:European Banking Authority large exposure standards mechanically constrain lead bank hold positions. Syndicate participation requirements expand, lengthening execution timelines and documentation complexity.
- EURIBOR transition friction:Benchmark rate reform from EONIA to €STR creates hedging mismatches and fallback clause uncertainty. Legacy contract amendments consume legal resources and delay facility closings.
Strategic Opportunities
- Polish renewable infrastructure:Baltic Sea offshore wind auctions and grid modernization programs remain underpenetrated by established arranger networks. Local currency tranches offer first-mover positioning.
- Direct lending convergence:Alternative credit platforms are integrating with traditional bank syndications to provide stapled financing solutions. Private credit funds assume mezzanine and junior tranche exposure.
- Hydrogen backbone financing:The European Hydrogen Backbone initiative creates dedicated offtake agreements that de-risk project finance structures. Pipeline and storage facilities in the Netherlands and Belgium qualify for green bond eligibility.
Industry Challenges
- ESG data verification:Sustainability-linked margin ratchets require third-party assurance of KPI performance. Borrowers face documentation delays sourcing accredited verification for environmental targets.
- Intercreditor coordination:Multi-tranche structures with institutional term loan B and direct lending components create complex waterfall negotiations. Secured party representative appointments consume closing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Syndicated Loans Market |
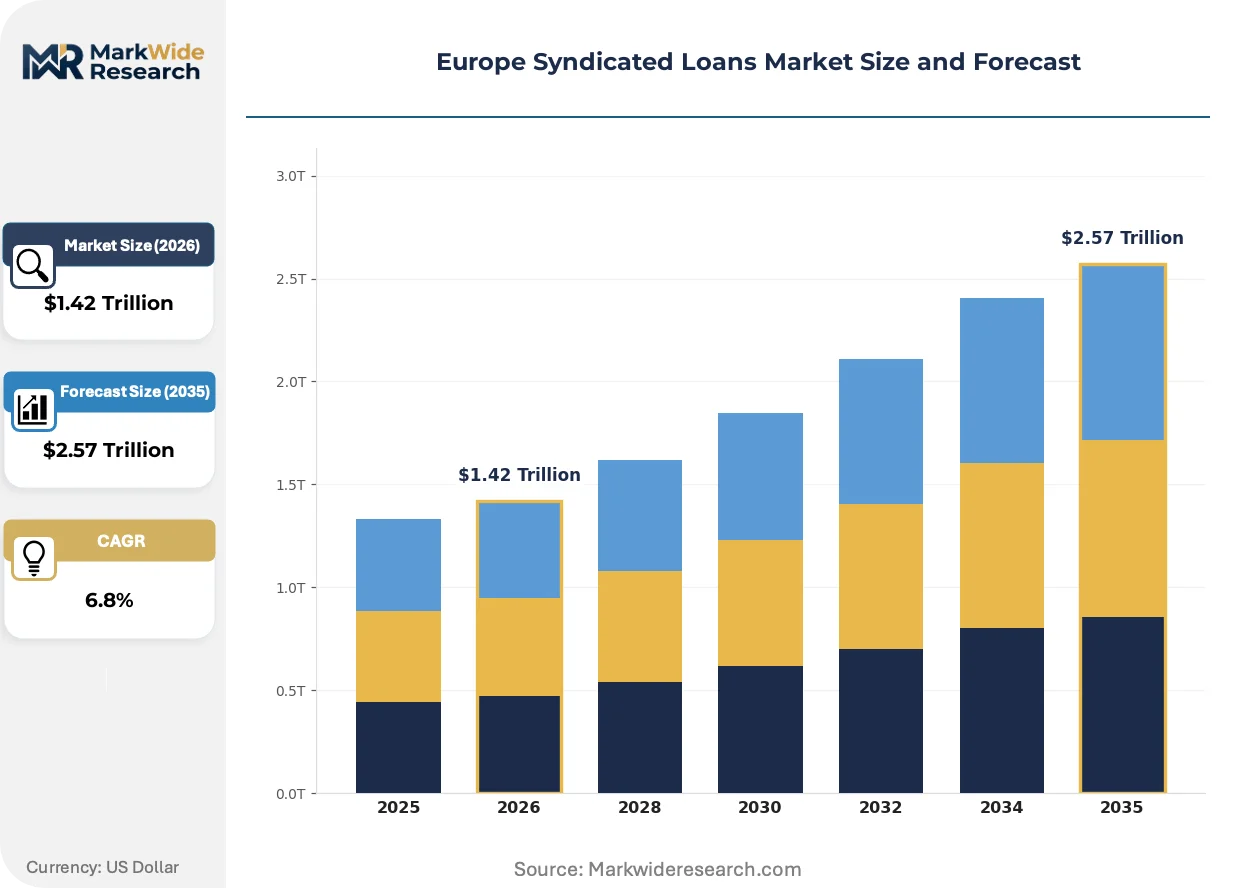
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.57 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Corporate Loans, Real Estate Loans, Acquisition Financing, Project Financing Borrower Type: Private Companies, Public Corporations, Government Entities, Non-Profit Organizations Loan Size: Small Loans, Medium Loans, Large Loans, Jumbo Loans Interest Rate Type: Fixed Rate, Floating Rate, LIBOR-linked, Eurobor-linked |
| Companies Covered | BNP Paribas, BofA Securities, Blackstone Credit, Ares, Arcmont, Lloyds, Barclays, Lazard, PNC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Syndicated Loans Market Trends and Innovations
Digital infrastructure is compressing documentation cycles and enabling real-time syndicate formation across dispersed institutional investors. Virtual data rooms and automated covenant monitoring are displacing traditional closing processes.
Blockchain-based smart contract platforms are virtualizing the execution of margin ratchets and financial covenant testing. Nordic pension funds and Dutch insurance asset managers are piloting automated compliance verification for sustainability-linked facilities. This virtualization is compressing administrative agent functions and enabling disintermediation of traditional trustee roles.
The EU Securitisation Regulation is reshaping institutional investor eligibility criteria for leveraged loan tranches. Risk retention rules and transparency requirements are narrowing the qualified buyer pool for certain mezzanine exposures. CLO managers in Ireland and Luxembourg are restructuring warehousing arrangements to maintain compliance.
Corporate treasury departments are consolidating banking relationships and demanding integrated cash management with credit facilities. Single-bank RFP processes are displacing multi-arranger beauty contests for investment-grade borrowers. French and German multinational corporations are centralizing liquidity structures through pan-European revolving credit platforms.
Europe Syndicated Loans Market Segmentation
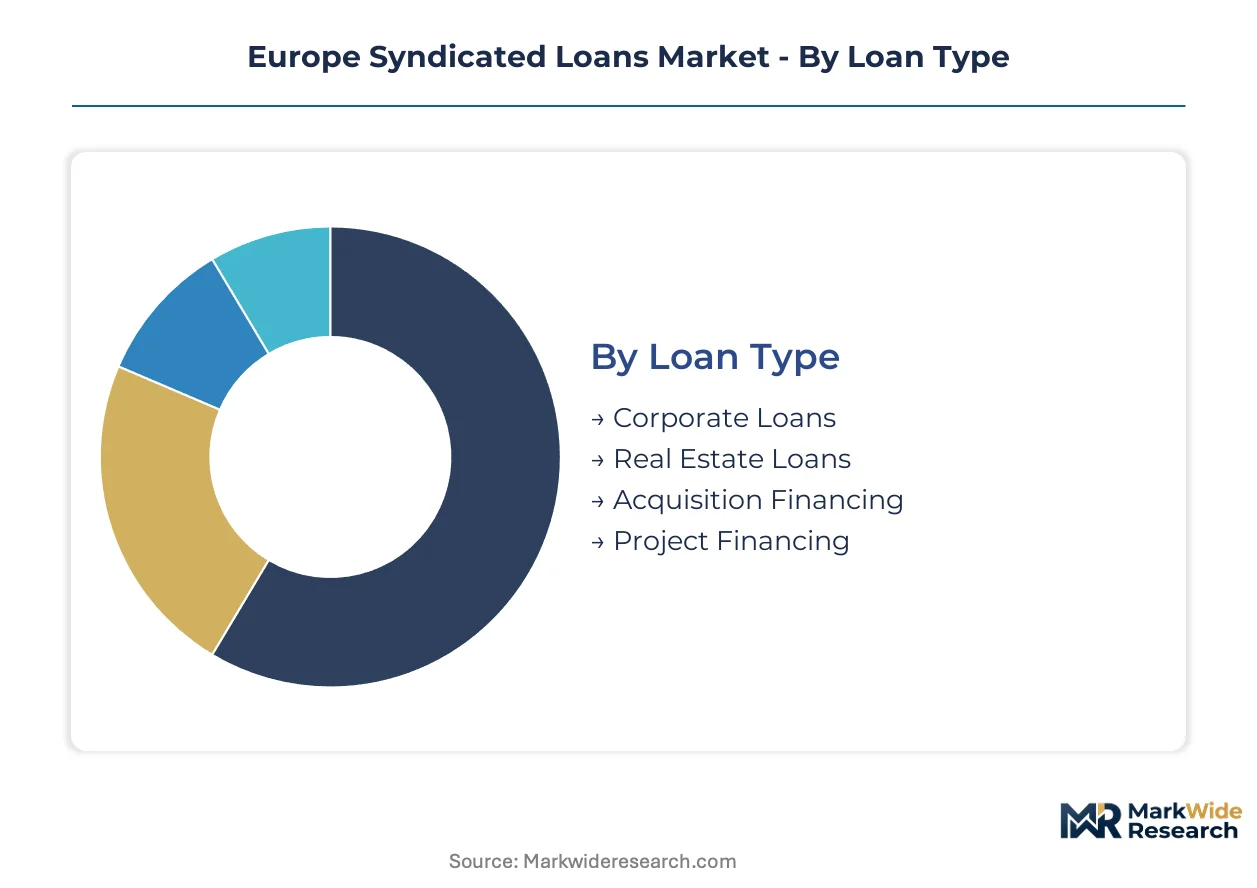
Segmentation in the Europe Syndicated Loans Market determines arranger specialization, documentation complexity, and distribution strategy. Loan type and borrower classification dictate covenant structures, while interest rate mechanics shape institutional investor appetite across tranche seniority.
Loan Type:
Corporate loans turn over fastest with repeat issuance cycles, while project financing extends across construction and operational phases lasting a decade or more.
- Corporate Loans:Revolving credit facilities and term loans support working capital and general corporate purposes. German and French multinationals dominate issuance volume through relationship-driven mandates with pan-European banks.
- Project Financing:Non-recourse or limited-recourse structures isolate construction-phase risk from sponsor balance sheets. North Sea offshore wind developments in the Netherlands and Germany drive long-tenor facility demand with multi-tranche institutional distribution.
- Real Estate Loans:Commercial mortgage-backed facilities finance office and logistics development across core European cities.
- Acquisition Financing:Leveraged buyout structures support private equity-sponsored transactions with covenant-heavy documentation.
Corporate loans anchor the volume base while project financing gains share at the steepest rate.
Borrower Type:
Cost tier differentiation separates investment-grade issuers accessing tight pricing from sub-investment-grade borrowers paying wider margins.
- Private Companies:Family-owned enterprises and mid-cap corporates access bilateral and club deal structures. French and German private firms utilize syndicated facilities for cross-border expansion with relationship bank consortiums.
- Public Corporations:Listed issuers with transparent disclosure command deepest syndicate participation and tightest pricing grids. Dutch and Spanish listed entities leverage equity market visibility for institutional term loan distribution.
- Government Entities:Municipal and regional authorities finance infrastructure through sovereign-guaranteed or quasi-sovereign structures.
- Non-Profit Organizations:Universities and healthcare systems access tax-advantaged financing with mission-aligned lender pools.
Public corporations dominate institutional distribution capacity while private companies expand syndicated market participation most rapidly.
Loan Size:
Volume concentration stratifies arranger league tables, with jumbo facilities requiring multi-bank coordination and small loans executing through bilateral or club structures.
- Large Loans:Facilities between 500 million and 2 billion euros aggregate institutional capital through multi-tranche structures. French utility-scale renewable projects and German automotive supplier consolidation drive category concentration.
- Jumbo Loans:Transactions exceeding 2 billion euros demand global coordinator appointment and multi-currency tranche architecture. Cross-border infrastructure in the Netherlands and Belgium requires these scaled facilities.
- Medium Loans:Mid-market corporates access club deal execution with regional bank participation.
- Small Loans:Bilateral and mini-syndicate structures serve sub-100-million-euro borrowers with streamlined documentation.
Large loans generate the majority of arranger fee income while jumbo loans attract the most institutional capital inflow.
Interest Rate Type:
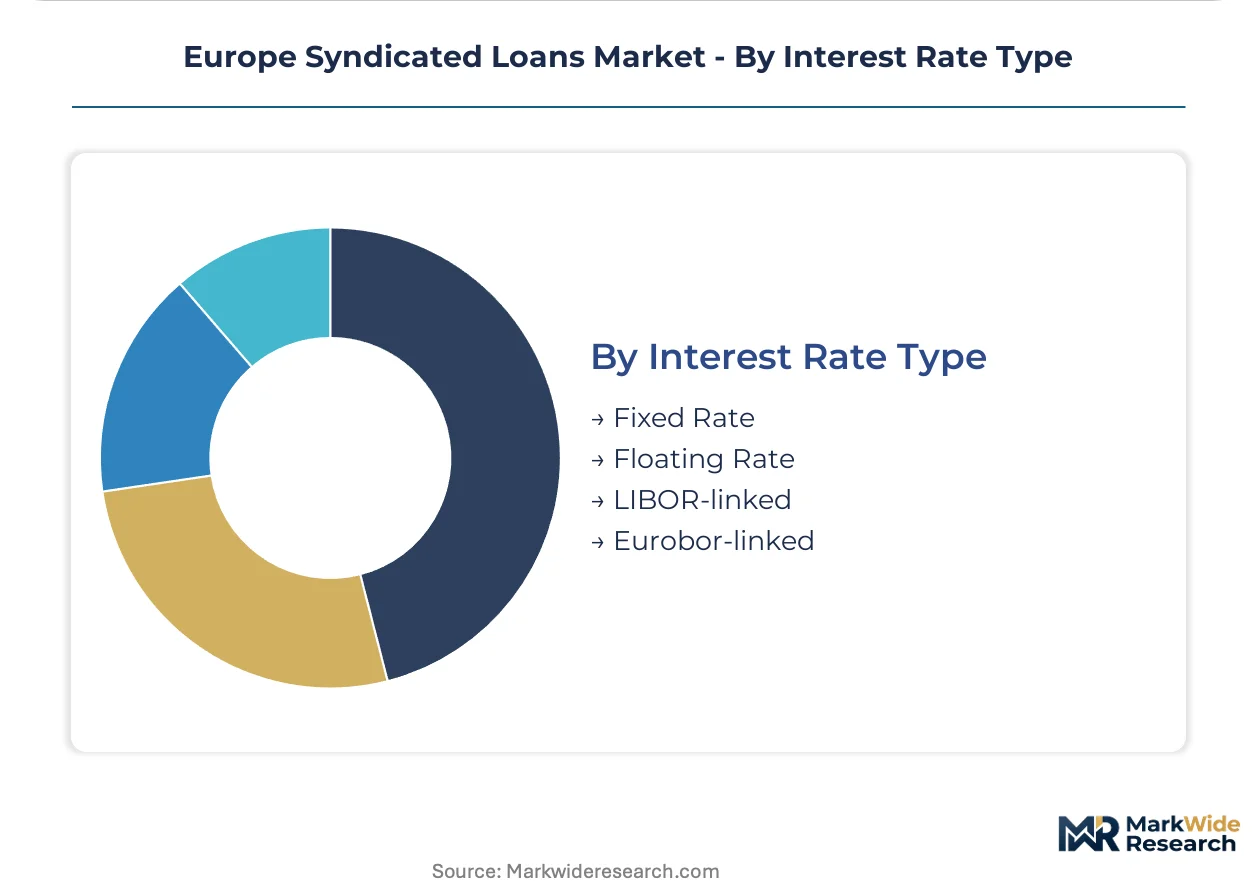
Maturity and repricing frequency separate fixed-rate term structures from floating-rate facilities that transfer benchmark risk to lender syndicates.
- Floating Rate:EURIBOR-linked structures dominate new issuance as borrowers exploit rate reset mechanics. French and German investment-grade corporates favor these facilities for working capital and general corporate purposes.
- Eurobor-linked:Term facilities reference euro interbank offered rate with periodic reset provisions. Spanish and Italian borrowers utilize these structures to align debt service with operating cash flow seasonality.
- Fixed Rate:Bond-style term loans lock borrowing costs for capital-intensive project durations.
- LIBOR-linked:Legacy dollar-denominated tranches reference interbank offered rate with fallback clause amendments.
Floating rate structures command the largest outstanding volume while Eurobor-linked facilities expand most quickly amid benchmark transition completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French investment-grade corporates command pricing grids 15-25 basis points tighter than Spanish equivalent credits, reflecting divergent ECB monetary transmission across eurozone core and periphery markets.
Germany
Utility-scale offshore wind developments in the North Sea basin drive long-tenor facility demand with multi-tranche institutional distribution. The country's national energy regulator enforces grid connection timelines that compress construction-phase financing windows. Industrial clusters around Hamburg and Bremerhaven anchor turbine manufacturing supply chains requiring working capital facilities.
Netherlands
Grid modernization programs and hydrogen backbone infrastructure create dedicated offtake agreements that de-risk project finance structures. EU Green Deal taxonomy alignment mandates direct bank consortium formation toward transition finance mandates. The Rotterdam-Antwerp port complex concentrates petrochemical refinancing activity with ESG-linked pricing mechanisms.
France
Pan-European multinational corporations centralize liquidity structures through relationship-driven mandates with domestic banking groups. The country's national financial markets authority implements sustainable finance disclosure standards that reshape documentation frameworks. Paris-based energy majors deploy syndicated credit for cross-border renewable acquisitions.
Spain
Periphery market pricing benchmarks widen spreads relative to core eurozone jurisdictions, generating arbitrage opportunities for multi-currency structures. The national securities market commission enforces transparency requirements affecting institutional investor eligibility. Madrid and Barcelona host listed entities leveraging equity market visibility for term loan distribution.
Poland
Baltic Sea offshore wind auctions remain underpenetrated by established arranger networks, offering first-mover positioning for local currency tranches. The national banking regulator applies large exposure standards that mechanically expand syndicate participation requirements. Warsaw and Gdańsk clusters concentrate renewable infrastructure development requiring construction-phase risk isolation.
Europe Syndicated Loans Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in syndicate formation and distribution architecture. The European syndicated loans market structures around consolidated global coordinators with pan-European balance sheet capacity, tiered regional arrangers with sector specialization, and alternative credit platforms filling mezzanine tranche exposure. Dominant competitive moves include geographic expansion into underpenetrated renewable infrastructure markets and portfolio diversification through ESG-linked pricing mechanism integration.
Within the platform integrator tier, BNP Paribas and Barclays anchor lead-left positioning on cross-border infrastructure facilities. Blackstone Credit occupies a position within the alternative credit archetype, complementing traditional bank syndications through direct lending platforms that assume junior tranche exposure.
| Leading Market Players |
|---|
| BNP Paribas |
| BofA Securities |
| Blackstone Credit |
| Ares |
| Arcmont |
| Lloyds |
| Barclays |
| Lazard |
| PNC |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in French and German banking syndicates is compressing arranger fee pools and forcing lead banks to accept tighter pricing grids on repeat corporate mandates. This utilization imbalance simultaneously erodes pricing power for standardized revolving credit facilities while concentrating margin recovery in bespoke project finance structures with complex documentation requirements.
Pricing Analysis
The customization-premium spread between ESG-linked project finance and standard corporate revolving credit has widened as sustainability performance targets demand specialized verification infrastructure. Pricing stratifies across premium, standard, and economy tiers based on borrower transparency and relationship depth, with investment-grade French multinationals accessing tightest grids while Polish renewable developers pay construction-phase risk premiums. Pricing pressure stems from ECB rate transmission divergence compressing core eurozone benchmarks. Private companies exhibit highest price sensitivity due to limited alternative financing channels.
Supply Chain Analysis
Upstream feedstock of institutional capital concentrates in Dutch insurance asset managers, German pension funds, and Luxembourg CLO platforms. The syndicated loan supply chain draws from these capital pools through arranger distribution networks, documentation legal frameworks, and administrative agent servicing infrastructure. Single-source vulnerability sits with dominant pan-European banks controlling lead-left positioning on cross-border infrastructure. Distribution runs through multi-tranche term loan B and direct lending convergence structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
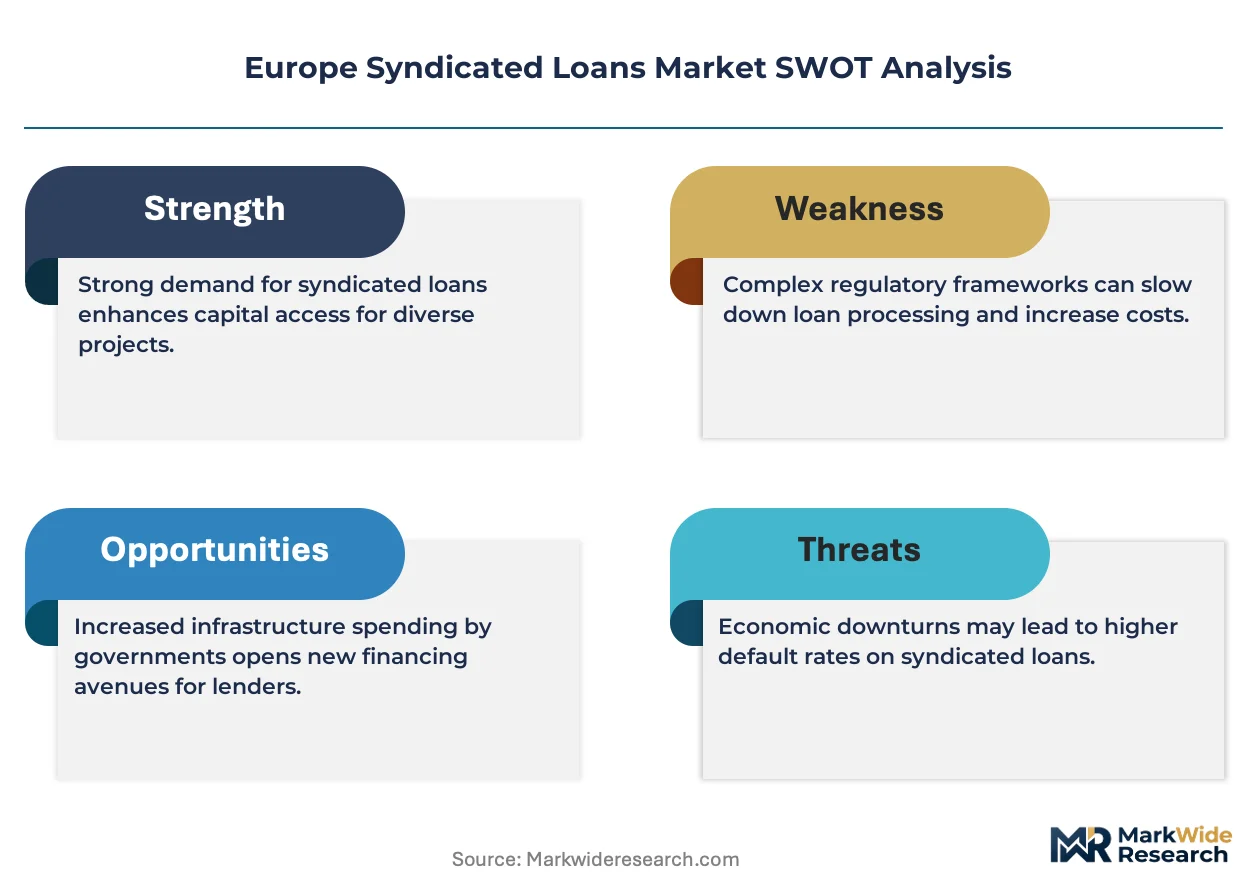
The Europe Syndicated Loans Market functions as a defensive-moat industry where regulatory entrenchment through EBA large exposure standards and EU Green Deal taxonomy requirements creates durable barriers to arranger displacement.
For Market Incumbents: Build switching-cost moats through integrated cash management and credit facility bundling for French and German multinational treasury departments. Deepen pan-European balance sheet deployment to capture lead-left positions on North Sea offshore wind developments before Basel III RWA compression further constrains competitor capacity. For New Entrants and Emerging Players: Establish a beachhead in Polish Baltic Sea offshore wind auctions where local currency tranches remain underpenetrated by established arranger networks. Target direct lending convergence opportunities assuming mezzanine exposure on hydrogen backbone infrastructure in the Netherlands and Belgium. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among administrative agent platforms with covenant monitoring and cash management integration. Long-term viability favors arranger franchises with institutional distribution depth across Dutch insurance and German pension capital pools. Watch for ECB monetary transmission divergence compression as inflection signal for peripheral market spread normalization.| Strategic Initiative | Industry Significance |
|---|---|
| ESG-Linked Pricing Mechanism Integration | EU Green Deal taxonomy alignment mandates sustainability performance targets in margin ratchets across German utility-scale renewable projects. |
| Direct Lending Platform Convergence | Alternative credit funds assume junior tranche exposure complementary to traditional bank syndications on Dutch hydrogen backbone facilities. |
| Local Currency Tranche Expansion | Polish zloty-denominated structures capture first-mover positioning in Baltic Sea offshore wind auctions outside established eurozone networks. |
| Administrative Agent Function Virtualization | Blockchain smart contract platforms automate covenant testing and disintermediate trustee roles for Nordic pension fund investors. |
| Pan-European Liquidity Structure Centralization | French multinational corporations consolidate banking relationships through integrated revolving credit platforms with relationship-driven domestic arrangers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Dealogic loan database extracts, ECB statistical warehouse releases, and EBA supervisory disclosure filings. Primary interviews engaged syndicated loan originators at pan-European banks, portfolio managers at Dutch insurance asset managers, and project finance directors at North Sea offshore wind developers. Secondary validation drew from LMA documentation standard updates, EU Green Deal regulatory texts, and arranger league table publications. Bottom-up facility-level aggregation and top-down macroeconomic scenario triangulation anchored market sizing.
Forecast inputs incorporate loan type segmentation by tenor and recourse structure, borrower classification across investment-grade and sub-investment-grade tiers, and interest rate mechanics distinguishing floating-rate from fixed-rate facilities. The analytical framework models deployment across the projection horizon through arranger capacity constraints, regulatory capital requirement evolution, and institutional investor appetite shifts. CAGRs derive from facility origination velocity trajectories and tranche distribution depth indicators.
Stress conditions across ECB rate cycle divergence, Basel III RWA implementation timing, and EURIBOR-€STR transition friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EBA guideline continuity and EU Taxonomy technical screening criteria stability. Cross-checking against Dealogic arranger fee pool distributions and institutional investor allocation surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Russia Car Loan Market