
 Solar Photovoltaic Ribbon Market | 2026-2036
Solar Photovoltaic Ribbon Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Photovoltaic Ribbon Market Insights
Utility-scale developers are rotating toward high-efficiency cell architectures that demand precision-engineered ribbon geometries. SHENMAO Technology leverages its copper-processing heritage to dominate flat ribbon supply for Chinese module giants. Ulbrich Solar Technologies anchors North American demand through vertically integrated wire drawing and tinning capabilities. Sveck Photovoltaic New Material competes on silver-coated variants optimized for heterojunction cell interconnection.
Solar photovoltaic ribbon consists of copper conductor strips, typically tin-lead or lead-free solder coated, that electrically interconnect individual silicon cells within a module and carry current to the junction box. Manufacturers draw oxygen-free copper to widths between 0.8 mm and 5.0 mm, then apply flux-cored solder layers via hot-dip or electroplating processes to ensure solderability during stringing operations. Flat ribbon continues to lead volume shipments due to its compatibility with conventional tabbing-stringing equipment, though structured ribbon variants are capturing margin pools by reducing shading losses on bifacial cells. The technology dimension shows crystalline-silicon applications sustaining the bulk of demand while building-integrated photovoltaics represents a faster-growing niche requiring aesthetically specialized ribbon formats.
China's GB standards and MIIT efficiency mandates are elevating conductivity and elongation specifications, effectively filtering out lower-grade suppliers. REACH and RoHS compliance in Europe is pushing lead-free solder coatings toward mainstream adoption despite higher material costs. Stakeholders must monitor how evolving IEC certification thresholds for module reliability will cascade into ribbon fatigue-resistance requirements and alloy formulation decisions.
Market Dynamics
China's MIIT efficiency mandates and dual carbon goals are compressing allowable resistivity tolerances for interconnection materials, forcing ribbon suppliers to retool drawing and plating lines or exit the supply chain entirely.
Growth Catalysts
- Heterojunction cell proliferation:N-type silicon architectures demand silver-coated ribbon variants with ultra-low contact resistance, expanding addressable material specifications for precision coating specialists.
- India PLI scheme:Domestic content requirements for solar module manufacturing are stimulating localized ribbon production capacity to serve Gujarat and Tamil Nadu cell fabs.
- Bifacial module standardization:Structured ribbon geometries that reduce front-side shading are capturing design wins as utility-scale developers prioritize energy yield per watt-peak.
Market Restraints
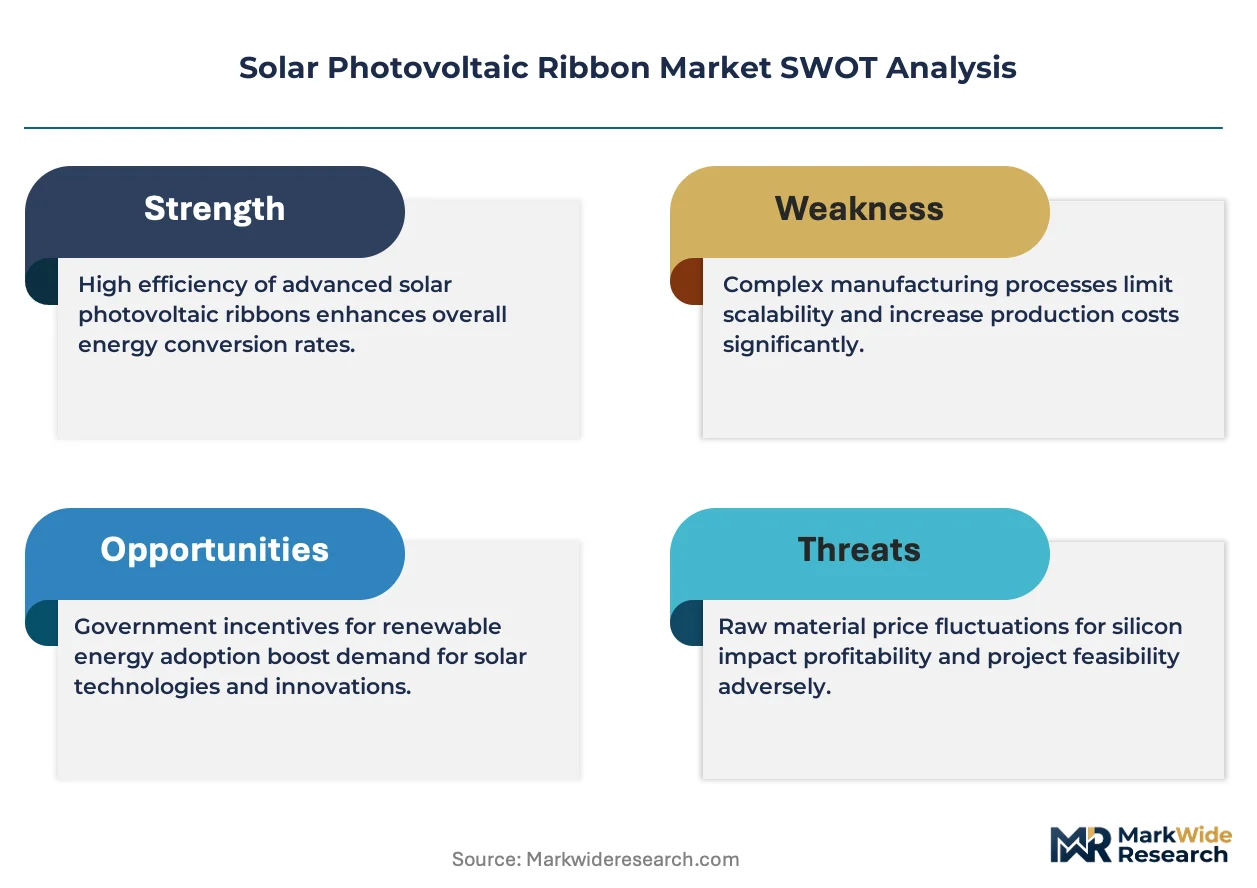
- Copper price volatility:LME copper fluctuations transmit directly to ribbon raw material costs, compressing margins for toll-coating operations lacking captive cathode supply.
- Jiangsu-Zhejiang supply concentration:Over 70 percent of global cell and module output concentrates in two Chinese provinces, creating geographic demand risk and procurement leverage asymmetry.
- Lead-free solder cost premium:REACH and RoHS compliance in Europe requires tin-silver-copper alloys costing 40-60 percent more than conventional tin-lead formulations.
Strategic Opportunities
- US IRA manufacturing credits:Section 45X advanced manufacturing production credits are incentivizing ribbon localization to serve Arizona and Ohio module assembly plants.
- Building-integrated photovoltaics:Aesthetically specialized black ribbon and narrow-width formats command margin premiums in residential and commercial rooftop segments.
- Perovskite tandem integration:Emerging tandem cell architectures will require ribbon metallization schemes compatible with temperature-sensitive top-cell layers.
Industry Challenges
- Plating chemistry expertise scarcity:Electroplating engineers capable of maintaining sub-micron coating uniformity across kilometer-length copper substrates command premium compensation in Suzhou and Hsinchu labor markets.
- IEC 61215 certification timelines:Module reliability testing protocols extending 6-12 months delay ribbon qualification for new alloy formulations, freezing supplier switching decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Photovoltaic Ribbon Market |
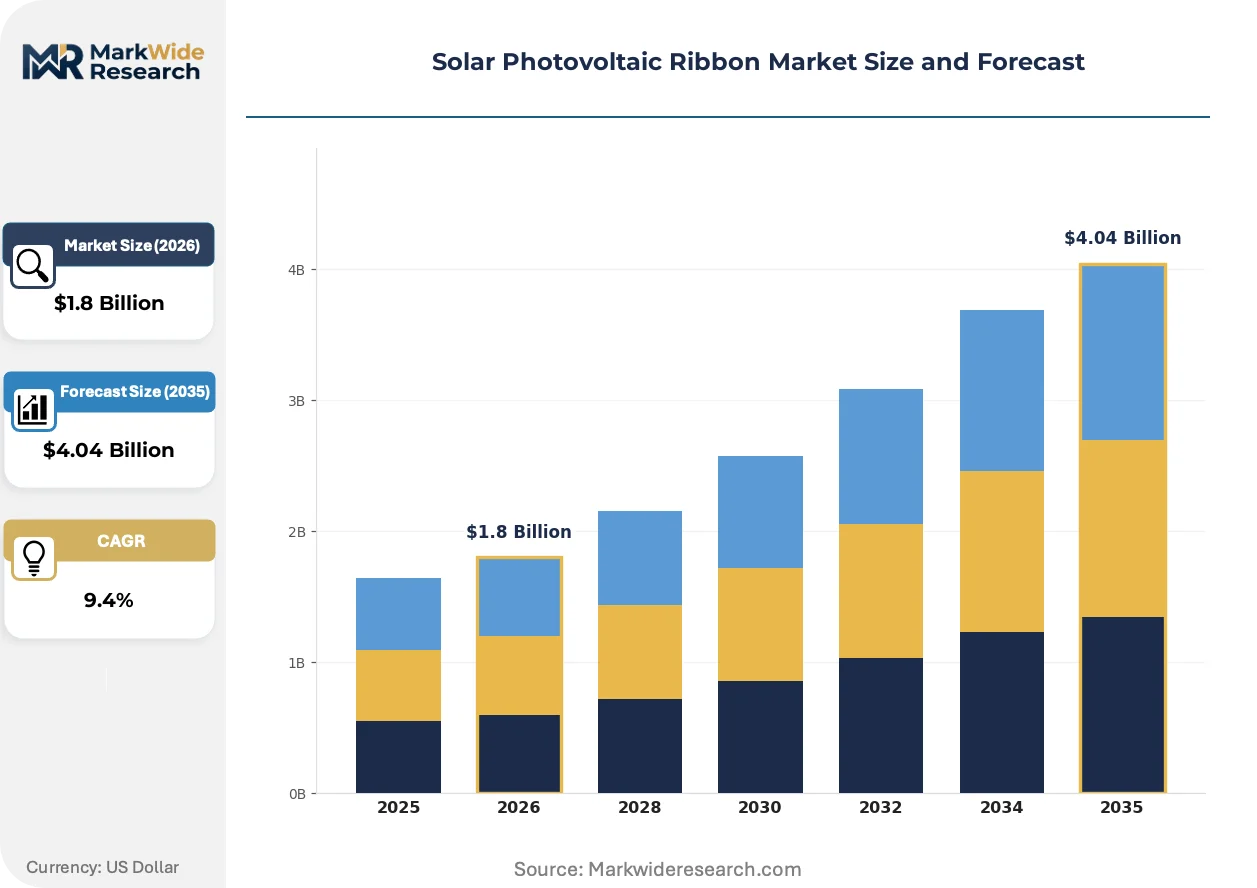
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Ribbon, Round Ribbon, Structured Ribbon, Silver Coated Ribbon End User: Utilities, Commercial, Residential, Industrial Technology: C-Si, BIPV, Thin Film, Multi-Junction Application: Solar Panels, Solar Farms, Off-Grid Systems, Building Systems |
| Companies Covered | Ulbrich Solar Technologies, Sveck Photovoltaic New Material, Hitachi Cable, Bruker-Spaleck, SHENMAO Technology, Jiangsu Sun Group, Sarkuysan, Luvata, Suzhou YourBest New Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Photovoltaic Ribbon Market Trends and Innovations
Interconnection technology is bifurcating between commodity flat ribbon serving cost-optimized capacity expansions and engineered structured variants capturing efficiency premiums in high-performance module lines.
Round wire interconnection is miniaturizing from conventional 0.3 mm diameters toward 0.26 mm and below to reduce silver consumption and shading losses on shingled cell designs. Tier-one module manufacturers in Hefei and Xi'an are qualifying these geometries for 600 W-plus bifacial products. The technology is miniaturizing cross-sectional dimensions while maintaining current-carrying capacity through copper core optimization.
REACH Annex XVII restrictions on lead content in electrical equipment are accelerating tin-silver-copper alloy adoption despite 15-20 percent conductivity penalties versus eutectic tin-lead. European module assemblers in Germany and the Netherlands are absorbing solder material cost inflation to maintain CE marking eligibility. Cell manufacturers are responding with busbar redesigns that reduce absolute solder volume requirements per module.
Direct material sourcing from copper smelters is displacing merchant wire purchases among large ribbon producers seeking lot-to-lot oxygen consistency. Procurement departments at Korean and Taiwanese coating specialists are negotiating cathode offtake agreements with Zambian and Chilean mining operations. This vertical consolidation is most visible in supply contracts for 5.0 mm wide flat ribbon serving utility-scale stringing operations.
Solar Photovoltaic Ribbon Market Segmentation
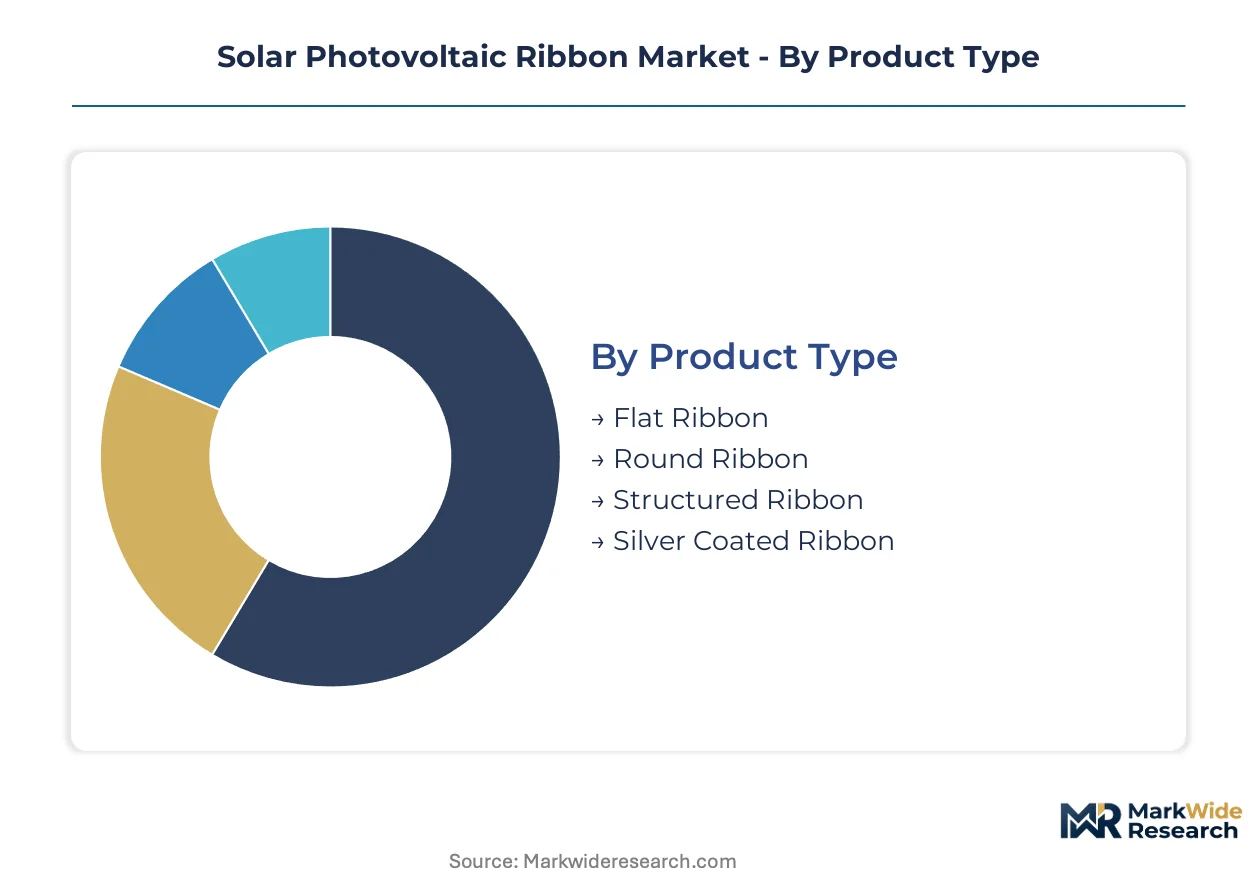
Solar photovoltaic ribbon segmentation reveals how material specifications diverge across cell architectures and installation scales. Product geometry, end-use scale, and technology compatibility each create distinct procurement criteria that filter supplier capabilities.
Product Type:
REACH Annex XVII and China's GB standards are bifurcating the supply base between lead-compliant and lead-free coating specialists.
- Flat Ribbon:Conventional rectangular cross-sections between 0.8 mm and 5.0 mm width dominate tabbing-stringing operations for crystalline-silicon modules. Jiangsu and Zhejiang module clusters absorb the majority of volume as manufacturers prioritize equipment compatibility over efficiency gains.
- Structured Ribbon:Triangular or trapezoidal profiles reduce front-side shading on bifacial cells by reflecting light toward the rear junction. Utility-scale developers in Gujarat and Arizona are specifying these geometries for 600 W-plus bifacial installations where energy yield per watt-peak drives procurement decisions.
- Round Ribbon:Circular cross-sections miniaturizing toward 0.26 mm diameter serve shingled cell interconnection with reduced silver consumption.
- Silver Coated Ribbon:Electroplated silver layers deliver ultra-low contact resistance for heterojunction cell architectures.
Established volume favors flat ribbon; emerging adoption favors structured ribbon.
End User:
Project scale determines whether procurement prioritizes unit cost or performance optimization.
- Utilities:Gigawatt-scale solar farms in Rajasthan and Nevada specify precision-tolerance ribbon lots with full metallurgical traceability. Developers negotiate cathode offtake agreements directly to hedge LME copper volatility across multi-year construction timelines.
- Commercial:Rooftop and carport installations across German industrial parks demand black-aesthetic ribbon formats that preserve building envelope aesthetics. ECHA compliance requirements are filtering suppliers unable to certify tin-silver-copper alloy coatings.
- Residential:Distributed generation systems in Australian suburbs and Japanese prefectures prioritize narrow-width ribbon for compact module footprints.
- Industrial:C&I microgrids in Tamil Nadu and Texas oilfield operations specify heavy-gauge ribbon for durability in high-temperature environments.
Procurement concentration tilts toward utilities for volume; margin capture concentrates in commercial aesthetic specifications.
Technology:
Cell metallization chemistry dictates ribbon alloy compatibility and thermal processing windows.
- C-Si:Crystalline-silicon architectures sustain the bulk of ribbon demand through conventional soldering temperatures compatible with tin-lead and lead-free coatings. Hefei and Xi'an cell fabs are the primary offtake centers for standard conductivity specifications.
- BIPV:Building-integrated formats require color-matched and ultra-narrow ribbon to preserve architectural aesthetics. European module assemblers in the Netherlands absorb premium pricing for black-coated variants that meet CE marking and aesthetic dual requirements.
- Thin Film:Cadmium-telluride and CIGS modules use minimal or no ribbon interconnection, constraining addressable market scope.
- Multi-Junction:Space-concentrator and terrestrial CPV applications demand specialized high-conductivity busbar designs.
C-Si commands absolute volume leadership; BIPV climbs the fastest on margin expansion.
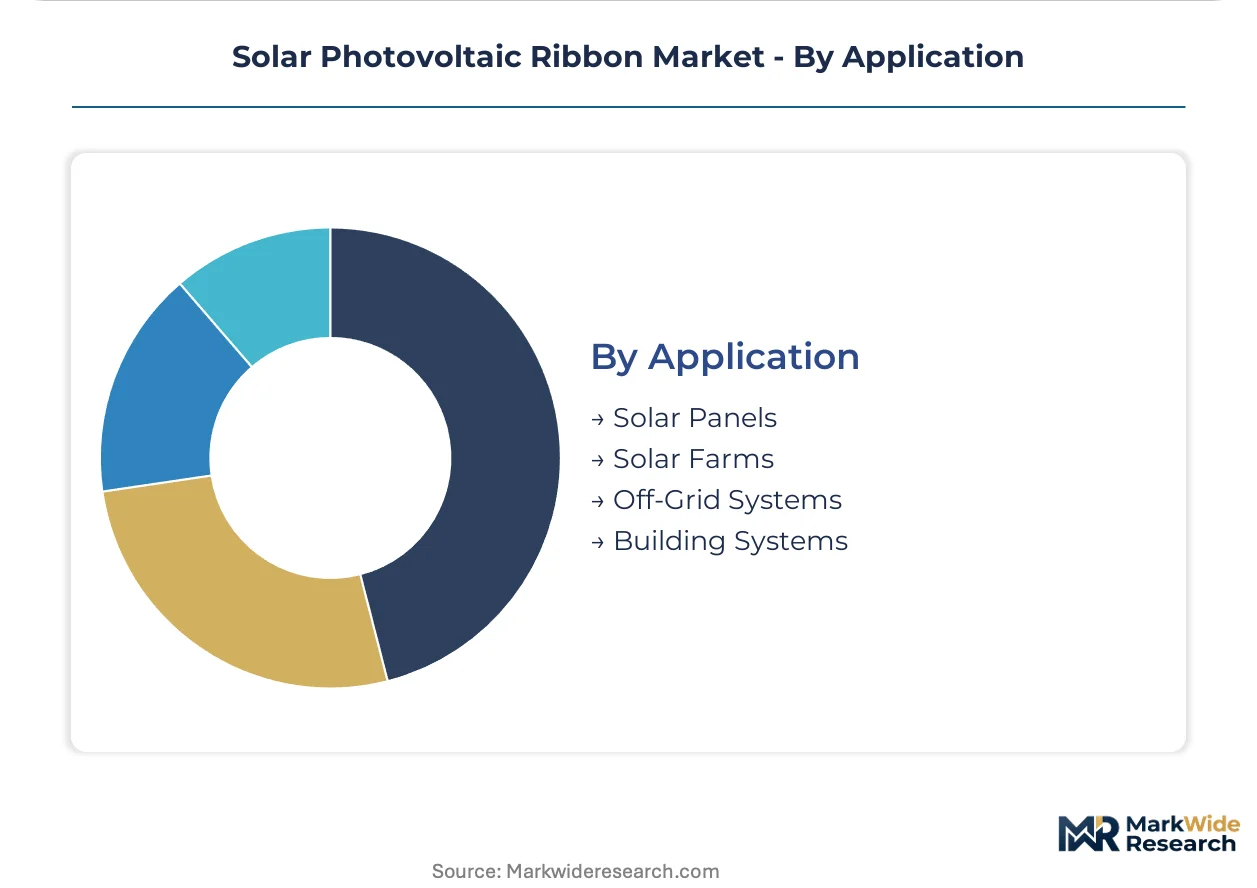
Application:
Installation environment shapes mechanical reliability requirements and certification protocols.
- Solar Panels:Standard module assembly for distributed and utility deployment represents the baseline ribbon consumption category. IEC 61215 certification timelines freeze supplier switching for 6-12 months, entrenching incumbent relationships.
- Solar Farms:Utility-scale stringing operations in Arizona and Ohio are localizing ribbon supply to capture IRA Section 45X credits. Module assemblers specify 5.0 mm wide flat ribbon for high-current handling across large-format cells.
- Off-Grid Systems:Remote installations in sub-Saharan Africa and Southeast Asian archipelagos prioritize corrosion-resistant coatings for humidity exposure.
- Building Systems:Façade-integrated and skylight applications combine BIPV aesthetics with structural load requirements.
Module-scale applications anchor procurement volume; integrated building systems expand specification diversity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese ribbon producers export the majority of flat and structured ribbon volumes to module assembly plants in India, the United States, and European Union member states. This trade corridor channels Jiangsu and Zhejiang manufacturing output toward Gujarat solar parks, Arizona utility-scale developments, and Dutch rooftop installations. Regional demand patterns diverge sharply between cost-optimized procurement in emerging markets and specification-intensive purchasing in regulated Western jurisdictions.
China
Jiangsu and Zhejiang provinces host over 70 percent of global cell and module manufacturing, concentrating ribbon procurement within a 200-kilometer radius of Suzhou and Ningbo. MIIT efficiency mandates and dual carbon goals are compressing resistivity tolerances, forcing suppliers to upgrade drawing and plating lines or exit the supply chain entirely. Hefei and Xi'an cell fabs are qualifying 0.26 mm round wire geometries for 600 W-plus bifacial products.
United States
Utility-scale developers in Arizona and Nevada are localizing ribbon supply to capture IRA Section 45X advanced manufacturing production credits. Module assemblers in Ohio and Texas specify 5.0 mm wide flat ribbon for high-current handling across large-format cells. Domestic content requirements are stimulating toll-coating partnerships between U.S. wire drawers and Asian plating specialists.
India
Gujarat and Tamil Nadu cell fabs are absorbing ribbon volumes under the PLI scheme's domestic content requirements for solar module manufacturing. Procurement departments negotiate directly with Zambian and Chilean copper smelters to hedge LME price volatility across multi-year project timelines. Rajasthan gigawatt-scale solar farms demand precision-tolerance ribbon lots with full metallurgical traceability.
Germany
REACH Annex XVII restrictions on lead content are accelerating tin-silver-copper alloy adoption despite 15-20 percent conductivity penalties versus eutectic tin-lead. Module assemblers in Bavaria and North Rhine-Westphalia absorb solder material cost inflation to maintain CE marking eligibility. Industrial park rooftop installations across Baden-Württemberg demand black-aesthetic ribbon formats that preserve building envelope aesthetics.
Netherlands
Building-integrated photovoltaic installations in the Randstad region command premium pricing for color-matched and ultra-narrow ribbon specifications. Dutch module assemblers source black-coated variants that satisfy both CE marking requirements and architectural aesthetic standards. Eindhoven-area coating specialists are developing electroplating chemistries compatible with temperature-sensitive perovskite tandem cell layers.
Solar Photovoltaic Ribbon Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The vendor base segments into three tiers: integrated copper processors with captive smelter relationships, independent coating houses dependent on merchant wire purchases, and regional toll-coating operations serving single-module customers. Strategic moves concentrate on backward integration into cathode supply and qualification of lead-free alloy formulations for European CE marking compliance.
Within the integrated processor archetype, SHENMAO Technology and Ulbrich Solar Technologies exemplify divergent geographic positioning—Chinese versus North American—while sharing vertical control over wire drawing and surface metallization. Sveck Photovoltaic New Material occupies a specialist tier focused on silver-coated variants. These three entities represent distinct competitive vectors: scale-driven commodity supply, regional manufacturing credit capture, and precision coating for next-generation cell architectures.
| Leading Market Players |
|---|
| Ulbrich Solar Technologies |
| Sveck Photovoltaic New Material |
| Hitachi Cable |
| Bruker-Spaleck |
| SHENMAO Technology |
| Jiangsu Sun Group |
| Sarkuysan |
| Luvata |
| Suzhou YourBest New Material |
| Others |
Pricing and Supply Chain Analysis
Sixty-day cathode offtake lead times from Zambian and Chilean smelters concentrate pricing power among ribbon producers with direct mining relationships, while toll-coating operations without captive copper supply absorb LME volatility through compressed margins. Jiangsu and Zhejiang procurement clusters leverage geographic proximity to force unit-cost concessions from dependent suppliers.
Pricing Analysis
Flat ribbon serving conventional crystalline-silicon modules commands economy-tier positioning against structured and silver-coated variants capturing premium-mid-economy pricing differentiation. Price differentiation separates precision-tolerance utility lots with full metallurgical traceability from standard-grade commercial shipments. Pricing pressure stems from REACH and RoHS compliance costs as European assemblers absorb tin-silver-copper alloy premiums. Utility-scale developers demonstrate lowest price sensitivity due to cathode offtake hedging, while residential distributors face acute margin compression.
Supply Chain Analysis
Strategic stockpiling of oxygen-free copper cathode dominates procurement strategy among integrated ribbon producers, while toll-coaters run just-in-time merchant wire purchases exposed to LME swings. Supply concentrates in China, Zambia, and Chile for copper cathode, with coating specialization clustering in Jiangsu and Zhejiang provinces. Raw material dependencies center on copper cathode purity grades, tin-lead and lead-free solder alloys, and electroplating chemical precursors. Single-source vulnerability from Jiangsu-Zhejiang manufacturing concentration creates geographic demand risk. Distribution runs through module assembly plants in Gujarat, Arizona, and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical coating services and alloy formulation consulting expand faster than commodity ribbon hardware as cell manufacturers outsource plating chemistry expertise. Recurring metallurgical certification and process optimization contracts deepen supplier stickiness beyond unit sales.
For Market Incumbents: Secure backward integration into Zambian or Chilean cathode supply to insulate margins from LME volatility, while accelerating lead-free alloy qualification timelines to preempt European regulatory exclusion. SHENMAO Technology's copper-processing heritage demonstrates how captive smelter relationships defend against toll-coating margin erosion. MIIT efficiency mandates threaten suppliers unable to upgrade drawing and plating lines. For New Entrants and Emerging Players: Anchor in US IRA Section 45X credit zones through toll-coating partnerships with Arizona and Ohio wire drawers, targeting the white-space between Asian export supply and domestic content requirements. Perovskite tandem cell metallization schemes offer penetrable entry points as established players delay temperature-sensitive coating R&D. Go-to-market leverage rests on electroplating chemistry expertise scarcity in Suzhou and Hsinchu labor markets. For Investors and Strategic Acquirers: Long-term, this sits as a process-specialist consolidation play because coating uniformity capabilities across kilometer-length substrates command irreplicable technical moats. Acquisition targets cluster among independent plating houses with IEC 61215 qualification track records and pending lead-free alloy certifications. Watch for bifacial module standardization crossing threshold penetration rates as the signal for structured ribbon margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Cathode Supply | Captive Zambian or Chilean offtake agreements insulate margin structures from LME volatility transmission. |
| Lead-Free Alloy Formulation Qualification | REACH Annex XVII compliance preserves CE marking eligibility for European module assembler contracts. |
| Silver-Coated Ribbon Capacity Expansion | Heterojunction cell proliferation demands ultra-low contact resistance variants from precision coating specialists. |
| US Domestic Toll-Coating Partnership | IRA Section 45X credit capture requires localized surface metallization for Arizona and Ohio module plants. |
| Perovskite Tandem Metallization R&D | Temperature-sensitive top-cell compatibility opens adjacent addressable market as tandem architectures mature. |
Research Methodology
A standing panel of cell manufacturing procurement directors, electroplating process engineers, module assembler quality managers, and copper cathode traders provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT efficiency mandate filings, IEC 61215 certification registries, LME copper futures data, and SEC disclosures from listed solar component suppliers. Bottom-up ribbon consumption modeling triangulated against top-down module production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product geometry, end-use scale, cell metallization chemistry, and installation environment. CAGRs derived from regression analysis of historical capacity expansion patterns and technology substitution curves. Forecast inputs incorporated heterojunction cell penetration assumptions and bifacial module adoption trajectories.
Material uncertainties — copper price volatility spikes, regulatory acceleration of lead-free mandates, and perovskite tandem commercialization timelines — sit outside the modeled envelope. Forecasts reflect assumptions about drawing and plating line upgrade rates among incumbent suppliers. Revision becomes warranted when MIIT resistivity tolerance compression crosses implementation thresholds that force supplier exit decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Solar Panel Cleaning System Market