
 Switzerland Self-Storage Market | 2026-2036
Switzerland Self-Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Self-Storage Market Analytics
Small-business operators seeking inventory overflow space is collapsing the traditional residential-only customer base that once defined Swiss self-storage. placeB AG leverages its urban micro-warehouse network to capture this commercial pivot. Homebox Switzerland SA sustains competitive density through automated access systems and digitized unit management. Shurgard Self-Storage anchors its position with purpose-built facilities near Zurich's logistics corridors.
Switzerland Self-Storage denotes leased, individually secured compartments within multi-unit facilities, typically constructed from galvanized steel partitioning with humidity control between 30-60% RH and fire-rated compartmentalization. These assets serve households and enterprises requiring flexible, short-to-medium term space for goods excluded from primary premises by cost or zoning constraints. Climate-controlled units command margin premiums over drive-up alternatives due to Switzerland's alpine temperature swings and sensitive goods storage requirements. Small and medium unit sizes generate the highest turnover velocity, while commercial storage purpose segments expand fastest as e-commerce sellers and service contractors outsource inventory holding.
Swiss cantonal building codes and municipal zoning boards regulate facility placement, often restricting self-storage to industrial peripheries and mandating minimum parking ratios per unit count. Swissmedic and SIA structural standards indirectly shape facility design through building safety and materials certification requirements. Investors and operators must monitor cantonal zoning liberalization debates and energy efficiency retrofit mandates that could reshape facility economics.
Market Dynamics
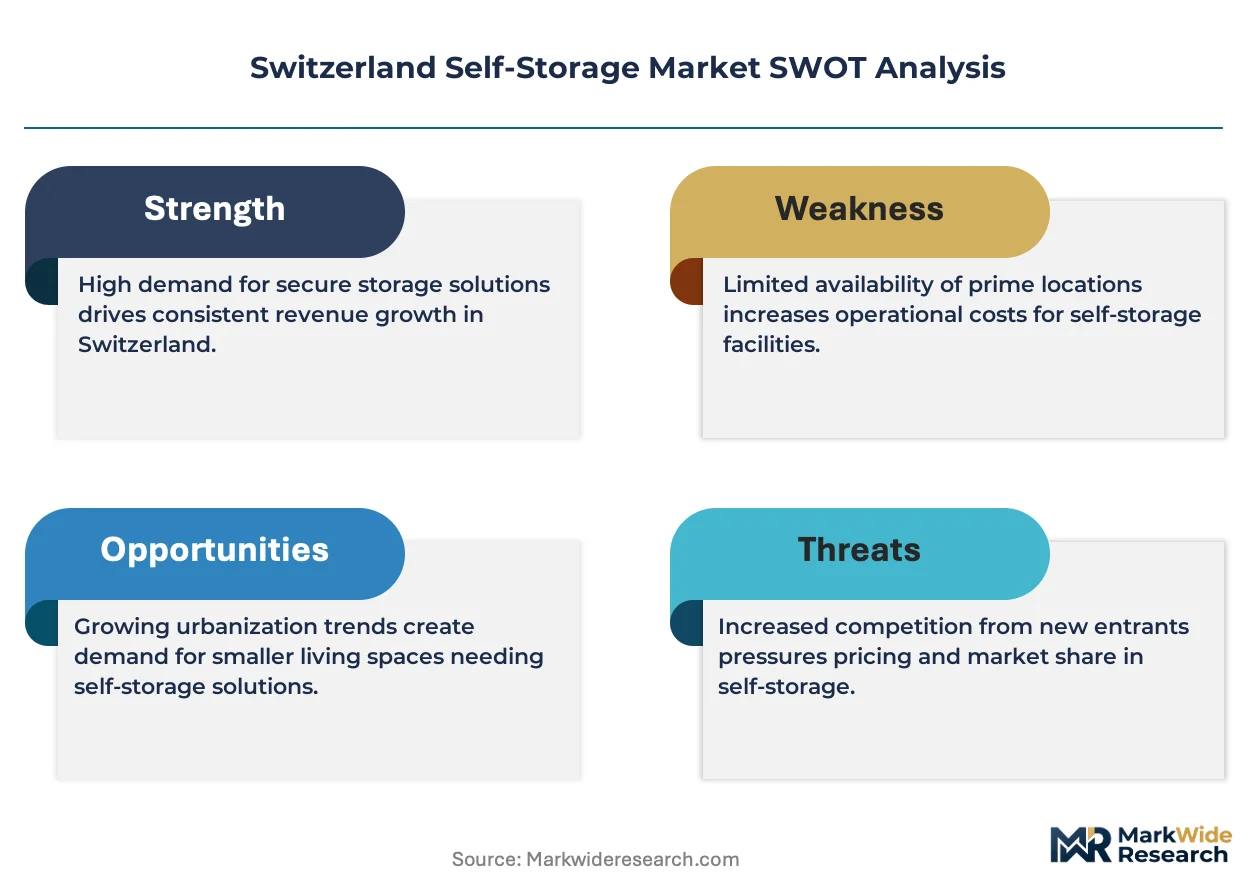
Cantonal zoning restrictions across Swiss cantons are tightening supply elasticity faster than demand growth from shrinking urban apartments, creating structural scarcity that rewards existing permit holders.
Growth Catalysts
- Urban densification mandates:Municipal master plans in Zurich and Geneva prioritize residential floor area ratios over commercial warehousing, pushing household overflow into third-party storage.
- E-commerce inventory outsourcing:Swiss SME sellers on regional platforms lack bonded warehouse access, driving demand for flexible commercial unit rentals.
- Swissmedic temperature compliance:Pharmaceutical samples and medical device storage require validated 15-25°C environments, expanding climate-controlled facility premiums.
Market Restraints
- Construction input cost volatility:Steel partitioning and HVAC equipment face Swiss franc-denominated import exposure, compressing development yields.
- Cantonal zoning fragmentation:Vaud, Zurich, and Geneva apply divergent industrial periphery definitions, complicating national portfolio expansion.
- Multi-use building substitution:Mixed-use developments with basement storage strata compete for household overflow demand.
Strategic Opportunities
- Ticino underpenetration:Italian-speaking southern Switzerland lacks purpose-built facilities relative to per-capita storage stock in German-speaking cantons.
- Renewable retrofit incentives:Federal building energy subsidies support photovoltaic and heat pump installations, reducing operational carbon intensity.
- Last-mile logistics convergence:Urban micro-warehousing combined with parcel locker networks creates hybrid storage-distribution nodes.
Industry Challenges
- Facility management digitization:Automated access and remote monitoring systems require cybersecurity competencies scarce in traditional real estate operations.
- SIA structural certification timelines:Seismic and fire safety approvals for multi-story steel construction extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Self-Storage Market |
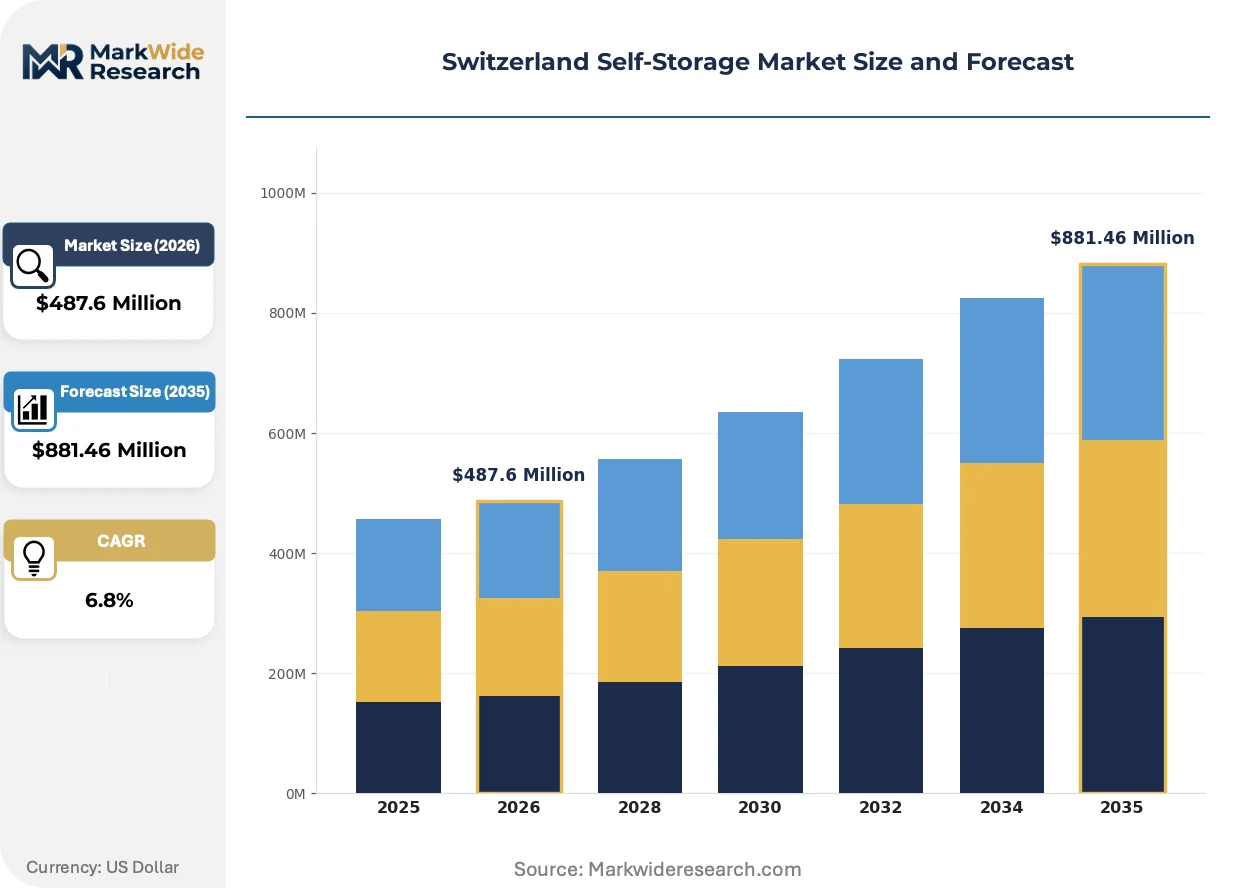
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Climate-Controlled, Drive-Up, Indoor, Outdoor Unit Size: Small, Medium, Large, Extra Large Ownership Model: Public, Private, Franchise, Independent Storage Purpose: Residential, Commercial, Vehicle, Business |
| Companies Covered | placeB AG, Homebox Switzerland SA, Shurgard Self-Storage, Storebox Holding GmbH, MyPlace Self-Storage GmbH, Zebrabox AG, Secur'Storage SA, Box at Work, Casaforte (SMC Self-Storage Management) SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Self-Storage Market Evolving Landscape
Facility operations are pivoting from passive space rental toward active inventory management services, blurring boundaries between self-storage and third-party logistics.
Mobile-enabled unit access and real-time occupancy dashboards are displacing physical key handoffs and paper lease agreements. Urban operators in Basel and Lausanne deploy these platforms to reduce staffing ratios. The compression of administrative overhead is displacing traditional on-site management models in premium locations.
Revised SIA energy efficiency standards for commercial buildings mandate heat recovery ventilation and envelope insulation upgrades. Facility operators face retrofit deadlines or operational penalties. Lake Geneva corridor assets with aging HVAC infrastructure confront the steepest compliance timelines.
Subscription-based storage with bundled moving and inventory photography services is capturing younger household segments. Traditional fixed-term leases lose share to flexible monthly models with digital inventory visualization. Zurich's dense rental apartment districts exhibit the fastest behavioral transition.
Switzerland Self-Storage Market Segmentation
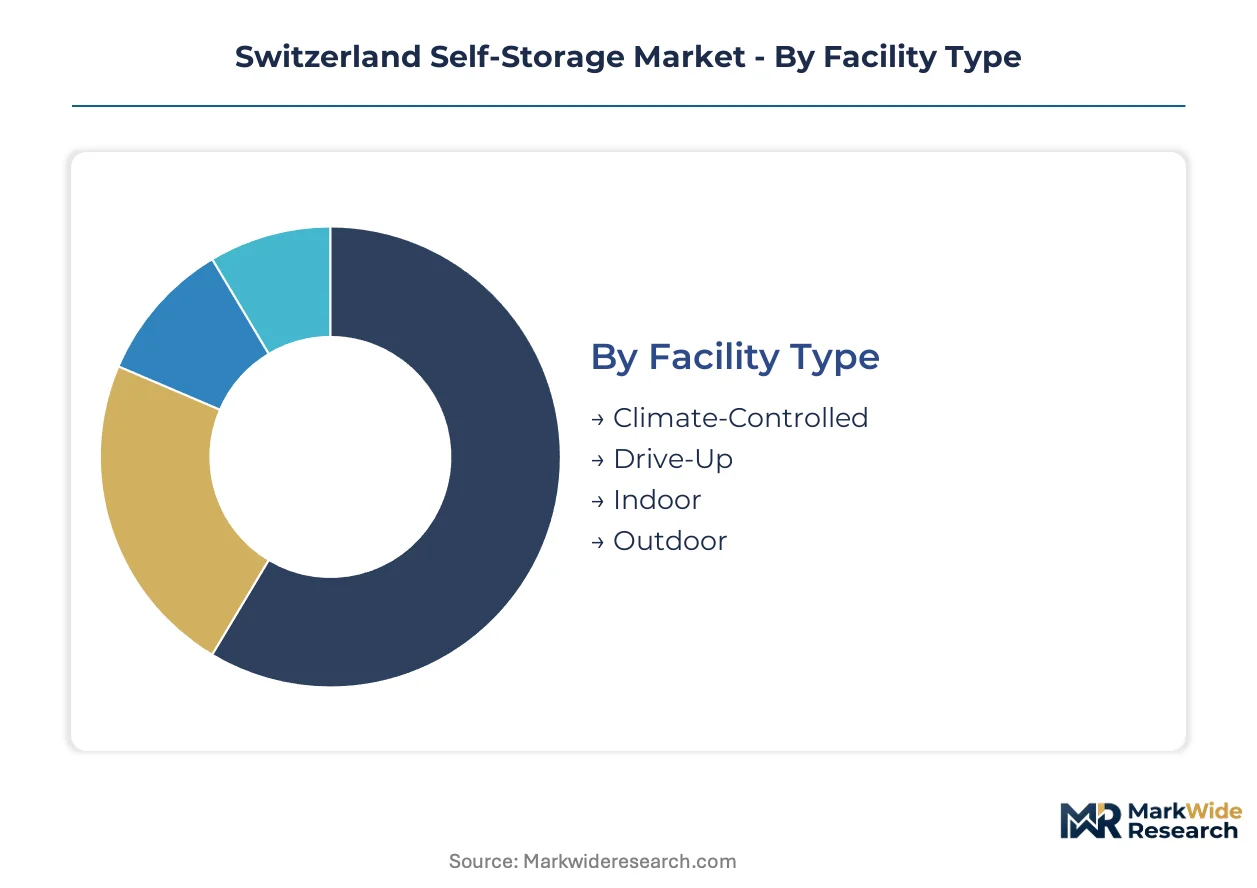
Swiss self-storage operators configure facility economics around four interlocking dimensions: environmental control specifications, unit scale granularity, capital structure, and end-use application. Each dimension carries distinct margin profiles and regulatory exposure that shape portfolio construction decisions.
Facility Type:
Climate-controlled facilities face the most acute substitution pressure from mixed-use basement storage in new Zurich and Geneva residential towers, while drive-up alternatives compete with peripheral industrial warehousing.
- Climate-Controlled:Enclosed environments maintain 15-25°C with 30-60% relative humidity through redundant HVAC and Swissmedic-validated monitoring systems. Lake Geneva corridor pharmaceutical distributors and medical device representatives anchor demand, paying premiums for temperature compliance that basement alternatives cannot match.
- Drive-Up:Ground-level roll-up door units with direct vehicle access minimize handling friction for bulky goods. Geneva logistics periphery contractors and Ticino construction equipment lessors concentrate here, prioritizing speed over environmental protection.
- Indoor:Corridor-access units within multi-story steel structures offer intermediate security and weather protection. Basel urban households with seasonal sports equipment and document archives form the core customer base.
- Outdoor:Fenced compounds with canopy or open-air parking accommodate vehicles, containers, and machinery. Agricultural equipment dealers in Bernese Mittelland and classic car collectors exploit cantonal industrial zoning at lowest per-square-meter rates.
Climate-Controlled anchors the volume base while Drive-Up gains share at the steepest rate as commercial logistics users prioritize access speed over environmental precision.
Unit Size:
Cost tier stratification separates premium small units from economy bulk space, with medium configurations capturing the densest demand concentration from urban apartment overflow.
- Small:Compartments under 5 square meters accommodate document boxes, seasonal clothing, and sports equipment. Zurich 1-2 person rental households drive turnover velocity through short-term cycling of limited possessions.
- Medium:Units between 5-15 square meters fit furniture from 2-3 room apartments during transitions. Lausanne young families and Geneva international assignees on rotation contracts sustain highest occupancy rates.
- Large:15-30 square meter spaces house complete household contents during renovations or relocations. Basel-Gasfabrik district contractors and Lucerne event equipment storers stretch lease durations.
- Extra Large:Units exceeding 30 square meters serve commercial inventory, vehicle storage, and bulk archiving. St. Gallen textile distributors and Winterthur machine tool resellers occupy these at lowest per-unit revenue yields.
Medium units generate the densest revenue per square meter while Small configurations climb fastest as single-person households proliferate in Swiss urban cores.
Ownership Model:
Capital access tiers separate institutional platforms from entrepreneurial operators, with franchise structures offering intermediate scale without balance-sheet concentration.
- Public:Stock-exchange listed REITs and property companies access institutional capital for portfolio expansion. Shurgard Self-Storage exploits this structure to anchor Zurich logistics corridor positions with purpose-built facilities.
- Private:Family offices and closed-end real estate funds hold assets for yield stability and capital appreciation. Geneva and Zug private banking channels channel this capital toward stabilized Lake Geneva corridor assets.
- Franchise:License agreements combine national brand recognition with local operational control. placeB AG deploys this model to scale urban micro-warehouse networks without direct property ownership.
- Independent:Single-facility or small-portfolio operators retain full operational autonomy. Ticino and Grisons mountain towns host these operators, exploiting limited competitive pressure in underpenetrated catchments.
Private ownership dominates transaction volume while Franchise structures expand most quickly as operators seek brand leverage without capital intensity.
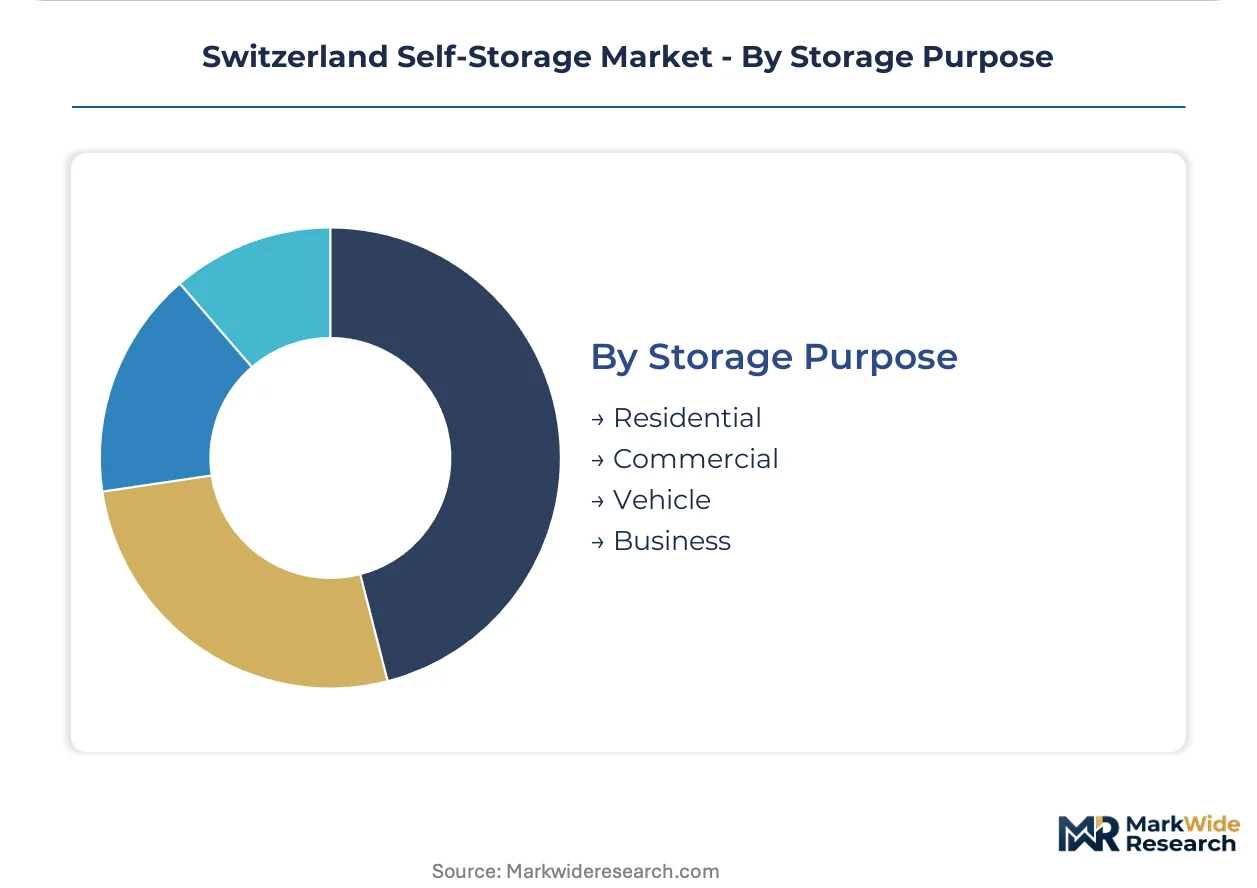
Storage Purpose:
Application-based demand segmentation reveals the fastest structural shift as commercial inventory outsourcing displaces traditional residential dominance.
- Residential:Household overflow from shrinking urban apartments and life transitions. Zurich and Geneva densification mandates compress primary living space, pushing seasonal goods into third-party storage.
- Commercial:SME inventory, sample stock, and equipment for e-commerce sellers and service contractors. Swiss Amazon Marketplace and Galaxus third-party sellers lacking bonded warehouse access drive steepest demand expansion.
- Vehicle:Classic cars, motorcycles, and recreational equipment requiring secure, climate-stable environments. Ticino collectors and Graubünden winter sports enthusiasts sustain premium pricing.
- Business:Document archiving, pharmaceutical samples, and regulated goods requiring audit trails. Swissmedic compliance requirements and FINMA document retention rules shape facility specifications.
Residential purpose anchors current inventory while Commercial applications gain share at the steepest trajectory as SME logistics outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gotthard Base Tunnel anchors Switzerland's north-south freight corridor, enabling rapid inventory repositioning between German industrial hubs and Italian distribution networks. This infrastructure underwrites self-storage demand across the Alpine transit corridor.
Zurich
Urban densification policies from the Zurich City Council compress apartment sizes below 70 square meters, pushing household overflow into third-party storage. Swissmedic temperature compliance requirements shape facility specifications for pharmaceutical distributors. The Altstetten logistics corridor hosts the densest concentration of purpose-built climate-controlled assets.
Geneva
International assignees on rotation contracts drive medium-unit demand from the Lake Geneva banking and UN sectors. Cantonal zoning under the Règlement sur les zones d'activité restricts new construction to industrial peripheries. Carouge and Lancy logistics zones capture premium commercial storage from cross-border SME sellers.
Basel
Pharmaceutical headquarters from Novartis and Roche generate validated cold-chain storage requirements for medical device samples. The city's building energy ordinances mandate heat recovery ventilation retrofits by 2028. The St. Johann industrial zone concentrates automated-access facilities serving Rhine port logistics contractors.
Lausanne
EPFL and UNIL student populations sustain high-turnover small-unit demand for seasonal cycling. Vaud cantonal tax incentives for brownfield redevelopment accelerate facility conversion from obsolete manufacturing. The Renens freight terminal district anchors urban micro-warehouse networks.
Ticino
Italian-speaking southern Switzerland exhibits storage stock deficits relative to per-capita German-speaking canton benchmarks. Mendrisio district zoning liberalization debates signal potential supply expansion. Lugano's cross-border e-commerce sellers currently rely on Como-based warehousing across the Italian frontier.
Switzerland Self-Storage Market Competitive Landscape
Listed leaders compete with private specialists across capital access tiers, fragmenting market structure between institutional REITs and family-office portfolios. Public platforms exploit balance-sheet scale for purpose-built corridor acquisitions while independents retain operational autonomy in underpenetrated catchments. Three archetypes dominate: urban micro-warehouse operators, climate-controlled specialists, and automated-access platforms. Competitive moves concentrate on cantonal permit aggregation and HVAC retrofit compliance acceleration.
Within the urban micro-warehouse tier, placeB AG exemplifies franchise-scaled network density without direct property ownership. Homebox Switzerland SA and Zebrabox AG occupy positions among automated-access specialists digitizing unit management. Shurgard Self-Storage anchors the listed REIT segment with logistics corridor concentration.
| Leading Market Players |
|---|
| placeB AG |
| Homebox Switzerland SA |
| Shurgard Self-Storage |
| Storebox Holding GmbH |
| MyPlace Self-Storage GmbH |
| Zebrabox AG |
| Secur'Storage SA |
| Box at Work |
| Casaforte (SMC Self-Storage Management) SA |
| Others |
Value Network & Pricing Analysis
SIA structural certification and Swissmedic temperature validation requirements gate facility construction permits and simultaneously stratify rental rates, compressing development timelines for compliant assets while amplifying margin premiums for validated climate-controlled inventory. Cantonal zoning boards reinforce this bifurcation by restricting new supply to industrial peripheries, entrenching pricing power among incumbent permit holders.
Pricing Analysis
Volume-discount tiering structures dominate lease negotiations, with medium and large units commanding lower per-square-meter rates than small configurations despite higher absolute revenue. Price differentiation rests on environmental control precision and Swissmedic compliance certification, separating Lake Geneva pharmaceutical storage from standard household overflow. Pricing pressure stems from mixed-use basement storage in new Zurich residential towers, eroding climate-controlled premiums. Commercial e-commerce sellers exhibit lowest price sensitivity due to inventory holding cost arbitrage, while single-person rental households in dense urban cores drive highest turnover velocity at tightest margins.
Supply Chain Analysis
Strategic stockpile preferences dominate facility construction inputs, with galvanized steel partitioning and redundant HVAC systems sourced months ahead of SIA approval timelines to compress development cycles. Supply draws from Germany, Italy, and Austria for steel components, while HVAC equipment originates from Swiss franc-denominated European import channels. Raw material dependencies center on steel sheet, aluminum framing, and compressor units. Supply chain risk concentrates in single-source vulnerability for Swissmedic-validated temperature monitoring systems. Distribution runs through cantonal construction wholesalers and specialized climate-equipment installers serving industrial periphery zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland's self-storage market constitutes a defensive-moat opportunity anchored in regulatory entrenchment, where cantonal zoning permits function as non-replicable assets that insulate incumbent cash flows from competitive replication.
For Market Incumbents: Compound permit portfolios through cantonal aggregation ahead of zoning liberalization debates, securing industrial periphery positions in Geneva and Vaud where Règlement sur les zones d'activité restrictions tighten fastest. Accelerate SIA energy retrofit compliance to capture federal subsidy pools before 2028 Basel ordinance deadlines erode margins for laggard facilities. For New Entrants and Emerging Players: Anchor in Ticino's storage stock deficit relative to German-speaking canton benchmarks, exploiting Mendrisio district zoning debates to secure pioneer permits before cross-border e-commerce sellers consolidate Como-based alternatives. Deploy automated-access platforms with digitized inventory management to differentiate from legacy operators in underpenetrated Italian-speaking catchments. For Investors and Strategic Acquirers: SIA energy efficiency retrofit mandates reshape the acquisition landscape by bifurcating facility economics between compliant assets and stranded inventory requiring capital-intensive HVAC upgrades. Target stabilized private portfolios in Lake Geneva corridor with completed Swissmedic validation and heat recovery ventilation installations. Monitor cantonal zoning liberalization legislative calendars as inflection signals for permit value repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Cantonal Permit Aggregation | Consolidating Zurich and Vaud zoning entitlements builds irreplicable competitive moats against fragmented municipal approval processes. |
| Climate-Controlled Retrofit Acceleration | Preemptive SIA energy compliance captures federal photovoltaic and heat pump subsidies before Basel's 2028 ordinance enforcement. |
| Urban Micro-Warehouse Network Expansion | Franchise-scaled density in Lausanne and Renens freight corridors converges self-storage with last-mile parcel locker distribution nodes. |
| Swissmedic Validation Investment | Temperature-monitoring certification unlocks pharmaceutical sample storage premiums from Novartis and Roche medical device representatives. |
| Automated Access Platform Deployment | Digitized unit management and mobile-enabled entry displace physical key handoffs, compressing staffing ratios in premium Zurich locations. |
Research Methodology
The analysis maps climate-controlled, drive-up, indoor, and outdoor facility configurations, each validated through facility operators, cantonal zoning officials, pharmaceutical logistics managers, and commercial real estate brokers. Primary interviews with placeB AG franchise partners, Homebox Switzerland SA automation specialists, and Shurgard Self-Storage portfolio managers combined with secondary validation from SIA structural standards documentation, Swissmedic temperature compliance guidelines, cantonal zoning board filings, and federal building energy subsidy registries. Bottom-up unit economics triangulated against top-down cantonal construction permit flows.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include environmental control specification, unit size granularity, ownership capital structure, and end-use application purpose. CAGRs derived from facility absorption rates, rental rate trajectories, and development pipeline tracking. Industry-specific forecast inputs incorporated cantonal zoning liberalization probability assessments and SIA energy retrofit compliance cost curves.
Material uncertainties — cantonal zoning board composition shifts, Swiss franc import exchange rate volatility, and mixed-use residential storage substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions around permit approval timelines and HVAC equipment cost stability. Practitioners should keep alternative scenarios live as federal building energy subsidy program renewals and Ticino zoning debates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
US Landscaping Services Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Lease Management Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
US Home Service Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
United States Self Storage Market