
 US Landscaping Services Market | 2026-2036
US Landscaping Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Landscaping Services Market Outlook
Market Context
Premium landscape architecture is decoupling from commodity lawn mowing in both pricing and talent requirements. BrightView Holdings leverages its national footprint to secure multi-site commercial contracts with standardized service levels. TruGreen Inc. anchors the residential subscription segment through recurring fertilization and pest management programs. The Davey Tree Expert Company specializes in high-margin arboriculture and utility vegetation management.
Technical Definition and Segments
US landscaping services encompass the planning, installation, and ongoing maintenance of exterior plant material, hard surfaces, and irrigation systems for functional and aesthetic site enhancement. Lawn Maintenance represents the mature revenue base with predictable recurring cash flows, while Hardscaping commands premium pricing due to specialized masonry and drainage engineering requirements. Landscape Design is capturing elevated interest from commercial clients seeking LEED-compliant site plans, and Irrigation Installation is accelerating as municipal water restrictions in drought-prone states drive demand for smart controller retrofits.
Regulatory Framework
EPA Clean Water Act provisions and state-level pesticide licensing through departments of agriculture shape operational compliance burdens and technician certification costs. OSHA landscaping safety standards and FIFRA-mandated application protocols constrain service delivery methods while creating barriers for unlicensed operators. Stakeholders must monitor evolving state water-use ordinances and electrification incentives that could restructure equipment procurement decisions.
Market Dynamics
EPA stormwater runoff enforcement is restructuring contract specifications for commercial property managers, forcing bundled maintenance agreements that integrate drainage compliance with aesthetic upkeep across multi-site portfolios.
Growth Catalysts
- Smart irrigation retrofits:Municipal water-use ordinances in drought-prone states mandate controller upgrades, creating recurring installation revenue streams for certified technicians.
- LEED-compliant site planning:Commercial developers pursue landscape architecture credits to satisfy green building certification requirements and secure preferential financing.
- Texas metropolitan clusters:Drought-tolerant design mandates in Austin, Dallas-Fort Worth, and Houston reshape procurement specifications toward xeriscaping and native plant palettes.
Market Restraints
- FIFRA-mandated certification costs:Pesticide application licensing through state departments of agriculture imposes recurring training expenses and technician turnover penalties.
- Seasonal labor concentration:H-2B visa program caps constrain workforce availability during peak spring installation windows in northern states.
- Diesel equipment dependency:Commercial-grade mowers and aerators lock operators into volatile fuel cost exposure absent electrification capital reserves.
Strategic Opportunities
- Electrification incentives:IRA clean vehicle and equipment tax credits subsidize battery-powered commercial mower fleet conversions for early-adopting contractors.
- Utility vegetation management:Power transmission corridor clearance contracts offer multi-year recurring revenue with higher margins than residential maintenance.
- Stormwater credit trading:Municipal green infrastructure programs enable landscape contractors to monetize bioswale and permeable pavement installations as regulatory offsets.
Industry Challenges
- Arboriculture skill scarcity:International Society of Arboriculture certification requirements outpace vocational program output, constraining Davey Tree-style high-margin service expansion.
- OSHA compliance documentation:Heat illness prevention and trench safety protocols demand administrative overhead that fragments small-operator competitive capacity.
Report Scope
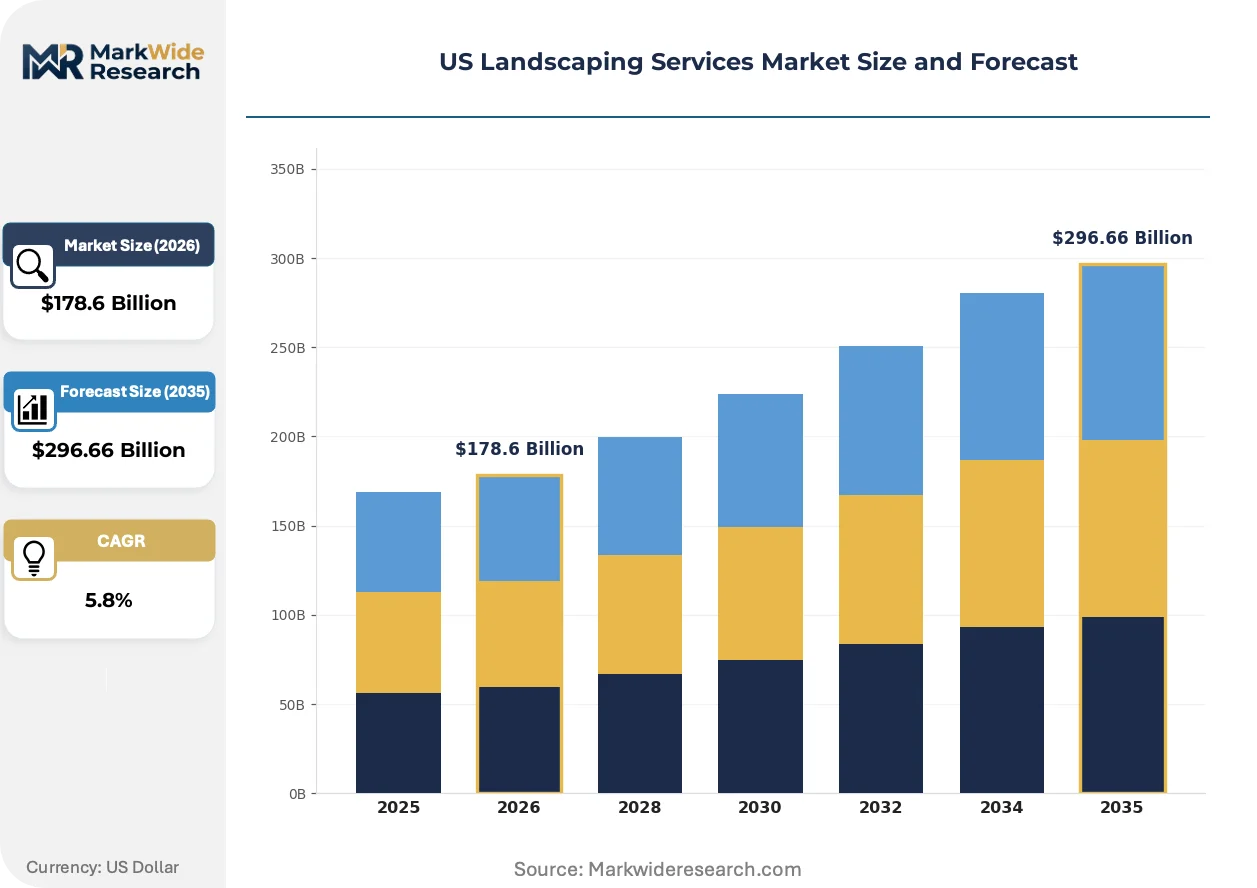
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Landscaping Services Market |
| Market Size in 2026 | $178.6 Billion |
| Market Size in 2035 | $296.66 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lawn Maintenance, Landscape Design, Hardscaping, Irrigation Installation Client Type: Residential, Commercial, Municipal, Institutional Service Frequency: One-time, Weekly, Bi-weekly, Monthly Lawn Care Type: Fertilization, Weed Control, Pest Management, Turf Management |
| Companies Covered | The F.A. Bartlett Tree Expert Company, SavATree, BrightView Holdings, Monarch Landscape Companies, HeartLand, The Davey Tree Expert Company, Yellowstone Landscape, Gothic Landscape, TruGreen Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Landscaping Services Market Strategic Shifts
Battery-powered commercial equipment is crossing performance thresholds that reshape capital allocation, while regulatory compliance automation and buyer consolidation rewrite contract structures.
Autonomous robotic mowers are electrifying fleet management economics for large commercial contracts. Property management firms with multi-site portfolios are piloting supervised autonomous units on corporate campuses and homeowner association common areas. This technology is compressing labor hour requirements per acre while elevating technician roles toward equipment oversight and precision edging.
EPA Clean Water Act municipal separate storm sewer system permits are tightening nitrogen and phosphorus runoff limits for commercial sites. Landscape contractors must now document fertilizer application rates and buffer zone maintenance to maintain general permit compliance. Texas and Florida markets face the steepest compliance cost escalation as state environmental agencies align enforcement with federal nutrient load targets.
Multi-year bundled service agreements are displacing seasonal bid contracts in commercial property management. Institutional investors acquiring apartment and office portfolios favor standardized national providers over fragmented local operators. This concentration is most visible in Sun Belt metropolitan statistical areas where net migration sustains construction activity and long-term maintenance backlog accumulation.
US Landscaping Services Market Segmentation
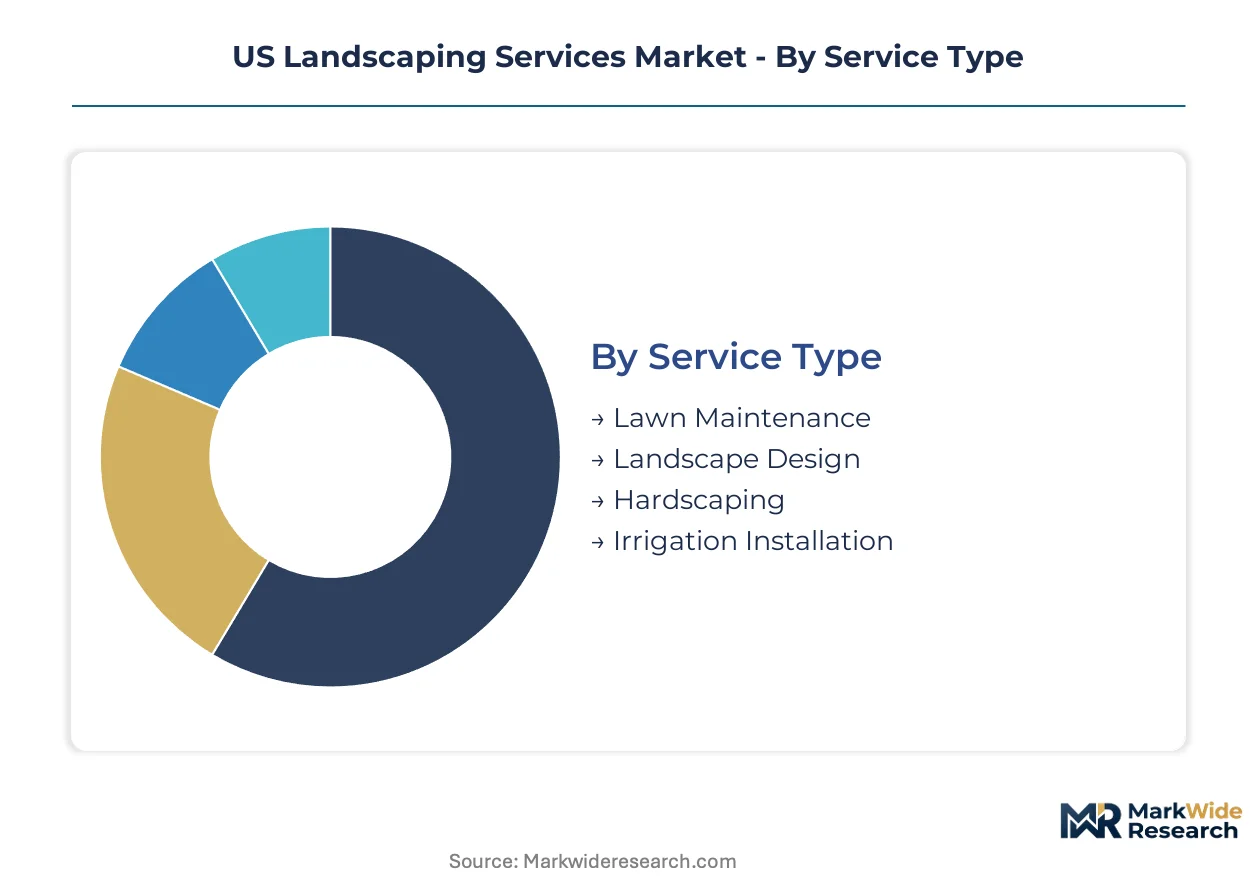
Segmentation in the US landscaping services market reveals how service delivery models, client procurement patterns, and regulatory compliance requirements create distinct operational and margin profiles across contractor portfolios.
Service Type:
Standalone installation services operate on project-based margins while recurring maintenance programs embed into multi-year facility management contracts.
- Lawn Maintenance:Mowing, edging, and debris removal on recurring schedules generate predictable cash flows. Demand concentrates in suburban residential clusters and commercial office parks where property managers bundle aesthetic upkeep with stormwater compliance documentation.
- Landscape Design:Site planning and plant material specification require certified landscape architects. LEED credit procurement in Texas metropolitan areas and Florida commercial developments drives specification toward drought-tolerant native palettes and permeable surface integration.
- Hardscaping:Retaining walls, patios, and drainage systems demand masonry and civil engineering coordination.
- Irrigation Installation:Smart controller retrofits and drip system conversions accelerate under municipal water-use ordinances.
Lawn Maintenance leads volumes today; Irrigation Installation is gaining share fastest.
Client Type:
Procurement sophistication varies sharply across client categories, with institutional buyers demanding certified compliance documentation that fragments small-operator competitive capacity.
- Commercial:Property management firms and corporate facility directors negotiate multi-site bundled agreements. EPA stormwater permit compliance requirements in Texas and Florida force integration of drainage maintenance with aesthetic contracts.
- Residential:Homeowner subscriptions for fertilization and pest management anchor recurring revenue models. TruGreen-style national providers dominate through standardized service protocols and automated scheduling platforms.
- Municipal:Parks departments and transportation agencies bid large-scale maintenance contracts with prevailing wage requirements.
- Institutional:Universities and healthcare systems require ISA-certified arboriculture and OSHA-compliant safety documentation.
Residential contracts dominate transaction volume; Commercial agreements command premium pricing per square foot.
Service Frequency:
Scheduling density directly determines labor deployment efficiency and equipment utilization rates across seasonal demand curves.
- Weekly:High-frequency mowing and edging programs maximize crew routing efficiency. Corporate campuses and homeowner associations in Sun Belt states sustain year-round weekly schedules absent winter dormancy.
- Bi-weekly:Reduced-frequency maintenance balances cost sensitivity with aesthetic standards. Residential subdivisions in northern states concentrate bi-weekly demand during compressed spring and fall growing seasons.
- Monthly:Seasonal cleanup and ornamental pruning operate on project-based margins.
- One-time:Installation projects and emergency storm response capture spot market pricing.
Weekly service anchors recurring revenue; One-time installation projects deliver the steepest margin expansion.
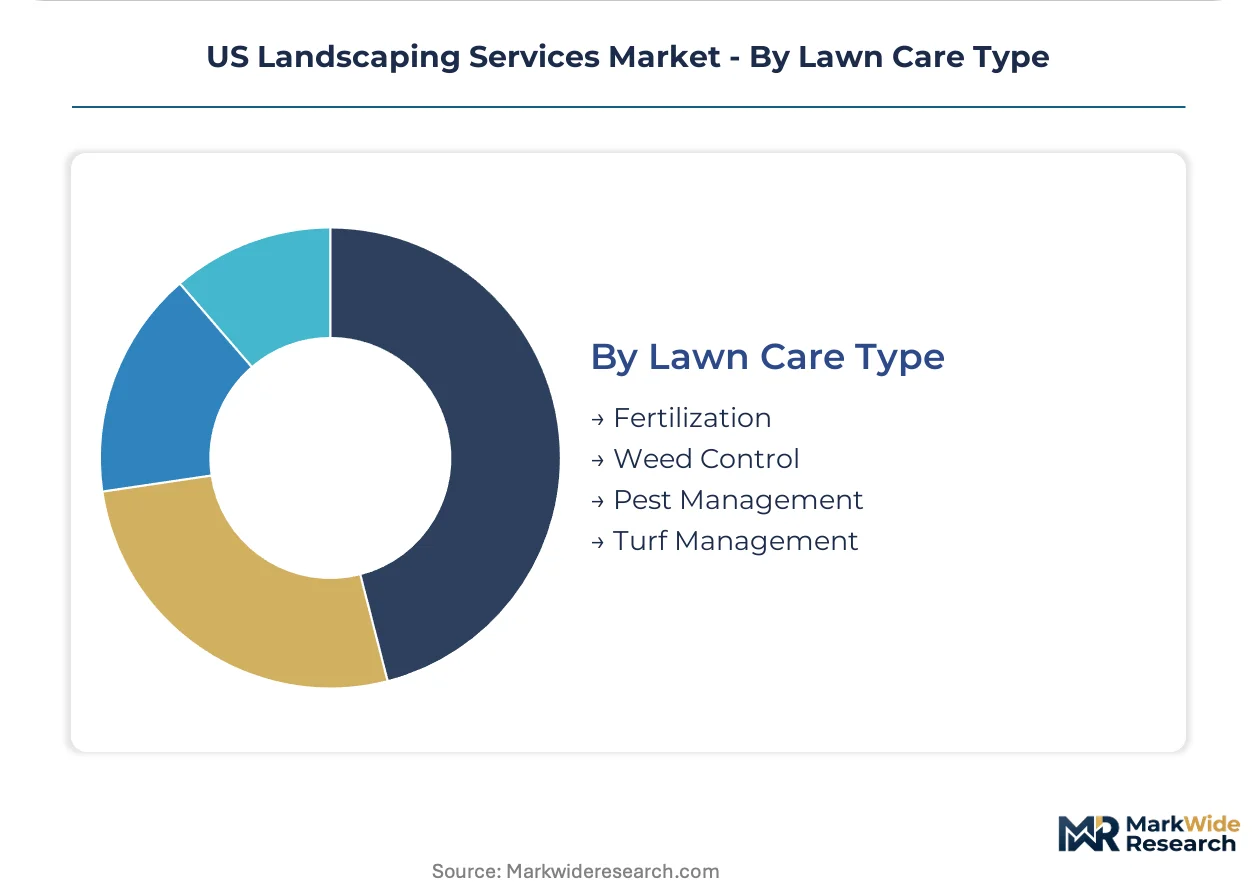
Lawn Care Type:
Regulatory licensing requirements and chemical application protocols create tiered technician certification barriers that reshape competitive positioning.
- Fertilization:Nitrogen and phosphorus application rates face EPA Clean Water Act runoff limits. Texas and Florida contractors must document buffer zone maintenance and seasonal blackout periods to maintain general permit compliance.
- Pest Management:FIFRA-mandated pesticide licensing through state departments of agriculture imposes recurring training costs. Commercial property managers increasingly require integrated pest management protocols that reduce chemical dependency.
- Weed Control:Pre-emergent and post-emergent herbicide programs require calibrated application equipment.
- Turf Management:Aeration, overseeding, and soil amendment programs demand specialized mechanical equipment.
Fertilization commands the largest addressable base; Pest Management carries the highest certification premium per service hour.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hispanic immigrant labor concentration anchors landscaping employment across Sun Belt metropolitan corridors, with Texas and Florida absorbing the largest seasonal workforce flows under H-2B visa allocations.
Texas
Drought-tolerant design mandates in Austin, Dallas-Fort Worth, and Houston reshape procurement toward xeriscaping and native plant palettes. EPA stormwater runoff enforcement through Texas Commission on Environmental Quality general permits forces commercial property managers to document fertilizer application rates and buffer zone maintenance. The Dallas-Fort Worth Metroplex sustains the densest contractor clustering, where bundled multi-site maintenance agreements displace fragmented seasonal bidding.
Florida
Commercial developers in Miami, Orlando, and Tampa pursue LEED landscape architecture credits to secure preferential financing and green building certification. State environmental agencies align nutrient load targets with federal Clean Water Act requirements, escalating compliance documentation burdens for nitrogen and phosphorus application. South Florida's year-round growing season sustains weekly service schedules absent winter dormancy, compressing crew routing efficiency advantages.
California
Municipal water-use ordinances in Los Angeles, San Diego, and the Bay Area mandate smart irrigation controller retrofits, creating recurring installation revenue for certified technicians. OSHA heat illness prevention protocols impose administrative overhead that fragments small-operator competitive capacity in Central Valley agricultural corridor spillover markets. The Los Angeles-Orange County metro sustains premium landscape architecture demand from entertainment industry estate management.
Arizona
Desert-adapted design specifications in Phoenix and Tucson metropolitan areas drive procurement toward low-water-use plant material and permeable hardscape integration. State departments of agriculture enforce FIFRA-mandated pesticide licensing with recurring training cost burdens. The Phoenix-Mesa-Scottsdale corridor concentrates national provider branch networks serving homeowner association common areas and corporate campus portfolios.
Georgia
Atlanta's commercial property management sector consolidates around standardized national providers as institutional investors acquire multi-site apartment and office portfolios. EPA municipal separate storm sewer system permits tighten nitrogen runoff limits for commercial sites across the Atlanta-Sandy Springs-Roswell metro. Piedmont region clay soils sustain aeration and soil amendment program demand distinct from sandy coastal plain specifications.
US Landscaping Services Market Competitive Environment
Top-tier vendors anchor national multi-site contract portfolios, while regional specialists and fragmented local operators compete on relationship density and specialized certification depth. The vendor base stratifies across three tiers: publicly traded national platforms with standardized service levels, multi-state regional consolidators with category depth, and single-market owner-operators with equipment-limited capacity. Two strategic archetypes dominate competitive positioning: scale-driven maintenance platforms optimizing route density, and arboriculture specialists capturing premium pricing through ISA-certified technical scarcity. M&A activity concentrates among regional consolidators acquiring owner-operator books, while electrification capital reserves differentiate early-adopting fleet investors.
Within the national-scale tier, BrightView Holdings and TruGreen Inc. exemplify divergent strategic positioning. BrightView leverages its footprint to secure multi-site commercial contracts with bundled stormwater compliance documentation, occupying a position aligned with institutional property management consolidation. TruGreen anchors residential subscription economics through recurring fertilization and pest management programs with automated scheduling platforms. The Davey Tree Expert Company sits within the specialized arboriculture vector, representing high-margin utility vegetation management and technical certification scarcity.
| Leading Market Players |
|---|
| The F.A. Bartlett Tree Expert Company |
| SavATree |
| BrightView Holdings |
| Monarch Landscape Companies |
| HeartLand |
| The Davey Tree Expert Company |
| Yellowstone Landscape |
| Gothic Landscape |
| TruGreen Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-tier divergence between ISA-certified arboriculture specialists and commodity lawn maintenance operators manifests in both hourly rate spreads and equipment procurement patterns across contractor portfolios. EPA stormwater compliance documentation and FIFRA-mandated pesticide licensing create tiered cost structures that concentrate premium pricing power among credentialed national platforms while fragmenting margin capacity for unlicensed local operators.
Pricing Analysis
Bundled multi-site maintenance agreements versus fragmented seasonal bid contracts anchor the dominant pricing split across commercial property management. Three-tier pricing structure across premium, standard, and economy levels separates ISA-certified technical services from route-optimized weekly mowing and uninsured spot-market installation work. Price differentiation centers on EPA compliance documentation depth and equipment electrification status. Cost compression in the commodity maintenance tier is intensifying because H-2B visa constraints elevate labor costs faster than automation offsets. Residential subscription buyers exhibit highest price sensitivity; institutional property managers with LEED mandates show lowest.
Supply Chain Analysis
Diesel-powered commercial mower manufacturing rests on engine suppliers concentrated in Wisconsin and Ohio, while smart irrigation controller assembly draws from semiconductor fabrication anchored in Taiwan and South Korea. Battery cell production for electrified fleet conversions sources from Chinese and South Korean cathode material suppliers. Fertilizer and pre-emergent herbicide distribution runs through agricultural chemical wholesalers with regional blending facilities in Texas and Florida. Single-source vulnerability concentrates in lithium-ion battery supply for zero-turn mower electrification programs. Downstream distribution channels branch through national equipment financiers and dealer networks serving contractor fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
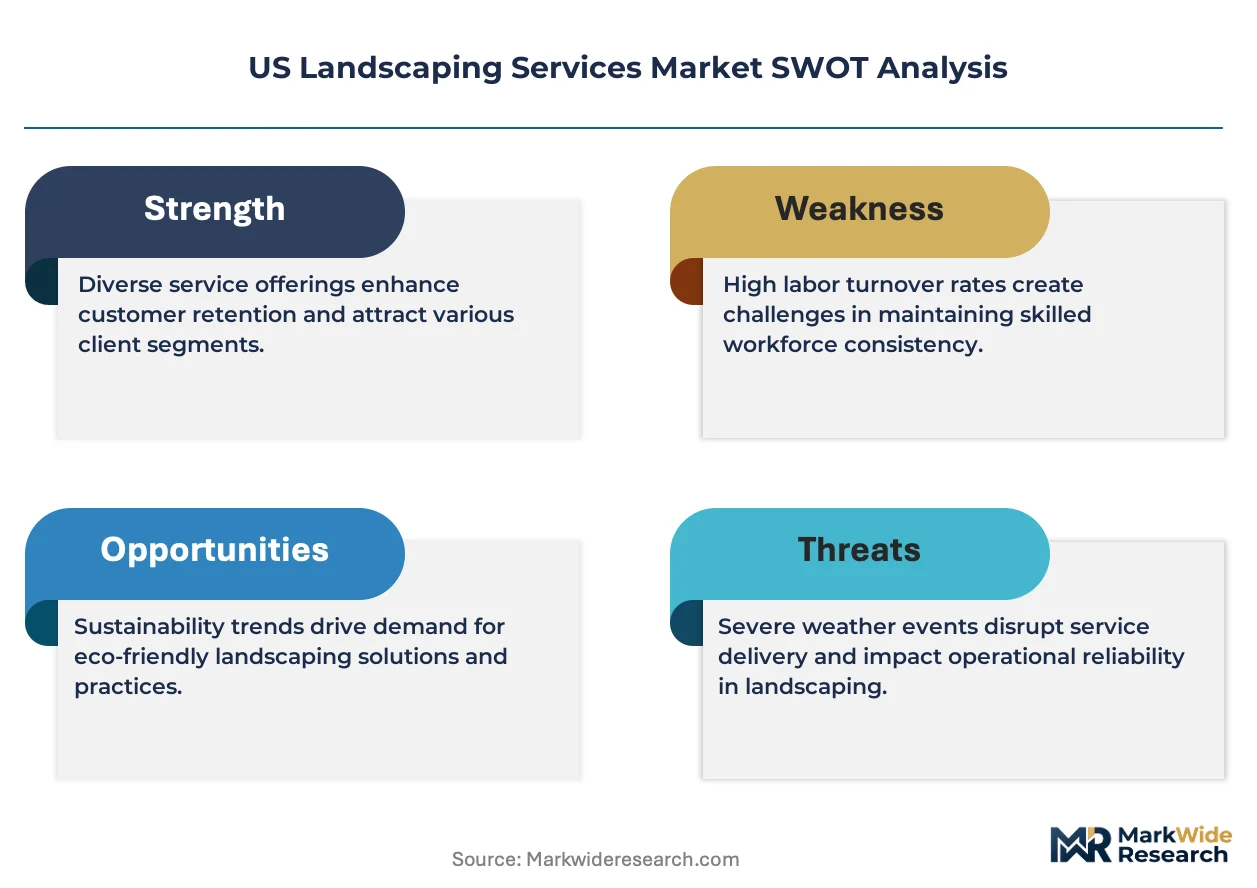
The US landscaping services market reads as a late-cycle quality story where drought-tolerant design mandates and EPA stormwater enforcement shift procurement specifications toward certified technical capabilities and documented compliance infrastructure.
For Market Incumbents: Deepen vertical integration into smart irrigation controller distribution and battery-powered equipment servicing to capture electrification subsidy flows and lock out regional consolidators. Expand ISA-certified arboriculture training pipelines to defend against technician scarcity eroding high-margin utility vegetation management contracts. Electrification capital reserves represent the critical lever for multi-site contract retention as property managers standardize ESG-aligned fleet specifications. For New Entrants and Emerging Players: Capture stormwater credit trading and bioswale installation niches in Texas and Florida metropolitan corridors where municipal green infrastructure programs create regulatory offset monetization opportunities. Target mid-sized commercial property management firms in Sun Belt secondary metros underserved by national platform branch density. Lead with EPA compliance documentation automation as the go-to-market wedge against fragmented local operators lacking administrative capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where owner-operator retirement waves intersect with institutional investor portfolio standardization demands across multi-site commercial real estate. Position acquisition screening toward regional consolidators with electrification fleet investments and certified technician benches spanning multiple metropolitan statistical areas. Watch H-2B visa allocation rulings and IRA equipment tax credit extension debates as inflection signals for labor cost trajectory and capital expenditure incentive durability.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Fleet Conversion | IRA clean vehicle tax credits subsidize battery-powered commercial mower procurement for early-adopting contractors. |
| ISA Certification Pipeline Expansion | Arboriculture skill scarcity constrains high-margin utility vegetation management service growth for technical specialists. |
| Smart Irrigation Platform Integration | Municipal water-use ordinances in drought-prone states mandate controller retrofits with recurring installation revenue. |
| Stormwater Compliance Documentation Automation | EPA Clean Water Act permit enforcement forces fertilizer application rate tracking across commercial property portfolios. |
| Multi-Site Bundled Service Agreement Standardization | Institutional real estate investors favor national providers with consistent service levels across acquired portfolios. |
Study Parameters
Direct dialogue with commercial property management directors, landscape contractor operations managers, municipal parks department procurement officers, and agricultural extension service specialists grounded qualitative findings. Secondary validation drew from EPA general permit filings, Texas Commission on Environmental Quality enforcement records, OSHA landscaping injury databases, and H-2B visa allocation reports. Bottom-up crew deployment models and top-down construction spending indices provided triangulation across market sizing approaches.
Bottom-up segment modeling tracked service frequency, client type, and regional labor cost differentials across the projection horizon. Segmentation dimensions included service type, client procurement sophistication, certification requirements, and metropolitan climate zone. CAGRs derived from historical contract value escalations and forward-looking equipment replacement cycles. Irrigation installation growth assumptions incorporated municipal ordinance adoption curves and smart controller price elasticity.
H-2B visa policy shifts, IRA incentive duration uncertainties, and EPA enforcement intensity variations are the dominant revision risks to contractor capacity and equipment procurement forecasts. Forecasts reflect assumptions around labor availability and regulatory compliance cost trajectories. A concentrated set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Lease Management Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Asia-Pacific Self Storage Market