
 South Korea Self-Storage Market | 2026-2036
South Korea Self-Storage Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Self-Storage Market Analytics
Market Context
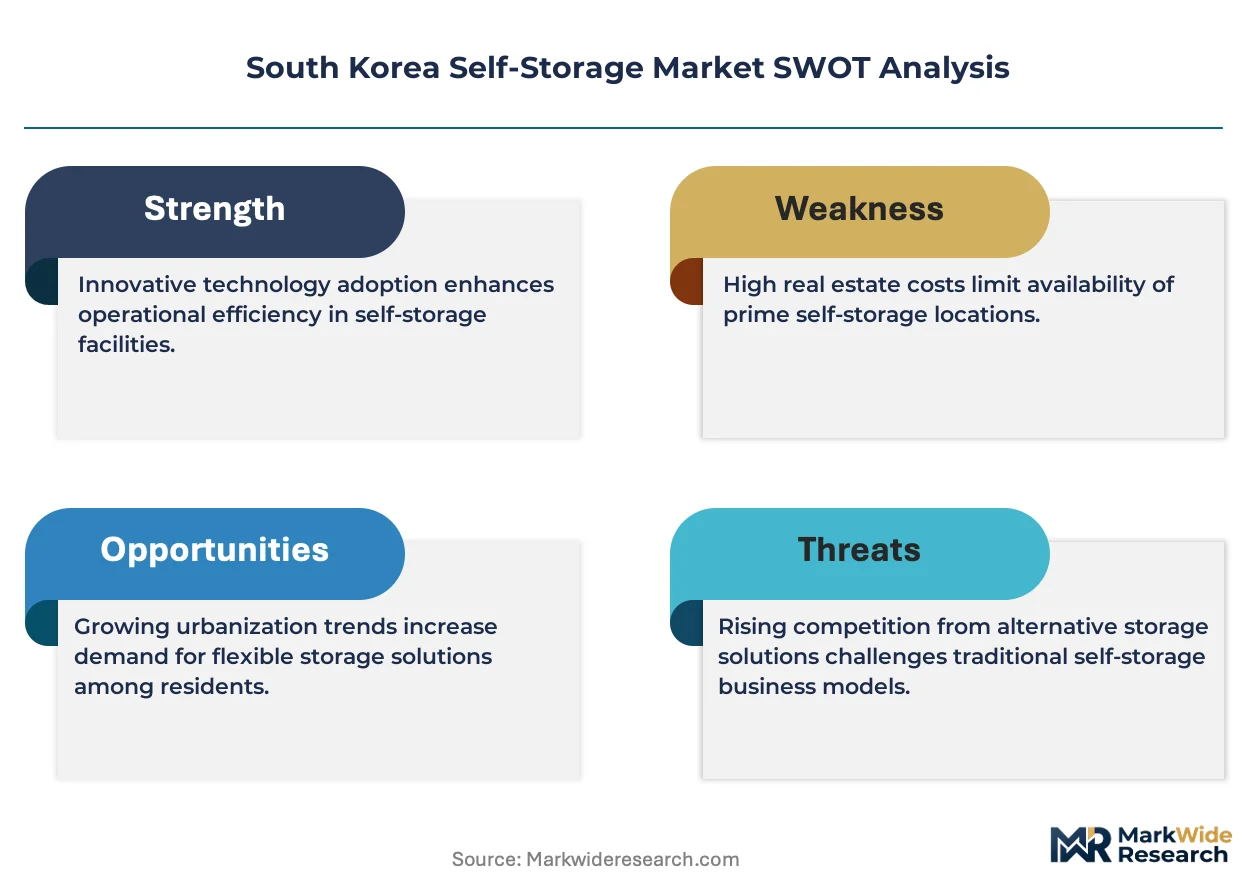
Urban logistics labor shortages in Seoul's last-mile delivery sector is reorganizing how small businesses manage inventory overflow, pushing merchants toward off-site storage solutions. Extra Space Asia leverages its climate-controlled network across the capital region to capture this commercial migration. Boxful Korea differentiates through technology leadership in mobile storage and digital inventory management. Lotte Self Storage anchors its position within mixed-use retail-residential complexes, securing foot traffic and brand visibility.
Technical and Structural Dimensions
South Korea self-storage comprises leased modular space—typically steel-construction units ranging from one to thirty square meters—designed for temporary household, commercial, or vehicle asset holding, with climate-controlled variants maintaining 18–24°C and 45–55% relative humidity for electronics and document preservation. Standard storage dominates facility footprints due to lower capital intensity and faster lease-up, while climate-controlled commands premium pricing from Seoul's dense residential base. Business storage is expanding fastest as e-commerce merchants seek flexible warehousing without long-term commercial leases.
Regulatory Environment
MFDS guidelines on pharmaceutical sample storage and KOSHA workplace safety standards indirectly shape facility design requirements for business-oriented operators. The Ministry of Land, Infrastructure and Transport's mixed-use zoning relaxations and Seoul Metropolitan Government's small-business support programs together expand permissible locations and subsidize tenant migration. Stakeholders must monitor whether municipal fire codes evolve to mandate sprinkler retrofitting in existing facilities, as compliance costs would reshape competitive economics for older assets.
Market Dynamics
Seoul's apartment size compression—now averaging under 60 square meters for new units—is forcing households and micro-businesses off-site for inventory and seasonal storage, redirecting demand toward modular leased space.
Growth Catalysts
- Remote-work inventory overflow:Seoul-based freelancers and e-commerce sellers require flexible warehousing for home-office equipment and merchandise stockpiles without commercial lease commitments.
- Mixed-use zoning relaxations:The Ministry of Land, Infrastructure and Transport permits self-storage integration into retail-residential complexes, unlocking supply in transit-rich neighborhoods previously zoned out.
- Climate-controlled premium uptake:Electronics merchants and document archivists in Busan's humid coastal climate pay premiums for humidity-regulated units protecting semiconductors and legal records.
Market Restraints
- Steel input cost volatility:Modular unit fabrication depends on galvanized steel pricing, exposing facility developers to construction cost swings that compress development yields.
- Seoul land scarcity:Capital region site availability limits greenfield expansion, forcing operators toward expensive brownfield conversions or secondary-city migration.
- Fire code retrofit uncertainty:Potential sprinkler mandates for existing facilities would impose capital burdens on older assets without revenue offsets.
Strategic Opportunities
- Busan secondary-city expansion:Korea's second-largest metro area shows underpenetrated self-storage supply relative to comparable Asian port cities, offering first-mover positioning.
- Digital inventory convergence:Mobile storage operators integrating RFID tracking and cloud-based asset management capture tech-forward commercial tenants.
- Small-business subsidy programs:Seoul Metropolitan Government's tenant migration incentives reduce customer acquisition costs for operators targeting merchant segments.
Industry Challenges
- Last-mile logistics labor shortages:Seoul's depleted delivery workforce complicates mobile storage pickup scheduling and customer service reliability.
- Pharmaceutical storage compliance:MFDS guidelines on temperature-controlled pharmaceutical samples require specialized facility certifications that extend permitting timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Self-Storage Market |
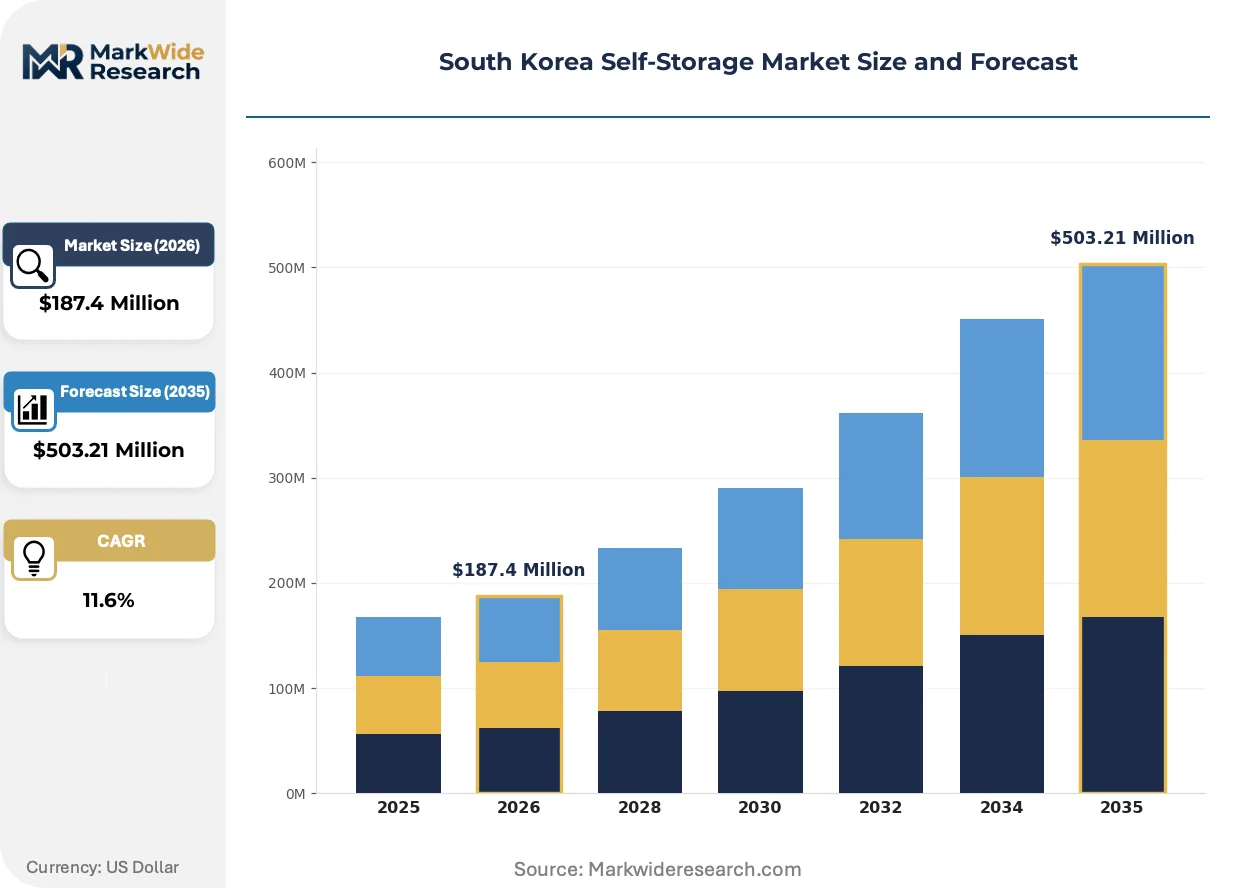
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Climate-Controlled, Standard, Vehicle Storage, Business Storage Customer Type: Residential Users, Small Businesses, Students, Corporations Facility Size: Small Units, Medium Units, Large Units, Extra Large Units Service Model: Self-Service, Full-Service, Mobile Storage, Managed Storage |
| Companies Covered | Extra Space Asia, Daloc, Qubizkorea Co Ltd (q Storage), Self Box, Boxful Korea, Mini-storage (sampyo Energy), Nemo S&S Co Ltd (nemo Storage), Lotte Self Storage, Storehub Korea Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Self-Storage Market Evolving Landscape
Technology integration and regulatory adaptation are compressing traditional self-storage models into digitally orchestrated, multi-use logistics nodes serving both consumer and commercial demand.
Mobile storage with door-to-door container delivery is decomposing the fixed-facility model by eliminating customer transport burdens. Seoul apartment dwellers lacking vehicle access adopt container retrieval services at three times the rate of traditional unit rentals. This shift is fragmenting market share between asset-light mobile operators and capital-intensive fixed facilities.
The Ministry of Land, Infrastructure and Transport's mixed-use zoning amendments enable self-storage co-location with retail and residential towers. Developers now embed storage mezzanines within parking structures and podium levels. Seoul's Gangnam and Yeongdeungpo districts show the densest deployment of these integrated formats.
Subscription-based storage contracts are displacing annual prepaid leases among millennial tenants. Busan and Seoul operators offering monthly digital billing with pause-resume flexibility report higher retention from gig-economy workers with irregular inventory cycles. This behavioral shift pressures legacy operators to modernize billing infrastructure or cede younger demographics.
South Korea Self-Storage Market Segmentation
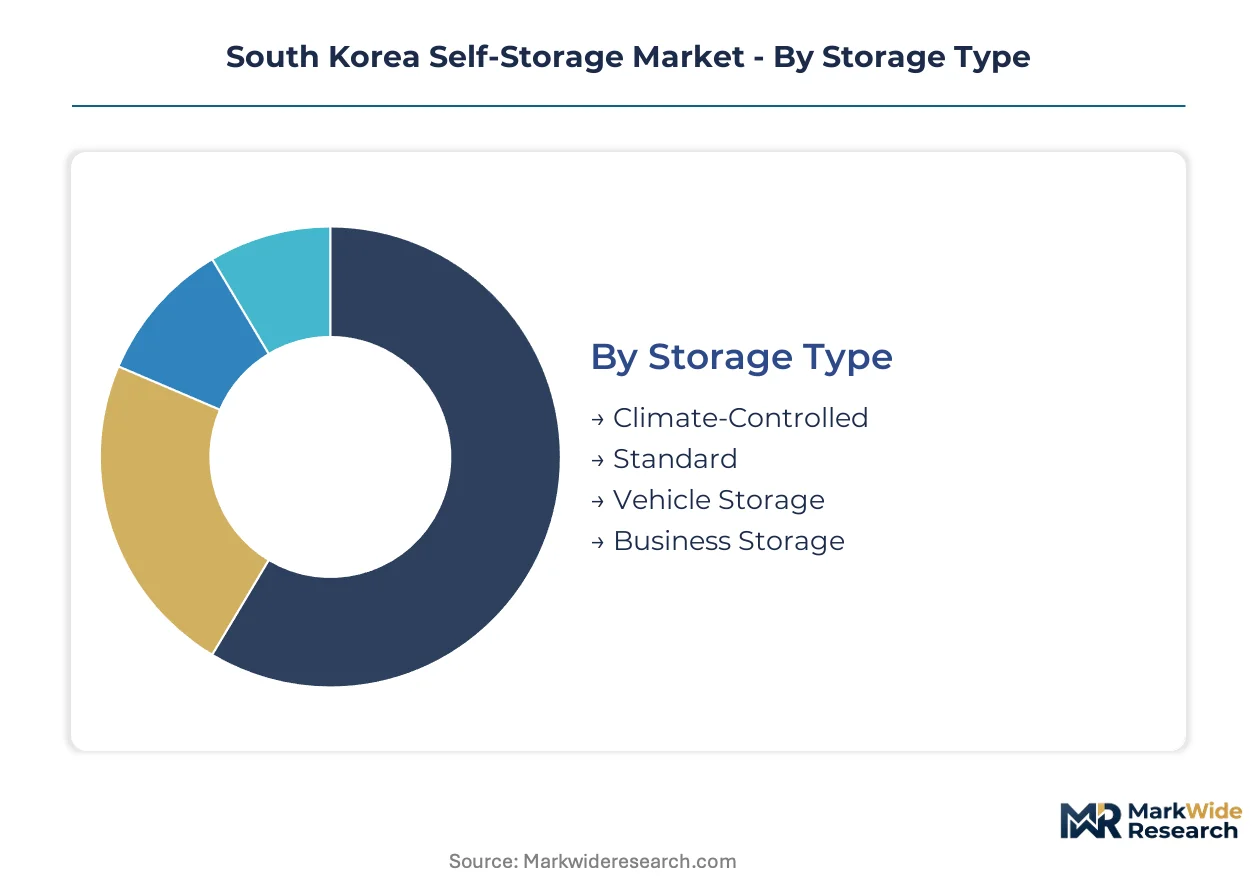
Segmentation in South Korea's self-storage market reveals how urban density and digital commerce reshape facility economics. Operators calibrate unit specifications, service tiers, and customer targeting to capture Seoul's apartment overflow and Busan's commercial warehousing migration.
Storage Type:
Channel distribution varies sharply across storage types, with climate-controlled units flowing through premium real estate channels while standard storage dominates high-volume retail corridors.
- Climate-Controlled:Steel-construction units maintain 18–24°C and 45–55% relative humidity through HVAC systems. Seoul's electronics merchants and document archivists in humid coastal zones pay premiums for semiconductor and legal record protection.
- Standard:Basic modular units without environmental regulation offer lower capital intensity and faster lease-up. These dominate facility footprints across the Seoul Capital Area where cost-sensitive residential overflow drives volume.
- Vehicle Storage:Secured bay or covered parking solutions target apartment dwellers lacking dedicated parking. Demand concentrates in Seoul's dense districts where vehicle ownership exceeds storage capacity.
- Business Storage:Flexible warehousing for e-commerce inventory and equipment without long-term commercial lease commitments. MFDS guidelines on pharmaceutical samples and KOSHA workplace safety standards shape facility design for specialized operators.
By volume, Standard leads. By growth pace, Business Storage is expanding most quickly.
Customer Type:
Cost tier differentiation separates premium corporate contracts from economy residential subscriptions, with margin compression deepest in the student segment.
- Residential Users:Apartment dwellers in Seoul's sub-60-square-meter units seeking seasonal and overflow storage. Remote-work equipment stockpiles and space constraints accelerate adoption of subscription-based monthly billing.
- Small Businesses:E-commerce sellers and freelancers requiring flexible inventory warehousing. Seoul Metropolitan Government's tenant migration subsidies reduce acquisition costs for operators targeting this merchant base.
- Students:Seasonal storage during academic breaks, concentrated in university-dense districts like Sinchon and Anam. Price sensitivity drives demand for shared-unit arrangements and short-term contracts.
- Corporations:Document archiving and equipment storage with compliance requirements. MFDS temperature-control mandates extend permitting timelines for pharmaceutical sample storage.
By volume, Residential Users dominate. By growth pace, Small Businesses gain share fastest.
Facility Size:
Application-based allocation shows small units serving residential overflow while large units anchor commercial warehousing contracts.
- Small Units:One to five square meter lockers for document boxes and seasonal items. Seoul's millennials adopt these at triple the rate of larger formats due to apartment size constraints.
- Medium Units:Five to fifteen square meter spaces accommodating furniture and small business inventory. These balance lease-up velocity against revenue per square meter in mixed-use developments.
- Large Units:Fifteen to thirty square meter configurations for household moves and commercial stockpiles. Busan's port logistics businesses utilize these for temporary import-export staging.
- Extra Large Units:Thirty-plus square meter spaces for vehicle fleets, construction equipment, and bulk inventory. Limited supply in the capital region commands premium rates.
By volume, Medium Units lead. By growth pace, Small Units show the steepest expansion trajectory.
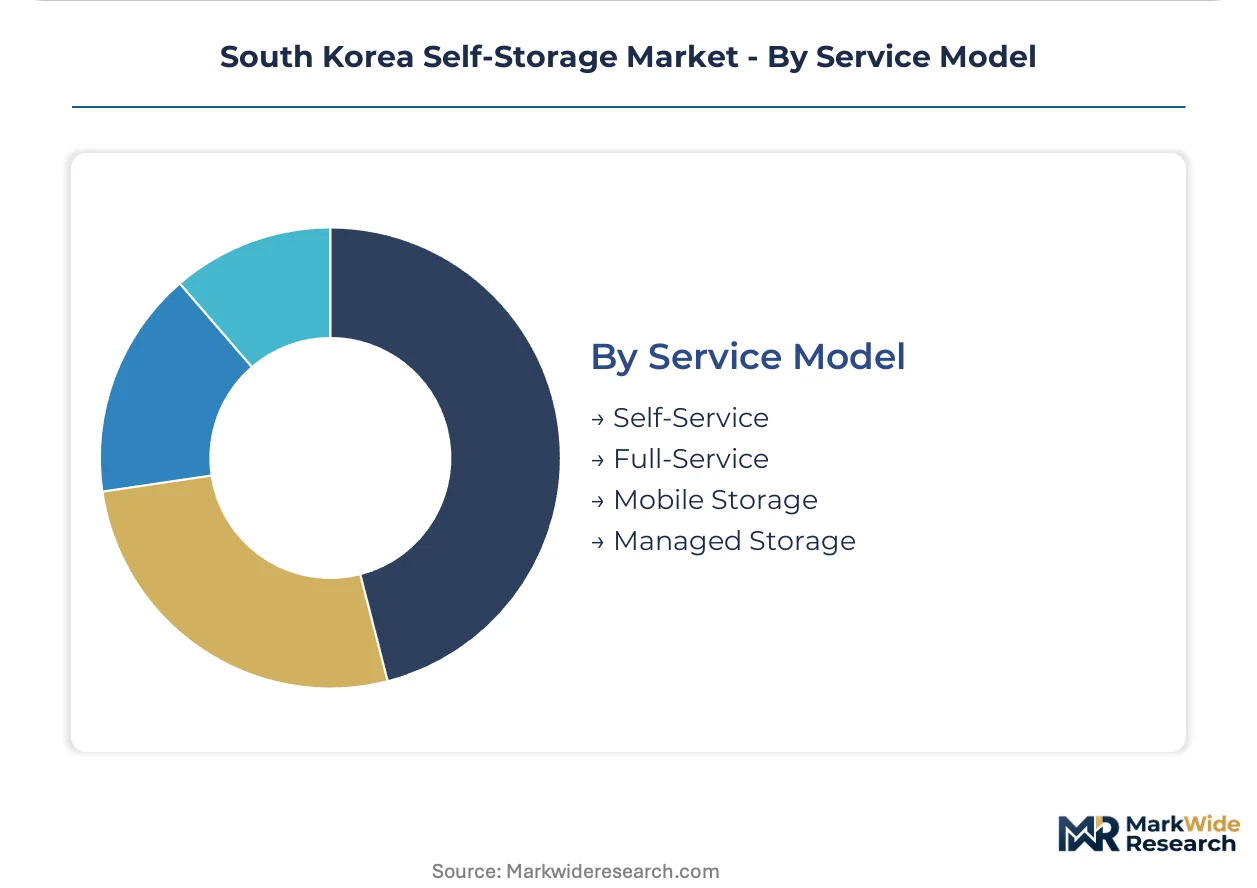
Service Model:
Geographic concentration patterns place self-service facilities in transit-rich neighborhoods while mobile storage penetrates vehicle-scarce districts.
- Self-Service:Customer-managed access through keypad or app-based entry systems. These dominate in Seoul's Gangnam and Yeongdeungpo mixed-use developments where zoning relaxations enable retail-residential integration.
- Full-Service:Staff-assisted loading, inventory management, and retrieval support. Premium positioning targets corporate clients with compliance documentation requirements.
- Mobile Storage:Door-to-door container delivery and retrieval eliminating transport burdens. Seoul apartment dwellers lacking vehicle access adopt this at three times the rate of traditional rentals.
- Managed Storage:Operator-controlled inventory tracking with digital asset management. RFID integration and cloud-based systems capture tech-forward commercial tenants in Busan's logistics corridor.
By volume, Self-Service leads. By growth pace, Mobile Storage climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Self-storage consumption across South Korea's major metropolitan zones diverges sharply by urban density and housing stock age, with Seoul's sub-60-square-meter apartments driving residential overflow demand while Busan's port logistics corridor anchors commercial warehousing migration.
Seoul Capital Area
Remote-work equipment stockpiles and shrinking apartment footprints push millennials toward climate-controlled units for electronics protection. Seoul Metropolitan Government's small-business tenant migration subsidies reduce customer acquisition costs for operators targeting merchant segments. Gangnam and Yeongdeungpo districts show densest deployment of mixed-use integrated storage formats within retail-residential towers.
Busan-Ulsan
Humid coastal conditions drive premium uptake for humidity-regulated units protecting semiconductors and legal records among electronics merchants. The Ministry of Land, Infrastructure and Transport's revised building codes permit self-storage in port-adjacent mixed-use developments. Busan's underpenetrated supply relative to comparable Asian port cities offers first-mover positioning for expansion-minded operators.
Daegu-Gyeongbuk
Manufacturing supply chain overflow from the region's textile and machinery clusters generates business storage demand without long-term commercial lease commitments. KOSHA workplace safety standards shape facility design requirements for industrial-oriented operators. Daegu's logistics corridor sees growing adoption of mobile storage for seasonal inventory staging.
Daejeon-Sejong
Government-research complex relocations create transient professional populations requiring flexible short-term storage solutions. Sejong City's planned urban design embeds storage mezzanines within parking structures of residential towers. The administrative capital's younger demographic profile accelerates subscription-based monthly billing adoption over traditional annual leases.
Gwangju-Honam
Agricultural equipment and seasonal harvest inventory drive demand for larger unit configurations in this southwestern hub. Student populations concentrated in university districts like Honam University area sustain price-sensitive shared-unit arrangements. Gwangju's lower land costs enable greenfield facility development absent the brownfield conversion premiums plaguing Seoul operators.
South Korea Self-Storage Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with climate-controlled network operators and mobile storage platforms occupying distinct strategic positions. The market structure shows moderate consolidation around real estate-backed incumbents with mixed-use development access, while technology-enabled challengers fragment the service model layer. Two dominant competitive moves define current positioning: zoning-driven mixed-use integration for fixed-facility operators, and digital inventory convergence for mobile service providers.
Within the integrated facility tier, Extra Space Asia and Lotte Self Storage exemplify real estate-backed positioning with climate-controlled networks across the capital region. Boxful Korea occupies the technology-forward mobile storage vector, representing the shift toward door-to-door container delivery and cloud-based asset management. These three anchors demonstrate how capital intensity separates fixed-facility economics from asset-light mobile operations.
| Leading Market Players |
|---|
| Extra Space Asia |
| Daloc |
| Qubizkorea Co Ltd (q Storage) |
| Self Box |
| Boxful Korea |
| Mini-storage (sampyo Energy) |
| Nemo S&S Co Ltd (nemo Storage) |
| Lotte Self Storage |
| Storehub Korea Co Ltd |
| Others |
Value Network & Pricing Analysis
Subscription-based monthly billing locks in tenant retention and price visibility for Seoul operators targeting gig-economy workers with irregular inventory cycles. This contract structure insulates revenue streams from seasonal vacancy swings while anchoring supply planning for facility developers navigating steel input cost volatility.
Pricing Analysis
Long-term subscription contracts dominate Seoul's residential segment, with annual prepaid leases retreating among millennial tenants. Price differentiation hinges on climate-control certification tier and unit proximity to transit nodes, with humidity-regulated units in Busan commanding premiums over standard formats. Pricing pressure stems from galvanized steel cost swings compressing development yields on new facilities. Students in university districts like Sinchon exhibit highest price sensitivity, while corporate document archivists with MFDS compliance requirements show lowest sensitivity.
Supply Chain Analysis
Inbound logistics costs from Busan Port congestion and container availability fluctuations on the China-Korea trade lane shape modular unit fabrication economics. Steel supply concentrates in China, South Korea, and Japan, with galvanized sheet metal and HVAC climate-control systems as critical component inputs. Single-source vulnerability in specialized humidity-regulation equipment creates permitting timeline risk for pharmaceutical-grade facilities. Distribution runs through direct facility contracts and mobile container delivery networks serving vehicle-scarce Seoul districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from mobile storage platforms decomposing the fixed-facility model through door-to-door container delivery, requiring defensive repositioning around mixed-use zoning access and climate-control certification.
For Market Incumbents: Fortify mixed-use development partnerships in Seoul's Gangnam and Yeongdeungpo districts to secure zoning-protected sites against mobile operator encroachment. Deepen climate-control certification investment to capture pharmaceutical and electronics merchant premiums that mobile platforms cannot replicate. Anchor tenant relationships through subscription billing infrastructure that matches gig-economy cash flow patterns. For New Entrants and Emerging Players: MFDS temperature-control certification fast-track positions operators to serve pharmaceutical sample storage demand with extended permitting timelines that deter rapid follower entry. Target Busan's underpenetrated port logistics corridor for first-mover warehouse positioning. Deploy RFID-integrated managed storage with cloud-based asset tracking to differentiate from legacy self-service incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors real estate-backed operators with mixed-use zoning access over pure technology plays. Long-term viability hinges on brownfield conversion capabilities in Seoul's land-scarce environment rather than greenfield expansion. Monitor municipal fire code deliberations on sprinkler retrofit mandates as the critical inflection signal for older asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Mixed-Use Zoning Integration | MFDS building code relaxations unlock retail-residential storage mezzanines in transit-rich Seoul districts. |
| Climate-Control Certification | KOSHA-compliant humidity regulation captures pharmaceutical and electronics merchant premium segments. |
| Mobile Storage Platform Launch | Door-to-door container delivery penetrates vehicle-scarce apartment districts at triple traditional rental rates. |
| Digital Inventory Convergence | RFID tracking and cloud-based asset management secure tech-forward commercial tenants in Busan logistics corridors. |
| Subscription Billing Infrastructure | Monthly pause-resume contracts align with gig-economy inventory cycles and improve millennial retention metrics. |
Research Methodology
Cross-validation between facility operator interviews and regulatory filing analysis anchors the qualitative findings on zoning and compliance evolution. Primary fieldwork encompassed self-storage facility operators, Ministry of Land officials, commercial real estate developers, and small-business tenant representatives. Secondary sources included MFDS pharmaceutical storage guidelines, KOSHA workplace safety standards, Seoul Metropolitan Government small-business support program documentation, and mixed-use development permit databases. Bottom-up unit economics modeling triangulates against top-down metropolitan demand projections.
Sensitivity analysis across steel price volatility scenarios and sprinkler mandate timing assumptions stress-tests facility development IRRs. Segmentation dimensions span storage type, customer archetype, unit size tier, and service model, with geographic granularity to Seoul sub-districts and Busan port zones. CAGRs derive from lease-up velocity curves calibrated against apartment size compression trends and remote-work equipment stockpile growth. Forecast inputs incorporate e-commerce merchant inventory cycle patterns and climate-controlled unit premium capture rates.
Underlying assumptions cover continued urban density intensification in Seoul and sustained e-commerce logistics demand, with deviation risk concentrated in steel input cost spikes and municipal fire code retroactivity rulings. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
US Property Management Software Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
Hungary Warehousing Sector Market
Property Management
Spain Warehousing Market
Property Management
Real Estate (Property) Management Market
Property Management
Property Management Software Market
Property Management
Europe Self Storage Market
Property Management
Real Estate Management Software Market
Property Management
United States Property Management Market
Property Management
Qatar Flexible Office Space Market
Property Management
Residential Property Management Market
Property Management
Property Management Service Market