
 Warehousing and Storage Services Market | 2026-2036
Warehousing and Storage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Warehousing and Storage Services Market Analytics
New industrial warehouse completions across the American Southeast is realigning national inventory distribution patterns. DHL Supply Chain leverages its automated fulfillment footprint to anchor pharmaceutical and e-commerce contracts. GXO Logistics specializes in robotics-integrated operations, while GEODIS competes through European rail-connected warehousing density.
Warehousing and storage services encompass the commercial receipt, handling, preservation, and dispatch of goods within dedicated facilities, typically operating across ambient, refrigerated, or automated environments with rack heights exceeding twelve meters and throughput measured in pallet positions per hour. These services enable inventory buffering, order consolidation, and last-mile staging for manufacturers, retailers, and logistics intermediaries. Public warehousing captures the broadest client base through multi-tenant flexibility, whereas automated storage commands premium pricing due to labor scarcity and throughput guarantees. Climate-controlled storage maintains structural growth from pharmaceutical and food safety compliance requirements.
OSHA warehouse safety standards, FDA pharmaceutical distribution regulations, and EPA refrigerant management rules collectively dictate facility design, worker training intensity, and cold-chain infrastructure investment across American operations. India's BIS warehousing standards and PLI scheme documentation requirements impose parallel compliance burdens on bonded facilities near manufacturing zones. Stakeholders must weigh automation capital cycles against evolving energy efficiency codes and cross-border customs integration timelines.
Market Dynamics
Pharmaceutical cold-chain logistics adoption is decentralizing fulfillment networks across third-party warehousing operators, forcing capital reallocation toward temperature-validated infrastructure and automated inventory systems that can meet FDA distribution regulations.
Growth Catalysts
- OSHA warehouse safety standards:Automation mandates under these rules are accelerating robotics deployment in American facilities, compressing labor dependency while raising throughput guarantees.
- India's PLI scheme:Manufacturing incentives near industrial corridors are generating bonded warehousing demand for raw material staging and finished goods distribution.
- Automated storage and retrieval systems:Labor scarcity across developed markets is pushing operators toward rack heights exceeding twelve meters with pallet-position-per-hour guarantees.
Market Restraints
- Steel and concrete input volatility:Warehouse construction costs fluctuate with commodity markets, squeezing development timelines for speculative build-to-suit projects.
- Refrigerant supply concentration:EPA refrigerant management rules constrain cold-chain infrastructure expansion where compliant coolant procurement faces geographic bottlenecks.
- Grid interconnection delays:Power-hungry automation systems face utility approval timelines that extend facility commissioning by quarters in dense logistics clusters.
Strategic Opportunities
- Indian bonded warehousing corridors:BIS warehousing standards compliance near manufacturing zones creates first-mover positioning for integrated logistics parks.
- Pharmaceutical serialization convergence:Track-and-trace technology integration with warehouse management systems opens premium service tiers.
- Rail-connected European density:GEODIS-style intermodal warehousing offers modal shift incentives under EU Green Deal freight targets.
Industry Challenges
- Warehouse management system integration:Legacy enterprise resource planning architectures resist real-time API connectivity with robotic material handling equipment.
- Cold-chain qualification timelines:FDA pharmaceutical distribution regulations demand extensive temperature-mapping studies that compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehousing and Storage Services Market |
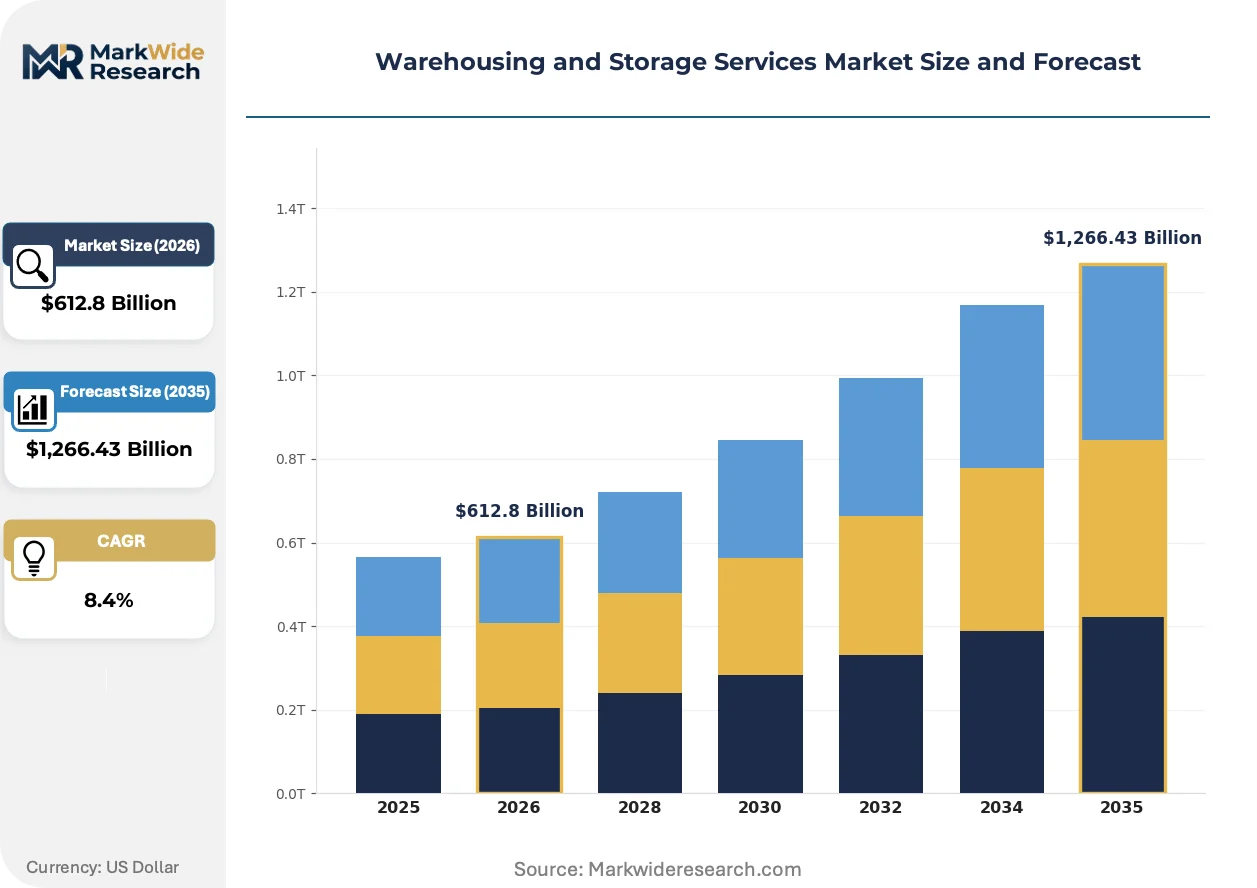
| Market Size in 2026 | $612.8 Billion |
| Market Size in 2035 | $1,266.43 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Warehousing, Private Warehousing, Co-Warehousing, Hybrid Warehousing Storage Type: Bulk Storage, Climate-Controlled Storage, Rack Storage, Automated Storage Industry Vertical: Retail, E-Commerce, Manufacturing, Logistics Technology: Warehouse Management Systems, RFID, IoT Solutions, Automation |
| Companies Covered | Kuehne + Nagel, Ryder Supply Chain Solutions, DHL Supply Chain, DB Schenker, UPS Supply Chain Solutions, GXO Logistics, CEVA Logistics, GEODIS, XPO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehousing and Storage Services Market Evolving Landscape
Automation architectures are fragmenting across modular robotics, edge-computing inventory systems, and predictive maintenance platforms that reshape how operators justify capital deployment cycles.
Autonomous mobile robots are decentralizing material flow patterns within fulfillment centers. Pharmaceutical and e-commerce operators are deploying these systems fastest, replacing fixed conveyor infrastructure with dynamic path optimization that compresses order cycle times and reduces rack-to-person travel distance.
REACH chemical safety regulations and EU F-Gas rules are tightening refrigerant specifications for climate-controlled facilities. Cold-chain operators face retrofit obligations or replacement timelines for existing mechanical systems, with pharmaceutical-grade warehouses bearing the steepest compliance costs and shortest implementation windows.
Service-level contracting is compressing toward throughput-guarantee structures with penalty clauses. Retail and healthcare buyers are displacing traditional space-rental agreements with performance-linked arrangements that shift operational risk to warehouse operators, with American Southeast distribution markets showing the fastest contract-structure rotation.
Warehousing and Storage Services Market Segmentation
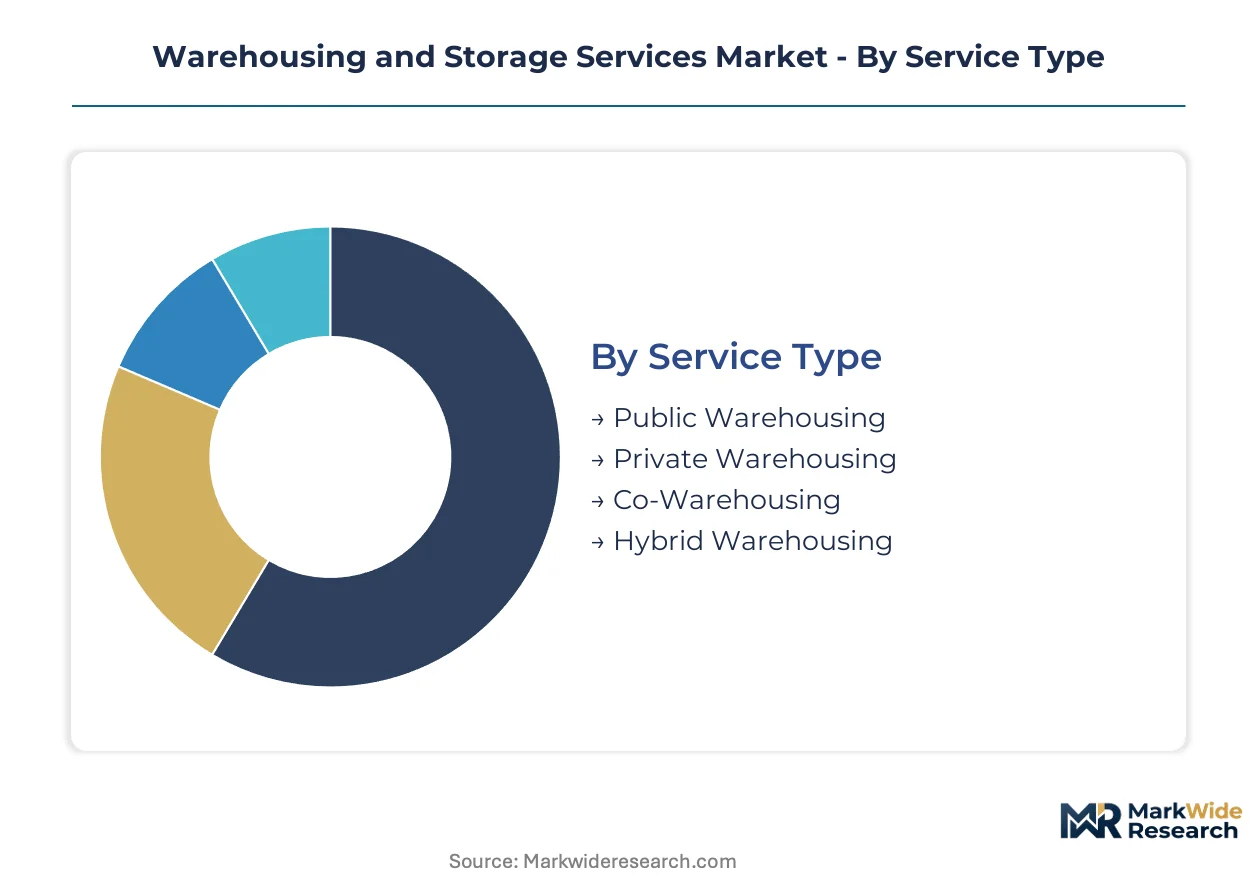
Warehousing and storage services fragment across operational models, infrastructure specifications, and technology integration levels. Each segmentation axis carries distinct capital intensity profiles and regulatory compliance burdens that reshape competitive positioning.
Service Type:
Technology and capital deployment intensity separate operational models across the ownership spectrum.
- Public Warehousing:Multi-tenant facilities offer flexible space allocation with shared labor pools and cross-dock capabilities. Pharmaceutical distributors and seasonal retailers concentrate demand here for FDA-compliant environments without fixed cost exposure.
- Private Warehousing:Captive facilities serve single-occupant requirements with dedicated automation architectures and customized rack configurations. E-commerce operators in the American Southeast are expanding private footprints to control last-mile staging.
- Co-Warehousing:Shared infrastructure with partitioned operational zones reduces per-unit occupancy costs for mid-scale manufacturers. India's PLI scheme beneficiaries near industrial corridors favor this model for bonded raw material staging.
- Hybrid Warehousing:Blended public-private arrangements combine dedicated automation zones with surge capacity buffers. Food safety compliance requirements under FSSAI and FDA rules drive adoption for temperature-sensitive inventory.
Public warehousing leads on scale; hybrid warehousing leads on momentum.
Storage Type:
Physical infrastructure specifications determine throughput capacity and energy intensity profiles.
- Automated Storage:Rack-to-person systems with pallet-position-per-hour guarantees compress labor dependency. OSHA automation mandates are accelerating deployment across American facilities handling pharmaceutical serialization.
- Climate-Controlled Storage:Temperature-validated zones with continuous monitoring satisfy FDA pharmaceutical distribution and FSSAI food safety requirements. Cold-chain qualification timelines extend commissioning but command premium pricing.
- Rack Storage:Conventional racking above twelve meters maximizes cubic utilization in ambient environments. Labor scarcity across developed markets limits expansion velocity.
- Bulk Storage:Floor-stacked configurations for non-perishable commodities minimize infrastructure investment. Manufacturing raw material staging in Indian bonded corridors sustains demand.
Climate-controlled storage leads on margin expansion; automated storage leads on technology adoption velocity.
Industry Vertical:
End-use concentration patterns dictate facility location strategies and service-level requirements.
- E-Commerce:Same-day fulfillment networks demand urban-edge positioning with returns processing capabilities. Autonomous mobile robot deployment is climbing fastest here.
- Retail:Seasonal inventory buffering requires flexible contract structures with penalty-linked throughput guarantees. American Southeast distribution markets show fastest contract-structure rotation.
- Manufacturing:Just-in-time staging and bonded warehousing integration near production facilities. India's industrial corridor expansion is generating concentrated demand.
- Logistics:Intermodal handoff points with rail-connected density, particularly across European networks under EU Green Deal freight targets.
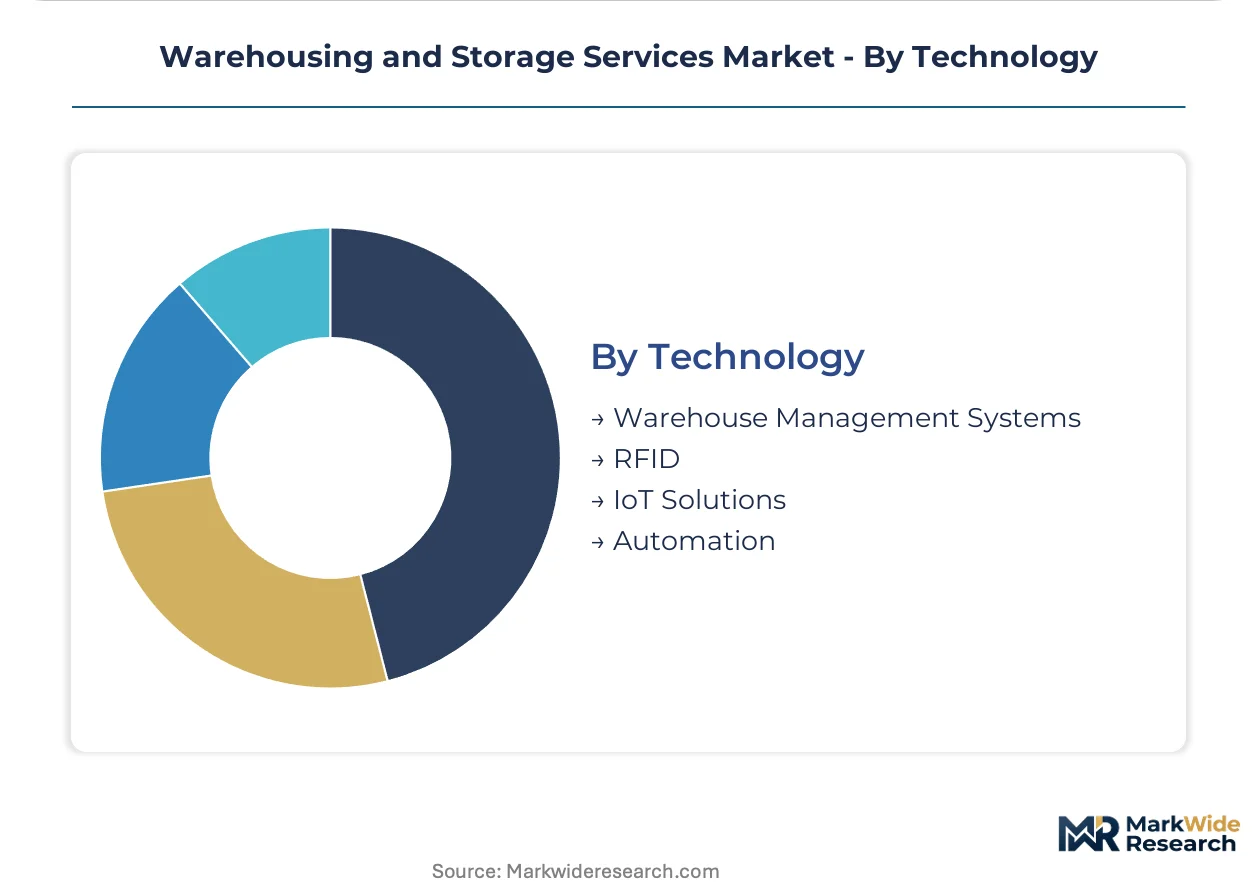
- Automation:Autonomous mobile robots and automated storage and retrieval systems with predictive maintenance platforms. Labor scarcity and OSHA safety mandates are forcing capital reallocation.
- Warehouse Management Systems:Core software orchestrating inventory tracking, labor allocation, and order fulfillment workflows. Legacy ERP integration resistance constrains deployment timelines.
- IoT Solutions:Sensor networks enabling predictive maintenance and energy optimization across climate-controlled zones. EPA refrigerant management rules drive environmental monitoring adoption.
- RFID:Item-level tracking for pharmaceutical serialization convergence with track-and-trace mandates. FDA distribution regulations require integration with warehouse management architectures.
E-commerce leads on automation intensity; manufacturing leads on geographic expansion momentum.
Technology:
Digital infrastructure layers determine real-time visibility and robotic integration depth.
Warehouse management systems lead on installed base; automation leads on investment growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting warehousing investment toward jurisdictions with streamlined customs integration and lower compliance friction. India's bonded corridor incentives and the United States' OSHA automation mandates are pulling capital in opposite directions—toward labor-intensive staging in South Asia and robotics-heavy fulfillment in North America.
United States
E-commerce same-day delivery networks and pharmaceutical cold-chain expansion are driving demand. OSHA warehouse safety standards mandate automation retrofits that compress labor dependency. The American Southeast—Georgia's Savannah corridor and South Carolina's Upstate region—is absorbing the fastest inventory redistribution as new industrial completions realign national distribution patterns.
Germany
Rail-connected intermodal density and REACH chemical safety compliance are shaping facility specifications. EU F-Gas rules tighten refrigerant specifications for climate-controlled warehouses. The Rhine-Ruhr corridor and Bavaria's Munich-Stuttgart axis concentrate pharmaceutical-grade automation investments as operators retrofit mechanical systems under shortened implementation windows.
India
PLI scheme manufacturing incentives are generating bonded warehousing demand for raw material staging and finished goods distribution. BIS warehousing standards impose compliance burdens on facilities near industrial zones. The Delhi-Mumbai Industrial Corridor and Gujarat's Sanand-Vithalapur belt are capturing concentrated logistics park development as manufacturing incentives accelerate.
China
Dual carbon goals and NMPA pharmaceutical distribution standards are reshaping cold-chain infrastructure investment. GB standards for automated facilities drive rack-height specifications above twelve meters. The Yangtze River Delta—Shanghai's Lingang New Area and Suzhou's industrial clusters—anchors robotics-integrated fulfillment expansion for domestic e-commerce networks.
Netherlands
Rotterdam's port-centric logistics density and EU Green Deal freight targets favor modal shift incentives. CSRD reporting requirements extend to warehouse energy intensity disclosures. The Randstad corridor—Amsterdam-Schiphol and the Venlo logistics cluster—concentrates pharmaceutical serialization convergence with track-and-trace technology integration.
Warehousing and Storage Services Market Competitive Landscape
Established logistics providers occupy the standard tier through integrated networks and long-term contracts; emerging entrants pursue niche automation specialization and regional corridor dominance. The market structures around three tiers: global integrated operators with multimodal density, regional specialists with robotics-integrated operations, and asset-light platform players aggregating warehouse capacity. Competitive moves concentrate on M&A for corridor positioning and strategic partnerships for technology licensing.
Within the global integrated tier, DHL Supply Chain and GEODIS exemplify divergent geographic anchoring strategies—DHL leveraging automated fulfillment footprints across pharmaceutical and e-commerce verticals, GEODIS competing through European rail-connected warehousing density. GXO Logistics occupies a position representing robotics-integrated operations specialization, with automation architectures that compress labor dependency in developed markets. These three operators collectively illustrate how capital deployment splits between automation intensity and intermodal connectivity.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Ryder Supply Chain Solutions |
| DHL Supply Chain |
| DB Schenker |
| UPS Supply Chain Solutions |
| GXO Logistics |
| CEVA Logistics |
| GEODIS |
| XPO Logistics |
| Others |
Value Network & Pricing Analysis
Captive automation architectures in American Southeast fulfillment centers anchor both supply positioning and pricing power, as OSHA-mandated robotics retrofits compress labor dependency while locking in throughput-guaranteed contract premiums for pharmaceutical and e-commerce operators.
Pricing Analysis
Distributor margins compress under contract-based long-term offtake structures that displace traditional space-rental agreements. Three-tier pricing structure across premium, standard, and economy levels separates climate-validated pharmaceutical storage from ambient rack configurations and bulk floor-stacked commodity handling. Cost compression in standard-tier ambient warehousing intensifies because speculative build-to-suit development faces steel and concrete input volatility. Seasonal retailers exhibit highest price sensitivity; pharmaceutical distributors with FDA serialization mandates show least.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme reshape sourcing toward bonded warehousing corridors near Delhi-Mumbai Industrial Corridor manufacturing zones. Steel fabrication draws from China and India; refrigerant procurement rests on concentrated supply from China and the United States; automation hardware feeds from Germany and Japan. Single-source vulnerability in compliant coolant procurement creates geographic bottlenecks for EPA-regulated cold-chain expansion. Distribution runs through third-party logistics operators with integrated rail and port connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
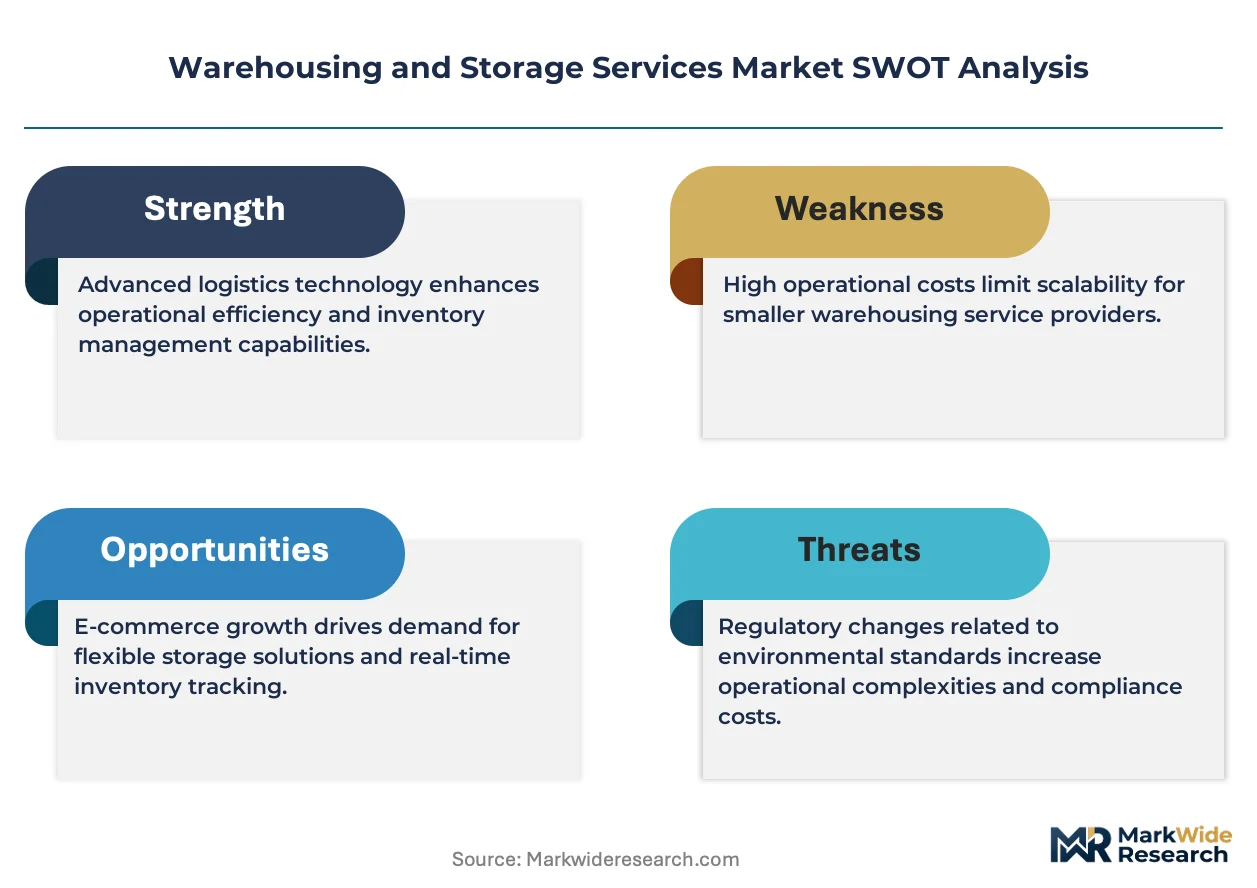
Margin expansion in warehousing and storage services hinges on automation capital cycles compressing labor costs while climate-controlled pharmaceutical tiers command premium throughput guarantees.
For Market Incumbents: Acquire automated storage and retrieval system footprints in American Southeast corridors to consolidate pharmaceutical and e-commerce contract positions. Defend against emerging robotics specialists by embedding predictive maintenance platforms that lock in multi-year service-level agreements with penalty-linked performance structures. For New Entrants and Emerging Players: Enter via Indian bonded warehousing corridors near Gujarat's Sanand-Vithalapur belt, where PLI scheme manufacturing incentives generate underpenetrated demand for raw material staging facilities. Target co-warehousing configurations for mid-scale manufacturers seeking partitioned operational zones without captive infrastructure investment. Pursue BIS compliance certification as primary go-to-market credential. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional operators lack automation capital to meet OSHA safety mandates and FDA pharmaceutical distribution regulations. Long-term viability favors asset-heavy platforms with rail-connected density and temperature-validated infrastructure. Watch for inflection where autonomous mobile robot deployment costs cross below fixed conveyor retrofit economics in American urban-edge fulfillment networks.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Retrofit Program | OSHA compliance mandates accelerate robotics deployment across American Southeast facilities. |
| Pharmaceutical Cold-Chain Expansion | FDA distribution regulations force capital reallocation toward temperature-validated infrastructure. |
| Indian Bonded Corridor Development | PLI scheme incentives concentrate logistics park investment near industrial manufacturing zones. |
| Rail-Connected Intermodal Density | EU Green Deal freight targets favor modal shift incentives for European warehousing networks. |
| Predictive Maintenance Platform Integration | Edge-computing inventory systems compress downtime guarantees for throughput-linked contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with warehouse operations directors, automation procurement leads, pharmaceutical supply chain managers, and third-party logistics contract specialists with secondary validation against SEC 10-K filings, customs and trade data, OSHA enforcement records, and FDA pharmaceutical distribution guidance documents. Bottom-up facility capacity modeling and top-down national inventory redistribution patterns were triangulated against regional construction permit data.
Historical reference periods spanning pre-automation and post-OSHA mandate implementation anchored the forecast window across the analysis window. Segmentation dimensions modeled include service type, storage infrastructure specification, industry vertical concentration, and technology integration depth. CAGRs were derived from facility commissioning timelines, automation capital cycle patterns, and contract-structure rotation velocity in American Southeast distribution markets. Cold-chain qualification timelines and grid interconnection approval durations served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement intensity and commodity input cost corridors; deviation in EPA refrigerant supply restrictions or India's PLI scheme incentive continuity would shift capacity deployment trajectories. Forecasts reflect documented assumptions regarding labor scarcity persistence and e-commerce same-day fulfillment network expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
US Home Service Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
United States Self Storage Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Singapore Customs Brokerage Market