
 Switzerland Data Center Server Market | 2026-2036
Switzerland Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Data Center Server Market Insights
Aftermarket service revenue is narrowing toward firmware management and predictive maintenance contracts as server refresh cycles compress. Dell Inc sustains its position through direct supply chain control across Alpine logistics corridors. Huawei Technologies Co Ltd competes on AI-accelerated rack architectures tailored to European latency requirements. Hewlett Packard Enterprise differentiates through liquid-cooled infrastructure partnerships with Swiss research institutes.
Switzerland data center servers are enterprise-grade computing systems engineered to operate within 18°C to 27°C ambient ranges, typically housing Intel Xeon or AMD EPYC processors with DDR5 memory subsystems and redundant power supplies for continuous uptime in commercial and institutional environments. Rack servers dominate procurement volumes among Zurich-based financial institutions requiring standardized 42U cabinet densities for trading floor co-location. Edge Computing deployments are accelerating fastest among telecommunications operators building low-latency nodes for Alpine corridor connectivity. Blade server configurations retain their position in government data centers where space constraints and centralized management outweigh per-unit cost premiums.
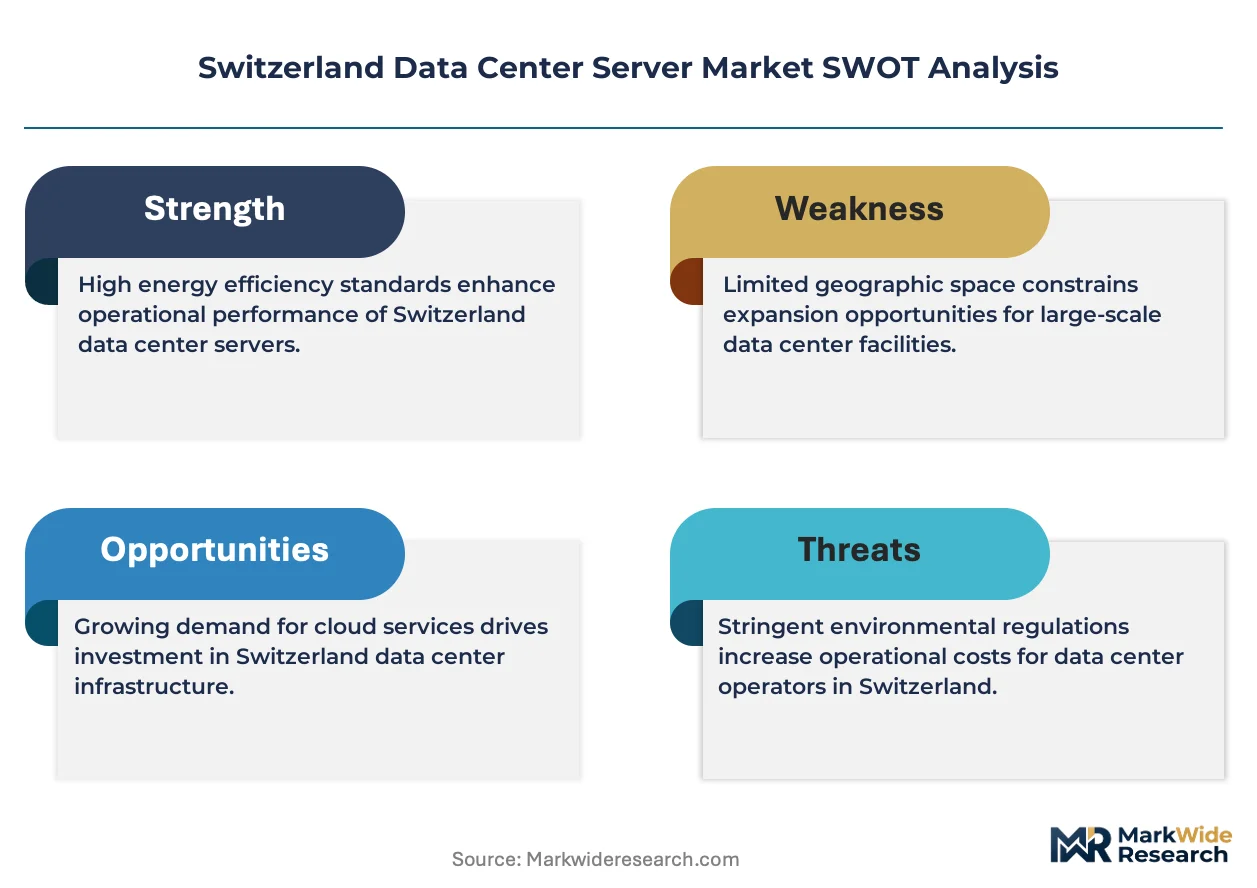
Swissmedic and the Federal Office of Communications (OFCOM) enforce data integrity standards that shape server procurement for healthcare and critical infrastructure operators, while FINMA guidelines on operational resilience mandate redundant hardware architectures for systemically important financial institutions. The Federal Act on Data Protection and its implementing ordinances require domestic data processing capabilities that favor locally deployed server capacity over cross-border cloud substitution. Stakeholders must weigh the trade-off between Geneva's tax-advantaged co-location zones and Zurich's denser fiber interconnection ecosystem when planning capacity additions.
Market Dynamics
The Federal Act on Data Protection revision is compressing server procurement timelines as financial institutions race to establish domestic processing capacity before compliance deadlines tighten cross-border data flows.
Growth Catalysts
- FINMA operational resilience mandates:Systemically important banks must maintain redundant hardware architectures, driving rack server refreshes across Zurich's trading floors.
- Hyperscale deployment by banking and insurance sectors:Swiss financial institutions are expanding private cloud infrastructure to retain data sovereignty under tightened federal guidelines.
- Geneva cloud corridor emergence:Tax-advantaged co-location zones are attracting sovereign wealth funds and commodity trading houses seeking latency-optimized compute.
Market Restraints
- Alpine logistics cost premiums:Server component transit through mountain corridors adds 8-12% landed cost versus flatland European routes.
- DDR5 memory supply concentration:Three Asian suppliers control 90% of high-bandwidth module production, creating input vulnerability.
- Swissmedic data integrity enforcement:Healthcare server procurement requires extended validation cycles that delay revenue recognition for vendors.
Strategic Opportunities
- Edge node deployment in Alpine corridors:Telecommunications operators are building low-latency infrastructure for cross-border connectivity between Switzerland and northern Italy.
- Liquid-cooled infrastructure partnerships:Swiss Federal Institutes of Technology research collaborations create technology transfer pathways for next-generation thermal management.
- OFCOM spectrum allocation for 5G standalone:New radio frequency bands enable mobile edge computing deployments previously constrained by backhaul limitations.
Industry Challenges
- Specialized firmware engineering scarcity:Predictive maintenance contracts require talent pools concentrated in Basel and Lausanne that competitors actively poach.
- Legacy mainframe integration complexity:Core banking systems running on IBM Z architectures resist seamless migration to x86 rack environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Data Center Server Market |
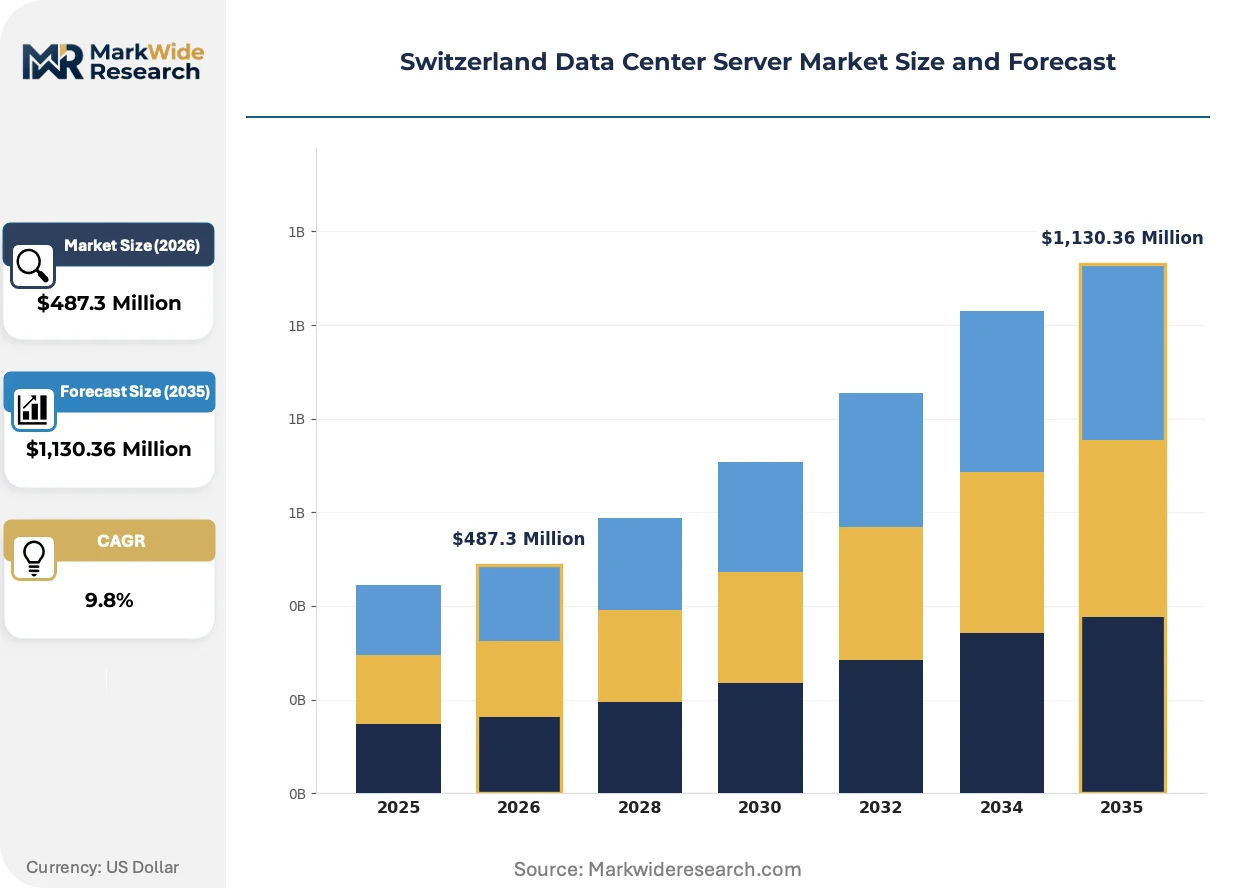
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,130.36 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Micro Servers End User: Telecommunications, Cloud Service Providers, Enterprises, Government Technology: Virtualization, Edge Computing, Artificial Intelligence, Blockchain Capacity: Standard Capacity, High Capacity, Ultra High Capacity, Others |
| Companies Covered | Dell Inc, International Business Machines (IBM) Corporation, Lenovo Group Limited, Cisco Systems Inc, Huawei Technologies Co Ltd, Inspur Group, Super Micro Computer Inc, Quanta Computer Inc, Hewlett Packard Enterprise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Data Center Server Market Trends and Innovations
Server architecture decisions in Switzerland are increasingly governed by thermal constraints and data sovereignty requirements rather than pure compute density optimization.
Direct liquid cooling is hybridizing traditional air-cooled rack designs with cold plate architectures that capture processor heat at the source. Swiss research institutes and commodity trading data centers are adopting these systems to sustain 40kW+ rack densities without expanding mechanical footprint. The technology is hybridizing procurement criteria as buyers now evaluate total cost of ownership across cooling energy, real estate, and carbon offset liabilities rather than capital expenditure alone.
The Federal Act on Data Protection implementing ordinances now require demonstrable domestic data processing capabilities for sensitive personal data categories. Financial institutions must maintain in-country server capacity that cannot be substituted with cross-border cloud instances without explicit regulatory approval. Asset managers and private banks in Geneva are responding by contracting dedicated bare-metal deployments rather than shared multi-tenant infrastructure.
Buying committees are consolidating vendor relationships around firmware lifecycle management capabilities rather than hardware specifications alone. Zurich-based financial institutions now require ten-year firmware update guarantees as a condition of rack server procurement, displacing transactional purchasing patterns. This concentration is most visible among cantonal banks and insurance mutuals that lack internal silicon engineering teams to manage supply chain discontinuation risks.
Switzerland Data Center Server Market Segmentation
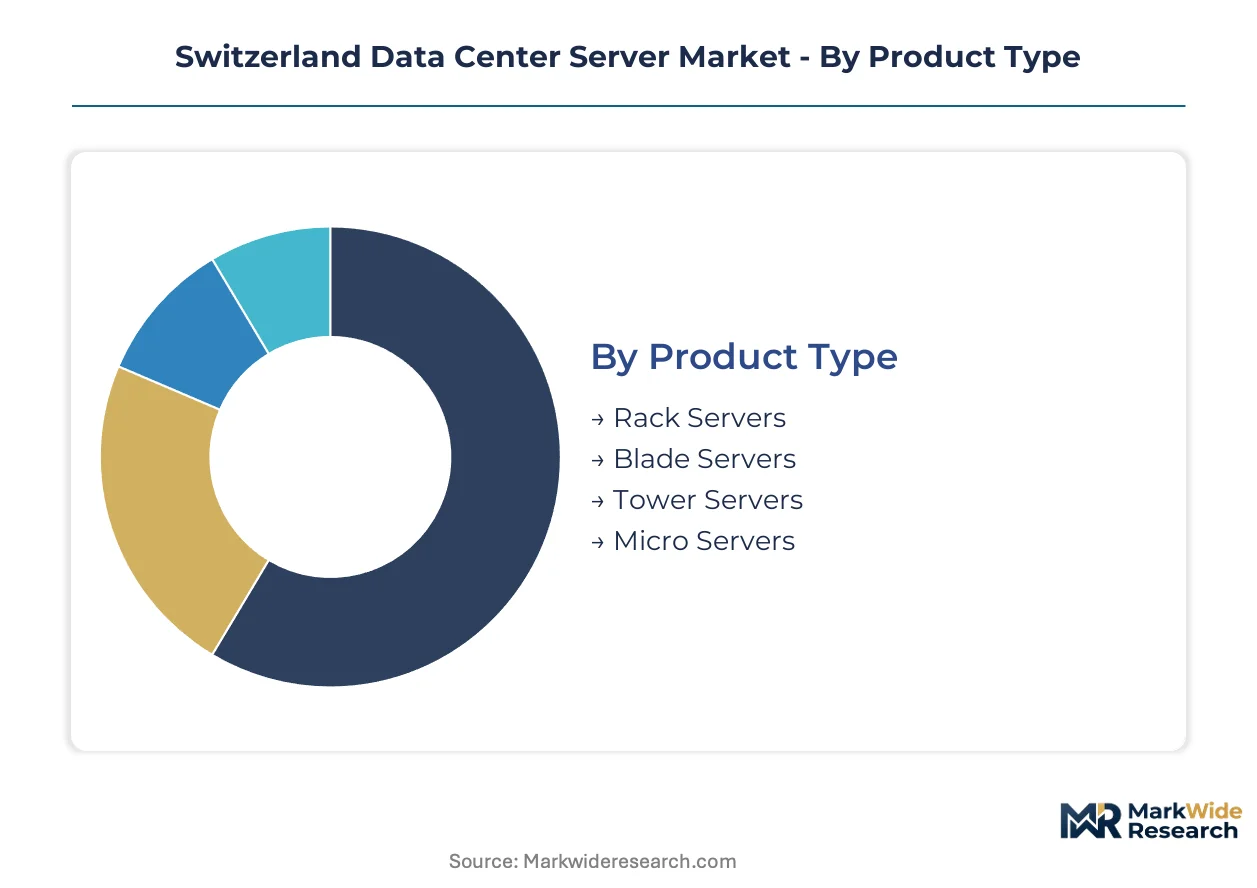
Switzerland's data center server market fragments along four dimensions that reflect competing priorities between legacy banking infrastructure and emerging sovereign cloud requirements. Procurement committees weigh thermal density against data residency mandates when selecting across these categories.
Product Type:
The maturity spectrum spans from standardized rack configurations dominating financial district deployments to emerging micro server architectures targeting Alpine edge nodes.
- Rack Servers:Standardized 42U cabinet densities house Intel Xeon or AMD EPYC processors with DDR5 memory subsystems. Zurich-based trading floors and Geneva commodity houses concentrate procurement here for co-location standardization under FINMA operational resilience mandates.
- Blade Servers:High-density chassis configurations enable centralized management through single console architectures. Swiss government data centers in Bern and Lausanne favor these for space-constrained facilities where administrative overhead reduction outweighs per-unit cost premiums.
- Tower Servers:Standalone pedestal configurations serve cantonal administration offices and regional healthcare providers with modest compute requirements. Swissmedic validation cycles extend procurement timelines for these deployments.
- Micro Servers:Compact single-board systems are emerging for telecommunications edge nodes across Alpine corridor connectivity projects. OFCOM spectrum allocations for 5G standalone backhaul are accelerating pilot deployments.
Rack servers handle the majority of throughput; micro servers are climbing the fastest on share.
End User:
Customer type segmentation reveals a cost tier stratification between systemically regulated financial institutions and emerging sovereign wealth operators.
- Telecommunications:Swisscom, Sunrise, and Salt Mobile are deploying low-latency infrastructure for cross-border Alpine connectivity. Edge node investments concentrate around St. Gotthard and Simplon transit corridors where latency arbitrage opportunities exist.
- Cloud Service Providers:Hyperscale operators are establishing Geneva co-location zones to serve commodity trading houses and private banking clients. Tax-advantaged structures attract bare-metal deployments that satisfy Federal Act on Data Protection domestic processing requirements.
- Enterprises:Pharmaceutical headquarters in Basel and precision manufacturing clusters in Zug drive private cloud refreshes. Extended firmware lifecycle guarantees are becoming standard procurement conditions.
- Government:Federal administration and cantonal authorities maintain redundant architectures for critical infrastructure. Swissmedic and OFCOM data integrity standards shape validation protocols for healthcare and communications operators.
Enterprises represent the largest installed base; cloud service providers are expanding most quickly.
Technology:
Application focus differentiates segments between infrastructure abstraction layers and specialized compute workloads.
- Virtualization:Hypervisor-based resource pooling remains the dominant deployment model for Zurich financial institutions consolidating legacy x86 estates. VMware and KVM architectures predominate in trading floor environments.
- Edge Computing:Distributed processing nodes are proliferating along Alpine transit corridors and within Geneva's emerging cloud zones. Latency-sensitive trading algorithms and 5G network functions drive hardware specifications.
- Artificial Intelligence:GPU-accelerated rack configurations are penetrating Swiss Federal Institutes of Technology research partnerships and commodity trading risk analytics. Liquid-cooled infrastructure investments correlate with AI training cluster deployments.
- Blockchain:Validated ledger infrastructure serves digital asset custody operations and trade finance consortia. FINMA guidance on distributed ledger technology shapes hardware security module integration requirements.
Virtualization retains the dominant deployment share; artificial intelligence is gaining share fastest.
Capacity:
Volume tiering aligns with workload intensity gradients from administrative computing to high-frequency trading.
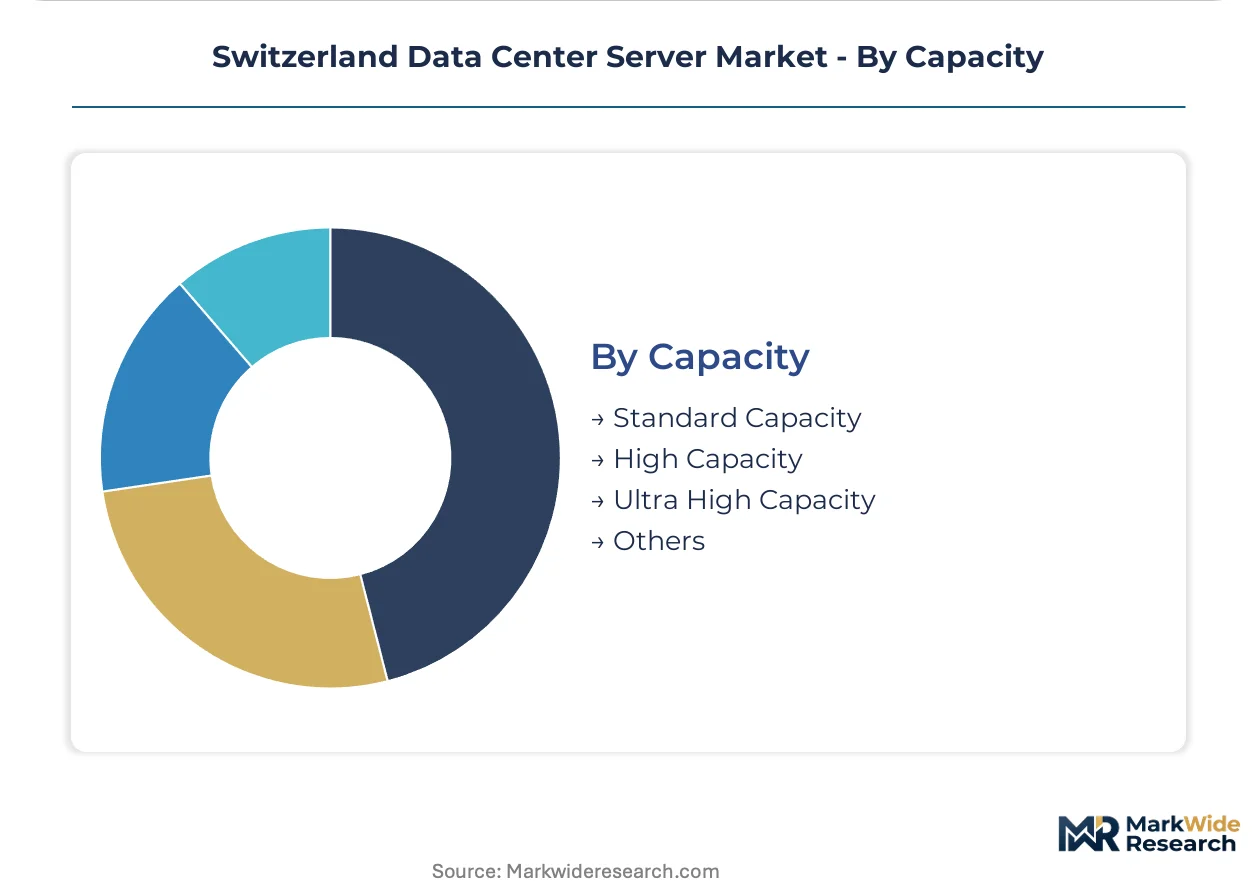
- Standard Capacity:Dual-socket configurations with 512GB to 2TB memory footprints serve cantonal administration and regional healthcare networks. Swissmedic validation requirements extend procurement cycles for these baseline deployments.
- High Capacity:Quad-socket and dense memory architectures support Zurich trading floor risk calculations and Basel pharmaceutical modeling workloads. DDR5 supply concentration creates input vulnerability for this tier.
- Ultra High Capacity:Liquid-cooled racks exceeding 40kW density accommodate AI training clusters and sovereign wealth fund quantitative analytics. Swiss Federal Institutes of Technology partnerships create technology transfer pathways for thermal management.
- Others:Specialized configurations including mainframe-adjacent appliances and legacy SPARC systems persist in core banking environments resisting x86 migration.
High capacity configurations generate the majority of revenue; ultra high capacity is expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland's data center server consumption patterns diverge sharply from neighboring economies, with financial sector sovereignty mandates driving domestic capacity builds rather than cross-border cloud arbitrage seen in Germany or France.
Zurich Financial District
FINMA operational resilience directives compel systemically important banks to maintain redundant rack server architectures within city limits. The Federal Act on Data Protection revision tightens processing location requirements for client transaction data. Trading floor co-location clusters concentrate along Hardbrücke corridor where fiber density supports sub-millisecond latency.
Geneva Cloud Corridor
Tax-advantaged co-location zones attract sovereign wealth funds and commodity trading houses seeking bare-metal deployments. OFCOM spectrum allocations for 5G standalone backhaul enable mobile edge computing pilots. Private banking data centers cluster near Cointrin airport logistics hub for transcontinental fiber access.
Basel Pharmaceutical Triangle
Swissmedic data integrity enforcement extends server validation cycles for healthcare operators. Precision manufacturing headquarters drive private cloud refreshes with ten-year firmware guarantees. Research institutes partner with thermal management specialists on liquid-cooled AI training clusters.
Lausanne-Bern Government Corridor
Federal administration and cantonal authorities prioritize blade server configurations for space-constrained facilities. OFCOM critical infrastructure standards shape procurement for telecommunications operators. Swiss Federal Institutes of Technology collaborations create technology transfer pathways for next-generation architectures.
Zug Crypto Valley
Distributed ledger infrastructure deployments concentrate around validated custody operations and trade finance consortia. FINMA guidance on digital assets shapes hardware security module integration requirements. Low-latency connectivity to Zurich and Geneva financial nodes drives edge node investments.
Switzerland Data Center Server Market Competitive Landscape
Capability concentration sits with specialized thermal management and firmware lifecycle vendors; scale advantage sits with diversified infrastructure conglomerates with Alpine logistics control. The vendor base stratifies across three tiers: direct supply chain operators with mountain corridor distribution networks, research partnership specialists leveraging Swiss Federal Institutes of Technology collaborations, and Asian-origin fabricators competing on AI-accelerated rack densities. Dominant competitive moves include liquid-cooled infrastructure joint ventures and extended firmware guarantee contracting.
Within the diversified infrastructure tier, Dell Inc and Hewlett Packard Enterprise occupy positions shaped by direct supply chain presence and research institute partnerships respectively. Huawei Technologies Co Ltd exemplifies the AI-accelerated specialization archetype, competing on latency-optimized architectures. These three anchors represent distinct strategic vectors: logistics-controlled distribution, technology transfer collaboration, and compute-density optimization.
| Leading Market Players |
|---|
| Dell Inc |
| International Business Machines (IBM) Corporation |
| Lenovo Group Limited |
| Cisco Systems Inc |
| Huawei Technologies Co Ltd |
| Inspur Group |
| Super Micro Computer Inc |
| Quanta Computer Inc |
| Hewlett Packard Enterprise |
| Others |
Pricing and Supply Chain Analysis
DDR5 memory supply concentration across South Korea, Taiwan, and China determines both pricing tier spreads and supply chain shape for Swiss data center server procurement. Three Asian suppliers control high-bandwidth module production, creating input vulnerability that compresses margins on ultra-high-capacity configurations while extending lead times for standard deployments.
Pricing Analysis
Long-term firmware management contracts dominate procurement patterns as Zurich-based financial institutions demand ten-year update guarantees. Pricing stratifies across liquid-cooled premium tiers, air-cooled standard configurations, and legacy tower economy segments. Cost compression in standard rack servers is intensifying because Alpine logistics premiums add landed cost versus flatland European routes. Cantonal administration offices exhibit highest price sensitivity; systemically important banks under FINMA mandates show lowest sensitivity to unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for Swiss server vendors. Component sourcing draws from Taiwan for advanced processors, South Korea for DDR5 memory modules, and China for power supply assemblies. Single-source vulnerability in high-bandwidth memory creates procurement chokepoints for AI-accelerated rack architectures. Distribution runs through Alpine corridor logistics networks controlled by direct supply chain operators with mountain transit expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance and firmware lifecycle contracts are expanding faster than hardware revenue, transforming server procurement into a service-attach opportunity. Recurring revenue layers now determine vendor profitability more than initial rack sales.
For Market Incumbents: Harden firmware engineering capabilities in Basel and Lausanne talent clusters against poaching by Asian competitors. Deepen liquid-cooled infrastructure partnerships with Swiss Federal Institutes of Technology to anchor thermal management differentiation. Capacity additions in Geneva's tax-advantaged co-location zones capture sovereign wealth fund demand before compliance deadlines tighten. For New Entrants and Emerging Players: Establish a beachhead in Alpine edge node deployments where telecommunications operators lack established vendor relationships. Micro server configurations for 5G standalone backhaul represent the most penetrable segment. A bare-metal sovereign cloud positioning bypasses hyperscale incumbents' shared infrastructure dominance. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors firmware-lifecycle specialists over pure hardware fabricators. Long-term viability hinges on ten-year service contract backlogs rather than refresh cycle spikes. Watch OFCOM spectrum allocation velocity as the inflection indicator for edge computing deployment scale.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooled Infrastructure Partnership | Swiss Federal Institutes of Technology collaborations transfer thermal management IP to commercial deployments. |
| Firmware Lifecycle Guarantee Extension | Ten-year update commitments displace transactional purchasing among cantonal banks lacking silicon engineering teams. |
| Alpine Logistics Network Control | Direct supply chain operators capture margin premiums from mountain corridor transit requirements. |
| Geneva Bare-Metal Sovereign Cloud | Tax-advantaged co-location zones attract commodity trading houses under Federal Act on Data Protection mandates. |
| Edge Node Micro Server Deployment | OFCOM 5G standalone allocations enable low-latency infrastructure along St. Gotthard and Simplon transit corridors. |
Research Methodology
Operator-level perspectives from data center procurement officers, IT infrastructure directors at systemically important banks, telecommunications network planners, and Swissmedic validation specialists anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of listed infrastructure vendors, hyperscaler capex disclosures, OFCOM spectrum allocation records, and FINMA operational resilience guidance documents. Bottom-up installation tracking and top-down market sizing triangulated volume estimates across the analysis window.
Scenario-bracketing around DDR5 supply disruption severity and Federal Act on Data Protection compliance timeline acceleration bounded forecast uncertainty. Segmentation modeling spanned product type, end user category, technology application, and capacity tier across the projection horizon. CAGRs derived from weighted average of historical replacement patterns and regulatory-driven compression effects. Alpine logistics cost premiums and firmware engineering talent scarcity served as industry-specific forecast inputs.
Stress conditions across memory supply concentration, cross-border data flow restrictions, and thermal density limits were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance deadline adherence and component availability continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Bengaluru Data Center Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
GCC Data Center Market