
 Nigeria Data Center Rack Market | 2026-2036
Nigeria Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Data Center Rack Market Insights
The capital-intensity divergence between hyperscale-grade fabricators and local assembly operators is unwinding competitive dynamics in Nigeria's data center rack supply base. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor premium rack deployments across Tier III facilities in Lagos. Rack Centre sustains operational credibility through direct control of its colocation real estate, while Africa Data Centres competes via pan-African footprint extension into Nigerian metro markets.
A data center rack is a standardized metal framework engineered to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310 specifications with load ratings between 1,500 and 3,000 pounds. Its primary purpose is to enable organized cable management, thermal airflow optimization, and physical security within controlled environment facilities. Enclosed rack configurations command margin premiums in Nigerian enterprise deployments where dust filtration and physical access control outweigh open-frame cost advantages. Steel material grades dominate procurement volumes due to local fabrication capacity and import tariff structures, though aluminum variants gain traction among cloud service providers prioritizing weight reduction for high-density layouts.
Nigeria's National Information Technology Development Agency sets data sovereignty and infrastructure localization benchmarks that directly influence rack specification requirements for government institution contracts. The Central Bank of Nigeria's cashless policy directives and payment system regulations amplify financial sector demand for certified equipment housing. BIS-equivalent standards enforcement through the Standards Organisation of Nigeria shapes import compliance pathways for foreign rack manufacturers. Stakeholders must monitor evolving power reliability standards and local content thresholds as determinants of procurement qualification and supplier selection criteria.
Market Dynamics
Power reliability deficits across Lagos, Abuja, and Port Harcourt are forcing rack specification upgrades toward integrated power distribution units and thermal containment systems, altering procurement criteria for both hyperscale deployments and enterprise edge facilities.
Growth Catalysts
- Data Localization Mandates:Nigeria's National Information Technology Development Agency guidelines require government data residency, compelling ministries and state agencies to expand on-premise rack capacity in certified Tier III facilities.
- Financial Sector Digitization:Central Bank of Nigeria cashless policy directives and payment system regulations drive bank procurement of enclosed rack configurations with enhanced physical access controls.
- Submarine Cable Landings:Lagos State infrastructure clustering around MainOne, Glo-1, and SAT-3 cable landing stations concentrates hyperscale demand for high-density aluminum rack variants.
Market Restraints
- Steel Input Volatility:Import tariff structures on cold-rolled steel grades and naira exchange rate instability compress margin predictability for local rack fabricators serving enterprise segments.
- Fabrication Concentration:Premium rack assembly capacity concentrates among three Lagos-based metalworking clusters, creating geographic supply vulnerability during port congestion or grid instability events.
- Certification Bottlenecks:Standards Organisation of Nigeria BIS-equivalent testing timelines extend equipment qualification periods, delaying foreign manufacturer market entry.
Strategic Opportunities
- Edge Computing Expansion:Kano, Ibadan, and Onitsha present underpenetrated secondary metro markets where distributed rack deployments can serve latency-sensitive manufacturing and logistics applications.
- Renewable Integration:Solar-hybrid power architectures create specification openings for racks with native DC power distribution and battery tray integration.
- Local Content Thresholds:Evolving domestic assembly percentage requirements under federal procurement rules advantage operators with captive metal fabrication capabilities.
Industry Challenges
- Certified Technician Scarcity:Rack installation and structured cabling competency gaps in northern Nigeria constrain deployment velocity for Abuja and Kano projects.
- Legacy Facility Retrofit Complexity:Enterprise data halls built for 2-4 kW per rack densities require structural reinforcement and cooling reconfiguration to accommodate 15-20 kW AI server loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Data Center Rack Market |
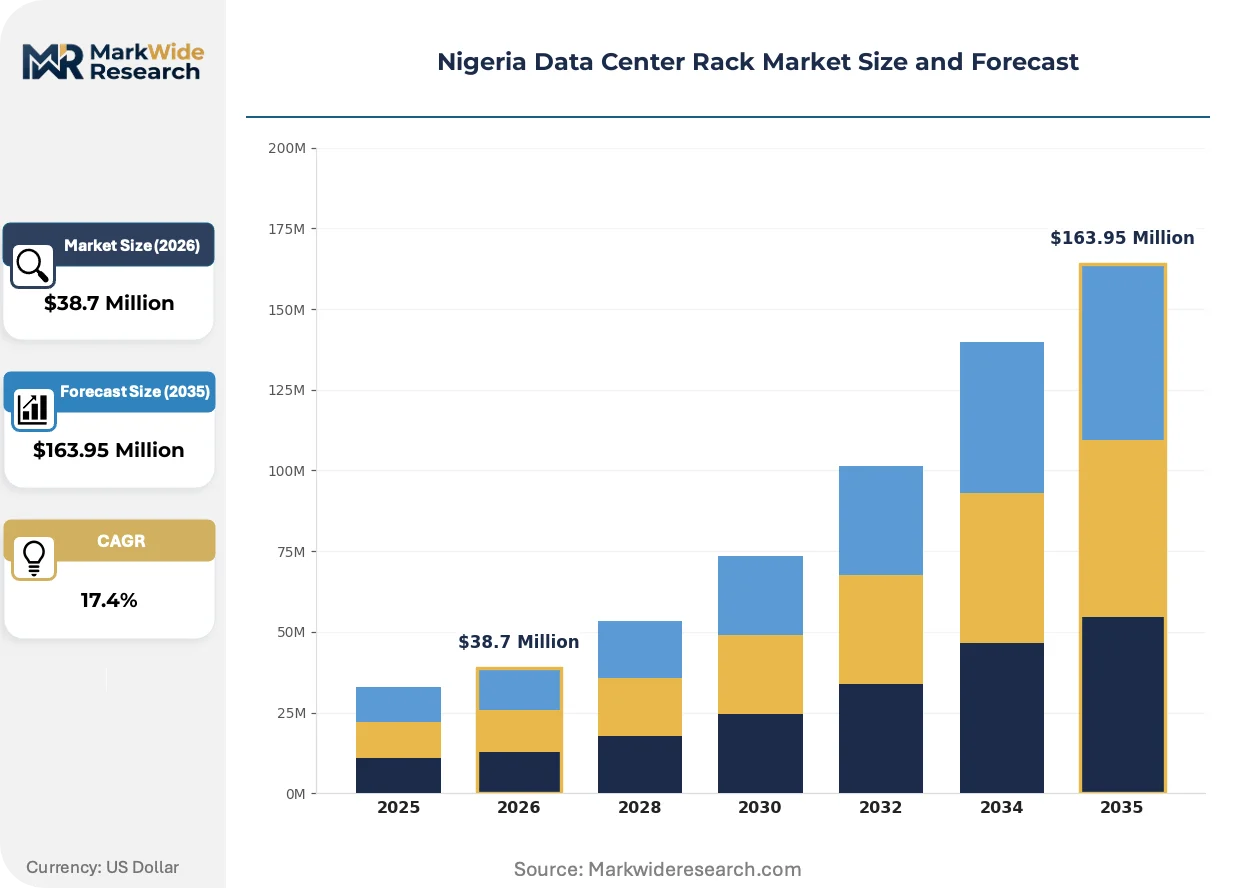
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $163.95 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Rack, Enclosed Rack, Wall-Mounted Rack, Custom Rack End User: Telecommunications, Cloud Service Providers, Enterprises, Government Institutions Material: Steel, Aluminum, Composite, Plastic Size: 1U, 2U, 4U, 6U |
| Companies Covered | Equinix (MainOne), Schneider Electric SE, Vertiv Group Corp., Eaton Corporation, Rittal GmbH & Co. KG, Rack Centre, Africa Data Centres, Dell Inc., nVent Electric PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Data Center Rack Market Trends and Innovations
Rack architecture is fragmenting into modular subsystems as Nigerian operators balance density ambitions against power constraints and skills shortages. Three developments are compressing traditional procurement patterns.
Liquid cooling distribution manifolds and rear-door heat exchangers are decomposing conventional perimeter cooling designs in Lagos hyperscale builds. Cloud service providers deploying NVIDIA H100 clusters are specifying these systems within twelve-month procurement cycles. The shift is compressing mechanical infrastructure vendor selection criteria toward thermal performance guarantees rather than rack frame commodity pricing.
Nigeria's National Information Technology Development Agency is tightening data sovereignty audit protocols for government cloud contracts. Ministries must now demonstrate physical rack segregation and access logging capabilities. Federal and state procurement panels are prioritizing enclosed cabinet configurations with biometric entry systems over open-frame alternatives.
Colocation buyers are unbundling rack-space contracts from cross-connect and remote hands services. Rack Centre and competing Lagos operators face margin pressure as enterprise procurement teams negotiate bare-metal leases and self-manage cabling. Financial services firms with internal engineering benches are driving this pattern most aggressively in Victoria Island and Ikoyi facilities.
Nigeria Data Center Rack Market Segmentation
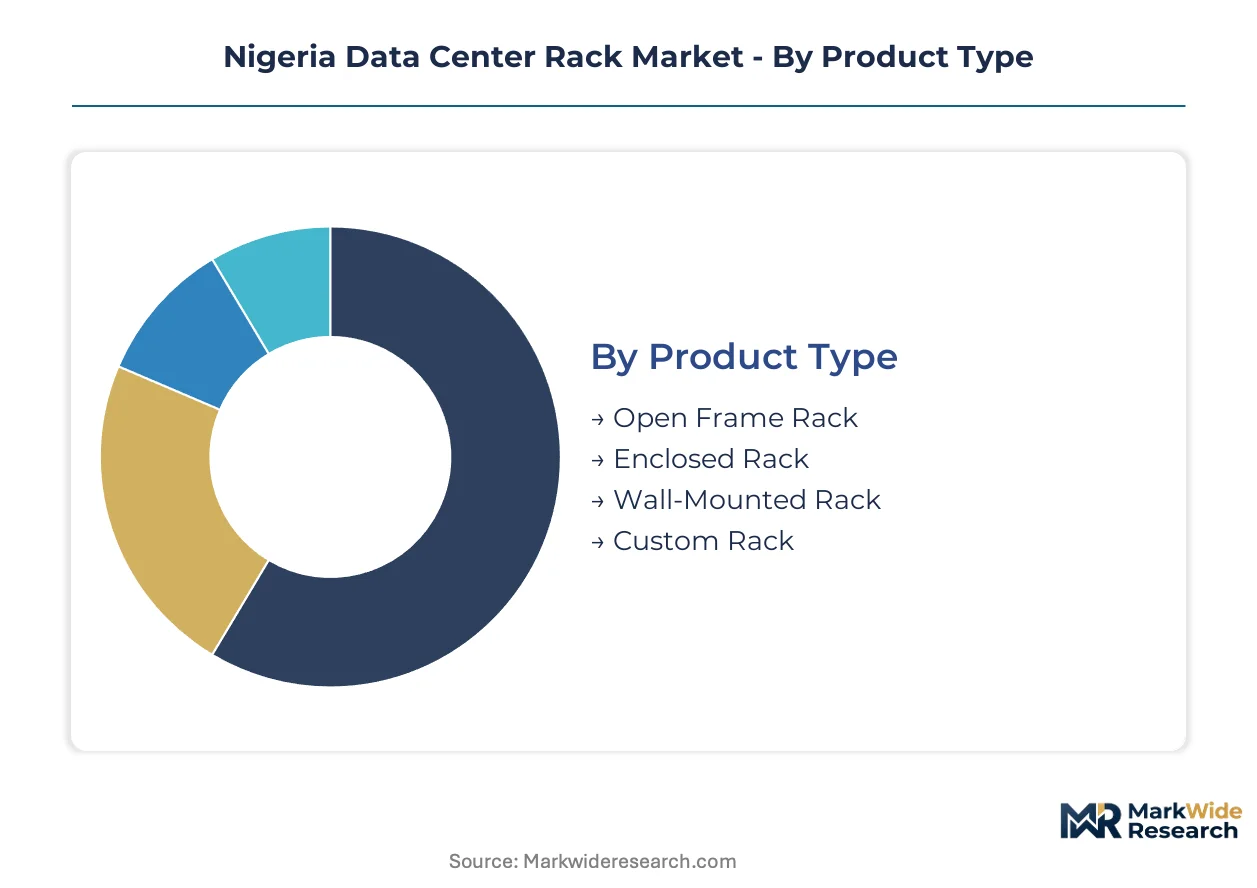
Segmentation in Nigeria's data center rack market reveals how procurement criteria diverge between hyperscale cloud operators prioritizing thermal density and government institutions emphasizing physical security compliance. Rack specification decisions cascade from material selection through enclosure architecture to mounting configuration, each tier carrying distinct margin implications for fabricators and distributors serving Lagos, Abuja, and emerging secondary metros.
Product Type:
Margin pools concentrate in enclosed rack configurations where dust filtration and biometric access controls command procurement premiums from financial and government buyers.
- Enclosed Rack:Sealed cabinet designs with integrated cable management and thermal containment dominate Tier III facility deployments. Lagos-based banks and Central Bank of Nigeria-regulated payment processors specify these units for physical access compliance. NITDA data sovereignty audits now mandate segregated rack logging capabilities.
- Open Frame Rack:Unenclosed four-post frameworks offer cost-optimized airflow for hyperscale operators managing high-density NVIDIA clusters. Cloud service providers in MainOne cable landing zones favor these for rapid deployment and maintenance access.
- Wall-Mounted Rack:Compact swing-out enclosures serve edge computing nodes in Kano and Ibadan manufacturing facilities.
- Custom Rack:Bespoke fabrication addresses non-standard floor loading and legacy facility dimensional constraints.
The dominant share belongs to Enclosed Rack, while Open Frame Rack is closing the gap fastest.
End User:
Application requirements shape specification divergence across buyer categories, with financial sector digitization and federal data localization mandates driving distinct procurement rhythms.
- Cloud Service Providers:Hyperscale operators deploying AI training infrastructure prioritize aluminum-framed high-density racks with liquid cooling manifold compatibility. MainOne, Glo-1, and SAT-3 cable landing proximity in Lagos concentrates their procurement volumes.
- Government Institutions:Federal ministries and state agencies require NITDA-certified enclosed configurations with biometric entry and audit logging. Data residency mandates compel on-premise capacity expansion across Abuja and state capitals.
- Telecommunications:Mobile network operators specify outdoor-hardened racks for base station aggregation points.
- Enterprises:Corporate data halls favor mid-density steel racks balancing capital constraints against 15-20 kW AI server power loads.
Cloud Service Providers capture the steepest expansion trajectory, though Government Institutions sustain the most predictable procurement pipelines.
Material:
Supply chain configuration and import tariff exposure differentiate margin stability across metal grades and alternative substrates.
- Steel:Cold-rolled carbon steel dominates procurement volumes due to local Lagos-based fabrication cluster capacity and established welding competencies. Naira exchange rate volatility and import tariff structures on higher-grade alloys compress margin predictability for fabricators.
- Aluminum:Lightweight extruded aluminum gains hyperscale share for high-density layouts where floor loading limits constrain steel deployments. Cloud operators in Victoria Island and Ikoyi facilities specify these for 20+ kW rack densities.
- Composite:Glass-reinforced polymer variants address corrosion resistance requirements in Port Harcourt coastal humidity.
- Plastic:ABS and polycarbonate housings serve low-load networking equipment in branch office edge deployments.
Steel retains volume leadership by a wide margin, while Aluminum is gaining share fastest among new hyperscale builds.
Size:
Mounting unit specifications track server form factor evolution and thermal load density trajectories across deployment scales.
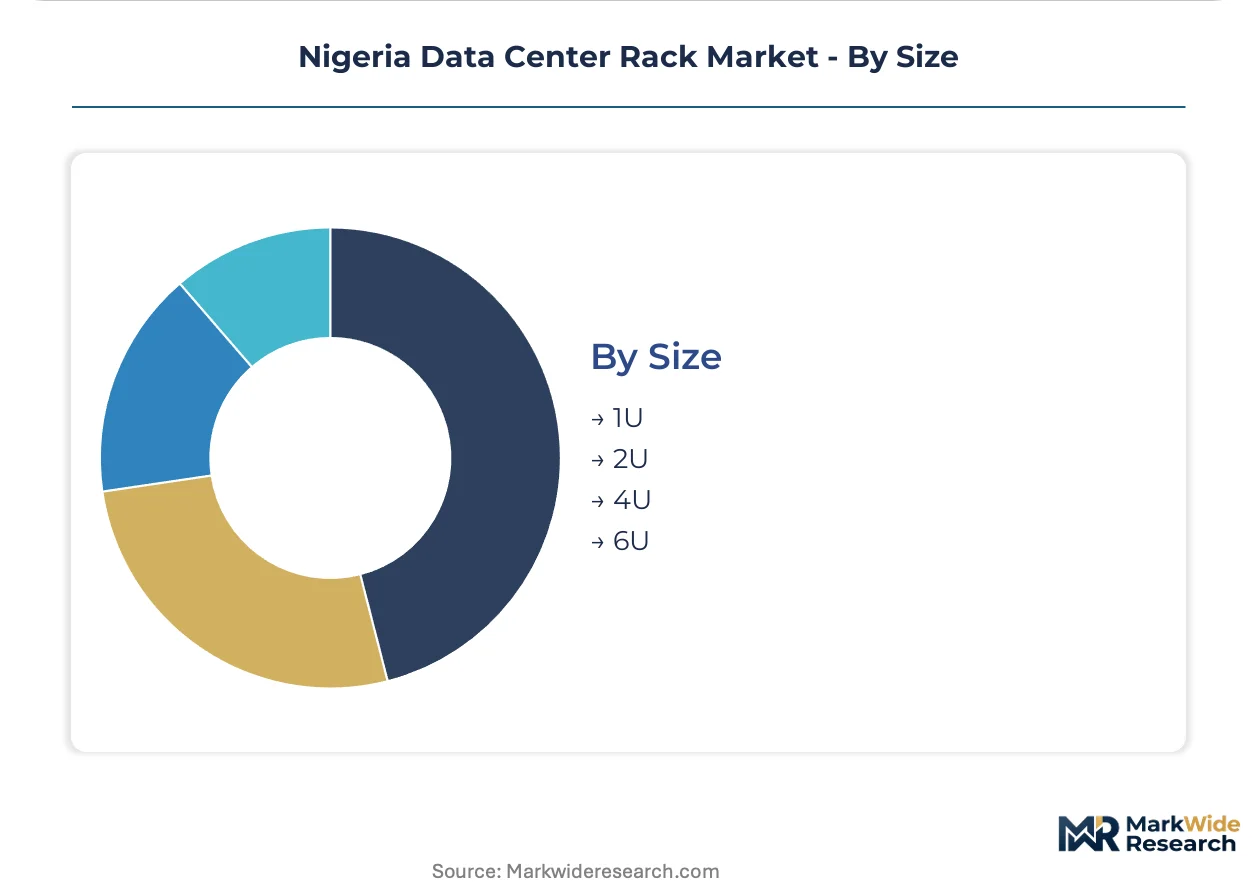
- 42U:Full-height cabinets accommodate standard server chassis and power distribution units in enterprise and colocation facilities. This configuration matches prevailing Lagos Tier III facility ceiling heights and aisle spacing standards.
- 48U:Extended-height variants serve hyperscale operators maximizing vertical space utilization before liquid cooling becomes mandatory. Cloud providers in Lekki Free Trade Zone deployments specify these for AI training clusters.
- 24U:Half-height units fit constrained floorplates in legacy enterprise retrofits.
- 12U:Compact enclosures address network equipment aggregation in distributed edge locations.
42U maintains the dominant installed base, while 48U is climbing the fastest among new hyperscale commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Lagos State, where submarine cable landings and hyperscale clustering create procurement premiums that secondary metros cannot replicate. Abuja commands institutional premiums through federal data localization mandates. Northern and eastern sub-regions face infrastructure deficits that compress rack specification budgets and extend deployment timelines.
Lagos State
MainOne, Glo-1, and SAT-3 cable landings concentrate cloud service provider demand in Victoria Island, Ikoyi, and Lekki Free Trade Zone corridors. National Information Technology Development Agency Tier III certification requirements shape procurement specifications for financial sector buyers. Rack Centre and competing colocation operators anchor high-density deployments across these districts, with liquid cooling manifold compatibility becoming standard for AI infrastructure.
Federal Capital Territory (Abuja)
Federal ministries and Central Bank of Nigeria-regulated institutions drive enclosed rack demand with biometric access and audit logging mandates. National Information Technology Development Agency data sovereignty protocols require physical segregation capabilities for government cloud contracts. Gwarinpa and Central Business District clusters host certified facilities serving diplomatic missions and regulatory bodies.
Kano State
Manufacturing and logistics enterprises generate distributed edge computing demand for latency-sensitive applications. Standards Organisation of Nigeria import compliance pathways extend equipment qualification timelines for northern deployments. Bompai and Sabon Gari industrial zones present underpenetrated opportunities for compact wall-mounted rack configurations.
Rivers State (Port Harcourt)
Oil and gas sector digitalization drives demand for corrosion-resistant composite rack variants in coastal humidity conditions. Onne and Trans Amadi industrial clusters require outdoor-hardened enclosures for base station aggregation points. Power reliability deficits force integrated power distribution unit specifications that Lagos buyers rarely need.
Oyo State (Ibadan)
Secondary metro status limits hyperscale presence but creates openings for mid-density steel rack deployments in enterprise data halls. University and research institutions generate specialized requirements for custom fabrication addressing legacy facility constraints. Ring Road and Moniya industrial corridors host emerging assembly capacity serving southwestern demand.
Nigeria Data Center Rack Market Competitive Landscape
Concentration sits with integrated electrical infrastructure multinationals and captive real estate operators. Premium rack deployments flow through vendors with power distribution and cooling portfolios. Local assembly clusters serve cost-constrained enterprise segments. Competitive moves center on pan-African footprint extension and thermal performance guarantee differentiation.
Within the integrated infrastructure tier, Schneider Electric SE anchors premium positioning through power and cooling portfolio bundling. Rack Centre exemplifies captive real estate control as a competitive moat. Africa Data Centres represents pan-African footprint extension into Nigerian metro markets. Among electrical component specialists, Eaton Corporation and nVent Electric PLC occupy positions in power distribution integration. Vertiv Group Corp. and Rittal GmbH & Co. KG sit within thermal containment and enclosure architecture segments.
| Leading Market Players |
|---|
| Equinix (MainOne) |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corporation |
| Rittal GmbH & Co. KG |
| Rack Centre |
| Africa Data Centres |
| Dell Inc. |
| nVent Electric PLC |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Lagos-based fabrication clusters lock in both steel supply access and price visibility for hyperscale operators committing to 48U aluminum rack deployments. These arrangements insulate cloud service providers from naira volatility while compressing margin predictability for local assemblers serving spot-market enterprise buyers.
Pricing Analysis
The customization-premium spread between configured-to-order enclosed racks and standard open-frame units runs wide in Nigerian procurement. Three-tier pricing structure across premium, standard, and economy levels tracks NITDA certification grade and biometric access integration. Cost compression in the standard tier is intensifying because local fabricators compete for bank procurement volume. Government institutions show least price sensitivity due to data sovereignty compliance mandates, while manufacturing enterprises in Kano and Ibadan drive hardest bargain on bare-metal configurations.
Supply Chain Analysis
Strategic stockpile preferences dominate among hyperscale operators buffering against Lagos port congestion, while just-in-time procurement persists for enterprise edge deployments with lower criticality. Cold-rolled steel supply concentrates in China, Turkey, and South Africa, with Nigerian fabricators drawing from Turkish mills to minimize tariff exposure. Aluminum extrusion feeds from Chinese and UAE sources. Single-source vulnerability sits with the three Lagos metalworking clusters controlling premium rack assembly. Distribution runs through direct OEM relationships for Tier III facilities and electrical wholesale channels for enterprise retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale cloud operators as their procurement volumes consolidate around MainOne and Lekki Free Trade Zone corridors. This concentration fragments pricing leverage for smaller enterprise buyers in secondary metros.
For Market Incumbents: Compound thermal performance differentiation through liquid cooling manifold integration to defend against emerging Chinese rack exporters penetrating Nigerian markets via lower-tier pricing. Prioritize captive metal fabrication capabilities to meet evolving local content thresholds in federal procurement rules. Certification investment with Standards Organisation of Nigeria creates switching costs for bank and government accounts. For New Entrants and Emerging Players: Differentiate on solar-hybrid rack specifications with native DC power distribution to capture renewable integration openings in Abuja and Port Harcourt where grid instability forces premium power architecture. Kano State presents the most penetrable geography given certified technician scarcity constraining incumbent deployment velocity. Target manufacturing logistics enterprises with compact wall-mounted configurations and bundled installation training. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation operators with captive real estate control and long-term bare-metal lease structures. Over the projection horizon, vertically integrated players with power distribution portfolios outperform pure-play fabricators. Acquisition target archetype: Lagos-based metalworking clusters with established welding competencies and NITDA certification pathways. Watch hyperscale capex commitment announcements to MainOne cable landing zones as inflection indicator for aluminum rack demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Local Fabrication Capacity Expansion | Captive Lagos metalworking clusters secure federal procurement qualification under evolving domestic assembly rules. |
| Liquid Cooling Manifold Integration | Thermal performance guarantees displace commodity rack pricing in NVIDIA H100 cluster deployments. |
| NITDA Certification Investment | Biometric access logging capabilities unlock government cloud contract eligibility for enclosed rack suppliers. |
| Pan-African Footprint Extension | Multi-country presence reduces Nigeria-specific currency and grid instability risk for hyperscale customers. |
| Solar-Hybrid Power Architecture Partnership | DC-native rack specifications capture renewable integration demand across Abuja and Port Harcourt markets. |
Research Methodology
Initial hypotheses were tested against primary input from data center operations directors, electrical infrastructure procurement managers, and Standards Organisation of Nigeria compliance officers and refined through secondary validation. Field engagement with colocation facility engineers, cloud service provider capacity planners, and Lagos-based metal fabrication cluster supervisors anchored supply-side assessment. Secondary sources included NITDA regulatory filings, Central Bank of Nigeria payment system directives, submarine cable landing station development records, and customs import data for cold-rolled steel grades. Bottom-up rack deployment counts triangulated against top-down facility capacity announcements.
Variance decomposition across product type, end user category, material grade, and regional deployment density shaped the analytical framework. Modeled segmentation captured enclosure architecture preferences, hyperscale versus enterprise procurement rhythms, steel versus aluminum specification splits, and metro-level demand concentration. CAGRs were derived from fitted growth curves against verified installation data. Forecast inputs included NITDA data sovereignty audit protocol expansion timelines and MainOne cable landing capacity augmentation disclosures.
Material uncertainties — naira exchange rate instability, Standards Organisation of Nigeria testing timeline extensions, and grid reliability deterioration beyond baseline assumptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about local content threshold evolution and hyperscale commitment patterns. Revision becomes warranted when federal procurement local assembly percentage requirements cross thresholds that invalidate incumbent competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market