
 Bengaluru Data Center Market | 2026-2036
Bengaluru Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Bengaluru Data Center Market Insights
Multi-source infrastructure procurement is recalibrating how enterprises contract capacity across Bengaluru's data center ecosystem. Nxtra Data Ltd leverages its parent organization's telecom backbone to sustain edge-node density across the city's periphery. STT GDC India anchors premium hyperscale deployments with direct utility tie-ins and liquid-cooling readiness. CtrlS Datacenters specializes in tier-IV certified facilities, occupying the ultra-resilient niche for banking and government workloads.
A data center constitutes a dedicated facility housing compute, storage, and networking infrastructure with controlled environments maintaining 18-27°C temperature bands and N+1 power redundancy for continuous operations. These facilities enable cloud service delivery, enterprise IT consolidation, and digital transaction processing at scale. Colocation and hyperscale deployments lead capacity absorption, with hyperscale capturing the dominant share of new megawatt additions as cloud providers expand India South availability zones. Edge infrastructure represents the fastest-growing structural segment, driven by latency-sensitive applications in autonomous systems and industrial IoT requiring sub-10 millisecond response times from Whitefield and Electronic City nodes.
BIS certification mandates for data center infrastructure, combined with CEA grid-connectivity standards and Karnataka state-level energy-efficiency directives, shape facility design and operational compliance requirements for all new builds. Karnataka's IT policy framework and single-window clearance mechanisms for digital infrastructure projects accelerate project timelines while embedding sustainability benchmarks. Stakeholders must monitor evolving state power allocation priorities and BIS amendments governing liquid-cooling discharge standards as facility densities climb past 50 kilowatts per rack.
Market Dynamics
Power procurement constraints and liquid-cooling infrastructure upgrades are compressing project timelines across Bengaluru's data center corridor, forcing operators to secure dedicated substations and cooling discharge permits before breaking ground on high-density builds.
Growth Catalysts
- BIS certification mandates:The Bureau of Indian Standards infrastructure guidelines tighten facility resilience requirements, pushing financial services firms toward certified colocation providers and accelerating premium capacity absorption.
- Karnataka single-window clearance:State-level digital infrastructure fast-tracking mechanisms shave months off permitting timelines, enabling faster time-to-revenue for hyperscale deployments in Whitefield and Electronic City.
- Edge latency requirements:Autonomous systems and industrial IoT applications demanding sub-10 millisecond response times are pulling compute capacity toward peripheral nodes with dense fiber backhaul.
Market Restraints
- Power allocation scarcity:Karnataka state electricity distribution priorities limit dedicated substation availability, forcing operators into competitive bidding for grid-connected megawatt blocks.
- Liquid-cooling discharge standards:BIS amendments governing thermal effluent management remain under draft status, creating permitting uncertainty for facilities exceeding 50 kilowatts per rack.
- Land cost concentration:Whitefield and Electronic City corridor premiums compress project IRRs, pushing smaller operators toward secondary locations with inferior fiber density.
Strategic Opportunities
- Tier-IV certification gap:Banking and government workloads seeking ultra-resilient infrastructure face limited certified supply, creating premium pricing power for operators achieving tier-IV status.
- Liquid-cooling convergence:Direct-to-chip thermal management combined with AI workload density requirements enables 30-40% space efficiency gains over traditional air-cooled designs.
- CEA grid-interconnection incentives:Central Electricity Authority standards for renewable-tied data center loads unlock priority dispatch for solar-wind hybrid powered facilities.
Industry Challenges
- Thermal engineering talent scarcity:Liquid-cooling system design and computational fluid dynamics expertise remains concentrated among hyperscale operators, constraining mid-tier facility upgrades.
- Legacy electrical infrastructure integration:Retrofitting existing facilities for 400V three-phase distribution and busbar trunking systems requires extended downtime windows that conflict with SLA commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bengaluru Data Center Market |
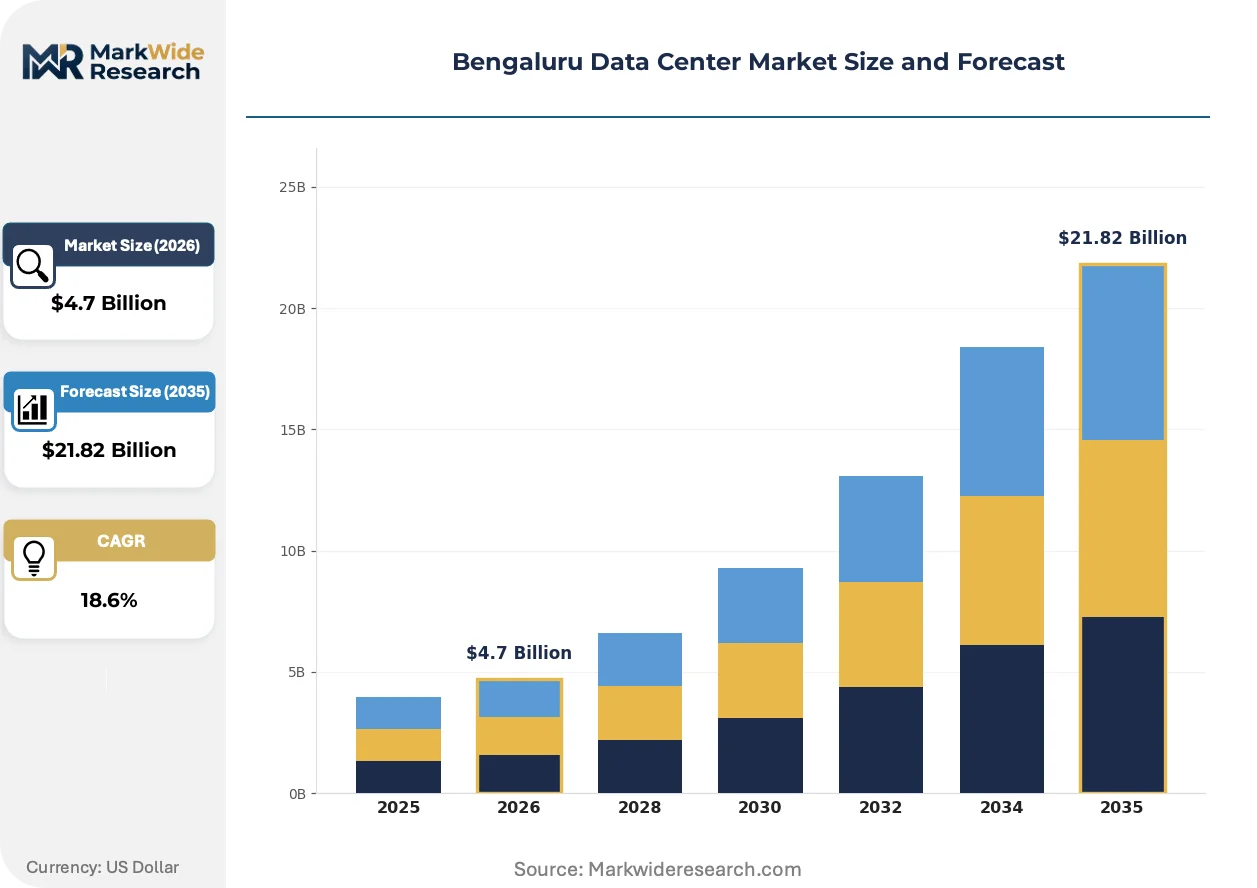
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Hyperscale, Edge, Managed Hosting End User: Telecommunications, IT Services, Government, Financial Services Solution: Infrastructure as a Service, Disaster Recovery, Backup Services, Network Security Deployment: On-Premise, Cloud, Hybrid, Multi-Cloud |
| Companies Covered | NTT Global Data Centers, Nxtra Data Ltd, STT GDC India, CtrlS Datacenters, Sify Technologies, Tata Communications, Reliance Data Centers, CapitaLand, L&T Cloudfiniti, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bengaluru Data Center Market Trends and Innovations
Direct liquid cooling architectures and AI-optimized workload placement are compressing facility design cycles while reshaping how operators contract power and thermal infrastructure across Karnataka's primary data center corridors.
Immersion cooling systems using dielectric fluids are overtaking conventional chilled-water designs in high-performance computing deployments. Hyperscale cloud providers and AI training clusters are adopting single-phase immersion at pace, with pilot installations operational in Electronic City. This thermal approach is overtaking legacy raised-floor air conditioning by enabling 100+ kilowatt rack densities without mechanical refrigeration energy penalties.
BIS infrastructure guidelines and CEA grid-connectivity standards are converging to mandate N+1 power redundancy and renewable energy disclosure for all new builds above 10 megawatts. The industrial consequence is a bifurcation between premium certified facilities and uncertified legacy stock. Banking and government verticals are responding by consolidating contracts with tier-III and tier-IV certified operators, leaving secondary facilities exposed to vacancy risk.
Capacity reservation contracts with take-or-pay structures are displacing traditional managed service agreements among enterprise buyers. Large financial services and e-commerce platforms are pre-committing to five-year blocks with annual escalation clauses, transferring demand risk onto operators. This pattern is most visible in Whitefield, where hyperscale pre-leasing activity has absorbed 18 months of forward supply before concrete pours complete.
Bengaluru Data Center Market Segmentation
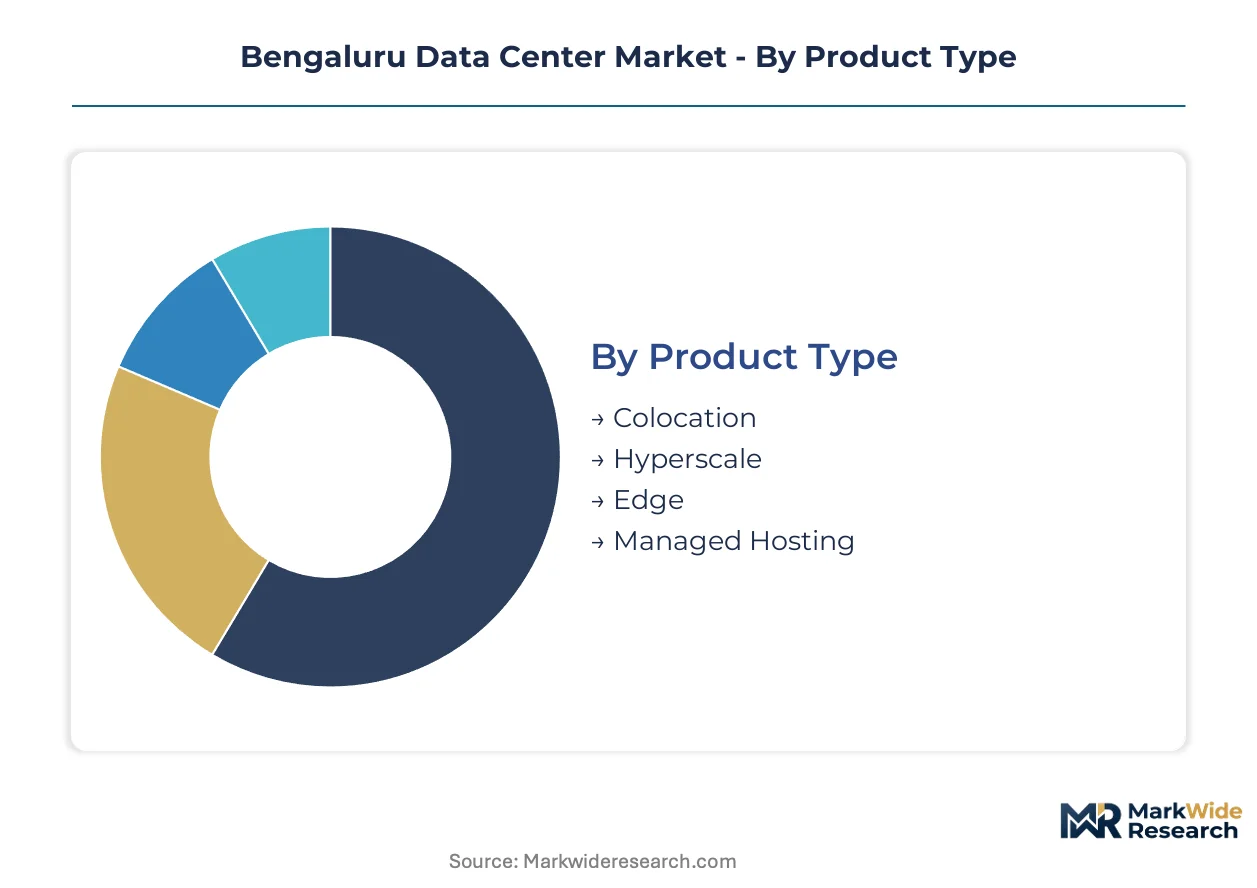
Segmentation in Bengaluru's data center market reveals how workload requirements, compliance mandates, and latency sensitivity drive facility selection across the city's Whitefield and Electronic City corridors. Understanding these divisions exposes where capacity constraints concentrate and which buyer profiles command premium pricing power.
Product Type:
Facility scale and operational control separate buyers seeking shared infrastructure from those demanding dedicated megawatt blocks with direct utility interconnects.
- Hyperscale:Dedicated facilities exceeding 10 megawatts with single-tenant designs, direct 132kV utility substations, and liquid-cooling readiness for AI training clusters. Cloud providers expanding India South availability zones absorb forward supply in Whitefield through five-year pre-leasing commitments with annual escalation clauses.
- Colocation:Multi-tenant environments offering rack-by-rack leasing with shared mechanical and electrical infrastructure. Financial services firms facing tightened BIS certification mandates are consolidating contracts with tier-III and tier-IV certified operators, leaving uncertified legacy stock exposed to vacancy risk.
- Edge:Distributed nodes under 1 megawatt positioned for sub-10 millisecond latency to autonomous systems and industrial IoT endpoints. Electronic City pilot installations operational for latency-sensitive manufacturing workloads.
- Managed Hosting:Operator-managed server deployments with bundled monitoring and maintenance services for mid-market enterprises lacking in-house infrastructure expertise.
Hyperscale leads volumes today; edge infrastructure is gaining share fastest.
End User:
Regulatory exposure and transaction density determine which verticals absorb premium-tier certified capacity versus commodity colocation.
- Financial Services:Banks, insurance carriers, and payment processors subject to RBI operational resilience guidelines and SEBI data localization mandates. Tier-IV certification requirements from BIS infrastructure guidelines push consolidation toward ultra-resilient facilities with N+1 power redundancy and 99.995% uptime SLAs.
- IT Services:System integrators and SaaS providers delivering cloud-enabled enterprise applications. Hybrid workload patterns spanning on-premise and multi-cloud architectures drive demand for cross-connect density and software-defined networking.
- Government:Central and state agencies implementing digital public infrastructure under MeitY data sovereignty requirements. Procurement prioritizes BIS-certified domestic facilities with dedicated security clearances.
- Telecommunications:Mobile network operators and internet service providers anchoring content delivery and 5G core network functions. Edge node co-location with radio access network infrastructure shapes site selection.
IT services dominates current absorption; financial services is expanding most quickly.
Solution:
Risk transfer mechanisms and operational responsibility allocation distinguish procurement patterns across managed service categories.
- Infrastructure as a Service:Compute and storage resources delivered on metered consumption models with API-driven provisioning. Enterprise buyers shifting from capital-intensive ownership to operational expenditure models.
- Disaster Recovery:Geographically separated failover environments with automated replication and sub-hour recovery point objectives. Karnataka state-level single-window clearance accelerates secondary site deployment timelines.
- Backup Services:Immutable data protection with air-gapped storage tiers meeting financial sector regulatory retention periods.
- Network Security:Distributed denial-of-service mitigation, web application firewalls, and zero-trust access controls delivered as managed security service edge functions.
Infrastructure as a Service commands the largest revenue pool; disaster recovery is climbing the fastest.
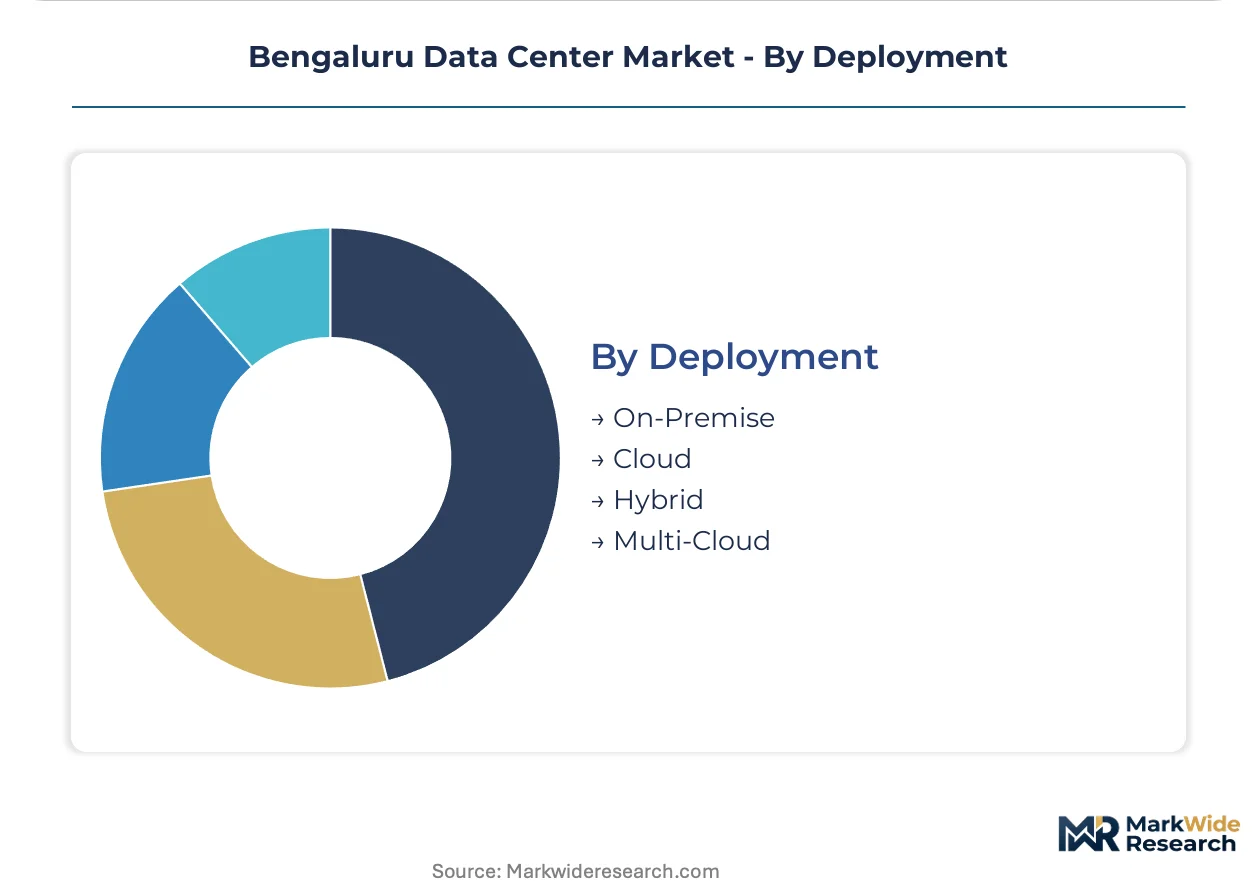
Deployment:
Control boundaries between owned infrastructure and third-party platforms define architectural decisions and contractual risk allocation.
- Cloud:Full third-party platform dependency with shared responsibility models for security and compliance. Hyperscale providers leverage India South availability zone expansion to capture enterprise workload migration.
- Hybrid:Orchestrated workloads spanning owned colocation and public cloud resources with consistent networking and identity management. Financial services firms retain sensitive transaction processing on certified premises while bursting analytics to cloud.
- On-Premise:Captive facilities with direct operational control, predominant in defense and intelligence community deployments with air-gapped security requirements.
- Multi-Cloud:Deliberate distribution across competing hyperscale platforms to mitigate vendor lock-in and optimize pricing through competitive bidding.
Hybrid deployments anchor current enterprise architecture; multi-cloud strategies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Whitefield and Electronic City corridors anchor Karnataka's data center density, where power availability and fiber density converge to support hyperscale and edge deployments. Sub-regional specialization across the state creates distinct competitive zones based on infrastructure maturity and regulatory compliance requirements.
Whitefield Corridor
Financial services firms and cloud providers drive demand for tier-III and tier-IV certified capacity in this eastern Bengaluru cluster. BIS infrastructure guidelines and RBI operational resilience mandates push banking workloads toward certified facilities with N+1 power redundancy. Hyperscale pre-leasing activity has absorbed substantial forward supply, with direct 132kV utility substations enabling dedicated megawatt blocks for single-tenant designs.
Electronic City
IT services exporters and industrial IoT deployments concentrate in this southern technology hub, where edge nodes target sub-10 millisecond latency for autonomous systems. Karnataka's single-window clearance mechanism accelerates permitting timelines for digital infrastructure projects. Pilot immersion cooling installations operational here enable 100+ kilowatt rack densities for AI training clusters without mechanical refrigeration energy penalties.
Devanahalli Aerospace Corridor
Emerging data center development targets aviation logistics and telecommunications workloads near Kempegowda International Airport. CEA grid-connectivity standards and renewable energy disclosure mandates shape facility design for new builds above 10 megawatts. Land cost advantages relative to Whitefield attract operators seeking secondary locations with adequate fiber backhaul to core network nodes.
Mysuru Road Peripheral Zone
Mid-market colocation and managed hosting providers target cost-sensitive enterprises outside Bengaluru's premium core. Karnataka state electricity distribution priorities limit dedicated substation availability, forcing competitive bidding for grid-connected capacity. Smaller operators accepting inferior cross-connect density compete on price against certified facilities in primary corridors.
Bengaluru Data Center Market Competitive Landscape
Established operators occupy the certified tier; emerging entrants pursue edge-node density and liquid-cooling specialization. Market structure consolidates around three archetypes: telecom-backed integrators leveraging parent network infrastructure, dedicated data center developers with direct utility relationships, and hyperscale cloud providers with captive India South availability zones. Dominant competitive moves include strategic partnerships for power procurement and capacity reservation contracts with take-or-pay structures transferring demand risk onto operators.
Within the telecom-integrated tier, Nxtra Data Ltd and Tata Communications occupy positions leveraging parent organization backbone assets for edge distribution. STT GDC India and CtrlS Datacenters exemplify the dedicated facility developer archetype, with the former anchoring premium hyperscale deployments and the latter representing tier-IV certification specialization for banking and government verticals. These four entities collectively illustrate how infrastructure control points—fiber density, utility interconnects, and certification status—determine competitive positioning across Bengaluru's corridor-based market structure.
| Leading Market Players |
|---|
| NTT Global Data Centers |
| Nxtra Data Ltd |
| STT GDC India |
| CtrlS Datacenters |
| Sify Technologies |
| Tata Communications |
| Reliance Data Centers |
| CapitaLand |
| L&T Cloudfiniti |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up facility operators across Bengaluru's data center corridor are consolidating land banks and utility interconnects, compressing development timelines while extracting premium lease rates from certified tier-III and tier-IV inventory. This ownership pattern concentrates pricing power among operators with secured power allocation and BIS certification, forcing mid-tier competitors toward secondary corridors with inferior fiber density.
Pricing Analysis
Input-cost pass-through from dedicated substation procurement and liquid-cooling infrastructure is reshaping contract structures across Bengaluru's data center market. Pricing stratifies across tier-IV certified, tier-III certified, and uncertified legacy facilities, with BIS compliance and RBI operational resilience mandates commanding substantial premiums from financial services tenants. Cost compression in uncertified colocation is intensifying because banking and government workloads are consolidating with certified operators, leaving secondary facilities exposed to vacancy-driven price erosion. Enterprise buyers with hyperscale pre-leasing commitments exhibit the lowest price sensitivity, while mid-market managed hosting clients in peripheral zones negotiate aggressively on per-rack economics.
Supply Chain Analysis
Certification and qualification gating through BIS infrastructure guidelines and CEA grid-connectivity standards is concentrating equipment procurement among vendors with demonstrated compliance track records. Supply chains for critical data center infrastructure draw from China for switchgear and power distribution units, the United States for precision cooling systems, and Germany for busbar trunking and electrical protection equipment. Single-source vulnerability in liquid-cooling component supply is elevating procurement risk as rack densities climb past 50 kilowatts. Distribution runs through direct manufacturer relationships with tier-I facility developers, bypassing traditional distribution channels for hyperscale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Bengaluru's data center market rests on the shift toward liquid-cooling readiness and tier-IV certification premiums, compressing development payback periods for operators with secured utility interconnects.
For Market Incumbents: To counter power allocation scarcity from Karnataka state electricity distribution priorities, anchor premium positioning through tier-IV certification investment and direct 132kV utility substation procurement in Whitefield. Deepen backward integration into renewable energy sourcing through captive solar-wind hybrid installations, securing priority dispatch under CEA standards while insulating against grid-connectivity bottlenecks. For New Entrants and Emerging Players: Karnataka's single-window clearance mechanism for digital infrastructure opens a window for edge-node deployment in Electronic City, where sub-10 millisecond latency requirements for industrial IoT remain under-supplied. Target tier-II certification gaps in Devanahalli Aerospace Corridor, where aviation logistics and telecommunications workloads seek cost-competitive alternatives to Whitefield premiums. Lead with immersion cooling specialization to differentiate against air-cooled legacy stock. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market colocation operators in Mysuru Road Peripheral Zone with uncertified facilities exposed to banking-sector consolidation. Long-term viability favors operators with secured power allocation and liquid-cooling engineering capabilities spanning the projection horizon. Watch BIS amendments governing thermal effluent discharge standards as the inflection indicator for facility upgrade capex cycles and certified capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Tier-IV Certification Investment | BIS infrastructure guidelines and RBI mandates concentrate banking demand on certified facilities with pricing power. |
| Liquid-Cooling Infrastructure Deployment | Direct-to-chip thermal management enables 100+ kilowatt rack densities for AI training clusters in Electronic City. |
| Renewable Energy Captive Sourcing | Solar-wind hybrid installations unlock CEA priority dispatch and insulate against Karnataka power allocation scarcity. |
| Edge Node Corridor Expansion | Sub-10 millisecond latency positioning in Whitefield and Electronic City captures autonomous systems and industrial IoT workloads. |
| Pre-Leasing Capacity Reservation | Five-year take-or-pay contracts with hyperscale cloud providers transfer demand risk and accelerate time-to-revenue. |
Research Methodology
Direct dialogue with data center facility operators, utility planning officers at Karnataka Power Transmission Corporation, financial services infrastructure procurement leads, and hyperscale cloud provider real estate teams grounded this analysis in operational realities. Secondary validation drew from BIS certification registries, CEA grid-connectivity filings, Karnataka state IT policy documents, and SEC disclosures from publicly traded data center REITs with India exposure. Bottom-up facility-level capacity tracking and top-down market sizing triangulated volume and value estimates across the analysis window.
Segmented outputs reflect modeling across facility type, end-user vertical, solution category, and deployment architecture throughout the forecast period. CAGRs were derived from capacity absorption rates, pre-leasing velocity, and certification-driven pricing tier differentials. Key forecast inputs include Karnataka state power allocation priority shifts, BIS amendment timelines for liquid-cooling discharge standards, and hyperscale cloud provider India South availability zone expansion cadence.
Revisions become necessary when BIS infrastructure guidelines materially tighten certification requirements, CEA renewable-tied dispatch rules shift, or Karnataka state electricity distribution priorities redirect dedicated substation allocation. Forecasts reflect assumptions regarding permitting timeline stability and fiber backhaul density continuity in primary corridors. A model refresh is warranted upon material change in hyperscale pre-leasing commitment patterns or liquid-cooling technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Asia-Pacific Hosting Infrastructure Services Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
Spain Data Center Rack Market
Data Center Infrastructure
Austria Data Center Physical Security Market