
 Global Data Center Rack Server Market | 2026-2036
Global Data Center Rack Server Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Rack Server Market Foresight
Enterprise buyer concentration is rebalancing toward hyperscale cloud operators and managed service providers, reducing traditional enterprise IT direct procurement. Dell Technologies leverages its supply chain scale to dominate rack-optimized configurations for AI workloads. Hewlett Packard Enterprise differentiates through liquid-cooling integration in high-density 2U and 4U platforms. Super Micro Computer specializes in open-standard designs that appeal to cloud-native deployment models.
A data center rack server is a standardized, horizontally mounted computing unit designed for installation in 19-inch equipment racks, typically measured in rack units (1U equals 1.75 inches in height), engineered to maximize compute density while enabling hot-swappable component maintenance and centralized thermal management in facility-scale deployments. The primary commercial purpose is to deliver scalable processing, storage, and networking capacity within climate-controlled data center environments where floor space and power density carry premium economics. Product type segmentation shows 2U and 4U form factors capturing expanded margin pools as GPU-accelerated AI servers require deeper chassis and enhanced power delivery. Technology segmentation reveals hyper-converged infrastructure and high-density computing as the fastest-expanding architecture categories, displacing traditional blade server footprints in new builds.
The EPA ENERGY STAR program and the EU Energy Efficiency Directive shape product standards by mandating disclosed power metrics and minimum efficiency thresholds for server equipment sold or operated within their jurisdictions. The FCC's equipment authorization rules govern electromagnetic emissions compliance for rack servers deployed in US telecommunications facilities, creating a certification barrier for non-compliant imports. China's GB standards and MIIT efficiency regulations add a parallel compliance track for servers manufactured or sold domestically. Stakeholders must monitor how divergent efficiency mandates across Washington, Brussels, and Beijing fragment product roadmaps and testing requirements.
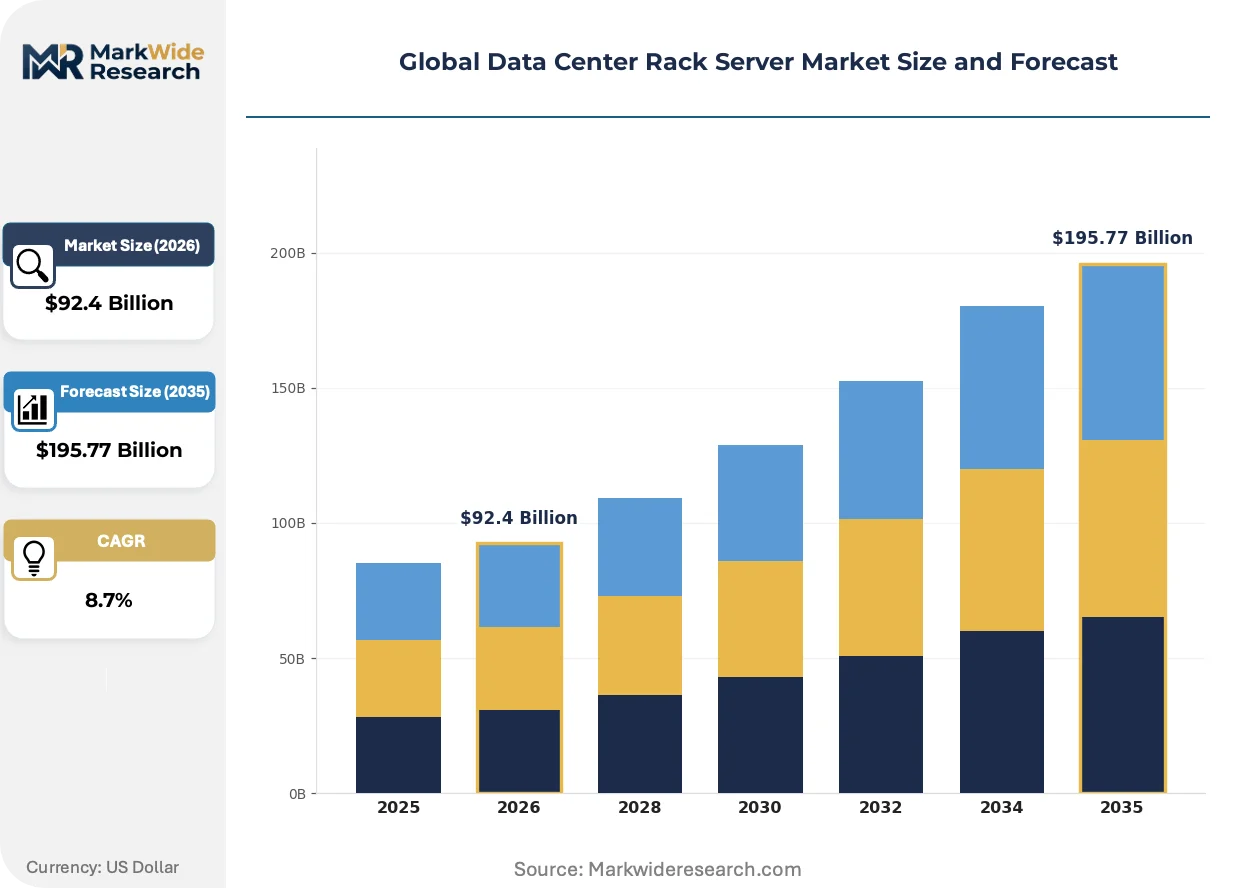
Market Dynamics
Hyperscale cloud operators are consolidating procurement authority and rebalancing rack configurations toward liquid-cooled architectures as AI training clusters expand, compressing traditional enterprise IT direct purchasing channels.
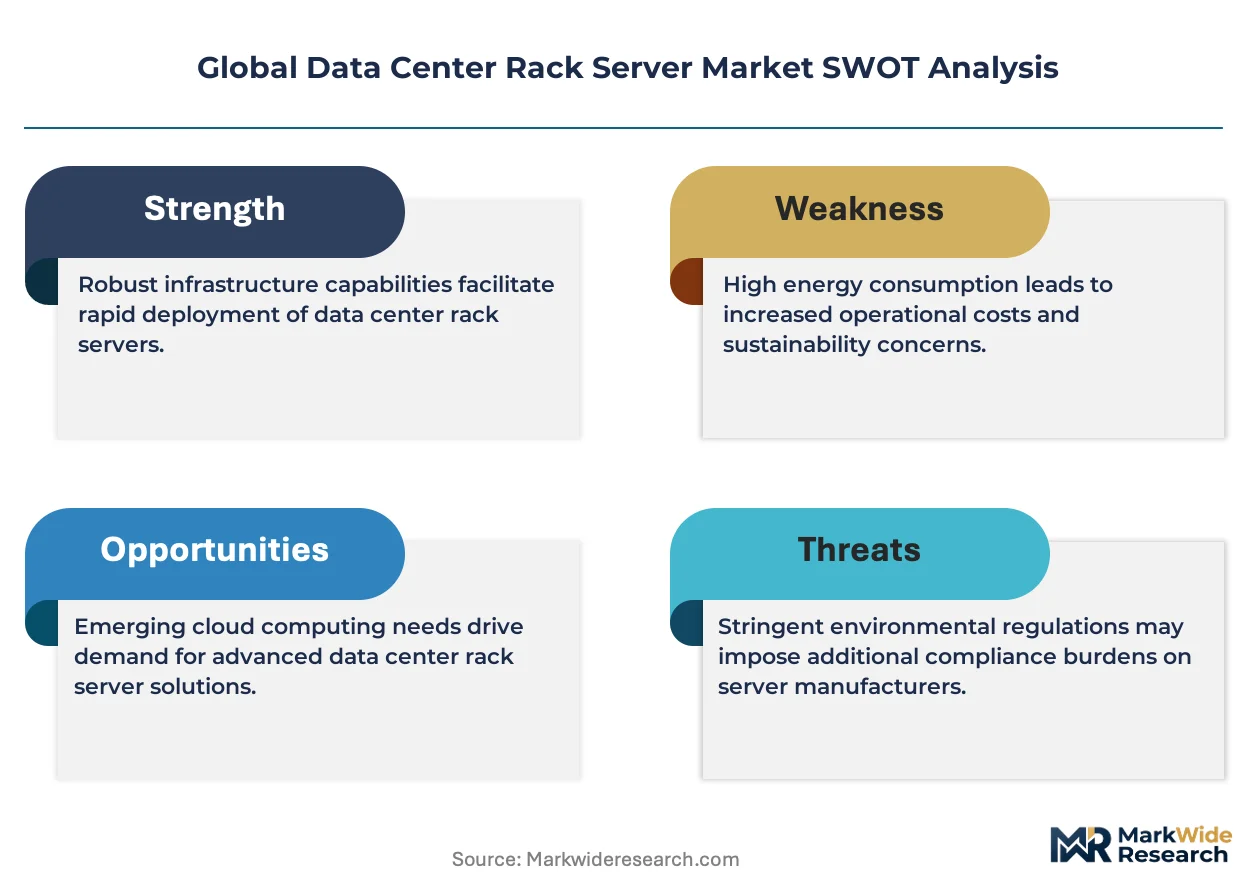
Growth Catalysts
- EU Energy Efficiency Directive:Mandatory disclosure of server-level power usage effectiveness is forcing facility upgrades and equipment refresh cycles across European colocation providers.
- GPU-accelerated AI clusters:Training workloads for generative models demand deeper 2U and 4U chassis with enhanced power delivery, expanding addressable hardware margins.
- Frankfurt Rhine-Main corridor:Colocation providers in Germany are densifying existing facilities rather than pursuing greenfield expansion, concentrating demand for high-density rack servers.
Market Restraints
- Copper and rare earth price volatility:Power delivery components and magnet materials face input cost swings that compress hardware margins before contract renegotiation windows open.
- Supply concentration in Taiwan:Advanced server motherboard and GPU substrate manufacturing clusters create single-source vulnerability for rack-optimized configurations.
- Thermal density ceiling:Air-cooled facilities hit physical limits around 30kW per rack, blocking AI server deployment without capital-intensive infrastructure overhaul.
Strategic Opportunities
- India's data center buildout:Cloud regions in Mumbai and Hyderabad are underpenetrated for liquid-cooled rack infrastructure, creating first-mover positioning for specialized vendors.
- Direct liquid cooling convergence:Integration of cold plate technology with existing facility water systems opens retrofit markets previously locked to air-cooled architectures.
- Japan's Green Transformation bonds:METI efficiency incentives subsidize equipment upgrades for domestic colocation providers adopting high-density computing platforms.
Industry Challenges
- Fluid dynamics engineering shortage:Data center operators lack in-house expertise to design and maintain direct liquid cooling loops, forcing reliance on vendor field service.
- Legacy facility integration:Retrofitting 10-15 year old raised-floor environments for liquid cooling requires structural assessment, permitting delays, and phased downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Rack Server Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $195.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1U, 2U, 4U, Blade Servers, Tower Servers Technology: Virtualization, Hyper-Converged Infrastructure, Cloud Integration, High-Density Computing, Modular Designs Use Case: Cloud Hosting, Big Data Analytics, Artificial Intelligence, High-Performance Computing, Content Delivery Networks End User: Telecom Providers, Financial Institutions, Government Agencies, E-commerce Platforms, Managed Service Providers |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, Lenovo, Cisco Systems, Huawei Technologies, Fujitsu, NEC Corporation, IBM, Super Micro Computer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Rack Server Market Shifts & Advancements
Liquid cooling architectures, regulatory disclosure mandates, and procurement consolidation are rewriting how rack servers are specified, deployed, and monetized across facility-scale environments.
Direct liquid cooling is rewriting thermal management economics for AI training clusters. Cold plate systems circulate coolant directly to GPU and CPU heat sources, enabling 100kW-plus rack densities. Hyperscale operators in the United States and Germany are adopting this technology at production scale. The shift is compressing the viable market for traditional air-cooled high-performance configurations.
REACH substance restrictions and the EU F-Gas Regulation are tightening material compliance for server manufacturing. Manufacturers must eliminate restricted flame retardants and transition away from high-global-warming-potential refrigerants in cooling systems. European colocation providers are now requiring full material disclosure from hardware suppliers before contract award.
Enterprise IT departments are ceding direct procurement authority to managed service providers and cloud resellers. Hardware specification decisions now concentrate with hyperscale operators and MSPs who aggregate demand across multiple end-users. This channel shift is most visible in Germany and the Netherlands, where enterprise colocation contracts increasingly bundle hardware as a service rather than separate capital purchase.
Global Data Center Rack Server Market Segmentation
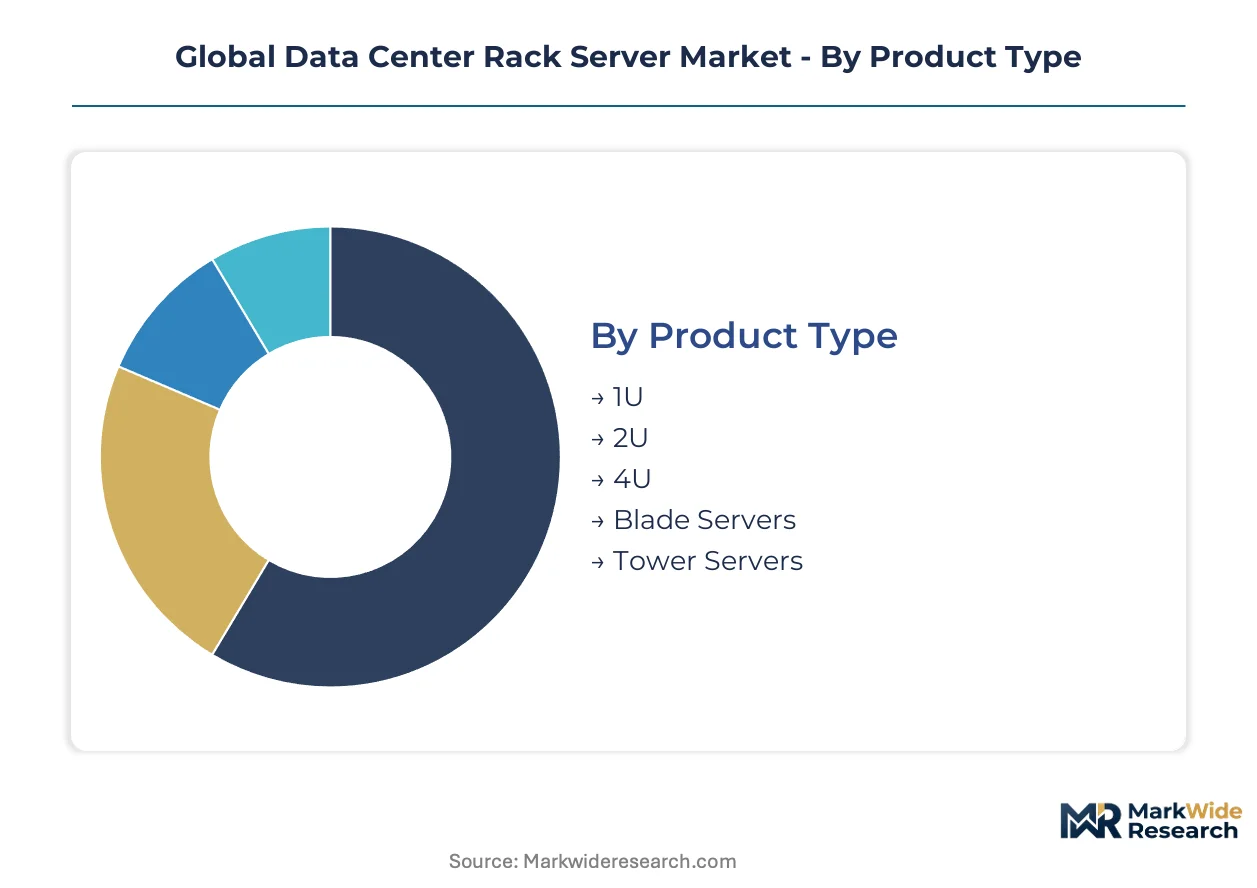
Segmentation in the data center rack server market reveals how procurement authority, workload density, and facility infrastructure interact to shape purchasing patterns. Each dimension captures a different axis of technical requirement and commercial decision-making.
Product Type:
Standardization dominates at the 1U tier while customization intensifies through 2U and 4U configurations where liquid cooling and GPU accommodation reshape chassis engineering.
- 1U:The shallowest rack-mounted form factor optimized for web serving and light virtualization workloads where horizontal scale trumps per-node performance. Hyperscale operators in the United States and Germany deploy these in bulk for front-end application tiers where density and power efficiency matter more than expansion slots.
- 2U:Deeper chassis accommodating dual-socket configurations and modest GPU expansion, now the default specification for AI inference workloads. Frankfurt Rhine-Main colocation providers specify 2U platforms as their standard refresh unit to bridge air-cooled legacy infrastructure and emerging liquid-cooled requirements.
- 4U:Full-depth platforms supporting multi-GPU configurations and 3000W-plus power delivery for training clusters.
- Blade Servers:Shared infrastructure enclosures popular in enterprise data centers through the 2010s now face displacement by hyper-converged alternatives.
- Tower Servers:Non-rack form factors retaining relevance only in edge micro-data centers and small business server closets.
Leading the category by volume: 2U. Growing fastest: 4U.
Technology:
Cost tier stratification separates commodity virtualization from premium hyper-converged and liquid-cooled high-density platforms where margin pools concentrate.
- Virtualization:Software abstraction of compute resources enabling multi-tenancy and workload portability across physical hosts. Indian cloud providers in Mumbai and Hyderabad deploy virtualization layers on commodity hardware to maximize utilization rates in capital-constrained buildouts.
- Hyper-Converged Infrastructure:Tightly integrated compute-storage-networking stacks displacing three-tier architectures in enterprise refreshes. German mid-market enterprises favor HCI for its operational simplicity and reduced rack footprint in Frankfurt facilities where floor space carries premium economics.
- Cloud Integration:Native compatibility with AWS, Azure, and GCP management APIs and billing frameworks.
- High-Density Computing:Liquid-cooled and enhanced power delivery configurations for AI training clusters.
- Modular Designs:Disaggregated server architectures allowing independent refresh of compute, memory, and storage subsystems.
Standard virtualization still commands the largest installed base. Hyper-converged infrastructure is expanding most quickly in European enterprise accounts.
Use Case:
Application intensity determines infrastructure investment, with AI training and high-performance computing demanding specialized hardware while content delivery optimizes for cost per request.
- Cloud Hosting:Multi-tenant infrastructure serving variable workloads with rapid provisioning requirements. Managed service providers across the Netherlands aggregate cloud hosting demand and specify rack servers through hardware-as-a-service contracts rather than direct enterprise procurement.
- Big Data Analytics:Distributed processing frameworks requiring high memory bandwidth and fast local storage. Financial institutions in London and Singapore deploy analytics-optimized 2U platforms with NVMe storage pools for real-time risk modeling.
- Artificial Intelligence:GPU-accelerated training and inference workloads driving liquid cooling adoption.
- High-Performance Computing:Scientific and engineering simulation clusters requiring low-latency interconnects.
- Content Delivery Networks:Caching and edge serving nodes optimized for throughput per watt.
Cloud hosting remains the volume anchor. Artificial intelligence workloads are climbing the fastest as training cluster buildouts accelerate.
End User:
Customer type dictates procurement channel, with hyperscale operators and managed service providers concentrating specification authority while traditional enterprises cede direct purchasing.
- Telecom Providers:Network function virtualization and edge computing infrastructure replacing proprietary appliances. Japanese carriers NTT and KDDI leverage METI Green Transformation bond subsidies to refresh central office facilities with high-density rack servers.
- Financial Institutions:Low-latency trading infrastructure and risk analytics clusters with strict compliance requirements. Frankfurt-based banks specify liquid-cooled 4U platforms for co-located trading environments where the EU Energy Efficiency Directive mandates disclosed power metrics.
- Government Agencies:Sovereign cloud and classified workload deployments with domestic manufacturing preferences.
- E-commerce Platforms:Seasonally variable capacity requiring rapid horizontal scaling.
- Managed Service Providers:Aggregated procurement across multiple end-users now controlling specification decisions previously held by enterprise IT departments.
Managed service providers are gaining share fastest as procurement authority consolidates. Telecom providers still represent the largest volume segment by unit deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale procurement authority concentrates in the United States, Germany, and China, with facility densification accelerating in established corridors rather than greenfield expansion. Cloud operators in these markets are rebalancing rack configurations toward liquid-cooled architectures as AI training clusters scale. Regulatory disclosure mandates in Europe and efficiency standards in Asia are fragmenting equipment roadmaps across jurisdictions.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are consolidating procurement authority and specifying liquid-cooled 4U platforms for AI training clusters. The EPA ENERGY STAR program mandates disclosed power metrics for federal procurement eligibility. Northern Virginia's Data Center Alley continues densifying existing facilities rather than permitting new greenfield campuses.
Germany
Frankfurt Rhine-Main colocation providers are densifying legacy facilities with 2U and 4U high-density configurations to avoid greenfield permitting delays. The EU Energy Efficiency Directive forces disclosed server-level power usage effectiveness across all facility upgrades. Frankfurt's financial district banks specify liquid-cooled rack servers for co-located trading infrastructure.
China
Domestic cloud operators in Beijing-Tianjin-Hebei and Yangtze River Delta are expanding GPU-accelerated training clusters requiring enhanced power delivery chassis. MIIT efficiency regulations and GB standards create parallel compliance tracks for domestically manufactured servers. Shanghai's Lingang New Area is concentrating hyperscale facility expansion with state-backed power infrastructure.
India
Cloud regions in Mumbai and Hyderabad are underpenetrated for liquid-cooled rack infrastructure, creating first-mover positioning for specialized vendors. The CEA and BIS efficiency frameworks are tightening disclosure requirements for imported server equipment. Mumbai's Mahape industrial corridor is attracting colocation investment from global operators seeking alternative to saturated Singapore and Hong Kong markets.
Japan
NTT and KDDI are leveraging METI Green Transformation bond subsidies to refresh central office facilities with high-density rack servers. METI efficiency incentives subsidize equipment upgrades for domestic colocation providers adopting liquid-cooled platforms. Tokyo's Otemachi financial district is concentrating demand for low-latency trading infrastructure with strict power disclosure requirements.
Global Data Center Rack Server Market Competitive Landscape
United States producers anchor one tier; Taiwan and Chinese specialists hold manufacturing scale for motherboard and GPU substrate production. The vendor base stratifies across three tiers: diversified technology conglomerates with supply chain scale, server-focused specialists with liquid-cooling integration, and open-standard fabricators serving cloud-native deployment models. Strategic archetypes include supply-chain-integrated full-stack providers, thermal-engineering specialists, and modular-design pure-plays. Competitive moves concentrate on backward integration into power delivery components and geographic expansion into underpenetrated cloud regions.
Within the diversified technology tier, Dell Technologies exemplifies supply-chain scale advantages in rack-optimized configurations. Hewlett Packard Enterprise occupies a position emphasizing liquid-cooling integration in high-density platforms. Super Micro Computer represents the open-standard specialist archetype appealing to cloud-native hyperscale procurement patterns. These three anchors illustrate how vendor positioning fragments across procurement channel concentration, thermal engineering capability, and design philosophy standardization.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| Lenovo |
| Cisco Systems |
| Huawei Technologies |
| Fujitsu |
| NEC Corporation |
| IBM |
| Super Micro Computer |
| Others |
Supply & Pricing Matrix
Copper price volatility on the London Metal Exchange cascades through power delivery component costs into three distinct hardware pricing tiers across the data center rack server market. Frankfurt Rhine-Main colocation providers face compressed margins on air-cooled 1U configurations while absorbing premium pricing for liquid-cooled 4U platforms.
Pricing Analysis
Volume concentrates in commodity 1U and 2U configurations where hyperscale operators extract scale discounts, while margins pool in customized 4U liquid-cooled platforms with GPU-accelerated power delivery. Price differentiation hinges on thermal engineering certification tier and volume commitment scale, with Frankfurt banks showing lowest sensitivity due to co-location premium economics. Pricing pressure intensifies in standard air-cooled tiers as legacy facility thermal ceilings block AI server deployment. Managed service providers exhibit highest price sensitivity as they aggregate demand across multiple end-users in hardware-as-a-service contracts.
Supply Chain Analysis
Reverse logistics flows for GPU substrate refurbishment and cold plate remanufacturing are emerging as cost centers as hyperscale operators extend hardware lifecycles. Manufacturing gravity centers on Taiwan for advanced server motherboards, China for power delivery components, and Malaysia for final assembly. Raw material dependencies span copper busbars, rare earth magnets, and high-thermal-conductivity alloys. Single-source vulnerability in Taiwan GPU substrate production creates concentration risk. Distribution runs through direct procurement channels to hyperscale operators and MSP-aggregated contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data center rack server market has become a vertical-integration race where captive control over liquid-cooling component supply separates margin leaders from assemblers. Players are pursuing backward integration into cold plate manufacturing and coolant distribution systems.
For Market Incumbents: Cement supply chain control through captive cold plate production or exclusive partnerships with Taiwan thermal engineering specialists. Acquire field service capabilities for direct liquid cooling loop maintenance to offset the fluid dynamics engineering shortage threatening deployment timelines. Dell Technologies and HPE must defend against Super Micro Computer's open-standard cloud-native positioning by locking hyperscale operators into bundled thermal service contracts. For New Entrants and Emerging Players: Begin with India's Mumbai and Hyderabad cloud regions where liquid-cooled rack infrastructure remains underpenetrated and CEA efficiency frameworks are tightening disclosure requirements for imports. Target financial institutions in Frankfurt's banking district seeking co-located trading infrastructure with EU Energy Efficiency Directive compliance. Lead with direct liquid cooling retrofit expertise for legacy raised-floor facilities rather than greenfield specifications. For Investors and Strategic Acquirers: The window for entry favors thermal engineering specialists with fluid dynamics IP and established field service networks over commodity server assemblers. Long-term viability hinges on positioning upstream of the AI training cluster buildout wave. Monitor METI Green Transformation bond disbursement velocity in Japan and CEA enforcement intensity in India as inflection signals for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold Plate Manufacturing | Captures margin pools in liquid-cooled AI server configurations for hyperscale operators. |
| Direct Liquid Cooling Retrofit Service Launch | Unlocks legacy facility upgrade revenue blocked by 30kW air-cooled thermal ceilings. |
| Geographic Expansion into Indian Cloud Regions | Establishes first-mover positioning in Mumbai and Hyderabad before CEA disclosure mandates harden. |
| Strategic Partnership with Taiwan GPU Substrate Suppliers | Mitigates single-source supply concentration risk for AI training cluster deployments. |
| Acquisition of Fluid Dynamics Engineering Specialist | Addresses talent scarcity blocking direct liquid cooling loop design and maintenance. |
Research Methodology
Independent corroboration across hyperscale operator procurement officers, colocation facility engineering directors, and server OEM product managers underwrites the qualitative findings in this study. Primary fieldwork captured specification decisions at Frankfurt Rhine-Main, Northern Virginia, and Mumbai facilities alongside secondary validation through SEC capex disclosures, EU Energy Efficiency Directive implementation guidance, and METI Green Transformation bond allocation records. Bottom-up triangulation across installation volumes and top-down reconciliation against facility power capacity expansion anchored the market sizing.
Rate-of-change decomposition across the projection horizon separates baseline replacement demand from AI training cluster incremental capacity. Segmentation dimensions modeled include form factor tier, cooling architecture, workload intensity, and procurement channel concentration. CAGRs derived from facility densification rates, GPU deployment trajectories, and regulatory compliance cycle timing. Hyperscale operator capital commitment announcements and colocation provider equipment refresh schedules fed directly into the forecast framework.
Underlying measurement precision varies by segment; hyperscale operator procurement volumes carry tighter precision than enterprise IT direct purchasing channels where authority is fragmenting. Forecasts assume continued concentration of specification decisions with managed service providers and sustained copper price volatility through the modeling period. Practitioners should monitor MIIT efficiency regulation enforcement in China and EPA ENERGY STAR program expansion for early signals of regulatory-driven equipment refresh acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Canada Data Center Power Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Physical Security Market
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Data Center IT Asset Disposition Market