
 Indonesia Data Center Market | 2026-2036
Indonesia Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Market Outlook
Hyperscale cloud operators are unwinding the dominance of enterprise-owned data centers across Indonesia. PT Telkom Data Ekosistem anchors domestic infrastructure through its NeutraDC platform and nationwide fiber backbone. Alibaba Cloud leverages its regional cloud expertise to compete for regulated-sector workloads requiring local presence. Princeton Digital Group specializes in hyperscale-ready campuses targeting international cloud deployers.
Indonesia data centers constitute purpose-built facilities housing servers, storage, and networking equipment with power densities typically ranging from 5 to 15 kW per rack, designed to deliver continuous compute, storage, and connectivity services for enterprise and digital platform operations. Colocation services lead current revenue as enterprises exit capital-intensive ownership models, while edge data centers represent the fastest-growing infrastructure type driven by latency-sensitive applications in secondary cities. Cloud services command expanding margin pools as providers bundle managed security and compliance layers atop raw infrastructure.
Indonesia's Ministry of Communication and Informatics enforces data localization through Government Regulation No. 71 of 2019, compelling foreign platforms to establish certified domestic facilities. BIS-equivalent technical standards and PLI scheme incentives shape equipment sourcing and construction compliance pathways. Stakeholders must monitor regulatory enforcement consistency against provincial permitting fragmentation that threatens deployment timelines.
Market Dynamics
Hyperscale cloud operators are compressing enterprise self-build timelines as Government Regulation No. 71 of 2019 mandates domestic data residency for foreign digital platforms. This regulatory pressure fuses with power availability constraints in Greater Jakarta to create deployment bottlenecks that favor operators with pre-certified facilities and established utility relationships.
Growth Catalysts
- Data Localization Mandate:Government Regulation No. 71 of 2019 compels foreign platforms to establish certified domestic facilities, directly expanding addressable demand for colocation and cloud services.
- Submarine Cable Landings:Batam and Jakarta anchor multiple international cable systems, reducing latency for regional cloud workloads and attracting hyperscale investment.
- PLI Scheme Incentives:Indonesia's Production Linked Incentive scheme subsidizes domestic manufacturing of data center equipment, lowering capital deployment costs for local builds.
Market Restraints
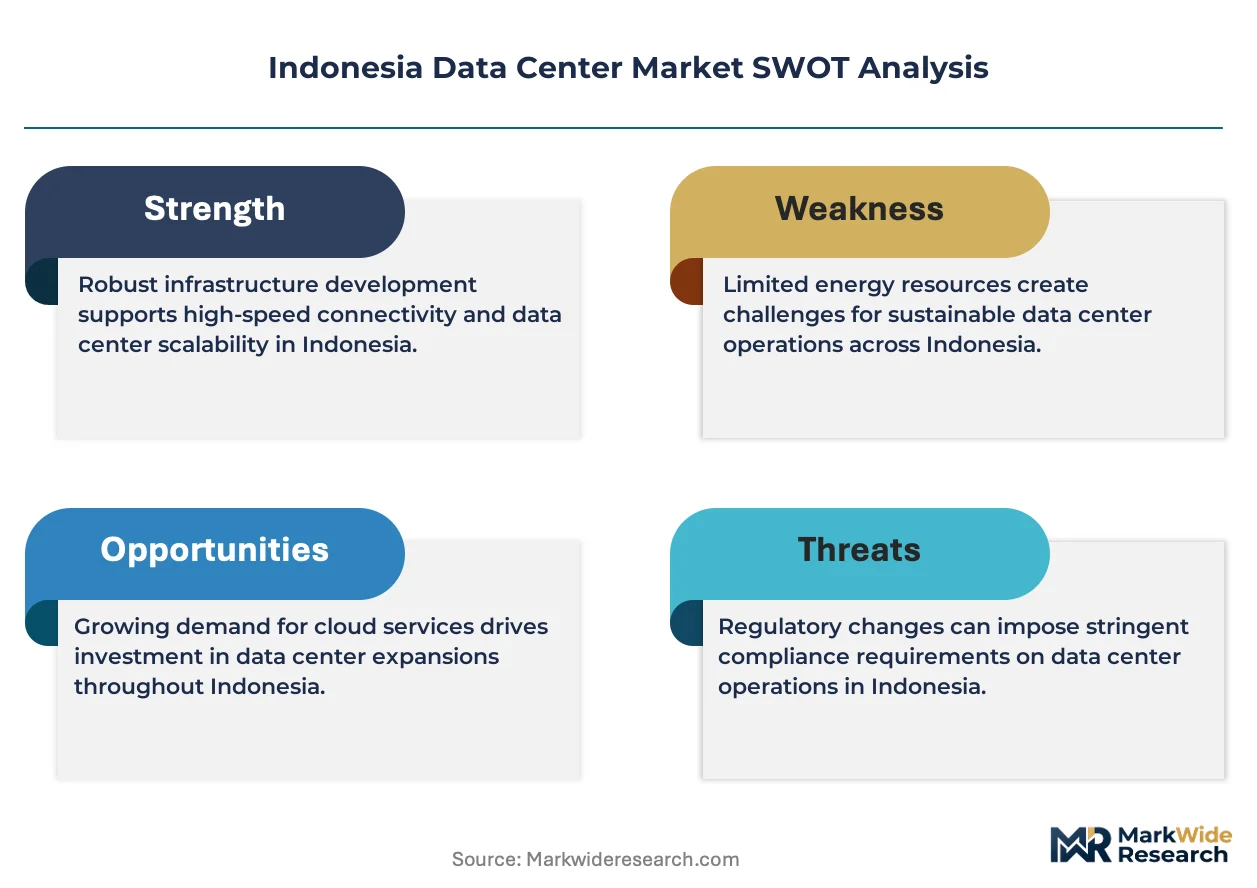
- Power Infrastructure Gaps:PLN's grid reliability in secondary cities forces operators to invest heavily in on-site generation, inflating project-level capex by 15-25% outside Greater Jakarta.
- Land Acquisition Complexity:Provincial permitting fragmentation across Indonesia's 34 provinces creates timeline uncertainty, with some jurisdictions requiring 18-24 months for environmental clearance.
- Liquid Cooling Supply Concentration:Precision cooling equipment relies on concentrated East Asian component supply, exposing operators to logistics volatility and extended lead times.
Strategic Opportunities
- Edge Deployment in Surabaya and Medan:These secondary metros show rising latency-sensitive demand from e-commerce logistics and industrial IoT, with minimal incumbent hyperscale presence.
- AI Training Workload Migration:Sovereign AI initiatives across Southeast Asia are redirecting GPU-intensive workloads toward Indonesian facilities with favorable power pricing and regulatory alignment.
- Green Bond Financing:Indonesia's OJK sustainable finance regulations enable preferential capital access for facilities achieving PUE targets below 1.4, reducing weighted average cost of capital.
Industry Challenges
- Certified Engineering Talent Scarcity:Uptime Institute and TIA-942 certified professionals remain concentrated in Jakarta, forcing operators to fund internal training programs or import expertise at premium cost.
- Legacy Enterprise Migration Complexity:Financial services and government agencies operate aging on-premise infrastructure with custom compliance layers, complicating cloud repatriation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Market |
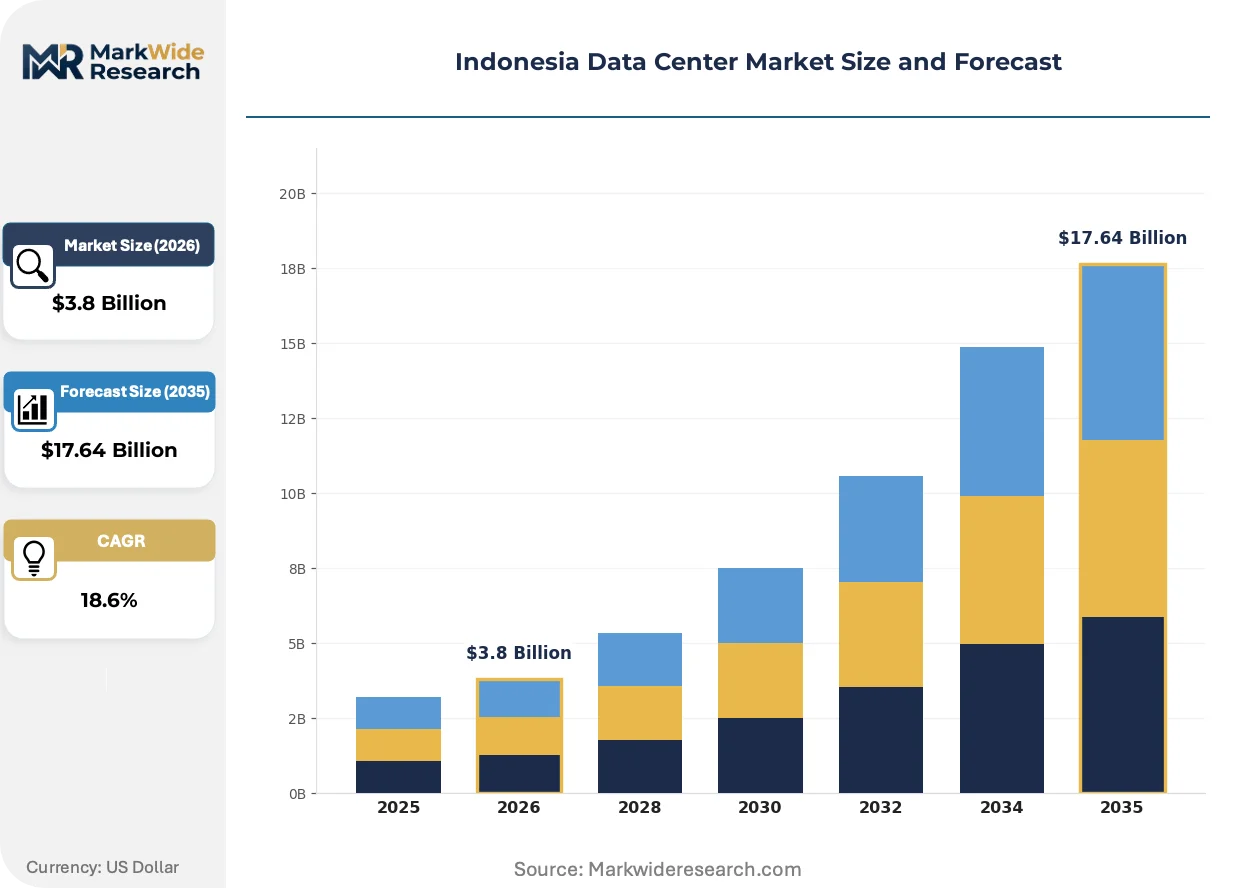
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Network Services, Cloud Services Infrastructure Type: Modular Data Centers, Traditional Data Centers, Edge Data Centers, Hyperconverged Infrastructure End User: Enterprises, SMEs, Government, Content Providers Energy Source: Renewable Energy, Grid Power, Diesel Generators, Hybrid Solutions |
| Companies Covered | PT Telkom Data Ekosistem (NeutraDC), PT DCI Indonesia, NTT Ltd, Amazon Web Services, Alibaba Cloud, EdgeConneX, Digital Edge, Princeton Digital Group, BDx Data Centers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Market Strategic Shifts
Modular infrastructure architectures are compressing deployment cycles from 24 months to under 12 months for standardized builds. This acceleration intersects with tightening sustainability mandates and evolving buyer procurement patterns to reshape competitive positioning across the Indonesian data center landscape.
Immersion cooling systems are miniaturizing from hyperscale-only deployments to enterprise colocation footprints. Financial services firms with high-density AI inference workloads are adopting single-phase dielectric fluid solutions at pilot scale. This technology diffusion is compressing the traditional three-year technology refresh cycle into 18-month intervals for premium-tier deployments.
Indonesia's Ministry of Communication and Informatics is tightening enforcement of Government Regulation No. 71 of 2019 through periodic compliance audits and public disclosure requirements. Foreign cloud platforms without certified domestic facilities face service restriction risks, accelerating localization investments. Regulated sectors including banking and healthcare are prioritizing providers with demonstrated audit history over cost-optimized alternatives.
Enterprise buyers are unbundling managed services from infrastructure contracts, demanding transparent pricing for power, cross-connect, and remote hands as separate line items. This procurement evolution favors operators with standardized service catalogs and API-driven billing platforms. Manufacturing and logistics verticals in Batam and Cikarang are driving this shift, having matured their internal IT capabilities through prior cloud adoption.
Indonesia Data Center Market Segmentation
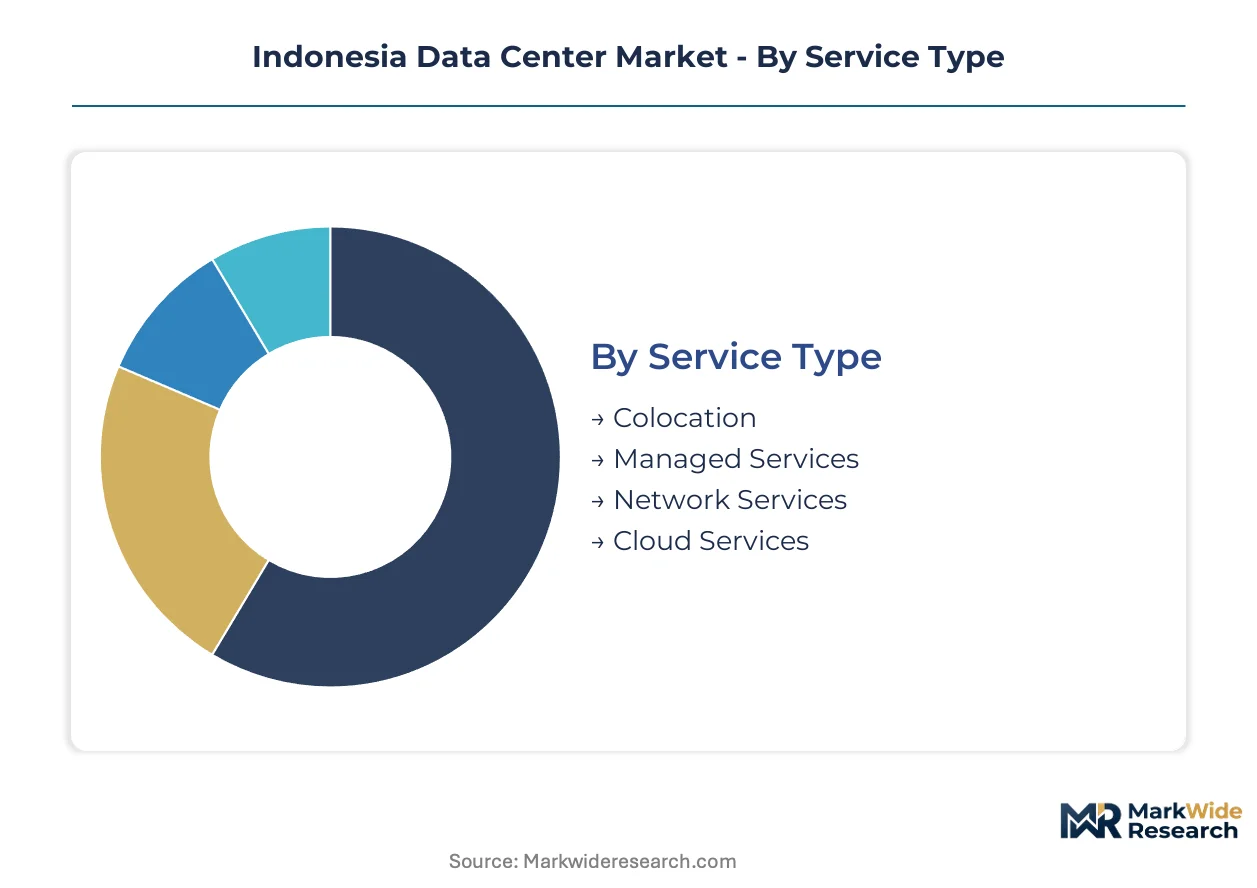
Segmentation reveals how Indonesia's data center value pools align with regulatory mandates and infrastructure constraints. Each dimension exposes distinct margin structures and deployment priorities across the market's expansion trajectory.
Service Type:
Margin concentration follows the shift from capital ownership to operational expenditure models across Indonesian enterprise buyers.
- Colocation:Third-party facility leasing with power, cooling, and physical security bundled per rack or cage. Demand concentrates among financial services firms in Greater Jakarta divesting owned facilities under Kominfo data localization audits.
- Cloud Services:IaaS, PaaS, and SaaS delivery with managed security and compliance layers atop raw infrastructure. Government and healthcare verticals in Surabaya and Bandung are rotating procurement toward providers with certified domestic presence.
- Managed Services:Remote hands, monitoring, and infrastructure management outsourced to facility operators. Mining and agribusiness enterprises in secondary cities leverage these to compensate for scarce certified engineering talent.
- Network Services:Cross-connects, internet exchange access, and dedicated connectivity provisioning. Content providers with latency-sensitive video delivery drive uptake in Batam cable landing zones.
Colocation holds installed capacity. Cloud Services is rotating up the share rankings.
Infrastructure Type:
Deployment velocity and capital efficiency separate the infrastructure categories as operators respond to compressed commissioning timelines.
- Traditional Data Centers:Purpose-built facilities with raised floor environments and centralized mechanical systems. Established operators in Greater Jakarta maintain these assets for enterprise clients with stable, predictable compute loads.
- Edge Data Centers:Compact, distributed facilities positioned within 10ms latency of end-users. E-commerce logistics platforms in Medan and Makassar are deploying these for real-time inventory and last-mile optimization.
- Modular Data Centers:Prefabricated, containerized or skid-mounted systems enabling rapid scaling. Hyperscale cloud deployers favor these for phased expansion in power-constrained locations.
- Hyperconverged Infrastructure:Integrated compute-storage-networking stacks with software-defined management. SMEs in Cikarang industrial zones adopt these to minimize on-site technical staffing requirements.
Traditional Data Centers anchor current capacity. Edge Data Centers are climbing the fastest as latency requirements harden.
End User:
Procurement sophistication and compliance burden vary sharply across buyer categories, shaping provider engagement models.
- Enterprises:Large organizations with dedicated IT infrastructure and multi-rack requirements. Banking and telecommunications sectors in Jakarta dominate current absorption, driven by OJK and BI regulatory examinations.
- Government:National and provincial agencies with sovereign data mandates. Kominfo certification requirements and SPBE digital transformation programs are accelerating dedicated facility procurement.
- SMEs:Small and medium enterprises with fractional rack or virtualized resource needs. Manufacturing clusters in Batam and Semarang are migrating from on-premise servers to colocation to ensure business continuity.
- Content Providers:Digital media, gaming, and streaming platforms with bandwidth-intensive workloads. Local over-the-top video services are expanding CDN footprints to reduce transit costs.
Enterprises retain volume leadership. Government is gaining share fastest as sovereign cloud initiatives mature.
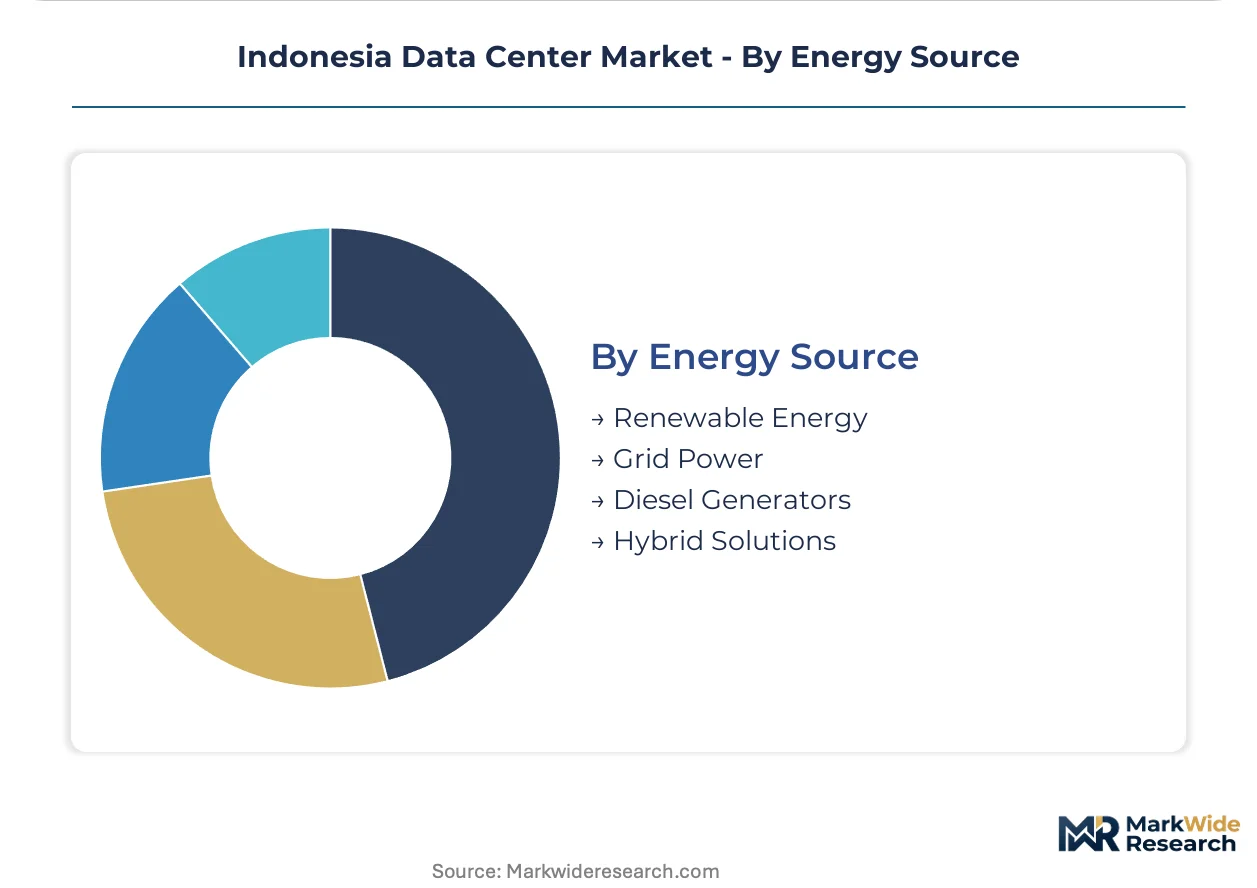
Energy Source:
Power procurement strategy directly determines operational cost structures and sustainability positioning for Indonesian operators.
- Grid Power:Electricity sourced from PLN's national utility network. Greater Jakarta facilities rely on this backbone, though operators maintain substantial on-site generation reserves for reliability.
- Renewable Energy:Solar, geothermal, or hydroelectric power with green certification. OJK sustainable finance regulations are steering bond-financed projects toward PUE-optimized renewable integration.
- Diesel Generators:Fossil-fuel backup systems for outage protection. Secondary city deployments outside Java carry heavier dependence due to grid reliability gaps.
- Hybrid Solutions:Combined grid, renewable, and storage configurations with intelligent load management. hyperscale campuses in Cibitung and Karawang are piloting these to meet internal carbon neutrality commitments.
Grid Power dominates current supply. Renewable Energy is expanding most quickly as green financing access widens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Java toll road and Java-Bali electricity interconnection anchor Indonesia's data center geography, concentrating capacity along a corridor linking Jakarta, Surabaya, and emerging secondary nodes.
Greater Jakarta
Financial services firms and hyperscale cloud operators drive absorption in Bekasi, Bogor, and Tangerang satellite cities. Kominfo audits under Government Regulation No. 71 of 2019 compel foreign platforms to secure certified domestic facilities. Cibitung and Karawang industrial zones host expanding campus developments targeting sovereign AI workloads.
West Java
Manufacturing and logistics enterprises in Cikarang and Bandung rotate procurement toward colocation to ensure operational continuity. PLN grid reliability exceeds national averages here, reducing backup generation requirements. Batu Jajar and Padalarang clusters attract modular deployments serving latency-sensitive industrial IoT applications.
East Java
Surabaya anchors demand from e-commerce fulfillment networks and provincial government digital transformation programs. The Suramadu Bridge connectivity and Madura Strait submarine cable landings reduce international transit latency. Gresik and Sidoarjo industrial corridors host edge facilities targeting real-time supply chain optimization.
North Sumatra
Medan emerges as a secondary hub for palm oil conglomerates and regional banking networks with distributed IT requirements. The Kuala Tanjung port modernization and Malacca Strait cable proximity create locational advantages. Deli Serdang regency attracts pilot edge deployments for agricultural commodity trading platforms.
Riau Islands
Batam leverages multiple international submarine cable landings and proximity to Singapore to capture content delivery and cross-border financial workloads. BP Batam free trade zone incentives reduce equipment import friction. Nagoya and Batu Ampar industrial zones concentrate facilities serving gaming and streaming platforms with bandwidth-intensive requirements.
Indonesia Data Center Market Competitive Environment
Concentration sits with state-affiliated infrastructure platforms and international hyperscale specialists. Three archetypes dominate: domestic telecom-captive operators with nationwide fiber backbones, Asia-Pacific regional specialists with modular deployment expertise, and global cloud hyperscalers with sovereign compliance capabilities. Competitive dynamics center on pre-certified facility availability and established utility relationships for power provisioning.
Within the domestic infrastructure tier, PT Telkom Data Ekosistem anchors nationwide capacity through its NeutraDC platform and Telkom Group fiber assets. Alibaba Cloud occupies a position among Asia-Pacific cloud specialists competing for regulated-sector workloads requiring certified local presence. Princeton Digital Group exemplifies the hyperscale-ready campus developer archetype targeting international cloud deployers with phased expansion capabilities.
| Leading Market Players |
|---|
| PT Telkom Data Ekosistem (NeutraDC) |
| PT DCI Indonesia |
| NTT Ltd |
| Amazon Web Services |
| Alibaba Cloud |
| EdgeConneX |
| Digital Edge |
| Princeton Digital Group |
| BDx Data Centers |
| Others |
Value Chain & Pricing Dynamics
Hyperscale facility scale economies in Greater Jakarta compress unit economics for power and cooling, concentrating procurement leverage among operators with pre-certified campuses and established PLN relationships. This concentration elevates price floors for smaller entrants while rewarding incumbents with volume-committed utility contracts and modular equipment sourcing.
Pricing Analysis
Volume-discount tiering structures separate hyperscale cloud deployers from enterprise colocation buyers and SME fractional-rack users. Pricing stratifies across premium certified facilities, standard commercial-grade builds, and economy-tier modular deployments, with Uptime Institute Tier III certification commanding substantial premiums. Cost compression in the economy tier is intensifying because Chinese equipment vendors are flooding secondary city markets with unbundled power and cooling packages. SMEs in Batam and Semarang exhibit highest price sensitivity, while financial services firms in Jakarta prioritize audit history over cost optimization.
Supply Chain Analysis
Inbound logistics costs from Singapore and Shanghai ports fluctuate with container availability through the Malacca Strait, exposing Indonesian operators to transshipment delays and customs clearance variability at Tanjung Priok. Precision cooling equipment and power distribution units draw from concentrated manufacturing bases in China, South Korea, and Taiwan, creating single-source vulnerability for liquid cooling components and high-density busway systems. Distribution runs through Jakarta-based system integrators with Batam free-trade-zone staging for cable landing zone deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified engineering talent scarcity across Indonesia's 34 provinces constrains deployment velocity, with Uptime Institute-accredited professionals concentrated in Greater Jakarta and forcing operators to fund internal training pipelines or import expertise at premium cost.
For Market Incumbents: Shield pre-certified facility positions in Cibitung and Karawang against modular campus developers by locking long-term PLN power allocation agreements before grid capacity saturates. Deepen backward integration into precision cooling maintenance capabilities to reduce dependence on East Asian component suppliers and compress response times for hyperscale tenants. For New Entrants and Emerging Players: Lead with edge deployment architectures in Surabaya and Medan where latency-sensitive e-commerce logistics demand outpaces incumbent hyperscale presence. Target palm oil conglomerates and regional banking networks in North Sumatra with distributed IT requirements, offering managed services bundles that compensate for scarce local engineering talent. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hyperscale-ready campus developers with phased expansion capabilities and established Kominfo certification histories. Long-term viability hinges on sovereign AI workload capture and green bond financing access under OJK sustainable finance regulations. Watch PLN grid expansion announcements into secondary cities as inflection indicators for geographic diversification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Campus Expansion | Phased buildouts in Cibitung and Karawang capture sovereign AI workload migration from Singapore. |
| Kominfo Certification Investment | Government Regulation No. 71 compliance creates defensible positioning for regulated-sector procurement. |
| Green Bond Financing | OJK sustainable finance regulations enable preferential capital access for PUE-optimized facilities. |
| Edge Deployment Partnership | Collaboration with e-commerce logistics platforms in Surabaya addresses latency requirements outside Jakarta. |
| Internal Training Academy | Uptime Institute certification programs reduce reliance on imported engineering talent and compress payroll costs. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with data center operators, PLN grid planning officers, and Kominfo regulatory affairs leads, combined with secondary validation against hyperscaler capex disclosures, submarine cable landing records, and OJK sustainable finance filings. Facility developers, enterprise IT procurement managers, and modular equipment vendors supplied deployment timeline and pricing intelligence. Bottom-up capacity installation tracking and top-down cloud revenue attribution were triangulated against PLN electricity consumption data.
Across the analysis window, the forecasting framework modeled service type segmentation alongside infrastructure category, end-user vertical, and regional power availability tiers. CAGRs were derived from capacity pipeline tracking and absorption rate benchmarking against comparable Southeast Asian markets. Inputs included Kominfo enforcement intensity assumptions, PLN grid reliability projections for Java versus outer islands, and hyperscale cloud operator expansion commitment signals.
The analysis sits within stated boundaries; outcomes outside sustained data localization enforcement, PLN generation capacity expansion, or stable submarine cable connectivity would require recalibration. Forecasts reflect documented assumptions regarding regulatory consistency and power infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
Retail Colocation Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Brazil Data Center Server Market